
 Paint Packaging Market | 2026-2036
Paint Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Paint Packaging Market Intelligence
Direct-to-contractor distribution is reconfiguring how paint manufacturers source containers, with bulk pail orders bypassing traditional wholesale layers. Ball Corporation leverages its metal forming expertise to dominate two-piece steel can supply for architectural coatings. Crown Holdings anchors North American production through integrated sheet-to-can operations near Midwest paint manufacturing corridors. Smurfit Kappa competes in corrugated pails with moisture-resistant paperboard formulations that target light-duty industrial segments.
Paint packaging encompasses rigid containers engineered to prevent solvent evaporation, pigment settling, and moisture ingress through specified barrier coatings or multi-layer constructions, serving manufacturers who require chemical compatibility and stack strength for waterborne, solventborne, and powder coatings. Metal cans retain primacy in solventborne architectural paints where internal epoxy phenolic linings resist corrosion from aggressive chemistries. Plastic pails, typically injection-molded from high-density polyethylene with snap-fit or screw-cap closures, capture share in waterborne formulations where lower permeability demands reduce material requirements. Drum formats in steel and plastic sustain industrial volume shipments for automotive and protective coatings, though this segment shows slower growth as just-in-time delivery models reduce bulk inventory positions.
The EPA regulates volatile organic compound emissions from paint packaging through container design standards that limit headspace and permeation, while REACH restricts hazardous substance migration from metal can linings and plastic additives into coating products. OSHA workplace exposure limits further shape container selection, driving demand for closed-system pouring and reduced-splash closure designs in industrial settings. Stakeholders must monitor evolving extended producer responsibility frameworks and mono-material recyclability mandates that will determine which material platforms retain cost-competitive access across major coating markets.
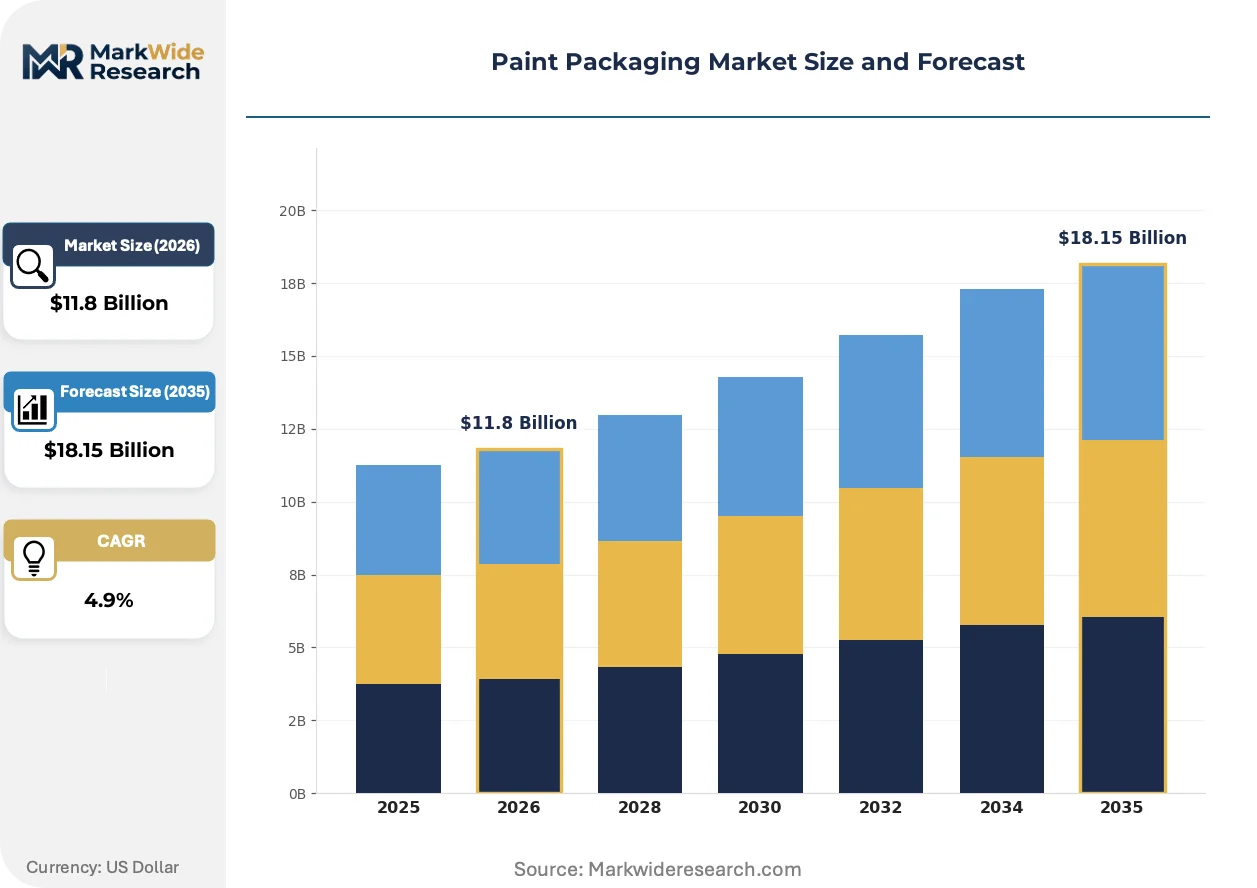
Market Dynamics
Waterborne paint formulations are compressing material specifications across container categories, forcing converters to abandon multi-layer barrier constructions optimized for solventborne chemistries in favor of lighter, mono-material designs that satisfy recyclability mandates without sacrificing shelf stability.
Growth Catalysts
- EU Green Deal packaging rules:Mandatory recyclability targets are accelerating converter investment in mono-material pail designs that eliminate adhesive layers and mixed-polymer closures.
- Automotive OEM waterborne transition:Tier-1 coating suppliers in Germany and the United States are specifying HDPE pails with fluorinated barrier treatments for electrocoat primers.
- China's dual carbon goals:Provincial emissions trading schemes in Shandong and Guangdong are pushing local paint manufacturers toward lighter-weight containers that reduce transport intensity.
Market Restraints
- Epoxy phenolic resin supply concentration:Internal can lining formulations depend on bisphenol-A derivatives sourced from a narrow base of specialty chemical producers in the US Gulf Coast.
- Steel sheet tariff volatility:Two-piece can fabricators face input cost instability from trade policy shifts affecting cold-rolled tinplate.
- Permeation rate floors:Waterborne alkyd formulations still exceed oxygen transmission limits of unmodified polyethylene, locking in multi-material solutions for certain architectural segments.
Strategic Opportunities
- India's PLI scheme for chemicals:Domestic paint production capacity expansion in Maharashtra and Gujarat creates demand for localized pail supply with reduced import dependency.
- Post-consumer recycled content mandates:California's SB 54 and similar extended producer responsibility frameworks reward converters achieving 30%+ PCR integration in rigid containers.
- Digital printing on metal:Direct-to-can decoration technology eliminates applied paper labels, streamlining recycling streams and enabling SKU proliferation without plate costs.
Industry Challenges
- Fluoropolymer barrier chemistries:PFAS restrictions under state-level US legislation and anticipated federal EPA action complicate migration-resistant pail specifications for aggressive waterborne formulations.
- Legacy steel can line curing:Phenolic coating ovens require substantial thermal energy and extended cycle times, creating capex barriers for capacity expansion in high-wage geographies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paint Packaging Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.15 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Cans, Pails, Drums, Tubes Material: Metal, Plastic, Glass, Paperboard End User: Residential, Commercial, Industrial, Automotive Closure Type: Screw Cap, Snap Fit, Spout, Others |
| Companies Covered | Ball Corporation, Smurfit Kappa, Kian Joo Can Factory Berhad, Berry Global Inc., Mondi PLC, Mold-Tek Packaging Limited, Crown Holdings, Inc., Trivium Packaging, Sonoco Products Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paint Packaging Market Strategic Shifts & Innovations
Container functionality is bifurcating between premium barrier-engineered solutions for specialty coatings and stripped-down recyclable formats for commodity architectural products, with digital manufacturing enabling both trajectories simultaneously.
In-mold labeling integration with thin-wall injection molding is rendering obsolete separate adhesive-applied label operations that previously complicated polyethylene pail recycling. Mid-tier architectural coating brands in North America are adopting this technology to meet retailer sustainability scorecards. The elimination of label-substrate separation steps is compressing total processing costs while improving post-consumer sortation yields.
REACH Annex XVII restrictions on bisphenol-A migration are forcing European metal can producers to validate alternative epoxy formulations for internal linings. ECHA substance evaluation timelines have compressed qualification windows for new barrier chemistries. Solventborne decorative coating segments in Italy and Spain face the steepest transition costs as legacy lining inventories deplete.
Direct-to-contractor e-commerce platforms are disintermediating traditional distributor networks for professional paint purchases. Large US home improvement retailers and specialized coating suppliers are building fulfillment infrastructure that favors smaller pack sizes and parcel-compatible container geometries. This channel shift concentrates in metropolitan construction corridors where contractor density supports same-day delivery economics.
Paint Packaging Market Segmentation
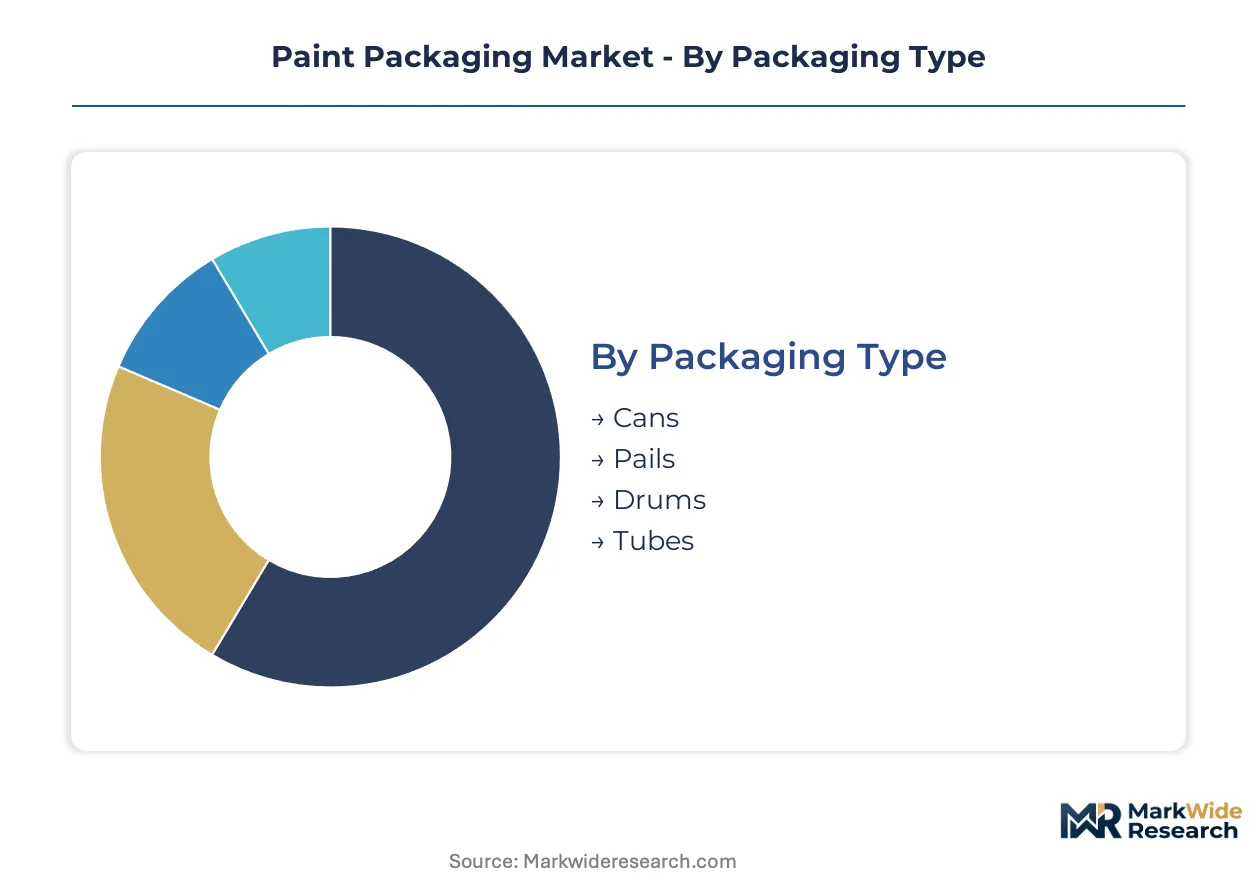
Paint packaging segmentation reflects divergent technical requirements across coating chemistries and application environments. Container specifications vary sharply between solventborne architectural products demanding corrosion-resistant metal linings and waterborne industrial formulations compatible with lighter plastic constructions.
Packaging Type:
Volume tier determines capital intensity and converter specialization, with high-throughput formats commanding dedicated fabrication lines and regional supply consolidation.
- Cans:Two-piece steel cylinders with internal epoxy phenolic linings dominate solventborne architectural coatings. Ball Corporation and Crown Holdings anchor supply in Germany and the United States where coating production clusters sit adjacent to metal forming facilities.
- Pails:Injection-molded HDPE containers with integrated handles capture waterborne formulation demand. Smurfit Kappa competes with moisture-resistant paperboard variants for light-duty industrial segments in North American metropolitan construction corridors.
- Drums:Steel and plastic bulk formats sustain automotive OEM and protective coating shipments, though just-in-time delivery compression reduces inventory positions.
- Tubes:Collapsible aluminum and laminate constructions serve touch-up and specialty coating niches requiring precise dispensing control.
Cans hold installed capacity. Pails are rotating up the share rankings as waterborne formulations expand.
Material:
Application chemistry dictates barrier performance requirements, with aggressive solventborne systems excluding lower-cost substrates from specification.
- Metal:Cold-rolled tinplate and aluminum deliver oxygen and moisture barriers essential for solventborne coatings. Internal lining formulations face REACH Annex XVII scrutiny on bisphenol-A migration in European markets.
- Plastic:HDPE and fluorinated barrier treatments serve waterborne alkyd and acrylic formulations. California SB 54 mandates are accelerating post-consumer recycled content integration in rigid containers.
- Glass:Borosilicate and soda-lime containers occupy premium decorative and artist coating segments where chemical inertness justifies weight and fragility penalties.
- Paperboard:Moisture-resistant corrugated pails target light-duty industrial applications with reduced chemical exposure and shorter shelf-life requirements.
Metal retains specification lock-in for aggressive chemistries. Plastic is gaining share fastest in waterborne transitions.
End User:
Customer type shapes order pattern density and pack size distribution, with professional contractor channels favoring bulk formats and retail DIY segments driving smaller unit volumes.
- Residential:DIY consumers purchase through home improvement retailers in parcel-compatible pack sizes. Direct-to-contractor e-commerce platforms are disintermediating traditional wholesale layers in United States metropolitan markets.
- Commercial:Professional painting contractors specify stack-strength containers for multi-site project logistics. Same-day delivery economics concentrate demand in high-density construction corridors.
- Industrial:Protective coating applicators require drum-scale shipments for infrastructure and marine projects, though inventory reduction pressures favor just-in-time pail delivery.
- Automotive:OEM electrocoat primers and refinish coatings demand fluorinated barrier pails with migration-resistant specifications. Tier-1 suppliers in Germany and the United States drive HDPE format qualification.
Automotive commands premium barrier engineering. Residential is climbing the fastest as direct-channel fulfillment infrastructure expands.
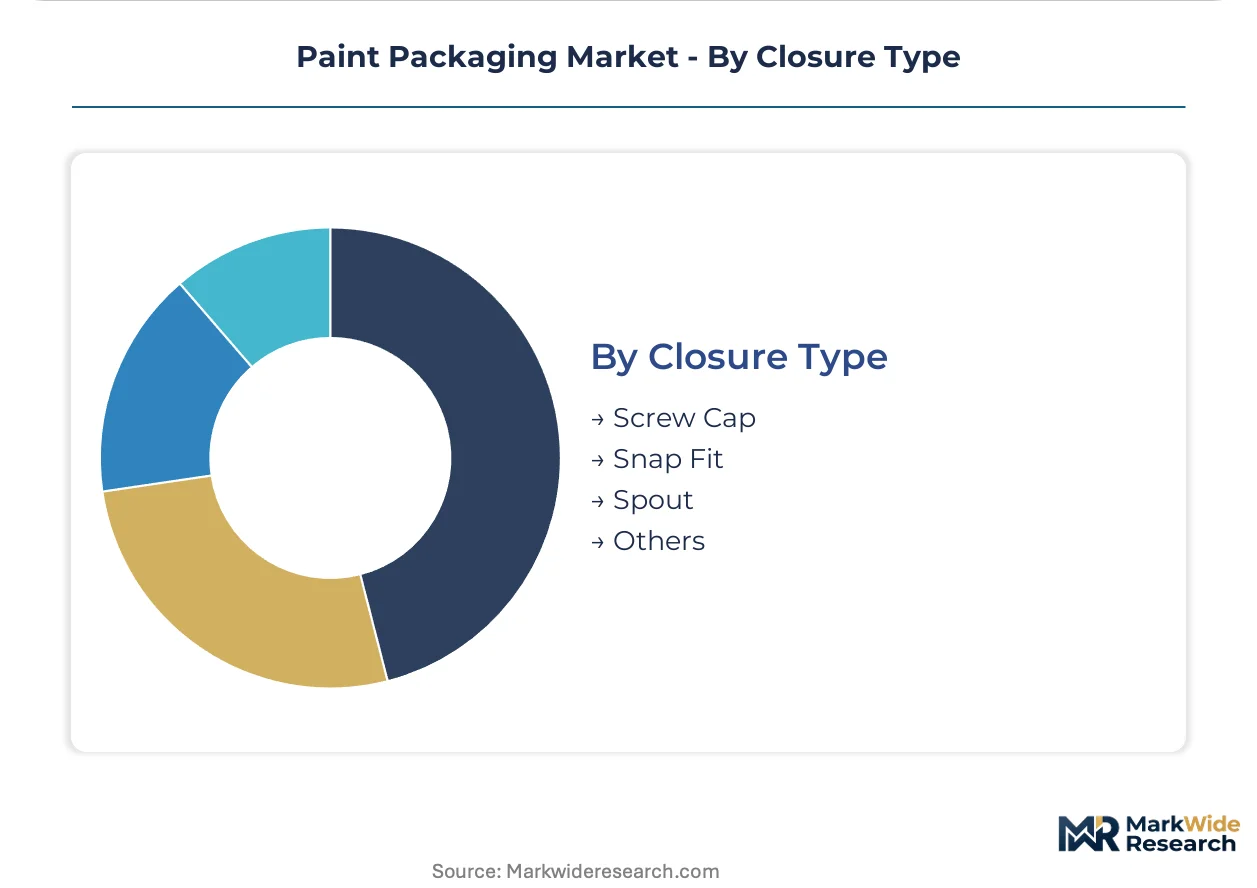
Closure Type:
Margin structure separates resealable precision systems from commodity snap-fit designs, with regulatory spill containment requirements elevating closure specification in industrial settings.
- Screw Cap:Threaded polyethylene and metal closures deliver resealability for partial-use architectural coatings. OSHA workplace exposure limits drive closed-system pouring designs in United States industrial applications.
- Snap Fit:Integral lid-to-pail locking mechanisms reduce material cost and simplify recycling streams for commodity waterborne products.
- Spout:Directional pouring apertures minimize splash and enable precise dispensing control for contractor-grade formulations.
- Others:Peelable membrane and hybrid closure systems serve specialty coating segments requiring contamination prevention or controlled atmosphere preservation.
Screw cap maintains specification breadth. Snap fit is rotating up the share rankings on recyclability mandate compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal packaging rules and China's dual carbon goals are redirecting capital toward mono-material container fabrication in coating production clusters across Germany, China, and the United States.
United States
Automotive OEM waterborne transitions in Michigan and Ohio are specifying HDPE pails with fluorinated barrier treatments for electrocoat primers. EPA container design standards limit headspace and permeation for volatile organic compound emissions. Crown Holdings anchors two-piece steel can supply through integrated sheet-to-can operations near Midwest paint manufacturing corridors.
Germany
REACH Annex XVII restrictions on bisphenol-A migration are forcing metal can producers to validate alternative epoxy formulations for internal linings. ECHA substance evaluation timelines have compressed qualification windows for new barrier chemistries. Solventborne decorative coating segments in Bavaria and North Rhine-Westphalia face steep transition costs as legacy lining inventories deplete.
China
Provincial emissions trading schemes in Shandong and Guangdong are pushing local paint manufacturers toward lighter-weight containers that reduce transport intensity. MIIT industrial standards govern chemical compatibility specifications for rigid packaging. Coating production clusters in the Yangtze River Delta and Pearl River Delta sit adjacent to pail fabrication hubs serving waterborne formulation demand.
India
The PLI scheme for chemicals is expanding domestic paint production capacity in Maharashtra and Gujarat, creating localized pail supply demand with reduced import dependency. BIS certification requirements shape container material specifications for industrial coatings. Mumbai-Pune and Ahmedabad-Vadodara industrial corridors concentrate converter investment in injection-molded HDPE capacity.
United Kingdom
Extended producer responsibility frameworks are accelerating post-consumer recycled content integration in rigid containers for architectural coatings. The Environment Agency regulates hazardous substance migration from packaging into coating products. Greater Manchester and West Midlands manufacturing zones host corrugated pail operations targeting light-duty industrial segments.
Paint Packaging Market Key Industry Players
On the supply side, the industry is consolidating around integrated metal forming operations and specialized plastic molding facilities that serve distinct coating chemistry segments. Tier-1 coating suppliers in automotive and industrial verticals demand barrier-engineered solutions, while commodity architectural markets favor cost-optimized recyclable formats. Two archetypes dominate: integrated metal can fabricators with captive sheet supply, and regional plastic pail specialists with thin-wall injection molding expertise. Capacity expansion and backward integration into resin compounding represent the primary competitive moves.
Among North American metal forming specialists, Ball Corporation and Crown Holdings exemplify the integrated archetype through proximity-based supply to Midwest coating corridors. Smurfit Kappa occupies a position within the diversified packaging tier, representing European-based competition in moisture-resistant paperboard formats. These three anchors illustrate how geographic clustering and material specialization stratify competitive positioning across solventborne and waterborne formulation demands.
| Leading Market Players |
|---|
| Ball Corporation |
| Smurfit Kappa |
| Kian Joo Can Factory Berhad |
| Berry Global Inc. |
| Mondi PLC |
| Mold-Tek Packaging Limited |
| Crown Holdings, Inc. |
| Trivium Packaging |
| Sonoco Products Company |
| Others |
Cost & Logistics Intelligence
The Yangtze River Delta freight corridor compresses logistics costs for pail converters serving waterborne coating plants, concentrating supply-side pricing power among HDPE molders while forcing metal can fabricators to absorb tinplate tariff volatility through tiered contract structures.
Pricing Analysis
Certification level creates the primary spread across container procurement, with REACH-compliant mono-material pails commanding premium positioning over legacy multi-layer constructions. Pricing stratifies across premium barrier-engineered, standard compliant-grade, and economy non-certified tiers. Cost compression in standard-grade metal cans is intensifying because epoxy phenolic resin supply concentrates on the US Gulf Coast. DIY retail channels exhibit highest price sensitivity, while automotive OEMs prioritize migration-resistant specifications over unit cost.
Supply Chain Analysis
Export-control scrutiny on fluoropolymer barrier chemistries limits technology flows to certain coating container specifications. Supply concentrates in China, Germany, and the United States where production clusters feed regional coating corridors. Raw material dependencies center on cold-rolled tinplate, high-density polyethylene resin, and specialty epoxy formulations. Single-source vulnerability in bisphenol-A derivative supply creates qualification bottlenecks for European lining transitions. Distribution runs through direct-to-contractor platforms disintermediating traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paint packaging is evolving into a service-attach opportunity as container leasing and closed-loop recovery programs expand faster than hardware sales, with sustainability scorecards driving recurring revenue models.
For Market Incumbents: Build regulatory compliance moats through REACH-validated alternative lining chemistries ahead of legacy inventory depletion. Deepen backward integration into post-consumer recycled resin compounding to satisfy California SB 54 mandates. Crown Holdings and Ball Corporation face displacement risk from fluorinated barrier HDPE pails in automotive electrocoat segments.
For New Entrants and Emerging Players: India's Maharashtra-Gujarat industrial corridor represents the most penetrable entry point as PLI-driven paint capacity expansion outpaces localized pail supply. Smaller pack sizes for direct-to-contractor e-commerce channels in United States metropolitan construction corridors offer second-mover advantage. Partner with digital printing equipment providers to enable SKU proliferation without plate cost barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core industrial container operations. Long-term viability hinges on mono-material recyclability platform ownership rather than legacy multi-layer asset bases. Watch PFAS restriction timelines at state and federal EPA levels as inflection indicators for fluorinated barrier pail demand destruction.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PCR Resin Compounding | Captures California SB 54 compliance premiums while securing supply certainty for HDPE pail production. |
| Digital Direct-to-Can Decoration Deployment | Eliminates label-substrate separation costs for Ball Corporation and Crown Holdings metal can operations. |
| Fluorinated Barrier Technology Pivot | Positions Tier-1 suppliers for automotive electrocoat specifications before anticipated EPA PFAS restrictions. |
| Closed-Loop Container Recovery Program | Generates recurring revenue streams through contractor-facing sustainability service layers. |
| Regional Pail Fabrication Capacity Addition | Reduces import dependency for India's Maharashtra-Gujarat coating production clusters under PLI schemes. |
Research Approach
Cross-validation between primary interviews with coating procurement directors and secondary customs data anchors the qualitative findings. Plant managers at German and Chinese pail fabrication facilities, technical R&D directors at epoxy lining formulators, and channel partners in North American metropolitan construction corridors contributed field intelligence. SEC 10-K filings, Cefic chemical trade reports, EPA container design standard documentation, and ECHA substance evaluation timelines provided external validation. Bottom-up volume modeling triangulates against top-down coating production estimates.
Calibration against historical capacity utilization rates and announced expansion projects shapes the projection framework. Segmentation dimensions span packaging format, material substrate, coating chemistry compatibility, and end-user channel across the modeling period. CAGRs derive from regression analysis of container demand intensity against coating output volumes. Waterborne formulation transition rates and extended producer responsibility mandate implementation timelines serve as key forecast inputs.
Practitioners should monitor REACH Annex XVII amendment proposals and state-level PFAS legislation for early signals. Forecasts reflect assumptions on regulatory timeline adherence and coating chemistry substitution elasticities. Material shifts in bisphenol-A migration limit stringency or fluoropolymer exemption frameworks would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Face Stock Films Market
Packaging Materials
Book Wraps Market
Packaging Materials
China Packaging Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Laminated Tubes Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
North America Stick Packaging Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
Postal Packaging Market
Packaging Materials
Packaging Reel Market
Packaging Materials
Foil Laminates Market
Packaging Materials
Flow Wraps Market
Packaging Materials
VCI Packaging Market
Packaging Materials
Tertiary Packaging Market