
 United States Print Label Market | 2026-2036
United States Print Label Market Size, Share, and Industry Trends Forecast 2026-2036
United States Print Label Market Analytics
California's SB 54 extended producer responsibility law is shifting demand toward recyclable and post-consumer recycled content labels across consumer packaged goods supply chains. Avery Dennison Corporation leverages its materials science portfolio to develop thinner film substrates that reduce plastic usage without sacrificing print fidelity. CCL Industries Inc. anchors North American pharmaceutical security labeling through specialized tamper-evident and serialization products. 3M Company differentiates via adhesive formulations engineered for extreme-temperature logistics environments.
United States print labels comprise substrates—paper, vinyl, polyester, or polypropylene—bearing printed information, barcodes, or graphics, applied via pressure-sensitive, heat-shrink, adhesive, or in-mold methods to identify, track, promote, or secure products throughout distribution and retail. Pressure-sensitive labels dominate unit volume due to versatility across automated and manual application lines, while heat-shrink formats command premium positioning in beverage and personal care segments requiring full-body container decoration. Food and beverage end users represent the most mature demand pool, whereas pharmaceutical barcode labeling carries the highest compliance-driven margin premiums.
FDA track-and-trace regulations for prescription drugs, EPA guidelines on volatile organic compound emissions from printing operations, and FTC Green Guides governing environmental marketing claims collectively shape material selection, ink chemistry, and supplier qualification protocols across the industry. OSHA workplace safety standards further influence label durability requirements in chemical and industrial applications. Stakeholders must weigh compliance cost trajectories against substrate innovation cycles when committing to multi-year printing equipment and supply agreements.
Market Dynamics
Pharmaceutical serialization mandates under the Drug Supply Chain Security Act are forcing substrate and adhesive suppliers to engineer tamper-evident, track-and-trace-compatible label architectures at production scale.
Growth Catalysts
- Pharmaceutical Compliance Mandates:FDA track-and-trace regulations for prescription drugs require unit-level barcode serialization, expanding demand for specialized security labels with integrated verification features.
- E-commerce Fultration Concentration:Direct-to-consumer distribution networks in California, Texas, and Pennsylvania are concentrating shipping label volumes as retailers expand automated fulfillment infrastructure.
- Film Substrate Innovation:Thinner polypropylene and polyester films are reducing plastic usage while maintaining print fidelity, aligning with California's SB 54 extended producer responsibility requirements.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and adhesive resin prices fluctuate with crude oil markets, compressing converter margins on long-term supply contracts.
- Domestic Equipment Concentration:Narrow base of domestic flexographic and digital press manufacturers creates lead time risk for capacity expansion programs.
- VOC Emission Controls:EPA guidelines on volatile organic compound emissions from solvent-based printing operations add capital expenditure burdens for smaller converters.
Strategic Opportunities
- Recyclable Content Labels:Post-consumer recycled substrate development opens premium positioning in consumer packaged goods supply chains responding to state-level packaging laws.
- Heat-Shrink Beverage Applications:Full-body container decoration demand in craft brewing and functional beverages offers margin expansion beyond conventional pressure-sensitive formats.
- Extreme-Temperature Logistics:Specialized adhesive formulations for frozen and heated supply chains address gaps in pharmaceutical and specialty food distribution.
Industry Challenges
- Digital Press Operator Shortage:Converters struggle to hire technicians skilled in hybrid flexographic-digital workflow management and color calibration.
- Multi-Agency Compliance Burden:Simultaneous FDA, EPA, FTC, and OSHA requirements create documentation complexity and audit preparation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Print Label Market |
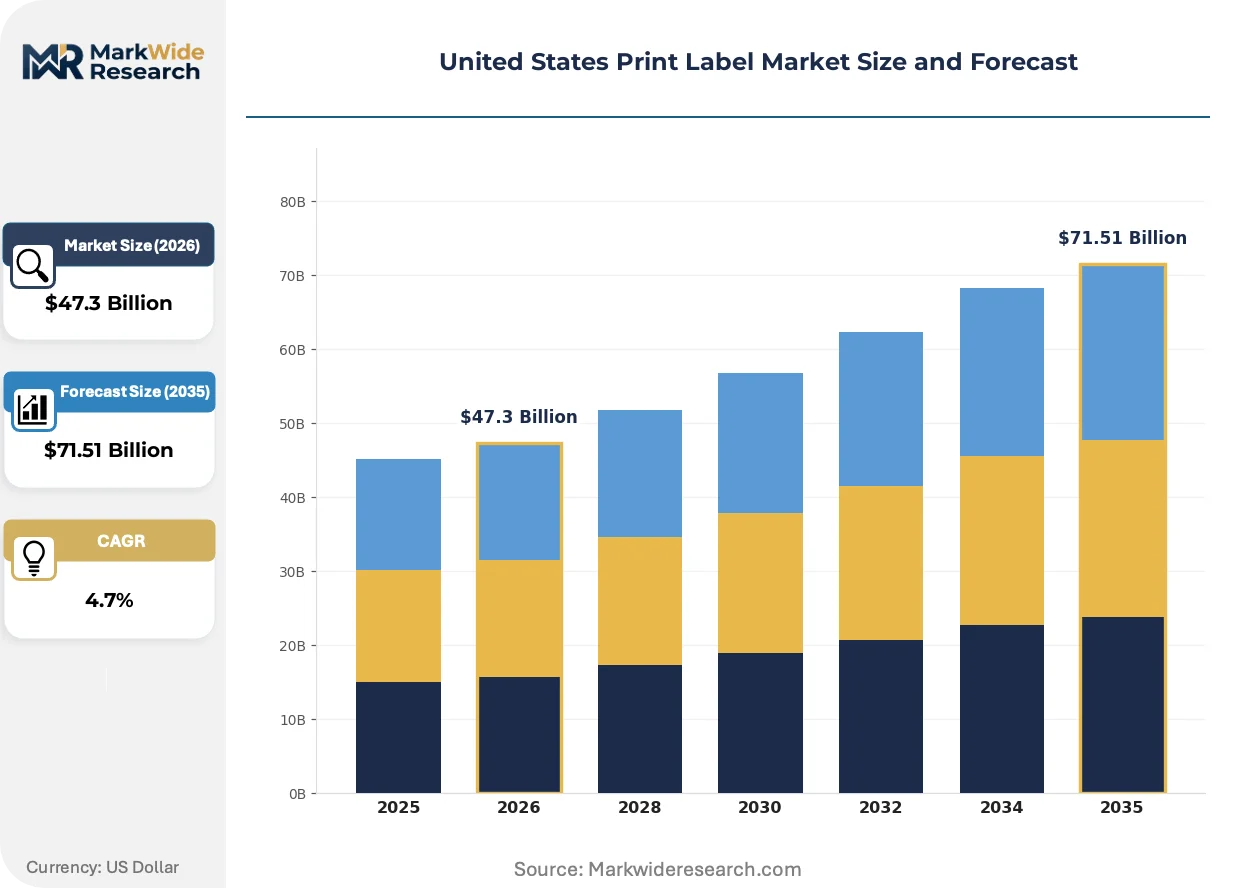
| Market Size in 2026 | $47.3 Billion |
| Market Size in 2035 | $71.51 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Pressure-Sensitive, Heat-Shrink, Adhesive, In-mold Material: Paper, Vinyl, Polyester, Polypropylene End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Application: Product Labeling, Barcode Labels, Shipping Labels, Promotional Labels |
| Companies Covered | Avery Dennison Corporation, CCL Industries Inc., Multi-Color Corporation, Taylor Corporation, 3M Company, Brady Corporation, UPM Raflatac, R.R. Donnelley & Sons Company, Mondi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Print Label Market Evolving Landscape
Digital printing integration with automated inspection systems is compressing production cycles while enabling mass customization at unit economics previously reserved for long-run flexographic jobs.
RFID inlay embedding is unifying inventory tracking with brand authentication functions in a single label construction. Pharmaceutical distributors and luxury goods manufacturers are adopting this at pilot scale now, with full production rollout expected across high-value supply chains. The technology is unifying what were separate barcode and security tag procurement decisions into consolidated supplier relationships.
California's SB 54 extended producer responsibility law is mandating recyclable or post-consumer recycled content thresholds for packaging materials, including labels. Consumer packaged goods brands are reformulating specifications to meet these thresholds ahead of enforcement deadlines. Food and beverage end users in the state are accelerating qualification of compliant substrate alternatives.
Direct procurement from converters is displacing distributor intermediaries among large e-commerce fulfillment operators. Amazon, Target, and Walmart are establishing captive label supply agreements with volume guarantees and dedicated production lines. This pattern is most visible in Pennsylvania and Texas distribution clusters where fulfillment center density supports dedicated manufacturing investment.
United States Print Label Market Segmentation
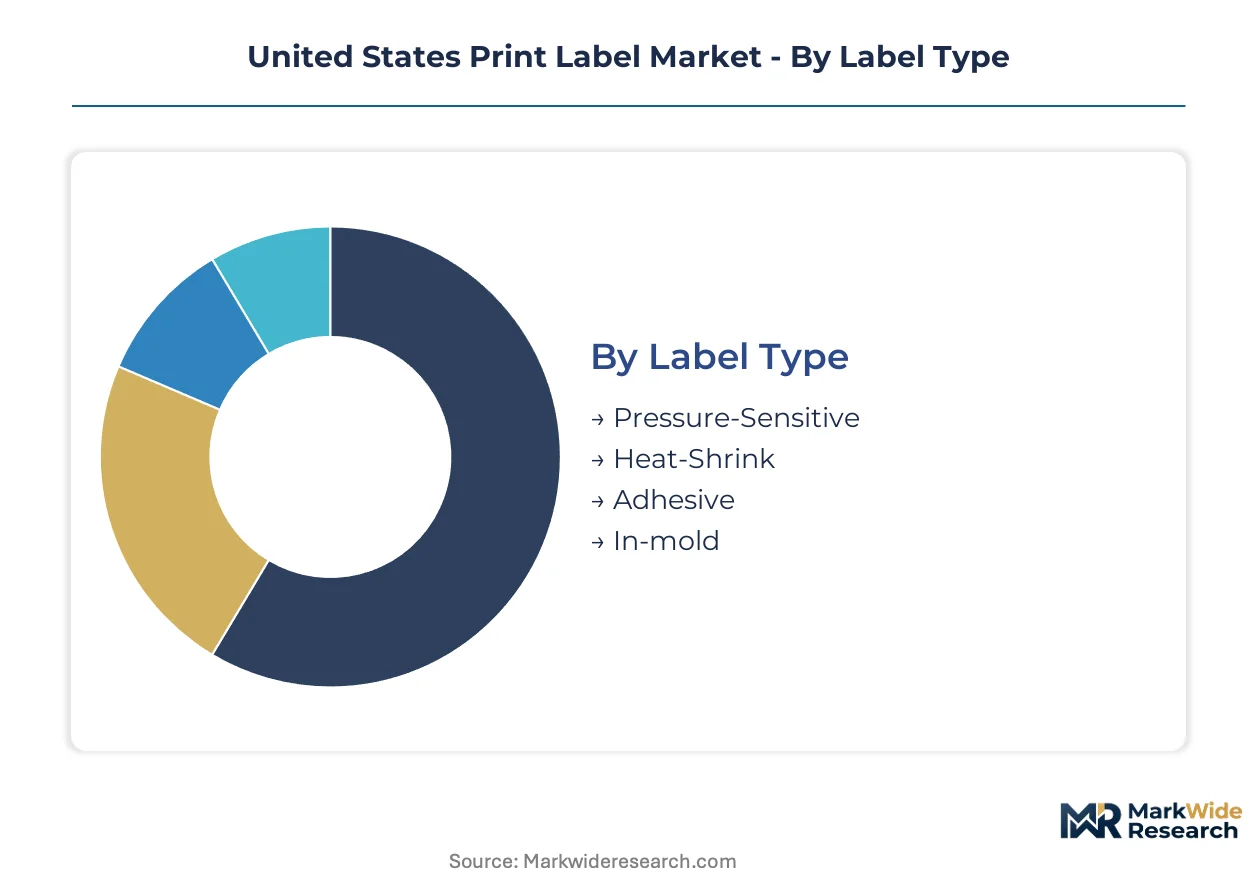
Segmentation in the United States print label market reveals distinct performance profiles across substrate technologies, application methods, and end-use compliance requirements. Procurement teams calibrate specifications against automation compatibility, regulatory exposure, and total applied cost rather than unit price alone.
Label Type:
Upgrade cycles in automated packaging lines are displacing legacy adhesive formats with pressure-sensitive and heat-shrink alternatives that integrate with vision inspection systems.
- Pressure-Sensitive:Self-adhesive construction with release liner enables high-speed application across both manual and automated lines. Food and beverage packaging lines in California and Texas fulfillment clusters account for the densest demand concentration as e-commerce direct-to-consumer volumes expand.
- Heat-Shrink:Full-body sleeve construction conforms to irregular container geometries through thermal activation. Craft brewing and functional beverage producers in Pennsylvania and Colorado are concentrating orders for premium shelf differentiation.
- Adhesive:Wet-glue application requires dedicated equipment and longer setup times. Legacy industrial chemical labeling in the Gulf Coast maintains residual demand.
- In-mold:Substrate fuses with container wall during blow-molding or injection processes. Automotive and durable goods manufacturers in Michigan and Ohio specify for abrasion resistance.
Pressure-Sensitive sits at the top of the volume ranking, with Heat-Shrink climbing the fastest.
Material:
Cost tier separation between commodity paper and engineered films is widening as California SB 54 compliance premiums reshape specification standards.
- Paper:Cellulose-based substrate with variable coatings for moisture resistance. Dry goods and short-shelf-life food applications in the Midwest maintain steady offtake.
- Vinyl:PVC construction delivers flexibility and chemical resistance for outdoor and industrial exposure. Construction material and agricultural chemical labeling in the Southeast specifies vinyl for weather durability.
- Polyester:PET film provides dimensional stability and thermal resistance across extreme logistics chains. Pharmaceutical distributors in New Jersey and Illinois are qualifying thinner-gauge variants to reduce plastic mass while retaining FDA track-and-trace readability.
- Polypropylene:Oriented PP film balances clarity, stiffness, and recyclability compliance. Beverage and personal care brands are accelerating adoption to meet post-consumer recycled content thresholds ahead of enforcement deadlines.
Polypropylene commands the steepest expansion trajectory as sustainability mandates tighten, with Paper retaining the largest installed base.
End User:
Application complexity and compliance burden create margin stratification across customer types, with pharmaceutical serialization carrying the highest qualification barriers.
- Food & Beverage:Mature demand pool with high volume and price sensitivity. Retail consolidation and private-label expansion are compressing converter margins despite stable unit offtake.
- Pharmaceuticals:Unit-level barcode serialization under FDA Drug Supply Chain Security Act mandates. CCL Industries and specialized security label converters are capturing premium positioning through tamper-evident and track-and-trace architectures.
- Cosmetics:Aesthetic and tactile specifications drive substrate innovation. Direct-to-consumer beauty brands are demanding shorter runs with mass-customization capabilities.
- Chemicals:OSHA workplace safety standards govern durability and hazard communication requirements. Industrial label demand concentrates in Texas and Louisiana petrochemical corridors.
Food & Beverage anchors volume scale, while Pharmaceuticals generates the highest per-unit margins.
Application:
Customer type—enterprise fulfillment operator versus regional manufacturer—determines procurement channel and specification granularity.
- Product Labeling:Primary container identification and brand communication. Consumer packaged goods specifications are converging on recyclable-content substrates.
- Barcode Labels:Machine-readable tracking across supply chain nodes. Pharmaceutical serialization and Amazon/Target/Walmart captive supply agreements are concentrating demand with qualified converters.
- Shipping Labels:Adhesive-backed logistics documentation for parcel sortation. California, Texas, and Pennsylvania fulfillment center density supports dedicated production line investment.
- Promotional Labels:Temporary price reduction and cross-sell messaging. Grocery and mass retail promotional calendars drive seasonal demand spikes.
Barcode Labels is gaining share fastest as compliance mandates deepen, with Shipping Labels holding the largest volume position.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pressure-sensitive adhesive technology first achieved commercial scale in the United States during the mid-20th century, establishing domestic converters as foundational suppliers to food, pharmaceutical, and industrial packaging sectors. The industry subsequently diffused across state-level manufacturing clusters tied to specific end-use concentrations.
California
E-commerce fulfillment centers in the Inland Empire and Central Valley generate dense shipping label demand as Amazon, Target, and Walmart expand automated sortation infrastructure. SB 54 extended producer responsibility mandates are forcing substrate qualification toward post-consumer recycled content thresholds. Los Angeles basin converters are retooling lines to meet recyclable-content specifications ahead of enforcement deadlines.
Texas
Petrochemical corridor demand for chemical drum and hazardous material labeling concentrates around Houston and Beaumont refining complexes. OSHA workplace safety standards govern durability specifications for industrial exposure applications. Dallas-Fort Worth fulfillment clusters are capturing dedicated production line investment from national retailers expanding direct-to-consumer distribution.
Pennsylvania
Pharmaceutical serialization mandates under the FDA Drug Supply Chain Security Act are concentrating track-and-trace barcode label demand near Philadelphia and Pittsburgh distribution hubs. The state's legacy printing infrastructure supports specialized tamper-evident and verification-feature production. Lehigh Valley logistics parks are anchoring captive supply agreements with volume-guaranteed production allocation.
Illinois
Pharmaceutical distributors in the Chicago metropolitan area are qualifying thinner-gauge polyester variants to reduce plastic mass while retaining FDA track-and-trace readability. Midwest dry goods and short-shelf-life food applications maintain steady paper substrate offtake. Rockford and Aurora industrial zones house converters serving automotive and durable goods in-mold labeling specifications.
Ohio
Automotive and durable goods manufacturers in the Toledo-Cleveland corridor specify in-mold labels for abrasion-resistant container identification. The state's manufacturing heritage supports legacy adhesive application equipment serving industrial chemical packaging. Cincinnati-area converters are positioning for craft brewing and functional beverage heat-shrink sleeve demand migrating from Pennsylvania and Colorado.
United States Print Label Market Competitive Landscape
Capital-heavy integrated substrate producers compete with asset-light specialized converters across tiered service models. The vendor base separates into three structural tiers: multinational material science conglomerates with captive adhesive and film production, mid-cap regional converters with dedicated equipment lines for specific end-use verticals, and distributed job shops serving short-run promotional and seasonal demand. Consolidation pressure is intensifying through strategic acquisition of digital press capacity and backward integration into film extrusion.
Among integrated material science specialists, Avery Dennison Corporation and 3M Company occupy positions exemplifying substrate-adhesive vertical coordination, while CCL Industries Inc. represents the security-label specialist archetype focused on pharmaceutical compliance architectures. These anchors demonstrate how scale-driven substrate innovation, regulatory specialization, and geographic production density constitute distinct competitive vectors within the same end-use markets.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Multi-Color Corporation |
| Taylor Corporation |
| 3M Company |
| Brady Corporation |
| UPM Raflatac |
| R.R. Donnelley & Sons Company |
| Mondi |
| Others |
Value Network & Pricing Analysis
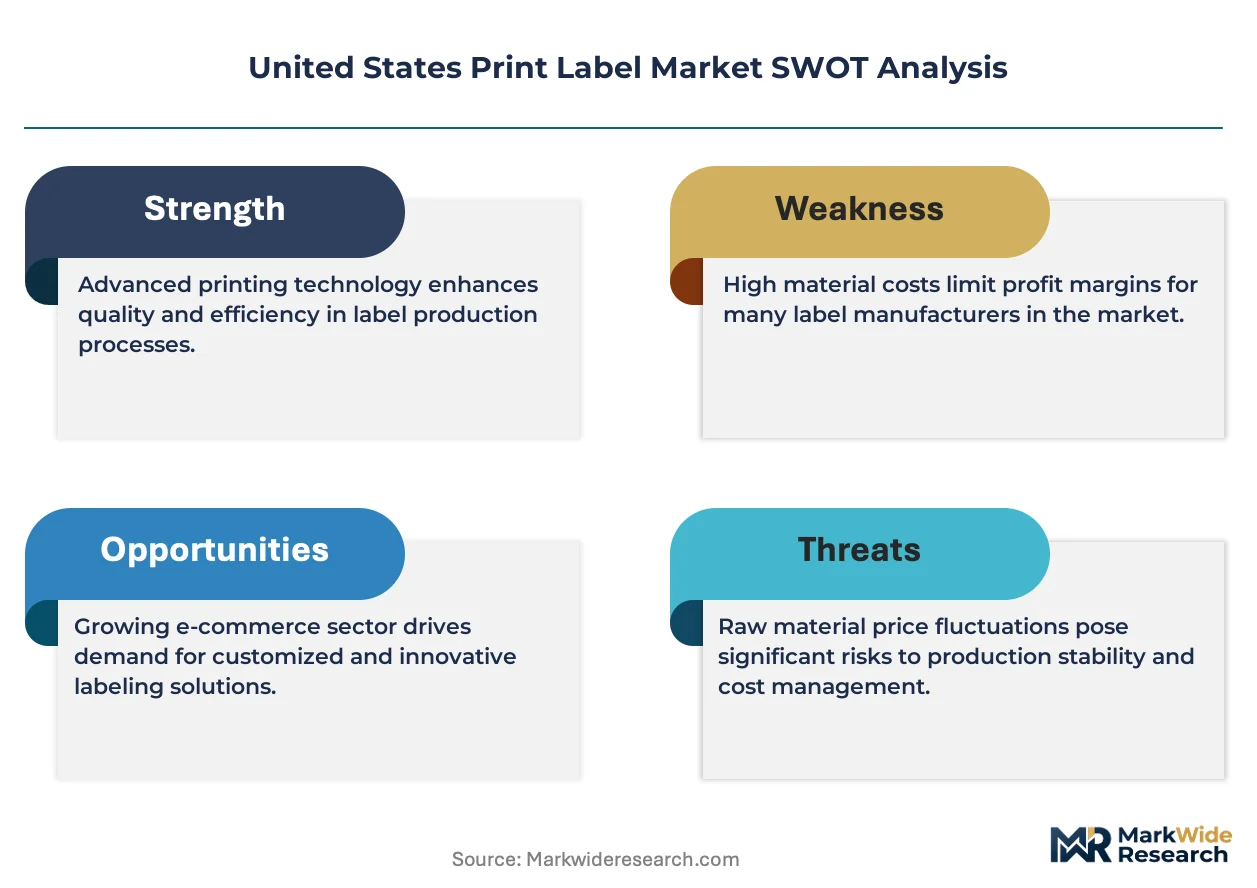
Large e-commerce fulfillment operators in California, Texas, and Pennsylvania negotiate volume-guaranteed captive supply agreements that compress converter margins while securing dedicated production line allocation. This buyer concentration establishes contract-based long-term offtake as the dominant pricing model, with spot-market transactions relegated to smaller regional manufacturers and seasonal promotional demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical serialization grades with FDA track-and-trace compliance from commodity food-grade pressure-sensitive labels and generic shipping formats. Price differentiation hinges on certification tier and volume scale, with enterprise fulfillment contracts commanding 40-60% discounts against list rates. Cost compression in the standard tier is intensifying because polypropylene resin feedstock volatility squeezes converter margins on fixed-price agreements. Food and beverage private-label buyers exhibit the highest price sensitivity, while pharmaceutical distributors accept premium positioning for tamper-evident architectures.
Supply Chain Analysis
Regional distribution centers in the Inland Empire, Dallas-Fort Worth, and Lehigh Valley operate on hub-and-spoke patterns that concentrate finished label inventory within 200 miles of major fulfillment clusters. Raw material supply draws from domestic petrochemical corridors in Texas and Louisiana for adhesive resins, with polyester and polypropylene films sourced from South Korea, Japan, and domestic extrusion facilities. Single-source vulnerability in digital press equipment—domestic manufacturers narrow to a handful of specialized builders—creates lead time risk for capacity expansion programs. Distribution runs through converter-direct relationships with national retailers, displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States print label market functions as a geographic-arbitrage play where converters locate production in Pennsylvania and Texas to exploit lower energy costs and weaker union density against California's SB 54 compliance premiums.
For Market Incumbents: Deploy backward integration into film extrusion to secure polypropylene supply against petrochemical feedstock volatility. CCL Industries and Avery Dennison should consolidate digital press capacity in Lehigh Valley and Dallas-Fort Worth to defend margin position against Amazon's captive supply expansion. Certification investment in FDA track-and-trace architectures creates switching costs that lock in pharmaceutical distributor relationships. For New Entrants and Emerging Players: Launch via specialized heat-shrink sleeve production for craft brewing clusters in Ohio and Colorado, where aesthetic differentiation commands premium positioning and incumbent converters underinvest. Target extreme-temperature adhesive formulations for frozen pharmaceutical distribution as the most penetrable application gap. Direct-to-consumer beauty brands seeking mass-customization capabilities offer a white-space channel with shorter qualification cycles than enterprise fulfillment. For Investors and Strategic Acquirers: Private equity firms with packaging platform experience are the most active acquirer in this space, rolling up mid-cap regional converters with dedicated equipment lines. The long-term viability window favors targets with pharmaceutical compliance architectures and captive e-commerce supply relationships. Watch for FDA enforcement action on Drug Supply Chain Security Act deadlines as the inflection signal that accelerates consolidation among undercapitalized security-label specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive polypropylene supply insulates margins against crude-linked resin volatility in Texas corridors. |
| Digital Press Capacity Expansion | Hybrid flexographic-digital workflows in Pennsylvania reduce setup waste for shorter pharmaceutical runs. |
| Recyclable Content Certification | Post-consumer recycled substrate qualification opens California SB 54-compliant CPG procurement channels. |
| RFID Inlay Embedding Scale-Up | Unified inventory-authentication labels consolidate supplier relationships for pharmaceutical distributors. |
| Extreme-Temperature Adhesive Development | Specialized formulations for frozen logistics address gaps in specialty food and pharmaceutical cold chains. |
Research Methodology
Multiple input streams — converter production data, resin pricing indices, and fulfillment center expansion announcements — were reconciled through structured primary interviews with label procurement managers at national retailers, plant managers at regional converters, regulatory affairs leads at pharmaceutical distributors, and technical R&D directors at adhesive suppliers. Secondary validation drew from EPA VOC emission filings, FDA Drug Supply Chain Security Act guidance documents, SEC 10-K disclosures from listed packaging companies, and California SB 54 implementation timelines. Bottom-up volume estimates by substrate type and application method were triangulated against top-down market sizing from trade association production surveys.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions for pressure-sensitive, heat-shrink, adhesive, and in-mold label types, cross-referenced with material trajectories in paper, vinyl, polyester, and polypropylene. End-user demand curves modeled food and beverage, pharmaceutical, cosmetics, and chemical applications against automation compatibility and compliance burden differentials. CAGRs were derived from historical production volume trends and forward-looking capacity expansion announcements, with pharmaceutical serialization mandates and e-commerce fulfillment density as primary forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical price spikes, accelerated FDA enforcement timelines, or delays in digital press equipment delivery. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Freshness Indicator Label Market
Labels
Eco-Friendly Labels Market
Labels
Label Applicator Market
Labels
Hang Tags Market
Labels
Freezer Label Market
Labels
Cut and Stack Labels Market
Labels
Industrial Label Printers Market
Labels
Shrink and Stretch Sleeve Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Retro-Reflective Labels Market
Labels
Shrink Sleeve Label Applicator Market
Labels
Global Security Labels Market
Labels
Global Pressure Labels Market
Labels
GCC Labeling Market
Labels
Metallic Labels Market
Labels
Integrated Labeling System Market