
 Plastic Strapping Materials Market | 2026-2036
Plastic Strapping Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Strapping Materials Market Outlook
Polypropylene is broadening its addressable market as a cost-effective substitute for steel in mid-weight bundling applications across consumer goods and food processing. Teufelberger leverages its Austrian fiber technology heritage to dominate high-tenacity PET strapping for construction and heavy industrial loads. Dynaric sustains North American market presence through specialized extrusion equipment that integrates strapping heads with automated packaging lines. Samuel Strapping anchors its competitive position via backward integration into steel and plastic resin supply chains.
Plastic strapping materials are extruded polymer bands, typically manufactured from polyethylene terephthalate (PET) or polypropylene (PP) resin with tensile strengths ranging from 300 to 2,000 pounds per square inch, designed to secure, bundle, or unitize goods for handling and transport. PET strapping leads in heavy-load palletizing due to superior elongation recovery and weather resistance, while PP grades occupy high-volume bundling where cost-per-foot governs procurement decisions. Application segmentation shows logistics outpacing retail packaging as e-commerce fulfillment centers specify automated strapping systems with consistent joint efficiency.
The EPA's recycled content standards and California's rigid plastic packaging container laws shape resin sourcing decisions for US-based converters, while REACH compliance in Europe restricts certain plasticizers and additives in strapping formulations destined for food-contact export pallets. China's GB standards for packaging materials mandate specific tensile testing protocols that foreign suppliers must certify through the national standards body. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode margin pools in contract strapping supply.
Market Dynamics
Automated strapping line deployment in Chinese export manufacturing clusters is compressing procurement cycles and forcing grade standardization across PET and polypropylene supply tiers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Recyclability mandates are pulling converters toward certified recycled-content PET grades for palletized exports to European distribution centers.
- Heavy-load palletizing:Asia-Pacific logistics operators are specifying high-tenacity PET strapping for containerized electronics and appliance shipments, displacing steel in weight-critical applications.
- Closed-loop extrusion:Post-industrial scrap recovery systems are lowering effective resin costs for integrated strapping producers serving high-volume bundling contracts.
Market Restraints
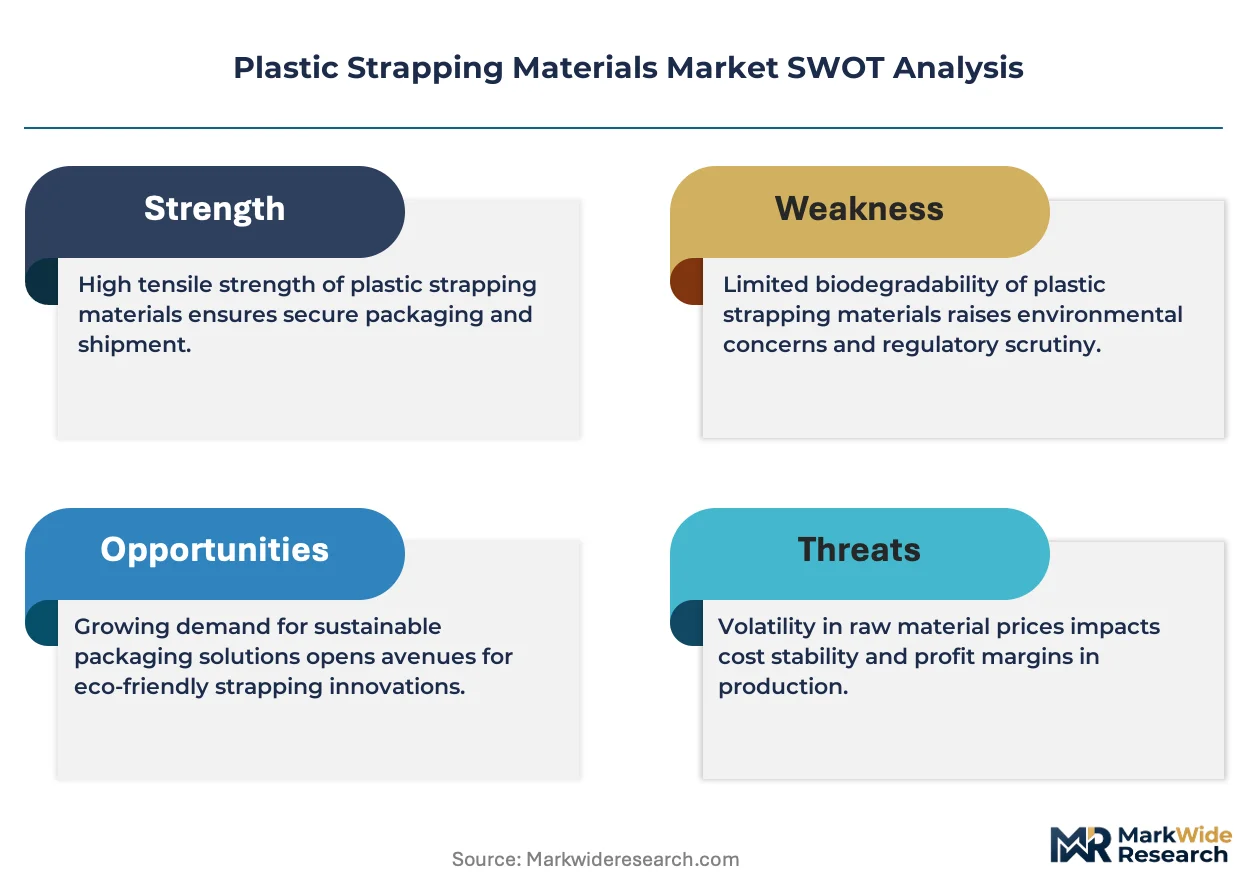
- Resin price volatility:Crude-linked polypropylene feedstock costs swing procurement budgets for mid-tier converters locked into annual bundling supply agreements.
- Steel substitution ceiling:Hot-rolled coil pricing dips periodically resurrect steel strapping in construction and metal coil applications, capping PET penetration in heavy industrial segments.
- REACH additive restrictions:ECHA limitations on specific plasticizers force reformulation of food-contact strapping grades, extending certification timelines for European-bound shipments.
Strategic Opportunities
- India export manufacturing:Electronics assembly clusters in Tamil Nadu and Karnataka lack automated strapping infrastructure, creating first-mover advantage for equipment-integrated suppliers.
- Bio-based PP development:Polypropylene derived from agricultural waste streams offers brand differentiation for consumer goods bundling where sustainability claims command shelf placement.
- Direct-to-fulfillment-center distribution:Bypassing traditional packaging distributors, strapping producers are contracting directly with e-commerce warehouse operators for specification lock-in.
Industry Challenges
- GB standards certification:China's national standards body requires foreign strapping suppliers to complete tensile testing protocols that add six to nine months to market entry timelines.
- Legacy steel strapping infrastructure:Converters with captive galvanizing lines face stranded asset risk when customers mandate polymer-only handling systems for international shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Strapping Materials Market |
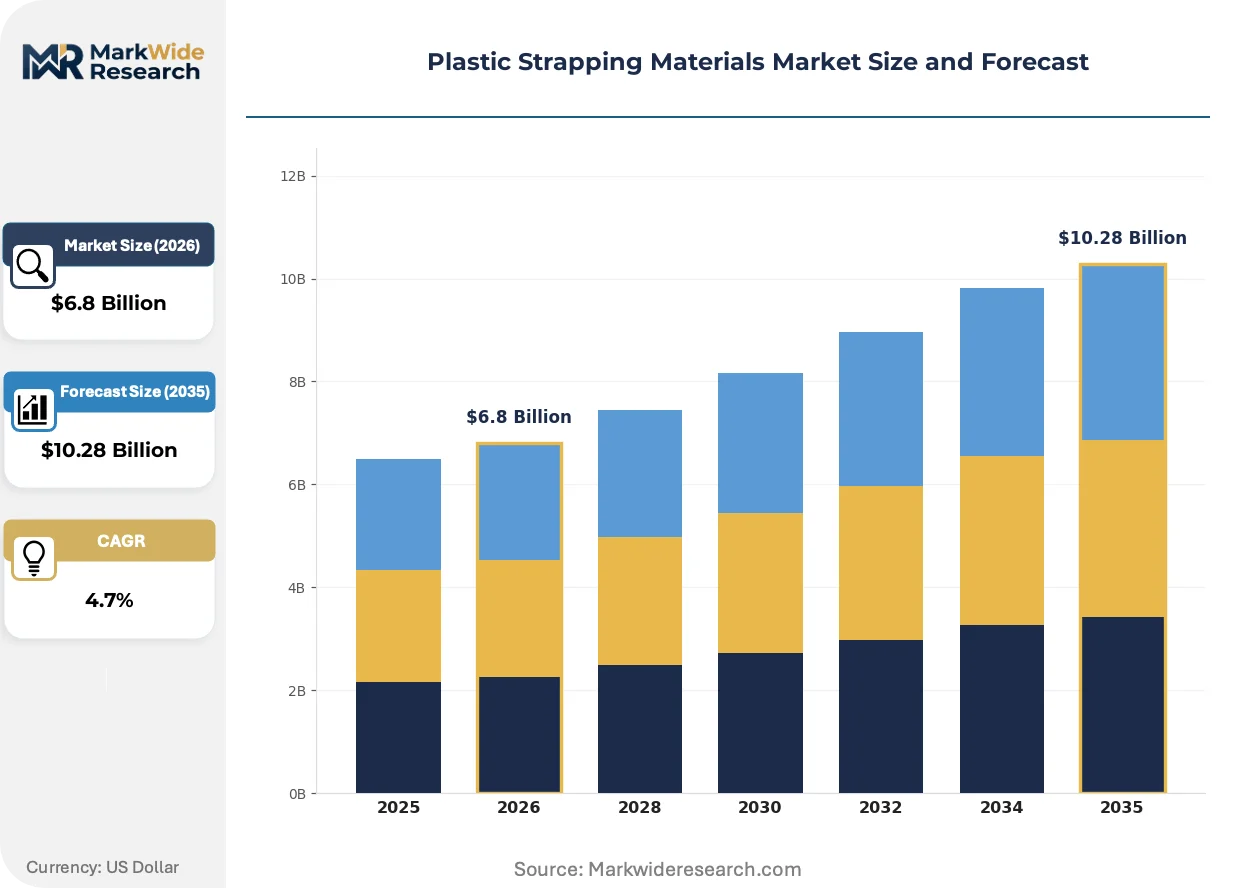
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, PP, Nylon, Steel Application: Packaging, Logistics, Palletizing, Bundling End User: Retail, Manufacturing, Shipping, Construction Distribution Channel: Direct Sales, E-Commerce, Distributors, Dealers |
| Companies Covered | Teufelberger, Dynaric, Signode, Samuel Strapping, Mosca, Polychem, Strapack, Scientex Berhad, FROMM Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Strapping Materials Market Strategic Shifts
Extrusion and joint-sealing technologies are converging with warehouse automation architectures, reshaping how strapping specifications propagate through supply contracts.
Vision-guided strapping heads equipped with real-time tension feedback are automating pallet securing in high-throughput fulfillment centers. E-commerce operators in Germany and the Netherlands are retrofitting existing lines with these systems to eliminate manual quality verification stations. The technology is automating workforce reduction in facilities where labor availability constrains peak-season throughput scaling.
REACH compliance deadlines for restricted substance categories are forcing additive substitutions in UV-stabilized strapping formulations. European converters are qualifying alternative hindered amine light stabilizers ahead of sunset dates for legacy chemistries. Food-contact pallet strapping destined for EU retail distribution faces the tightest reformulation windows, with some suppliers advancing bio-based stabilizer platforms to preempt regulatory disruption.
Specification consolidation among multinational logistics providers is compressing the approved vendor lists for strapping procurement. Third-party fulfillment operators in the US Southeast are mandating ISO-certified joint efficiency testing as a baseline qualification, displacing regional converters lacking accredited laboratory partnerships. This concentration is most visible in automotive parts distribution, where tier-one suppliers face downstream pressure to standardize pallet securing protocols across their North American warehouse networks.
Plastic Strapping Materials Market Segmentation
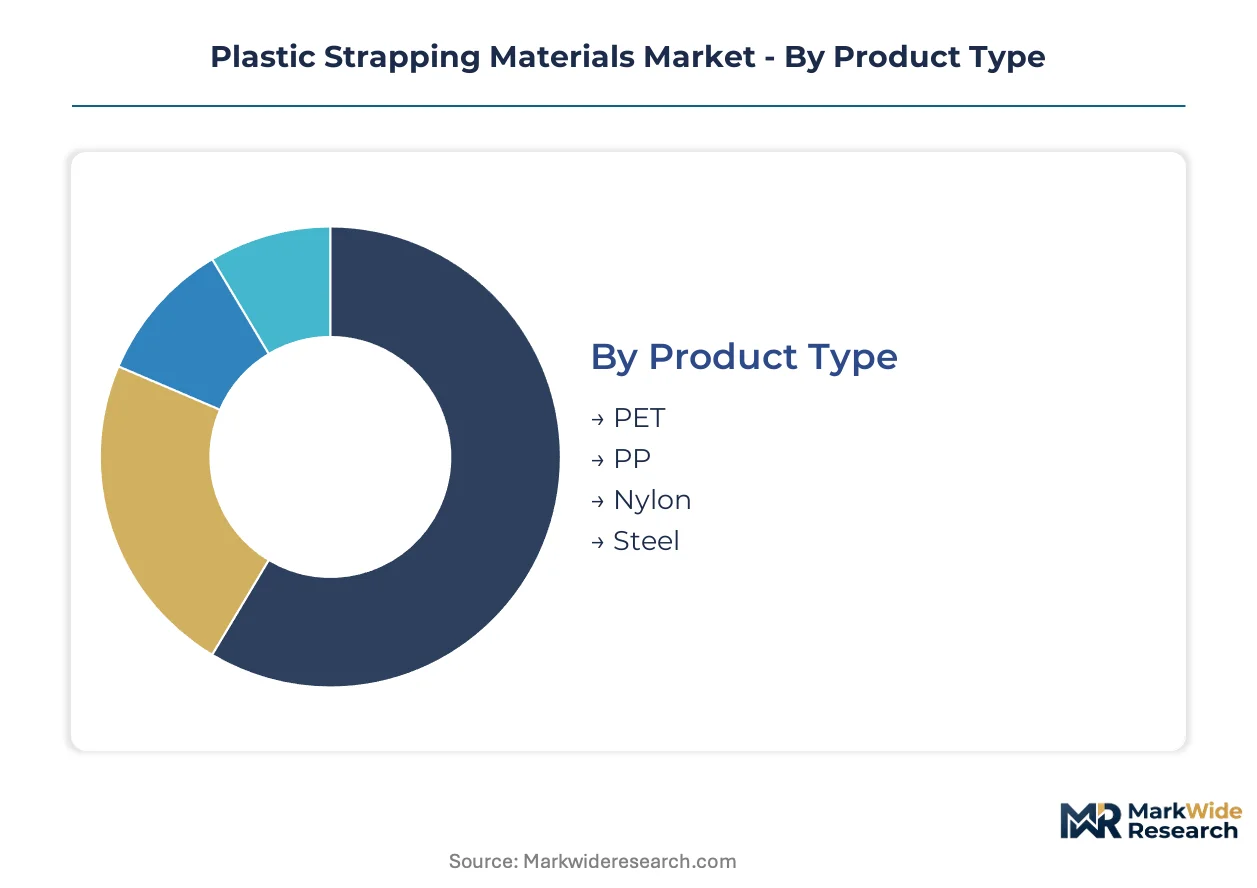
Strapping procurement decisions diverge sharply across material grades, application stresses, and channel economics. Specification lock-in by end-use vertical creates distinct margin pools that converters must navigate through differentiated product positioning.
Product Type:
Buyers in this category separate by load-bearing requirements and weather exposure tolerance rather than upfront unit cost.
- PET:Extruded polyethylene terephthalate delivers elongation recovery above 10% and tensile strength spanning 600-2,000 psi. Electronics manufacturers in China's export belt specify high-tenacity PET for containerized appliance shipments where moisture resistance prevents load relaxation during ocean transit.
- PP:Polypropylene strapping occupies high-velocity bundling lines where cost-per-foot governs procurement. Food processors in Germany favor PP for lightweight carton sealing under EFSA food-contact compliance frameworks.
- Nylon:Premium-grade polyamide strapping serves extreme cold-chain applications requiring flexibility retention at sub-zero temperatures.
- Steel:Hot-rolled coil strapping persists in metal coil and construction material securing where cut-through resistance outweighs weight penalties.
Volume sits with PP; growth tilts toward PET.
Application:
Operational throughput demands and automation readiness distinguish procurement patterns across use cases.
- Logistics:Automated strapping heads in e-commerce fulfillment centers require consistent joint efficiency above 85% to maintain line speeds. Third-party operators in the Netherlands are retrofitting vision-guided tension feedback systems to eliminate manual quality stations.
- Palletizing:Heavy-load unitization for containerized exports drives specification toward high-tenacity grades with weather stabilization. Asia-Pacific electronics clusters specify automated PET systems for outbound appliance flows.
- Packaging:Retail-ready bundling emphasizes printability and color consistency for shelf-facing applications.
- Bundling:High-volume consumer goods aggregation favors cost-optimized PP grades with rapid heat-seal joint formation.
Procurement concentrates in logistics; palletizing commands the steepest expansion trajectory.
End User:
Asset intensity and shipment destination requirements fragment buyer priorities across verticals.
- Manufacturing:Integrated producers with captive extrusion lines prioritize resin cost stability and closed-loop scrap recovery. Electronics assembly plants in Tamil Nadu lack automated strapping infrastructure, creating specification gaps for equipment-integrated suppliers.
- Shipping:Container freight operators face downstream pressure to standardize securing protocols across warehouse networks, compressing approved vendor lists.
- Retail:Brand owners specify certified recycled-content grades to meet EU Packaging and Packaging Waste Regulation requirements for palletized exports.
- Construction:Metal coil handlers periodically revert to steel strapping when hot-rolled coil pricing dips, capping polymer penetration.
Manufacturing anchors volume; retail drives specification upgrading fastest.
Distribution Channel:
Contract scale and technical service needs determine channel selection for strapping procurement.
- Direct Sales:Large-format e-commerce operators contract directly with strapping producers for specification lock-in, bypassing traditional packaging distributors. Fulfillment centers in Germany mandate ISO-certified joint efficiency testing as baseline qualification.
- Distributors:Regional converters lacking accredited laboratory partnerships face displacement as multinational logistics providers consolidate procurement.
- E-Commerce:Small-volume buyers access standardized grades through digital procurement platforms with limited technical support.
- Dealers:Local equipment integrators bundle strapping supply with maintenance contracts for mid-tier manufacturing plants.
Direct sales capture the largest contract value; distributor relationships face compression from specification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's export manufacturing belt special economic zones concentrate automated strapping infrastructure investment, while EU regulatory pressure and US recycled-content mandates reshape resin sourcing across regional supply chains.
China
Electronics and appliance manufacturers in the Yangtze River Delta and Pearl River Delta drive PET strapping consumption for containerized export palletizing. GB standards for packaging materials mandate tensile testing certification through the national standards body, extending foreign supplier entry timelines. Shenzhen and Dongguan clusters deploy vision-guided automated strapping heads to compress procurement cycles for outbound flows.
Germany
E-commerce fulfillment operators in the Netherlands-Germany corridor retrofit existing lines with real-time tension feedback systems to eliminate manual quality stations. REACH compliance deadlines force additive substitutions in UV-stabilized formulations ahead of sunset dates for legacy chemistries. The Rhine-Ruhr industrial region concentrates converter capacity serving automotive parts distribution networks.
United States
EPA recycled content standards and California's rigid plastic packaging container laws shape resin sourcing decisions for domestic converters. Third-party fulfillment operators in the Southeast mandate ISO-certified joint efficiency testing as baseline vendor qualification. The Midwest manufacturing belt anchors high-volume PP bundling contracts for consumer goods aggregation.
India
Electronics assembly clusters in Tamil Nadu and Karnataka lack automated strapping infrastructure, creating specification gaps for equipment-integrated suppliers. BIS certification requirements for imported packaging materials add regulatory friction for foreign entrants. The Chennai-Bengaluru industrial corridor attracts first-mover investment in automated palletizing systems for export manufacturing.
Japan
Cold-chain logistics operators specify premium-grade nylon strapping for sub-zero flexibility retention in pharmaceutical and food distribution. METI efficiency standards for packaging equipment drive adoption of integrated strapping heads with automated warehouse systems. The Kanto region around Tokyo concentrates demand from precision electronics manufacturers requiring moisture-resistant securing protocols.
Plastic Strapping Materials Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated extrusion equipment suppliers commanding premium positioning in automated lines while regional resin converters compete on cost-per-foot in high-volume bundling. The vendor base organizes around three strategic archetypes: fiber technology heritage players leveraging high-tenacity PET formulations, specialized extrusion equipment integrators, and backward-integrated resin processors. Dominant competitive moves include specification lock-in through direct e-commerce fulfillment contracts and closed-loop scrap recovery systems that lower effective resin costs.
Within the fiber technology heritage tier, Teufelberger and Samuel Strapping exemplify divergent integration strategies—Teufelberger leveraging Austrian technical fiber capabilities for heavy-load applications, while Samuel Strapping anchors positioning through captive supply of steel and plastic resin feedstocks. Among North American equipment specialists, Dynaric occupies a position representing the extrusion-integrated automation archetype. These three entities collectively illustrate how competitive positioning stratifies across material science depth, equipment integration, and upstream supply control rather than scale alone.
| Leading Market Players |
|---|
| Teufelberger |
| Dynaric |
| Signode |
| Samuel Strapping |
| Mosca |
| Polychem |
| Strapack |
| Scientex Berhad |
| FROMM Group |
| Others |
Value Chain & Pricing Dynamics
EU recyclability mandates for palletized exports are forcing converters toward certified recycled-content PET grades, compressing margin pools for suppliers lacking accredited sourcing and reshaping procurement economics toward specification-driven premiums.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as e-commerce fulfillment centers penalize suppliers unable to meet compressed procurement cycles in China's export belt. Pricing stratifies across certified recycled-content, virgin high-tenacity, and economy-grade PP tiers. Cost compression in mid-tier PP bundling intensifies because resin price volatility erodes annual contract margins. High-volume consumer goods aggregators exhibit acute price sensitivity, while electronics manufacturers prioritizing moisture-resistant ocean transit specifications show markedly lower elasticity.
Supply Chain Analysis
Post-industrial scrap recovery flows are lowering effective resin costs for integrated strapping producers serving closed-loop contracts. Manufacturing concentrates in China, Germany, and the United States. Feedstock draws from crude-linked polypropylene and recycled PET flake. Single-source vulnerability looms in high-tenacity PET fiber supply where Austrian technical heritage dominates. Distribution runs through direct sales to large-format e-commerce operators and equipment-integrated dealer networks for mid-tier manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic strapping materials market functions as a cost-of-compliance arena where REACH additive restrictions and EU Packaging and Packaging Waste Regulation create durable moats for converters with pre-qualified food-contact and recycled-content grades.
For Market Incumbents: Cement specification lock-in through direct e-commerce fulfillment contracts in Germany and the Netherlands, insulating against distributor displacement as multinational logistics providers consolidate procurement. Invest in closed-loop extrusion infrastructure to capture margin from post-industrial scrap recovery. Prioritize backward integration into resin supply to buffer against crude-linked polypropylene volatility threatening annual bundling agreements. For New Entrants and Emerging Players: Vision-guided strapping heads with real-time tension feedback offer a technology-first wedge into India's Tamil Nadu and Karnataka electronics clusters lacking automated palletizing infrastructure. Target equipment-integrated supply contracts where first-mover advantage persists. Pursue BIS certification early to compress regulatory friction timelines for imported packaging materials. For Investors and Strategic Acquirers: Re-rating potential sits with fiber technology heritage players given EU regulatory deadlines forcing additive substitutions ahead of legacy chemistry sunset dates. Long-term viability favors converters with captive high-tenacity PET formulation capabilities and accredited laboratory partnerships. Monitor REACH compliance certification timelines as inflection indicators for market share redistribution toward pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive polypropylene and PET sourcing buffers margin erosion from crude-linked feedstock volatility. |
| Closed-Loop Scrap Recovery Systems | Post-industrial reprocessing lowers effective material costs for high-volume bundling contract winners. |
| Direct-to-Fulfillment-Center Distribution | Bypassing traditional distributors secures specification lock-in with German and Dutch e-commerce operators. |
| REACH-Compliant Additive Qualification | Pre-approved UV stabilizer platforms preempt reformulation disruption for EU-bound food-contact pallet strapping. |
| GB Standards Certification Investment | Early tensile testing protocol completion compresses six-to-nine-month market entry timelines for China access. |
Study Parameters
Document review covered customs and trade data, SEC filings from packaging equipment manufacturers, and EU regulatory submissions, complemented by interviews with plant managers at integrated strapping converters, procurement leads at third-party logistics operators, distribution channel partners, and technical R&D directors specializing in polymer extrusion. Primary fieldwork across China's Yangtze River Delta, Germany's Rhine-Ruhr region, and the US Midwest manufacturing belt informed demand-side validation. Secondary sources included resin price indices, automated packaging line deployment databases, and national standards body certification records. Bottom-up contract value estimates and top-down resin consumption models were triangulated for cross-verification.
Segment-level outputs across material grade, application stress, end-use vertical, and regional production hub were generated through the analytical framework. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules. Industry-specific inputs encompassed e-commerce fulfillment center automation adoption curves, REACH compliance deadline impacts on reformulation timelines, and GB standards certification bottlenecks affecting foreign supplier entry.
Several conditions sit outside the modeled scope, including abrupt steel strapping substitution reversals triggered by hot-rolled coil pricing dips and unforeseen regulatory divergence between EU and Chinese food-contact packaging standards. Forecasts reflect assumptions regarding sustained e-commerce infrastructure investment and resin price regime stability. Practitioners should monitor hot-rolled coil price indices and REACH sunset date enforcement intensity for early signals of demand and margin trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Laminated Tubes Market
Packaging Materials
Packaging Suction Cups Market
Packaging Materials
Construction Films Market
Packaging Materials
Expendable Packaging Market
Packaging Materials
Packaging Inserts Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Asia-Pacific Solar Control Window Films Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Composite Packaging Market
Packaging Materials
Floppy Disk Liner Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Crimped End Mailing Tubes Market