
 Sliding Blister Packaging Market | 2026-2036
Sliding Blister Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Sliding Blister Packaging Market Analytics
Buyer concentration among pharmaceutical contract packagers is expanding as mid-sized generics manufacturers consolidate procurement across fewer vendors. Rohrer Corporation leverages in-house thermoforming and printing capabilities to serve these consolidated buyers with shorter lead times. Ecobliss Holding BV anchors its position through specialized child-resistant closure technologies that meet stringent pharmaceutical safety standards. Tekni-Plex competes by extending its material science expertise into multi-layer barrier films for moisture-sensitive drug applications.
Sliding blister packaging consists of a thermoformed plastic cavity sealed to a printed card or lidding material, with a sliding mechanism enabling product access without full seal destruction; typical constructions use PVC, PET, or polyethylene in gauges ranging from 0.010 to 0.030 inches, formed via pressure or vacuum thermoforming to create precise dimensional tolerances for product retention and display visibility. The format serves retail environments where theft deterrence, product visibility, and consumer interaction must coexist in a single package. Standard blister configurations dominate volume production for commodity pharmaceutical tablets, while custom blister designs command premium positioning in cosmetic and small device segments where shelf differentiation drives purchase decisions. Clamshell blister variants sustain growth in consumer electronics by accommodating irregular geometries without secondary tooling investments.
FDA regulations governing pharmaceutical packaging integrity and child-resistance directly shape material selection and closure design requirements for US-market suppliers. REACH and RoHS frameworks in Europe restrict certain plasticizers and heavy metals in packaging substrates, compelling converters to certify alternative formulations through ECHA-recognized testing protocols. Stakeholders must monitor evolving extended producer responsibility schemes across multiple jurisdictions, as these programs increasingly assign end-of-life collection costs to original packaging manufacturers rather than downstream waste handlers.
Market Dynamics
Pharmaceutical contract packagers are consolidating procurement volumes across fewer vendors, forcing converters to absorb tooling costs and compress lead times or exit commodity tablet formats entirely.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mono-material PET structures gain preference as converters redesign laminates to meet tightened recovery thresholds without mechanical separation.
- Germany's central European distribution networks:Contract packagers in Bavaria and North Rhine-Westphalia aggregate demand from Polish and Czech generics manufacturers, creating dense order clusters for regional converters.
- Child-resistant closure innovation:Push-slide mechanisms with dual-action release now satisfy FDA 16 CFR 1700 protocols while preserving senior-friendly access for arthritis patients.
Market Restraints
- Resin cost volatility:PET and PVC pricing tracks ethylene feedstock swings from Gulf Coast crackers, squeezing converter margins on fixed-price annual contracts.
- Tooling capital intensity:Precision thermoforming molds for 0.015-inch gauge cavities require 12-16 week lead times and six-figure investments, deterring mid-volume entrants.
- Substitution by cold-form foil:Aluminum-polymer laminates capture moisture-sensitive prescriptions where sliding blister barrier performance falls short.
Strategic Opportunities
- Indian pharmaceutical export packaging:CDSCO-aligned child-resistant formats for US-bound generics remain undersupplied by domestic Indian thermoformers.
- Cosmetic device convergence:Sliding blisters for serum-filled micro-needling rollers merge pharmaceutical barrier standards with prestige retail unboxing rituals.
- Extended producer responsibility schemes:France's Citeo modulation fees reward mono-material designs with lower eco-contribution rates than multi-layer alternatives.
Industry Challenges
- Validation timeline compression:Pharmaceutical customers now demand 90-day qualification cycles for new cavity geometries, down from 180 days historically.
- Colorant compliance complexity:REACH Annex XVII restrictions on heavy metal pigments force reformulation of brand-consistent lidding inks mid-contract.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sliding Blister Packaging Market |
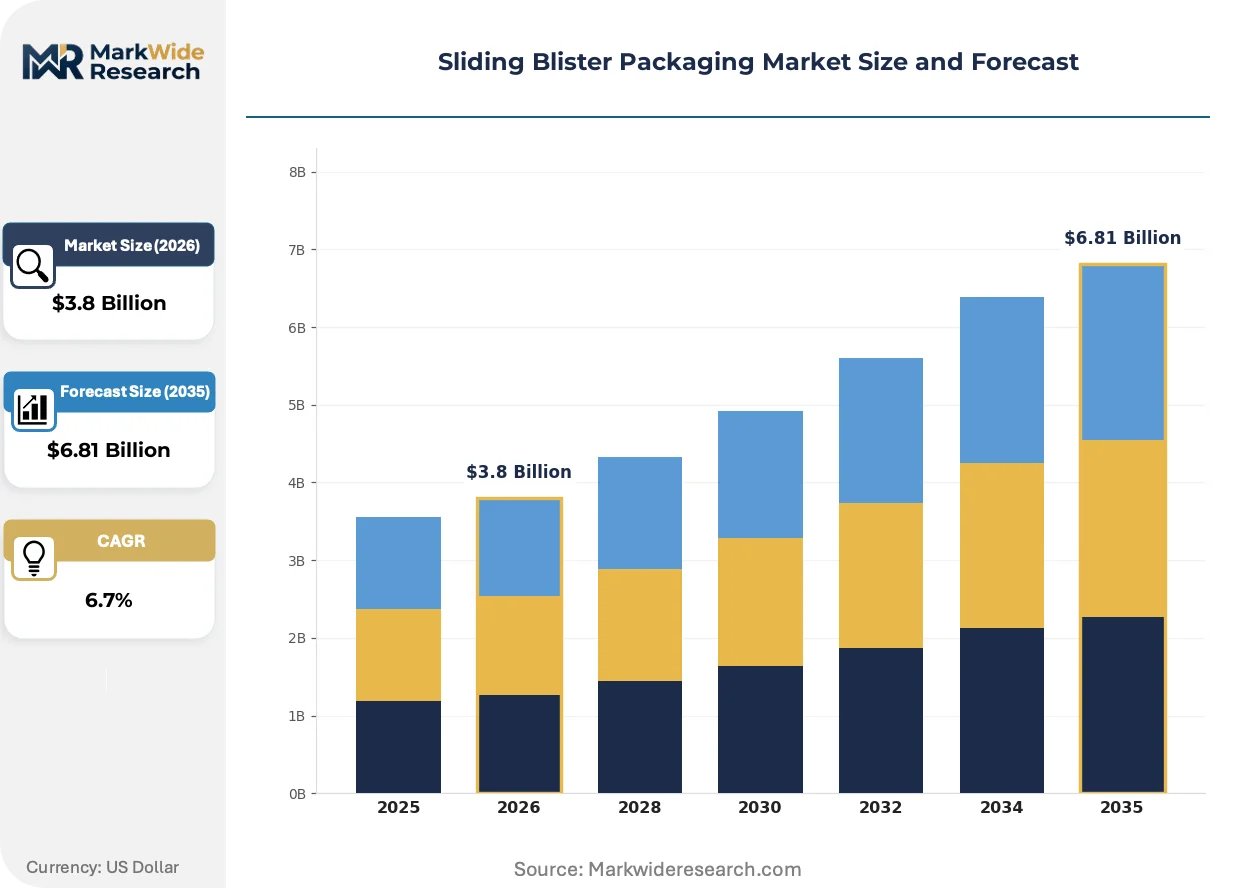
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Blister, Clamshell Blister, Pocket Blister, Custom Blister Material: Polyethylene, PVC, PET, Aluminum End User: Pharmaceuticals, Consumer Electronics, Food Packaging, Household Goods Application: Tablet Packaging, Cosmetic Packaging, Small Device Packaging, Fast Moving Consumer Goods |
| Companies Covered | Aikpak Plastic Forming, Rohrer Corporation, Ecobliss Holding BV, Tekni-Plex, National Plastics Inc., Display Pack Inc., KPAK, VisiPak, Blisterpak Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sliding Blister Packaging Market Evolving Landscape
Material science and regulatory alignment are compressing format diversity into fewer substrate families, while automation investments reshape converter economics across high-volume pharmaceutical corridors.
Mono-material PET structures are consolidating multi-layer PVC/PVDC laminates in European pharmaceutical applications. Thermoformers in Germany and Switzerland now run 0.020-inch APET sheet with integrated desiccant coatings, eliminating separate foil lidding for moisture protection. This substrate convergence is consolidating tooling inventories and reducing changeover downtime for contract packagers serving pan-European distribution networks.
REACH authorization requirements for phthalate plasticizers are compelling PVC converters to certify citrate-based alternatives through ECHA-recognized protocols. The industrial consequence is a bifurcation between legacy lines running compliant formulations and new capacity designed around PET from inception. Oral solid dose manufacturers with US-EU dual labeling needs are most affected, responding by specifying identical substrate constructions across both regulatory jurisdictions.
Pharmaceutical procurement teams are compressing vendor panels from six suppliers to two preferred partners per region. This concentration is displacing spot-market purchasing for standard blister formats and replacing it with multi-year framework agreements indexed to resin futures. The shift is most visible among North American generics manufacturers consolidating post-merger packaging spend.
Sliding Blister Packaging Market Segmentation
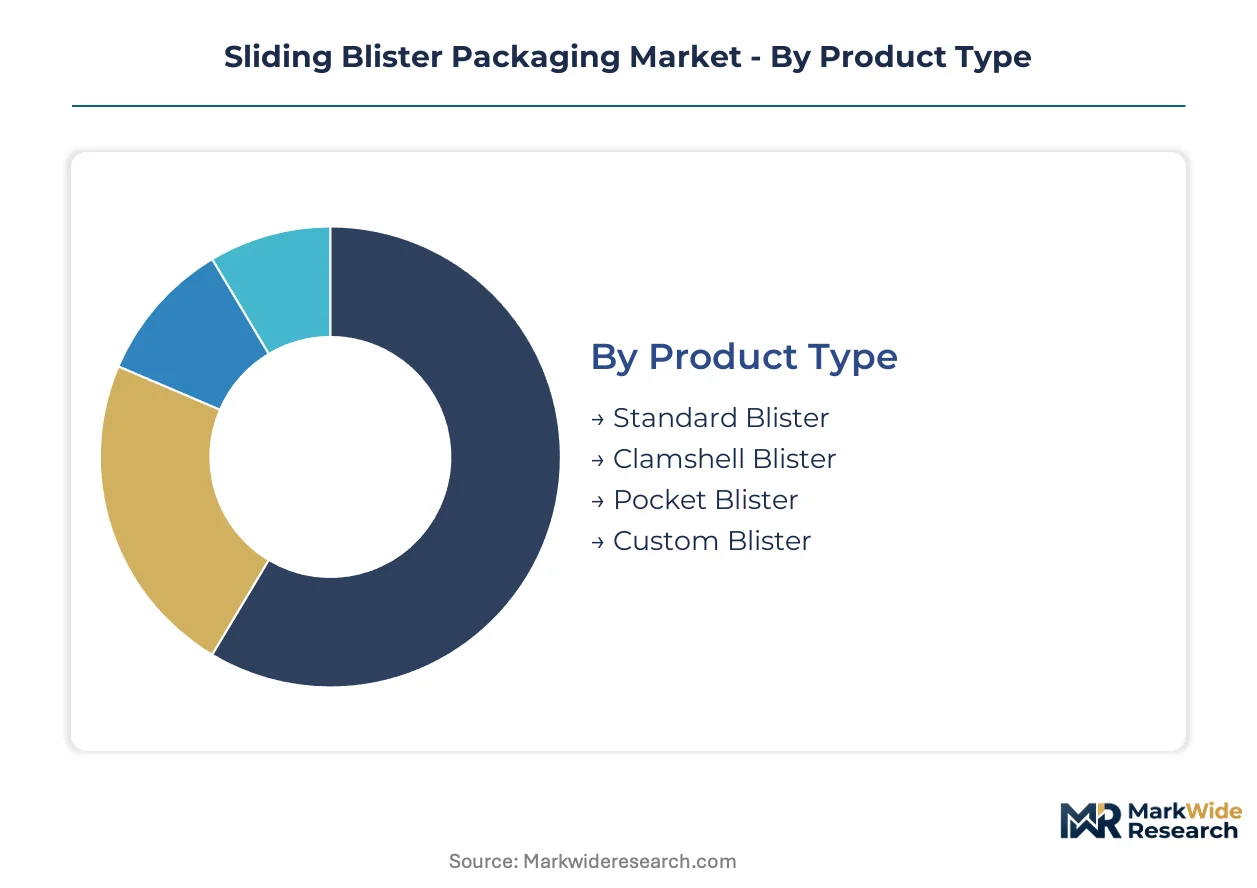
Sliding blister packaging serves divergent performance requirements across pharmaceutical integrity, retail theft deterrence, and consumer unboxing rituals. Material selection and cavity geometry determine barrier properties, while closure mechanisms balance regulatory compliance with user accessibility. Segmentation reveals where converters capture premium margins versus commodity volume.
Product Type:
Standard formats dominate high-volume pharmaceutical contracts, while specialized configurations command tooling premiums in retail differentiation plays.
- Standard Blister:Thermoformed PVC or PET cavities sealed to printed lidding card via heat-seal coating, typically 0.015-inch gauge for oral solid dose tablets. Demand concentrates among North American generics manufacturers consolidating procurement across fewer vendors, with converters absorbing six-figure tooling investments to secure multi-year framework agreements.
- Clamshell Blister:Hinged two-piece construction eliminating separate lidding material, formed via pressure thermoforming to accommodate irregular geometries without secondary sealing operations. Consumer electronics manufacturers in Shenzhen and Dongguan specify these variants for accessories and small devices, prioritizing theft deterrence and shelf visibility over pharmaceutical barrier standards.
- Pocket Blister:Multi-cavity carded formats with individual product retention pockets.
- Custom Blister:Bespoke cavity geometries and printed graphics for cosmetic and prestige retail applications.
Mature deployment sits with Standard Blister. Newer deployment is concentrated in Custom Blister.
Material:
Substrate selection tracks regulatory jurisdiction, with European converters migrating toward mono-material recoverability and US suppliers maintaining multi-layer barrier laminates.
- PET:Amorphous and crystalline grades ranging 0.010-0.030 inch gauge, increasingly specified with integrated desiccant coatings to eliminate separate foil lidding. German and Swiss thermoformers run APET sheet exclusively for EU pharmaceutical contracts, responding to Packaging and Packaging Waste Regulation recovery thresholds that penalize mechanical separation requirements.
- PVC:Legacy substrate with established thermoforming behavior and lower tooling wear, now reformulated with citrate-based plasticizers to satisfy REACH authorization constraints. Oral solid dose manufacturers with US-EU dual labeling needs specify identical PET constructions across jurisdictions, displacing PVC from new capacity investments.
- Polyethylene:Lower-cost alternative for moisture-tolerant applications and short shelf-life consumer goods.
- Aluminum:Cold-form foil laminates capturing moisture-sensitive prescriptions where thermoformed barrier performance falls short.
Volume concentration rests with PVC legacy lines. Steepest expansion trajectory belongs to mono-material PET structures.
End User:
Pharmaceutical procurement teams compress vendor panels from six suppliers to two preferred partners per region, while electronics and household goods buyers prioritize spot-market flexibility.
- Pharmaceuticals:Oral solid dose and over-the-counter medications requiring child-resistant closure compliance and moisture barrier validation. Contract packagers in Bavaria and North Rhine-Westphalia aggregate demand from Polish and Czech generics manufacturers, creating dense order clusters for regional converters with validated cleanroom thermoforming capacity.
- Consumer Electronics:Small devices, accessories, and components where clamshell configurations provide theft deterrence and retail display functionality.
- Food Packaging:Moisture-sensitive confectionery and portion-controlled products with shorter barrier requirements.
- Household Goods:Batteries, hardware, and personal care items prioritizing cost efficiency over pharmaceutical-grade validation.
Procurement consolidation is most advanced in Pharmaceuticals. Spot-market purchasing persists in Household Goods.
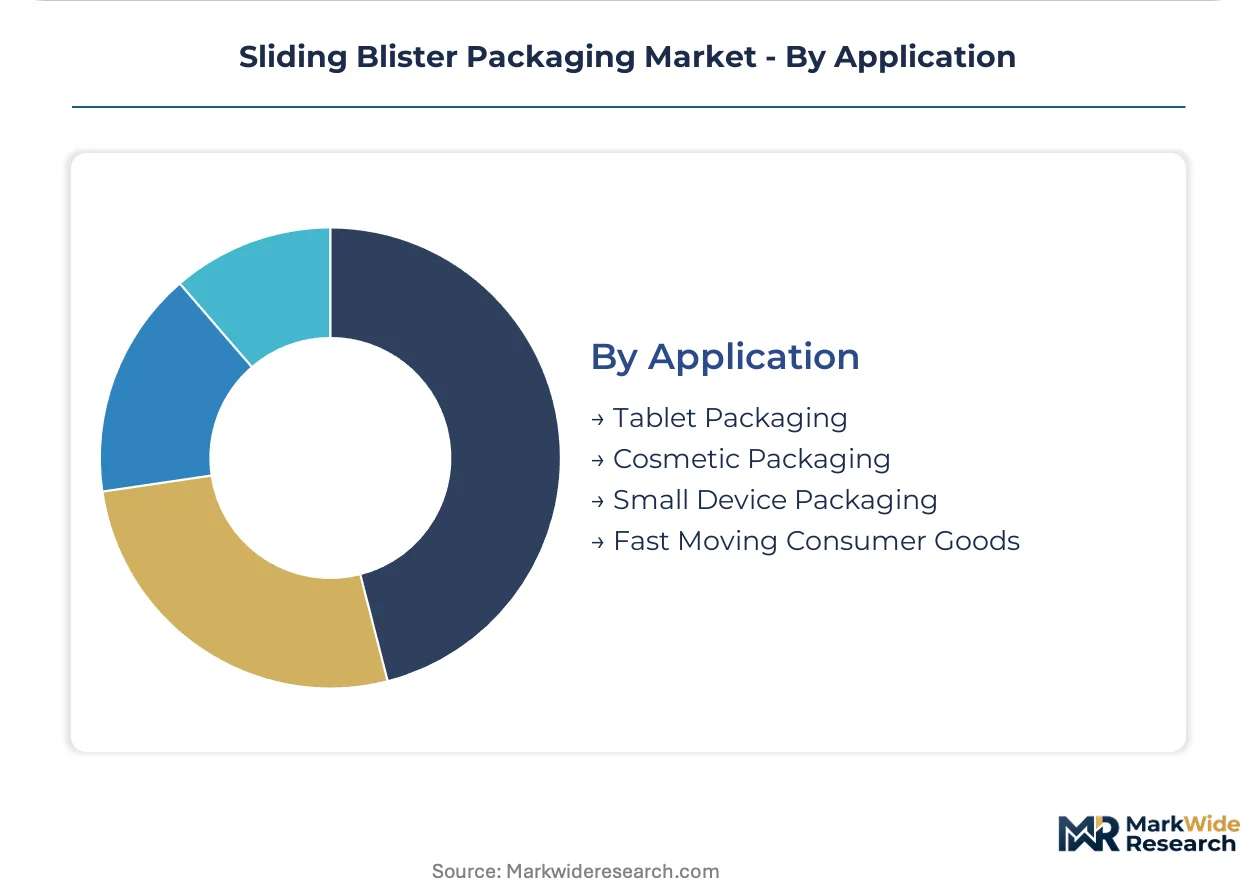
Application:
Tablet formats absorb fixed-price annual contract pressure, while cosmetic and device applications sustain premium pricing through custom tooling and shorter production runs.
- Tablet Packaging:Standard cavity configurations for pharmaceutical oral solid dose, governed by FDA 16 CFR 1700 child-resistance protocols and USP moisture permeability standards. Push-slide mechanisms with dual-action release now satisfy regulatory requirements while preserving senior-friendly access, with 90-day qualification cycles replacing historical 180-day validation timelines.
- Small Device Packaging:Serum-filled micro-needling rollers and cosmetic applicators merging pharmaceutical barrier standards with prestige retail unboxing rituals.
- Cosmetic Packaging:Premium skincare and beauty tools requiring shelf differentiation through custom graphics and cavity geometry.
- Fast Moving Consumer Goods:High-volume, low-margin applications with minimal barrier requirements and rapid inventory turnover.
Validation infrastructure concentrates in Tablet Packaging. Margin expansion is strongest in Small Device Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packagers in Germany aggregate procurement volumes across central European distribution networks, creating dense demand clusters that reshape converter economics regionally.
Germany
Bavarian and North Rhine-Westphalian contract packagers consolidate orders from Polish and Czech generics manufacturers. The EU Packaging and Packaging Waste Regulation tightens material recovery thresholds, pushing converters toward mono-material PET structures. Thermoformers in Stuttgart and Munich run validated cleanroom capacity serving pan-European pharmaceutical distribution.
United States
North American generics manufacturers compress vendor panels from six suppliers to two preferred partners post-merger. FDA 16 CFR 1700 protocols govern child-resistant closure design for over-the-counter medications. Regional converters in New Jersey and Pennsylvania absorb six-figure tooling investments to secure multi-year framework agreements.
Switzerland
Swiss thermoformers supply high-barrier pharmaceutical packaging to EU and US dual-labeling manufacturers. Swissmedic validation requirements align with EMA standards for oral solid dose applications. Basel-area converters specialize in integrated desiccant coatings that eliminate separate foil lidding.
India
Domestic thermoformers remain undersupplied for CDSCO-aligned child-resistant formats bound for US generics markets. Pharmaceutical exporters in Gujarat and Maharashtra seek validated packaging partners for FDA-submission batches. Mumbai and Ahmedabad clusters concentrate contract packaging capacity serving export-oriented formulations.
China
Shenzhen and Dongguan electronics manufacturers specify clamshell configurations for consumer accessories prioritizing retail theft deterrence. NMPA-aligned pharmaceutical packaging capacity lags behind device-sector thermoforming scale. Pearl River Delta converters serve global OEMs with pressure-formed irregular geometries.
Sliding Blister Packaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized barrier applications and mono-material recoverability. The vendor base stratifies across integrated converters with captive thermoforming capacity and specialized closure-technology developers. Three archetypes dominate: full-service contract packagers, child-resistant mechanism specialists, and material-science-forward film suppliers. Competitive moves concentrate on multi-year framework agreements indexed to resin futures and accelerated validation timelines compressing 180-day qualification cycles to 90 days.
Among North American integrated producers, Rohrer Corporation exemplifies the full-service archetype with in-house thermoforming and printing capabilities. Ecobliss Holding BV anchors the European specialist tier through Netherlands-based closure-technology development. Tekni-Plex occupies the material-science position, extending multi-layer barrier expertise into moisture-sensitive pharmaceutical applications. These three represent distinct competitive vectors: geographic coverage, regulatory specialization, and substrate innovation.
| Leading Market Players |
|---|
| Aikpak Plastic Forming |
| Rohrer Corporation |
| Ecobliss Holding BV |
| Tekni-Plex |
| National Plastics Inc. |
| Display Pack Inc. |
| KPAK |
| VisiPak |
| Blisterpak Inc. |
| Others |
Value Network & Pricing Analysis
Ethylene feedstock pricing from Gulf Coast crackers cascades through PET and PVC resin markets, compressing converter margins on fixed-price annual contracts and forcing tiered pricing stratification across premium validated capacity, standard thermoforming lines, and economy spot-market supply.
Pricing Analysis
Volume-margins split sharply between commodity tablet formats and specialized barrier applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and cleanroom validation status. Pricing pressure stems from resin cost volatility tracking naphtha and ethylene swings. North American generics manufacturers exhibit highest price sensitivity, while Swiss dual-labeling buyers prioritize barrier performance over unit cost.
Supply Chain Analysis
Skilled thermoforming technician availability constrains capacity expansion in Stuttgart, Munich, and Basel manufacturing corridors. Raw material supply draws from Saudi ethylene crackers, German PET resin producers, and Chinese specialty film coaters. Single-source vulnerability sits with precision mold fabrication concentrated in Bavarian tool-and-die shops. Distribution runs through pharmaceutical contract packagers aggregating central European demand before final conversion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sliding blister packaging is consolidating into a two-tier vendor structure as pharmaceutical procurement compression eliminates mid-sized converters lacking validated cleanroom capacity or child-resistant closure expertise.
For Market Incumbents: Hedge against cold-form foil substitution by deepening mono-material PET capabilities aligned with EU Packaging and Packaging Waste Regulation recovery thresholds. Secure multi-year framework agreements with resin futures indexing before spot-market volatility widens margin gaps. Prioritize backward integration into desiccant coating technologies to eliminate separate foil lidding dependencies. For New Entrants and Emerging Players: Push-slide dual-action child-resistant mechanisms offer technology-first wedge positioning in CDSCO-aligned Indian export packaging, where domestic validated capacity remains undersupplied. Target Gujarat and Maharashtra pharmaceutical clusters with FDA-submission-ready formats. Pursue partnership-led market entry alongside established contract packagers rather than greenfield thermoforming investment. For Investors and Strategic Acquirers: The window for entry favors material-science specialists with integrated barrier film expertise over pure-play thermoformers. Long-term viability centers on substrate innovation capabilities rather than molding scale. Watch for EU PPWR enforcement acceleration as inflection signal favoring mono-material recoverability investments.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material PET Transition | Eliminates mechanical separation costs under EU PPWR recovery thresholds for German pharmaceutical distribution. |
| Child-Resistant Closure Certification | FDA 16 CFR 1700 compliance opens North American over-the-counter medication procurement panels. |
| Cleanroom Capacity Expansion | Swissmedic-validated thermoforming captures EU-US dual-labeling oral solid dose contracts. |
| Desiccant Coating Integration | Basel-area specialty eliminates separate foil lidding for moisture-sensitive drug applications. |
| Indian Export Packaging Partnership | CDSCO-aligned capacity addresses undersupplied US-bound generics validation requirements. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with thermoforming plant managers, pharmaceutical procurement directors, contract packaging executives, and ECHA regulatory affairs specialists. FDA 510(k) submissions, EU Packaging and Packaging Waste Regulation impact assessments, and resin futures exchange data provided validation benchmarks. Bottom-up capacity modeling triangulated against top-down pharmaceutical packaging spend analysis.
Granularity-level modeling distinguished product type, material substrate, end-user industry, and regional regulatory cluster dimensions across the analysis window. CAGRs derived from segmented volume-demand buildups indexed to pharmaceutical tablet production forecasts and electronics accessory shipment data. Barrier performance specifications and child-resistance validation timelines informed premium-tier growth assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU PPWR enforcement acceleration or Gulf Coast cracker supply disruption scenarios. Pharmaceutical customer consolidation pace and resin price volatility represent material forecast sensitivities. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Blister Packaging
Alu Alu Cold Blister Films Market
Blister Packaging
Blister Paper Market
Blister Packaging
High Barrier Pharmaceutical Packaging Films for Blister Market
Blister Packaging
PVC Blister Packs Market
Blister Packaging
Blister Foil Market
Blister Packaging
Middle East and Africa Blister Packaging Market
Blister Packaging
Alu Alu Blister Packaging Machine Market
Blister Packaging
United States Blister Packaging Market
Blister Packaging
Pharma Blisters Packaging Market
Blister Packaging
Blister Pack Pharmaceutical Products Market
Blister Packaging
Carded Blister Packaging Market
Blister Packaging
Healthcare Blister Packaging Market
Blister Packaging
Asia Pacific Pharmaceutical Blister Packaging Market
Blister Packaging
Global Cold Form Blister Packaging Market
Blister Packaging
Welded Blisters Market
Blister Packaging
Blister Packaging Equipment Market