
 Mailer Packaging Market | 2026-2036
Mailer Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Mailer Packaging Market Intelligence
FSC Chain of Custody certification is bifurcating the competitive landscape. Smurfit Kappa leverages its European recycled paperboard network to secure large retail contracts. Mondi sustains integrated kraft paper production across Central European mills. Georgia-Pacific competes through scale advantages in corrugated mailer manufacturing.
Mailer packaging denotes lightweight, self-contained shipping enclosures engineered from paper, plastic, or composite substrates with closure mechanisms rated for single-trip distribution stress. Poly mailers incorporate linear low-density polyethylene films between 2-4 mil thickness to resist puncture during automated sortation. Kraft mailers lead in European e-commerce channels where paper-based recovery mandates tighten. Bubble mailers capture premium electronics segments despite composite recycling complexity. Self-seal closures dominate high-velocity fulfillment centers requiring sub-three-second pack cycles.
The EU Packaging and Packaging Waste Regulation and the US EPA sustainable materials management framework reshape material specifications and extended producer responsibility obligations. California's SB 54 plastic pollution reduction requirements force reformulation of poly mailer streams. Stakeholders must monitor regulatory divergence between European circularity mandates and US state-level plastic restrictions to align capital allocation with compliance trajectories.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing material transition timelines while e-commerce fulfillment automation accelerates throughput requirements. This dual squeeze forces capital reallocation toward certified substrates and high-velocity sealing systems.
Growth Catalysts
- California SB 54 mandates:Plastic pollution reduction targets are compelling poly mailer reformulation toward recyclable mono-material structures. Fulfillment operators in Los Angeles and San Francisco are accelerating supplier audits.
- Automated sortation infrastructure:Distribution centers in Germany's Ruhr corridor are specifying puncture-resistant films rated for 2-meter drops onto roller conveyors. This specification is pulling film thickness standardization.
- Kraft paper recovery mandates:French and Italian e-commerce channels face paper-based packaging minimums under national circular economy plans. Retailers are securing FSC Chain of Custody certification to maintain shelf access.
Market Restraints
- LLDPE resin volatility:Poly mailer producers face margin compression from naphtha-linked feedstock swings. European converters lack backward integration into cracker operations.
- Recycling infrastructure gaps:Bubble mailer composite layers—polyethylene film bonded to air-cell substrates—lack mechanical separation pathways. German sorting facilities reject these streams.
- REACH chemical restrictions:Slip agents and anti-static coatings in poly mailers face substance evaluation timelines. Reformulation cycles compress product development windows.
Strategic Opportunities
- Indian e-commerce expansion:Flipkart and Amazon India fulfillment networks are specifying lightweight mailers for last-mile density. Domestic converters lack scale to capture this volume.
- Reusable mailer systems:Returnable polypropylene enclosures with integrated RFID tracking are piloting in Dutch apparel subscription services. Reverse logistics integration remains unresolved.
- US Midwest distribution belt:Chicago and Columbus fulfillment hubs are consolidating supplier bases. Regional paperboard integration offers captive substrate supply.
Industry Challenges
- FSC certification backlog:Audit capacity constraints extend Chain of Custody approval timelines to 14 months. Smaller converters lose retail contract eligibility.
- High-speed sealing integration:Sub-three-second pack cycles demand hot-melt adhesive compatibility with recycled-content films. Adhesion failure rates spike during humidity swings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mailer Packaging Market |
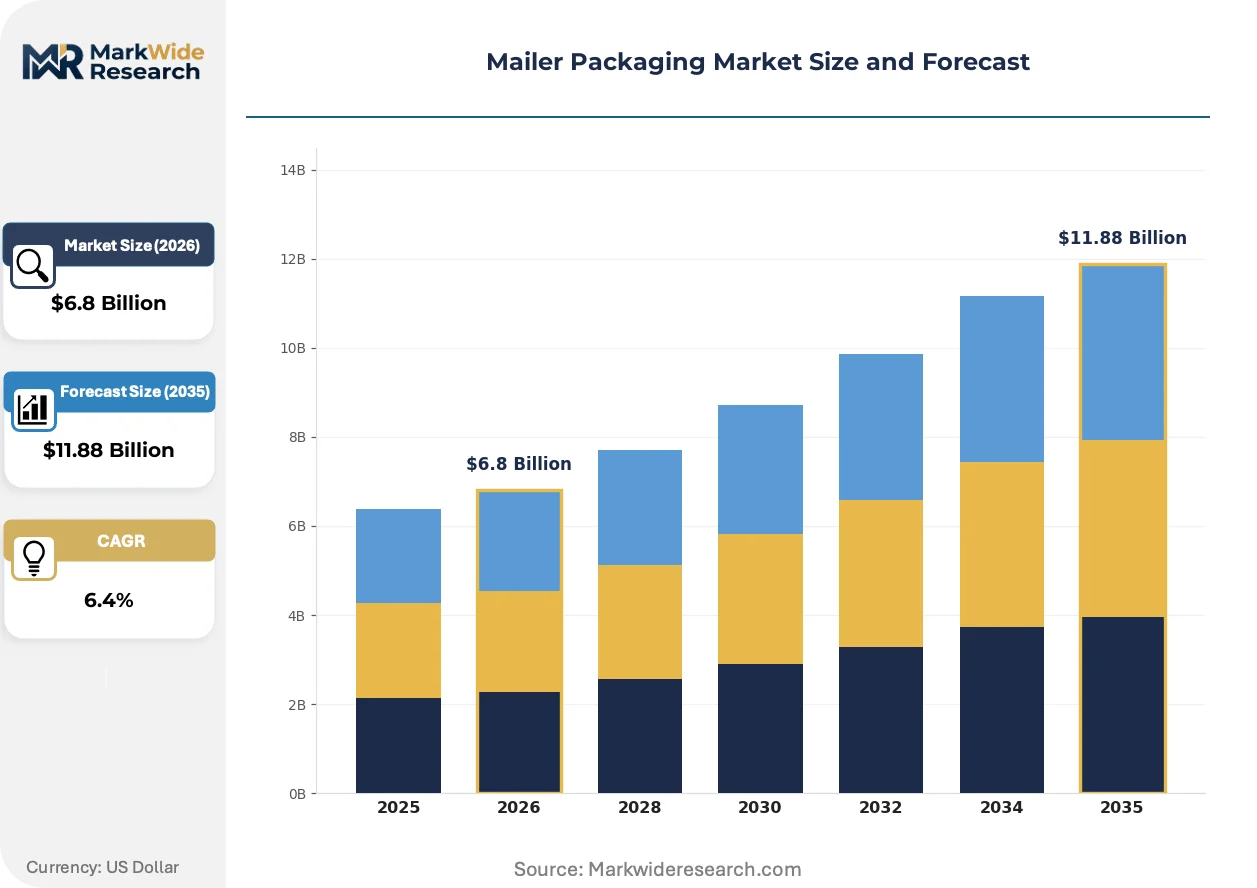
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Rigid Mailers, Poly Mailers, Bubble Mailers, Kraft Mailers Material: Plastic, Paper, Composite, Foam Closure Type: Self-Seal, Peel & Seal, Tie, Tape End User: E-commerce, Retail, Wholesale, Direct Mail |
| Companies Covered | Sealed Air Corporation, Mondi, Pregis Corporation, DS Smith, ProAmpac, Intertape Polymer Group, 3M Company, Smurfit Kappa, Georgia-Pacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mailer Packaging Market Strategic Shifts & Innovations
Material substitution and automation compatibility are compressing legacy product lifecycles. Regulatory chemistry restrictions and fulfillment velocity requirements are converging to reshape supplier qualification criteria.
Water-based barrier coatings on kraft paper are displacing polyethylene lamination in European e-commerce channels. Dutch and Belgian fulfillment operators adopted these substrates for automated packaging lines in 2023. The shift is displacing composite mailer volumes in premium apparel segments.
REACH substance evaluation is restricting per- and polyfluoroalkyl substances in grease-resistant mailer treatments. German paperboard converters are reformulating with bio-based alternatives ahead of sunset dates. Food-contact mailer segments face the steepest compliance cost escalation.
Subscription box operators are consolidating supplier bases around vertically integrated converters offering design-to-delivery programs. Direct-to-consumer brands are bypassing traditional distribution packaging distributors. This concentration is most visible in UK and German beauty and wellness verticals.
Mailer Packaging Market Segmentation
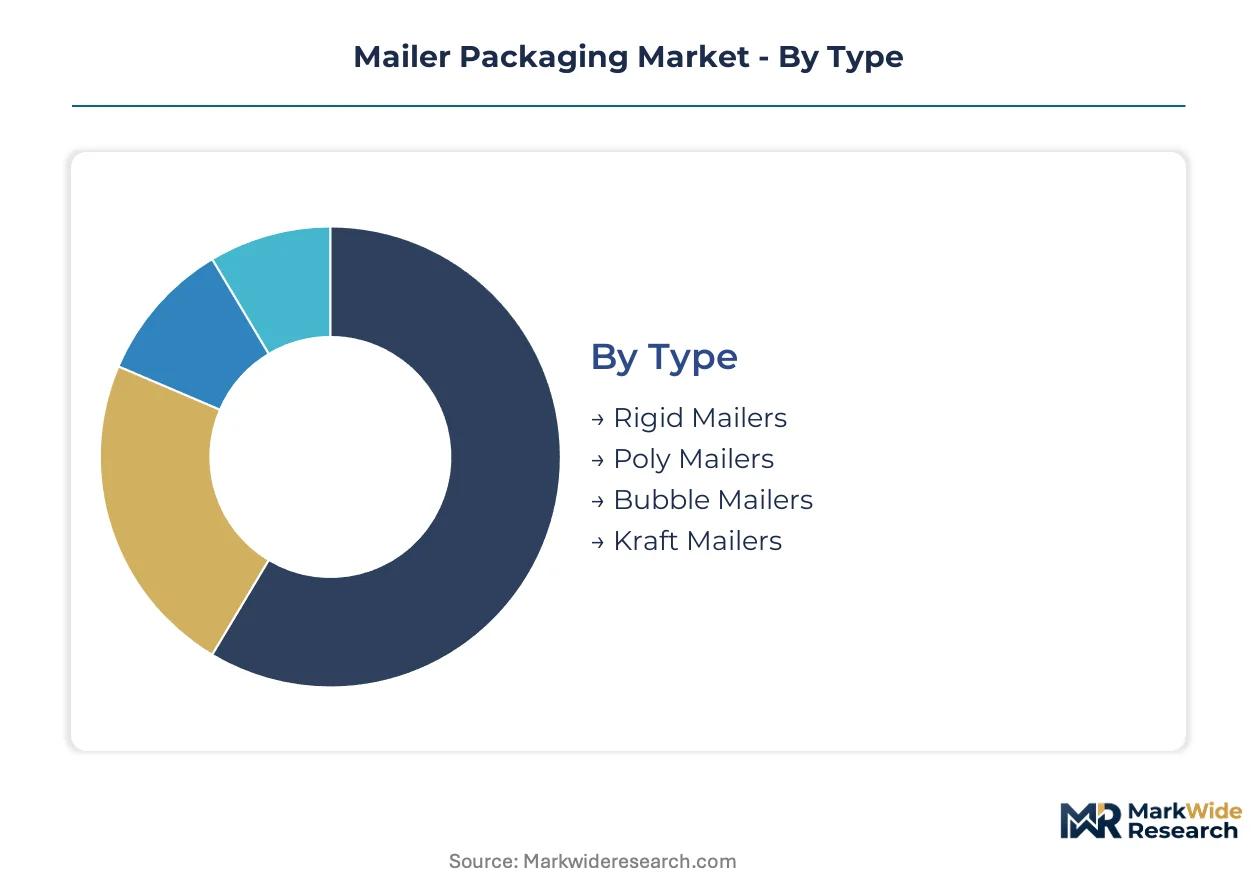
Mailer packaging segmentation reflects divergent channel economics. E-commerce fulfillment centers prioritize throughput velocity and automated compatibility. Retail and wholesale channels weight material compliance and brand presentation more heavily.
Type:
Channel mix determines type selection. Poly mailers dominate high-velocity e-commerce lines. Kraft mailers capture retail channels facing paper recovery mandates.
- Poly Mailers:Linear low-density polyethylene films between 2-4 mil thickness resist puncture during automated sortation. Demand concentrates in Los Angeles and San Francisco fulfillment hubs where California SB 54 is forcing mono-material reformulation.
- Kraft Mailers:Recycled paperboard substrates with FSC Chain of Custody certification satisfy French and Italian circular economy minimums. German e-commerce channels specify these for regulatory shelf access.
- Bubble Mailers:Composite polyethylene-air cell construction targets premium electronics segments despite German sorting facility rejection of bonded layers.
- Rigid Mailers:Corrugated paperboard shells protect documents and flat media in direct mail channels requiring edge crush resistance.
By volume, poly mailers lead. By growth pace, kraft mailers are climbing the fastest.
Material:
Cost tier stratification separates commodity substrates from certified alternatives. Paper commands premium positioning in regulated European channels. Plastic retains volume leadership through scale economies.
- Paper:Recycled kraft and paperboard grades with water-based barrier coatings displace polyethylene lamination in Dutch and Belgian automated packaging lines. FSC certification backlog extends supplier qualification timelines.
- Plastic:LLDPE and HDPE films face margin compression from naphtha-linked feedstock volatility. European converters lack cracker backward integration.
- Composite:Multi-layer polyethylene-paper constructions offer puncture resistance but face mechanical separation gaps at German recycling facilities.
- Foam:Expanded polyethylene and polyurethane inserts protect fragile goods in specialty electronics and medical device shipments.
Paper substrates gain share in premium channels. Plastic retains dominance in high-volume fulfillment.
Closure Type:
Application velocity dictates closure specification. Automated fulfillment lines demand sub-three-second sealing cycles. Manual packing stations tolerate slower adhesive systems.
- Self-Seal:Hot-melt adhesive strips enable sub-three-second pack cycles at Chicago and Columbus distribution hubs. Humidity swings challenge recycled-content film adhesion rates.
- Peel & Seal:Silicone-release liner systems suit mid-velocity retail operations requiring clean opening presentation. UK beauty subscription services specify these for unboxing experience.
- Tie:Drawstring and flap-tie closures serve reusable mailer pilots in Dutch apparel subscription networks.
- Tape:Pressure-sensitive adhesive application remains viable for low-volume wholesale and direct mail channels with manual packing labor.
Self-seal closures dominate e-commerce volume. Peel and seal formats expand in premium direct-to-consumer channels.
End User:
Customer type determines specification complexity. E-commerce operators prioritize unit economics and line speed. Retail and wholesale buyers emphasize compliance documentation and brand customization.
- E-commerce:Amazon, Flipkart, and regional marketplace fulfillment networks drive standardization around lightweight, puncture-resistant films. Indian expansion outpaces domestic converter capacity.
- Retail:Big-box and specialty store private label programs require FSC-certified paperboard with design-to-delivery program integration. UK and German beauty verticals consolidate supplier bases.
- Wholesale:Bulk distribution channels prioritize cube utilization and pallet density over individual pack presentation. Standardized poly mailer specifications reduce SKU complexity.
- Direct Mail:Marketing and publishing segments demand rigid edge protection and printable surfaces for brand messaging. Postal compatibility constraints limit dimensional variation.
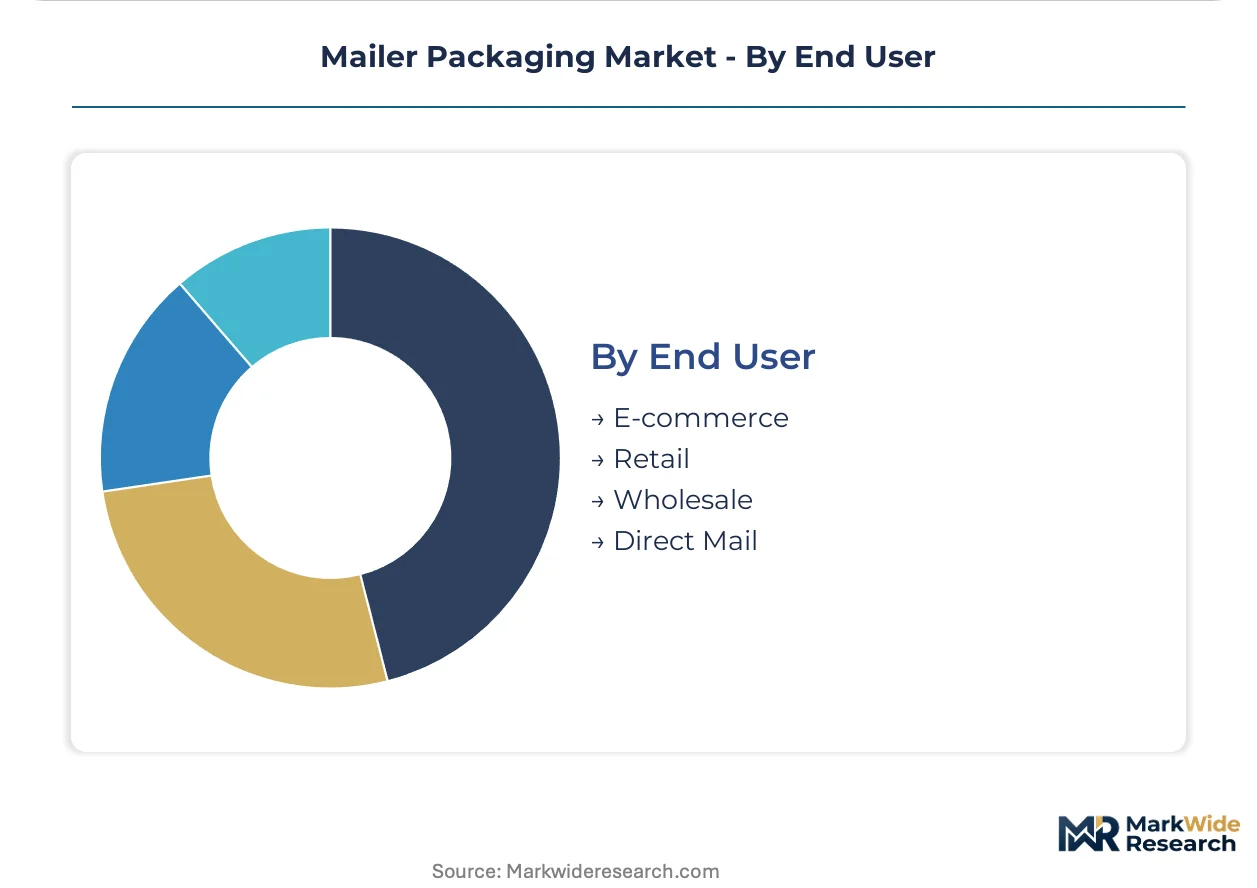
E-commerce channels absorb the highest volume. Retail channels generate the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California SB 54 mandates are accelerating material reformulation across fulfillment networks. The EU Packaging and Packaging Waste Regulation tightens compliance timelines for substrate certification. India's e-commerce expansion outpaces domestic converter capacity.
United States
Los Angeles and San Francisco fulfillment hubs drive poly mailer specification changes under California SB 54 plastic pollution reduction targets. The EPA sustainable materials management framework shapes federal procurement guidelines. Chicago and Columbus distribution belt consolidation favors regional paperboard integration.
Germany
Ruhr corridor distribution centers specify puncture-resistant films for automated sortation infrastructure. REACH chemical restrictions target slip agents in poly mailer formulations. Berlin-Brandenburg logistics networks enforce FSC Chain of Custody documentation for retail shelf access.
India
Flipkart and Amazon India fulfillment networks specify lightweight mailers for last-mile density optimization. DGFT import regulations affect substrate equipment sourcing timelines. Maharashtra and Karnataka industrial corridors lack scaled domestic converter capacity to capture e-commerce volume growth.
France
National circular economy plans impose paper-based packaging minimums on e-commerce channels. ECHA substance evaluation timelines compress reformulation windows for barrier coatings. Île-de-France logistics clusters adopt water-based kraft paper substrates ahead of recovery mandate deadlines.
Netherlands
Dutch apparel subscription services pilot reusable polypropylene mailers with integrated RFID tracking. EU Green Deal circularity targets accelerate mono-material adoption in automated packaging lines. Rotterdam and Amsterdam fulfillment hubs standardize puncture-resistant film specifications for European distribution.
Mailer Packaging Market Key Industry Players
Listed leaders compete with private specialists across substrate certification and fulfillment velocity dimensions. The vendor base stratifies between integrated paperboard producers and film converters lacking backward integration. Three archetypes dominate: FSC-certified paperboard specialists, LLDPE film scale producers, and composite mailer technology holders. Capacity expansion and strategic supplier audits constitute the dominant competitive moves as retailers consolidate approved vendor lists.
Within the integrated paperboard tier, Smurfit Kappa and Mondi occupy positions anchored to European recycled fiber networks. Sealed Air Corporation exemplifies the film-based archetype with scale advantages in automated fulfillment compatibility. Georgia-Pacific represents the North American corrugated specialization vector serving Midwest distribution belt consolidation.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Mondi |
| Pregis Corporation |
| DS Smith |
| ProAmpac |
| Intertape Polymer Group |
| 3M Company |
| Smurfit Kappa |
| Georgia-Pacific |
| Others |
Cost & Logistics Intelligence
Water-based barrier coatings displacing polyethylene lamination in European kraft mailers simultaneously redraws supply geography toward Nordic pulp networks and compresses pricing premiums for certified substrates. This substitution dynamic concentrates purchasing power among vertically integrated paperboard producers while fragmenting legacy film converter margins.
Pricing Analysis
Certification level creates the primary spread between FSC Chain of Custody kraft mailers and uncertified alternatives. Three-tier pricing structure separates premium certified grades from standard recycled-content products and economy virgin-polymer mailers. Cost compression in poly mailer tiers is intensifying because LLDPE resin volatility lacks backward integration hedges. Wholesale distributors exhibit highest price sensitivity; beauty subscription services show lowest.
Supply Chain Analysis
Inventory cycles for FSC-certified paperboard extend lead times to fourteen months as audit capacity constrains supplier qualification. Raw material flows draw from Swedish and Finnish pulp networks, German recycled fiber mills, and US Gulf Coast petrochemical corridors. Single-source vulnerability concentrates in European cracker-dependent LLDPE supply. Distribution runs through consolidated fulfillment hubs in Chicago, Columbus, and Germany's Ruhr corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs mailer packaging procurement as Amazon, Flipkart, and subscription box operators consolidate approved vendor lists around design-to-delivery integrators. Interoperability between automated sealing systems and certified substrate specifications is reshaping supplier qualification thresholds.
For Market Incumbents: Fortify FSC certification coverage across European mill networks before audit backlog extends retail contract eligibility windows. Prioritize hot-melt adhesive compatibility R&D for recycled-content films to defend high-velocity fulfillment share against composite mailer specialists. Channel control through captive design-to-delivery programs represents the critical defensive lever against direct-to-consumer brand bypass. For New Entrants and Emerging Players: Last-mile density optimization services for Indian e-commerce fulfillment networks sit underserved as domestic converter capacity lags Flipkart and Amazon India specifications. Reusable mailer reverse logistics integration in Dutch apparel subscriptions offers penetrable white-space before RFID tracking standardizes. A design-to-delivery partnership model with UK beauty verticals provides the optimal go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European paperboard converters holding FSC certification but lacking automated fulfillment compatibility. Five-to-ten year viability hinges on capital deployment toward high-velocity sealing system integration rather than capacity expansion alone. Monitor California SB 54 enforcement velocity as the inflection signal for mono-material mailer valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain of Custody Certification | Retail shelf access in France and Germany now requires documented fiber provenance. |
| Backward Integration into Pulp Supply | Nordic pulp network control insulates margin from recycled fiber price spikes. |
| Automated Sealing System Integration | Sub-three-second pack cycle compatibility qualifies suppliers for Chicago hub consolidation. |
| Mono-Material Film Reformulation | California SB 54 compliance enables continued access to Los Angeles fulfillment volume. |
| Design-to-Delivery Program Launch | Direct-to-consumer brand bypass of traditional distributors demands integrated creative services. |
Research Approach
Initial hypotheses were tested against primary input from packaging procurement managers at e-commerce fulfillment operators, sustainability directors at retail private label programs, and technical directors at paperboard and film converters, then refined through secondary validation. SEC filings of listed packaging producers, EU ECHA substance evaluation databases, California SB 54 regulatory comment filings, and customs trade data for LLDPE resin and kraft paperboard flows provided triangulation anchors. Bottom-up volume modeling across substrate types and top-down value reconciliation ensured analytical consistency.
Variance decomposition across material type, closure mechanism, end-use channel, and regional regulatory cluster shaped the projection framework. CAGRs were derived from segmented volume build-ups calibrated to e-commerce fulfillment automation deployment curves and circular economy mandate implementation timelines. Feedstock price sensitivity bands and certification adoption S-curves informed scenario boundaries throughout the modeling period.
Forecasts assume regulatory continuity in EU Packaging and Packaging Waste Regulation implementation and California SB 54 enforcement trajectories; material policy shifts would require re-modeling. LLDPE resin volatility, FSC audit capacity constraints, and REACH substance evaluation timelines constitute specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Composite Packaging Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Sun Control Films Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Corrugated Wraps Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Water Soluble Pods Packaging Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Tertiary Packaging Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Polycoated Cup Stock Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Thermoformed Trays Market