
 Canada Plastic Bottles Market | 2026-2036
Canada Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Plastic Bottles Market Insights
A capital-intensity divergence between blow-molding equipment scale and recycled-content processing capability is redrawing competitive tiers. Silgan Holdings Inc leverages its multi-plant North American footprint to sustain resin hedging advantages across Ontario and Quebec operations. Amcor Group GmbH anchors its position through rPET flake-to-preform integration, while Berry Global Inc differentiates via pharmaceutical-grade barrier bottle specialization serving Health Canada-regulated drug packaging.
Canada plastic bottles are hollow thermoplastic containers manufactured through extrusion blow molding, injection blow molding, or stretch blow molding processes, typically formed from PET, HDPE, LDPE, or PVC resins with wall thicknesses calibrated for internal pressure, chemical compatibility, or barrier requirements; they function as primary packaging for liquid, semi-solid, and granular products across consumer and industrial supply chains. PET dominates beverage applications due to clarity and carbonation retention, while HDPE occupies the dairy and household cleaning segments where chemical resistance and post-consumer recyclability matter most. Closure type selection—screw cap versus pump dispenser—tracks directly to end-use viscosity and dispensing precision requirements, with pharmaceutical and personal care applications driving premium closure attachment investments.
Health Canada sets food-contact material safety standards through the Food and Drugs Act and associated Division 23 packaging regulations, while the Canadian Environmental Protection Act governs plastic polymer manufacturing emissions and end-of-life disposal protocols; provincial extended producer responsibility programs in British Columbia, Ontario, and Quebec mandate minimum recycled content thresholds that reshape converter sourcing strategies. The Competition Bureau's greenwashing enforcement against unsubstantiated recyclability claims adds compliance cost layers for brand owners specifying bottle substrates. Stakeholders must monitor whether federal single-use plastics prohibition expansion captures certain bottle formats and how provincial deposit-return system harmonization alters post-consumer collection economics for rPET feedstock security.
Market Dynamics
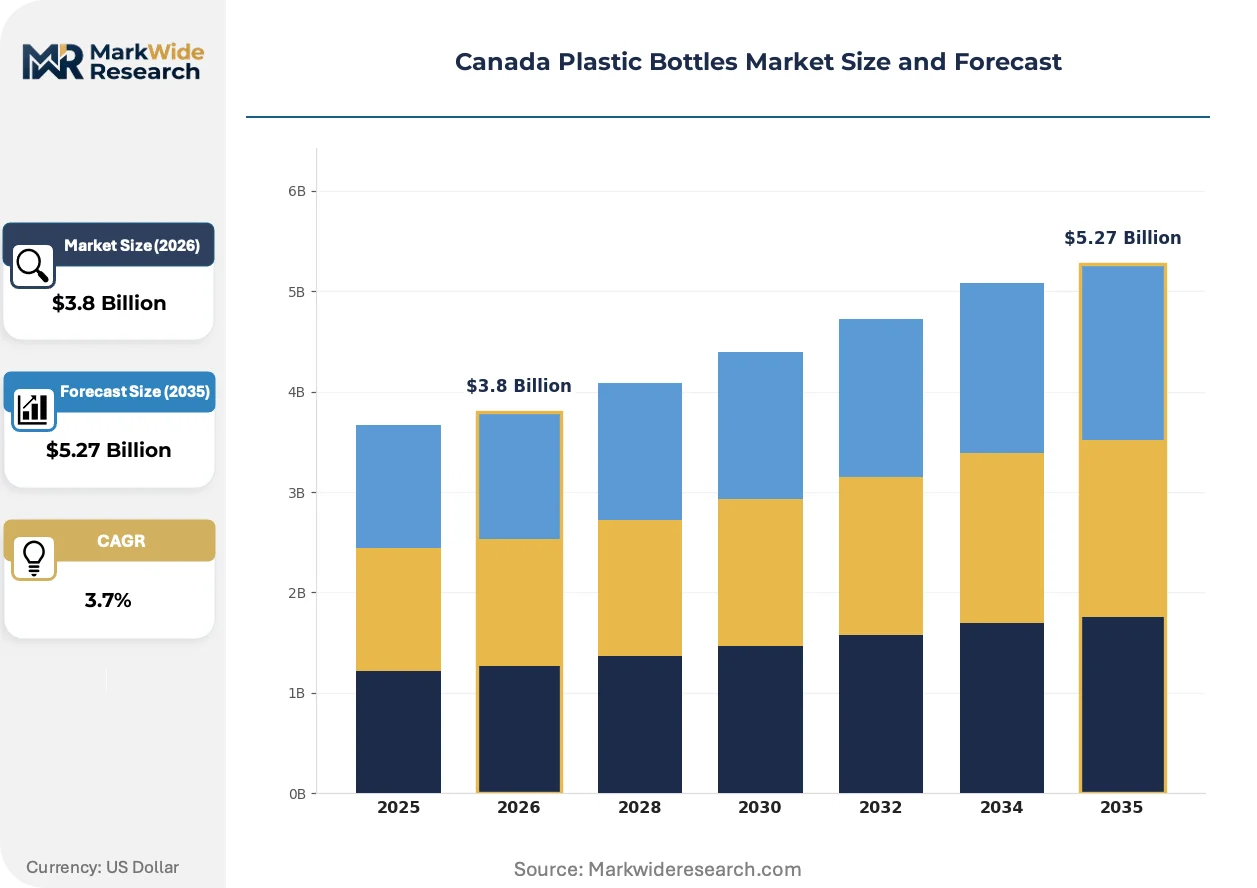
Health Canada's tightening recycled content mandates are forcing converters to reconfigure resin sourcing and blow-molding asset footprints, creating a capital barrier between certified food-grade rPET suppliers and commodity-grade competitors.
Growth Catalysts
- Ontario-Quebec beverage cluster expansion:PET procurement volumes from refillable and single-serve bottlers in Toronto and Montreal are pulling through preform capacity investments.
- Extended Producer Responsibility mandates:British Columbia, Ontario, and Quebec programs are mandating minimum post-consumer recycled thresholds that secure rPET feedstock demand.
- Dairy processing infrastructure:HDPE jug formats are gaining pull-through from Greater Toronto Area co-packing logistics and fluid milk distribution networks.
Market Restraints
- Resin price volatility:Virgin PET and HDPE feedstock costs track crude oil and natural gas liquid indices, compressing converter margins during upstream spikes.
- rPET supply concentration:Food-grade flake availability concentrates in Ontario and British Columbia collection zones, creating geographic feedstock insecurity for Quebec converters.
- Technical limitation:Multiple reheat-stretch-blow cycles degrade PET molecular weight, limiting refillable bottle loop counts before mechanical recycling.
Strategic Opportunities
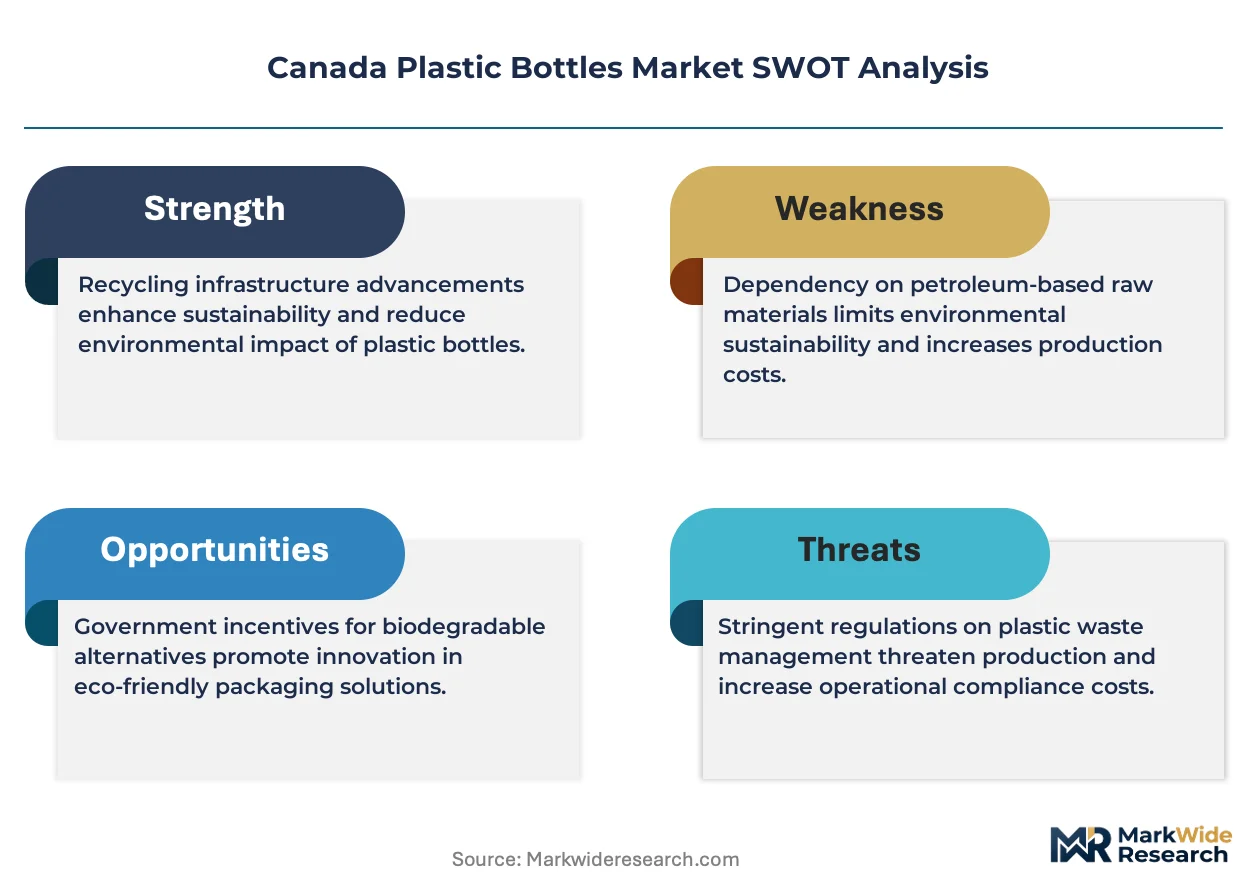
- Pharmaceutical barrier specialization:Health Canada Division 23 drug packaging regulations are creating premium niches for multilayer HDPE and fluorinated PET bottles.
- Deposit-return system harmonization:Provincial program alignment could unlock economies of scale in post-consumer collection and sorting infrastructure.
- Personal care pump dispenser conversion:Viscous product formats in Toronto and Vancouver manufacturing clusters are shifting from jars to bottles with precision closure systems.
Industry Challenges
- Food-grade rPET certification timelines:Health Canada Letters of No Objection for recycled content in beverage contact applications require 18-24 month validation cycles.
- Blow-molding asset reconfiguration:Legacy extrusion equipment in Quebec and Ontario plants cannot process high-contamination rPET flake without screw and die modifications.
- Greenwashing enforcement exposure:Competition Bureau substantiation requirements for recyclability claims are forcing label redesign and legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Plastic Bottles Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC Closure Type: Screw Cap, Snap-on Cap, Cork, Pump Dispenser End Use: Food & Beverage, Personal Care, Household Cleaning, Pharmaceutical Packaging Size: Small (Under 500ml), Medium (500ml-1L), Large (1L-5L), Bulk (Over 5L) |
| Companies Covered | Silgan Holdings Inc, Amcor Group GmbH, Berry Global Inc, Container Corporation of Canada, TricorBraun Canada, Bramalea Bottle Inc, CoastPak Industrial Co, Berlin Packaging, International Bottle Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Plastic Bottles Market Trends and Innovations
Active pharmaceutical and dairy packaging specifications are pulling through material and process innovations that redefine barrier performance and circularity credentials in Canadian converter operations.
Chemical recycling via pyrolysis and glycolysis is decomposing contaminated PET waste streams into virgin-quality monomers, enabling beverage bottlers in Ontario to meet Health Canada food-contact purity standards without sourcing constraints. Toronto-area converters are piloting these units at commercial scale. The technology is decomposing the historical trade-off between recycled content targets and optical clarity requirements.
Health Canada's Division 23 packaging material safety standards under the Food and Drugs Act are tightening extractables testing protocols for pharmaceutical and natural health product containers. Converters serving drug packaging must now validate barrier layer adhesion and leachate profiles against updated guidance documents. The regulatory revision most affects Montreal and Toronto sterile manufacturing corridors, where contract packers are demanding certificate-of-analysis documentation for every resin lot.
Brand-owner sustainability scorecards are compressing supplier qualification cycles from annual reviews to quarterly audits, with rPET content percentage and carbon footprint metrics now weighted above unit price in Ontario beverage procurement. Direct converter relationships are displacing distributor intermediaries for volume commitments above 10 million units annually. This pattern concentrates in Greater Toronto Area dairy and soft drink bottling, where co-manufacturing agreements tie packaging supply to processing slot allocations.
Canada Plastic Bottles Market Segmentation
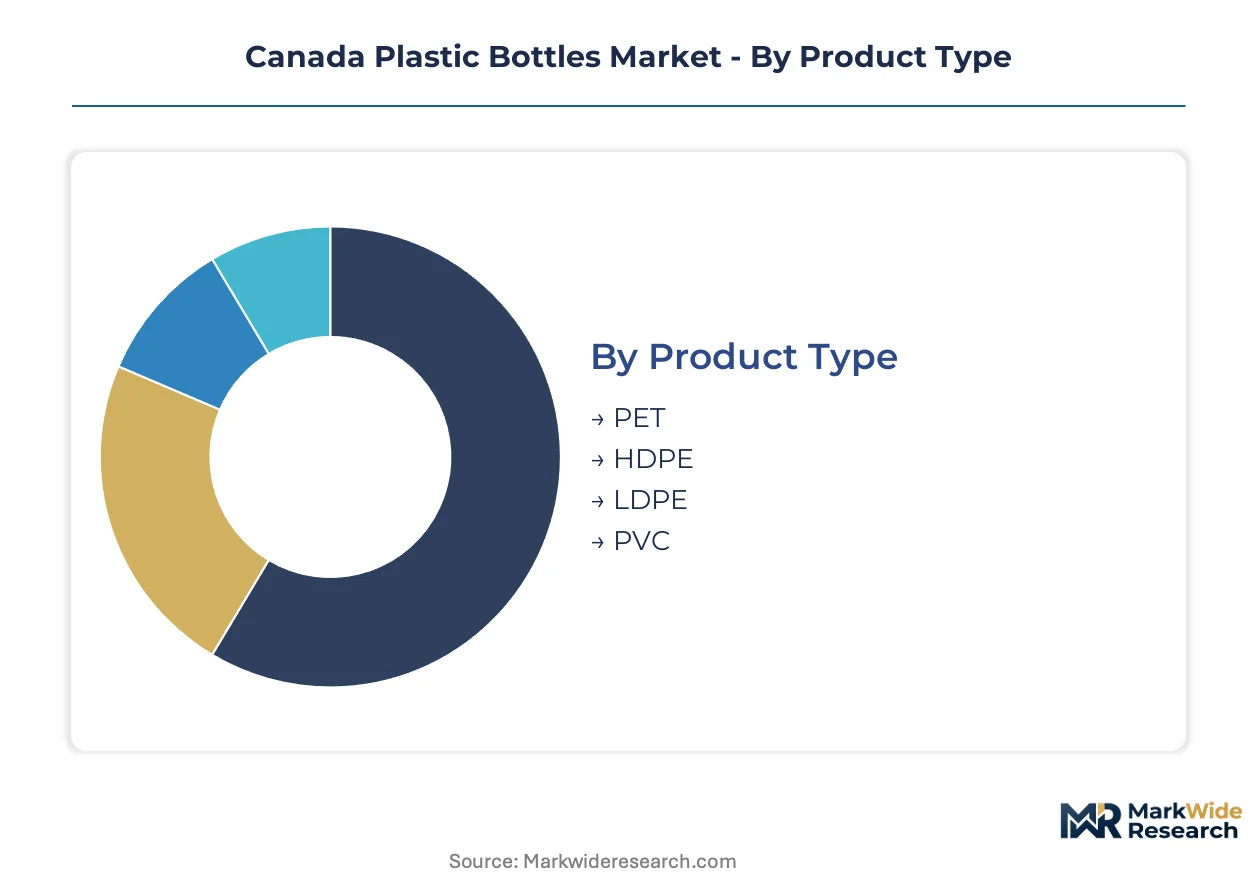
Segmentation in the Canada plastic bottles market reveals how resin chemistry, closure mechanics, and end-use specifications create distinct procurement channels. Ontario and Quebec converters configure blow-molding assets around these divides, with Health Canada regulations further stratifying food-contact from pharmaceutical-grade supply chains.
Product Type:
Domestic demand concentrates in PET and HDPE for beverage and dairy applications, while PVC and LDPE serve specialized export-oriented niches.
- PET:Polyethylene terephthalate delivers clarity and carbonation retention for refillable and single-serve beverage formats. Toronto and Montreal bottlers are expanding procurement volumes to meet deposit-return system requirements in Ontario and Quebec.
- HDPE:High-density polyethylene offers chemical resistance and post-consumer recyclability for fluid milk distribution. Greater Toronto Area dairy processors favor HDPE jug formats for co-packing logistics efficiency and existing recycling infrastructure compatibility.
- LDPE:Low-density polyethylene serves squeeze bottles and flexible dispensing applications in personal care manufacturing clusters around Vancouver and Toronto.
- PVC:Polyvinyl chloride occupies shrinking pharmaceutical and chemical-resistant niches as Health Canada scrutiny tightens on plasticizer migration risks.
PET holds the largest share; momentum sits with HDPE as dairy processors accelerate refillable jug format conversions.
Closure Type:
Cost tiers separate precision-engineered pump dispensers from commodity screw caps, with pharmaceutical and personal care applications commanding premium attachment investments.
- Screw Cap:The standard threaded closure dominates beverage and household cleaning segments for resealability and tamper-evidence. Ontario soft drink bottlers specify 28mm PCO finishes for carbonated PET bottles under deposit-return program requirements.
- Pump Dispenser:Precision-engineered dispensing systems serve viscous personal care products in Toronto and Vancouver manufacturing corridors. Brand owners are converting from jars to bottles with metered pump systems for hygiene and dosing accuracy.
- Snap-on Cap:Press-fit closures occupy water and non-carbonated beverage segments where thread engagement adds unnecessary cost.
- Cork:Synthetic and natural cork finishes persist in wine and premium spirits packaging from British Columbia and Ontario vineyard bottling operations.
Screw cap configurations command volume leadership; pump dispenser specifications are climbing the fastest as personal care brands upgrade packaging formats.
End Use:
Application requirements dictate barrier specifications, with Health Canada Division 23 standards creating the steepest compliance gradients in pharmaceutical packaging.
- Food & Beverage:The dominant consumption channel spans carbonated soft drinks, bottled water, dairy, and edible oils. Deposit-return systems in British Columbia, Ontario, and Quebec secure rPET feedstock demand for bottle-to-bottle recycling loops.
- Pharmaceutical:Drug packaging and natural health products demand multilayer HDPE and fluorinated PET for moisture and oxygen barrier performance. Montreal and Toronto sterile manufacturing corridors require certificate-of-analysis documentation for every resin lot under updated extractables protocols.
- Personal Care:Shampoo, lotion, and cosmetic bottles drive premium closure attachment investments and decorative labeling specifications.
- Household Cleaning:Bleach, detergent, and solvent containers prioritize chemical resistance and child-resistant closure compatibility.
Food and beverage applications retain dominant volume; pharmaceutical specifications are gaining share fastest on regulatory barrier upgrades.
Packaging Size:
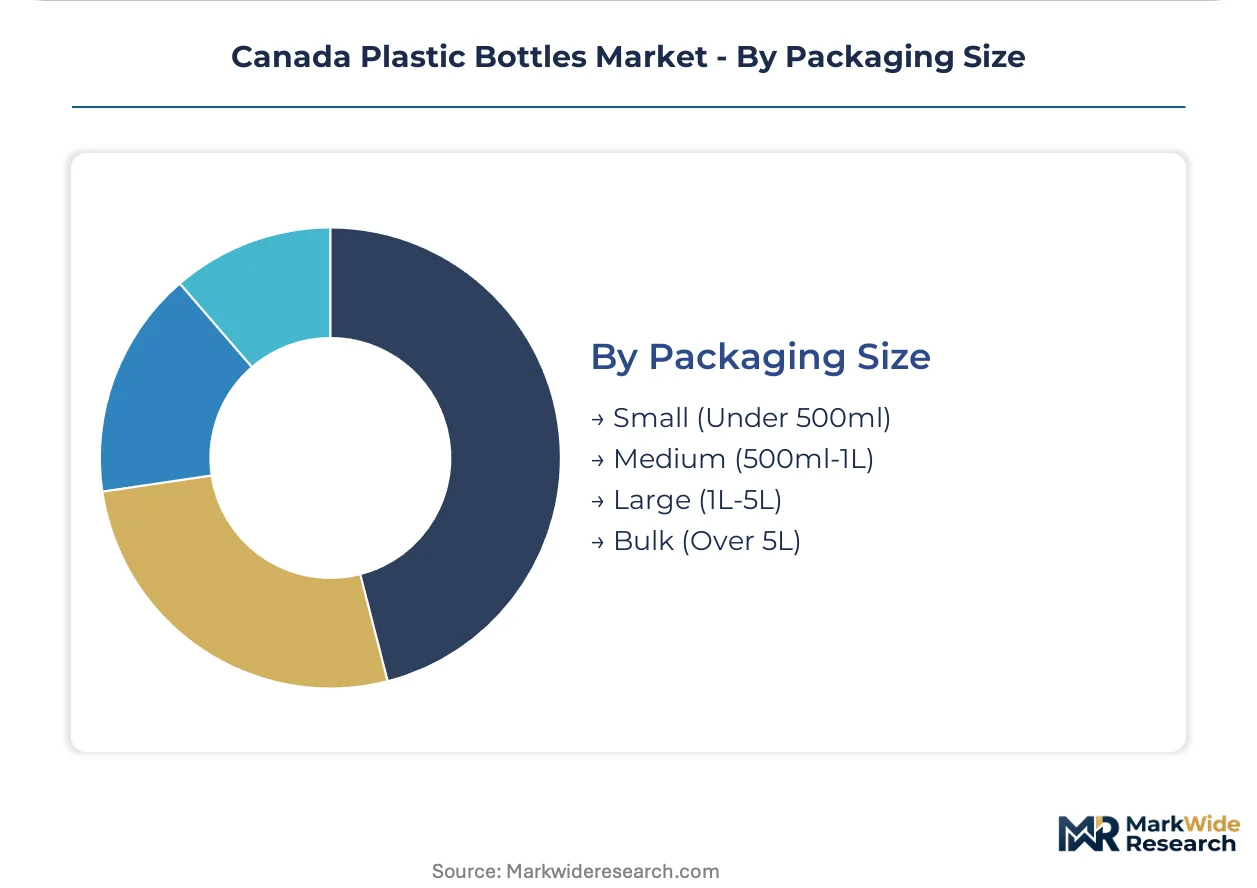
Volume concentration in medium formats reflects single-serve consumption patterns, while bulk sizes track institutional and e-commerce channel expansion.
- Medium (500ml-1L):The standard single-serve beverage format aligns with convenience store and vending channel specifications. Ontario and Quebec bottlers configure stretch blow-molding lines around 591ml and 1L finish standards for maximum asset utilization.
- Large (1L-5L):Family-size and on-premise formats serve food service and club retail channels. HDPE milk jugs at 2L and 4L volumes dominate Greater Toronto Area dairy distribution networks.
- Small (Under 500ml):Miniature formats address travel retail, sample distribution, and premium positioning in personal care.
- Bulk (Over 5L):Institutional and industrial containers serve cleaning chemical concentrates and food service oil dispensing with integrated handle and spout designs.
Medium formats hold the largest share; bulk specifications show the steepest expansion trajectory as commercial channel procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Canadian provinces. Ontario and Quebec buyers absorb premium pricing for certified food-grade rPET, while Atlantic Canada processors remain highly price-sensitive to virgin resin fluctuations.
Ontario
Toronto's packaging cluster drives PET preform demand from refillable beverage bottlers and dairy processors. Health Canada's Letters of No Objection for recycled content force 18-24 month certification timelines on converters. The Greater Toronto Area's co-packing logistics infrastructure pulls through HDPE jug formats for fluid milk distribution networks.
Quebec
Montreal beverage bottlers expand single-serve PET procurement to meet deposit-return system requirements. The province's extended producer responsibility program mandates minimum post-consumer recycled thresholds that reshape converter sourcing. Laval and Longueuil manufacturing corridors face geographic rPET feedstock insecurity relative to Ontario and British Columbia collection zones.
British Columbia
Vancouver's personal care manufacturing cluster shifts from jars to pump dispenser bottles for viscous product formats. The provincial deposit-return system secures rPET feedstock demand for bottle-to-bottle recycling loops. Richmond and Burnaby sorting facilities concentrate food-grade flake availability that Quebec converters lack.
Alberta
Calgary and Edmonton chemical processing plants supply virgin HDPE resin to Prairie dairy bottlers. The province's natural gas liquid feedstock costs track crude oil indices, compressing converter margins during upstream spikes. Local blow-molding operations serve agricultural chemical and institutional cleaning concentrate markets with bulk format specialization.
Canada Plastic Bottles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Canadian plastic bottles market. The vendor base consolidates around three tiers: integrated multinationals with resin hedging capabilities, regional converters with rPET certification investments, and specialized barrier bottle fabricators. Strategic moves concentrate on blow-molding asset reconfiguration for high-contamination flake processing and pharmaceutical-grade barrier layer validation.
Within the integrated multinational tier, Silgan Holdings Inc and Amcor Group GmbH exemplify divergent approaches to North American footprint leverage. Silgan's multi-plant presence sustains resin hedging advantages across Ontario and Quebec operations. Amcor anchors its position through rPET flake-to-preform integration investments. Berry Global Inc occupies the specialized fabrication vector, differentiating via pharmaceutical-grade barrier bottle production serving Health Canada Division 23 drug packaging regulations.
| Leading Market Players |
|---|
| Silgan Holdings Inc |
| Amcor Group GmbH |
| Berry Global Inc |
| Container Corporation of Canada |
| TricorBraun Canada |
| Bramalea Bottle Inc |
| CoastPak Industrial Co |
| Berlin Packaging |
| International Bottle Corp |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month certification timelines for Health Canada Letters of No Objection concentrate pricing power with Ontario and British Columbia converters holding validated food-grade rPET capacity, while Quebec processors absorb geographic feedstock premiums that compress margins against virgin resin spot benchmarks.
Pricing Analysis
After-sales revenue from technical service contracts and blow-molding equipment maintenance drives lifetime value for converter OEMs serving Canadian bottlers. Three-tier pricing structure across pharmaceutical-grade barrier, food-contact certified, and commodity-grade standard levels tracks Health Canada Division 23 compliance tiers and rPET content percentages. Pricing pressure stems from virgin PET and HDPE feedstock costs tracking crude oil and natural gas liquid indices, compressing converter margins during upstream spikes. Dairy processors in the Greater Toronto Area exhibit highest price sensitivity due to fluid milk's thin margin structure, while pharmaceutical contract packers in Montreal and Toronto corridors accept premium pricing for extractables-tested resin lots.
Supply Chain Analysis
The United States and Alberta supply virgin HDPE resin to Prairie dairy bottlers, while Ontario and British Columbia concentrate food-grade rPET flake availability that Quebec converters lack. Raw material dependencies rest on virgin PET pellets from Gulf Coast petrochemical complexes, natural gas liquid feedstocks from Alberta gas processing plants, and post-consumer baled bottles from provincial deposit-return collection systems. Single-source vulnerability concentrates in Ontario's preform molding capacity serving Quebec beverage bottlers, exposing converters to interprovincial logistics disruptions. Distribution runs through co-packing logistics hubs in the Greater Toronto Area, where dairy processors and soft drink bottlers consolidate packaging procurement with processing slot allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada plastic bottles market operates as a regulatory-moat story where Health Canada's 18-24 month food-grade rPET certification timelines create switching costs that entrench validated converters against commodity-grade competitors.
For Market Incumbents: Shield market position by accelerating in-house production of rPET flake-to-preform capacity in Ontario and British Columbia collection zones, eliminating geographic feedstock insecurity that exposes Quebec operations to margin compression. Deepen upstream control over blow-molding asset reconfiguration for high-contamination flake processing before legacy extrusion equipment obsolescence threatens volume commitments from Toronto beverage bottlers. For New Entrants and Emerging Players: Anchor in pharmaceutical barrier specialization serving Health Canada Division 23 drug packaging regulations, where Montreal and Toronto sterile manufacturing corridors demand certificate-of-analysis documentation that incumbent commodity converters struggle to provision. Target personal care pump dispenser conversion opportunities in Vancouver and Toronto manufacturing clusters, where viscous product brands shift from jars to precision closure systems and procurement patterns remain unsettled. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with underutilized Canadian blow-molding assets lacking rPET certification investments. Long-term viability hinges on feedstock security rather than unit cost position, favoring converters with validated collection zone relationships over virgin resin hedging capabilities. Watch for provincial deposit-return system harmonization announcements as the inflection signal that would unlock economies of scale in post-consumer sorting infrastructure and reshape competitive tiers.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Flake-to-Preform Integration | Health Canada certification timelines favor converters with captive food-grade recycling capacity in Ontario and British Columbia. |
| Pharmaceutical Barrier Specialization | Division 23 extractables protocols create premium niches for multilayer HDPE and fluorinated PET in Montreal-Toronto corridors. |
| Blow-Molding Asset Reconfiguration | Legacy extrusion equipment modifications enable high-contamination rPET processing without greenfield capacity investments. |
| Deposit-Return System Harmonization | Provincial program alignment would concentrate post-consumer collection economics and secure feedstock demand for bottle-to-bottle loops. |
| Pump Dispenser Conversion Partnerships | Personal care brands in Vancouver and Toronto manufacturing clusters shift procurement from jars to precision closure systems. |
Research Methodology
A spread of perspectives from blow-molding plant managers, beverage procurement leads at Ontario and Quebec bottlers, dairy co-packing logistics coordinators, and Health Canada regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with converter operations executives and secondary validation against customs trade data, Canadian Plastics Industry Association reports, provincial extended producer responsibility program disclosures, and SEC filings from multinational packaging parents. Bottom-up resin demand modeling and top-down packaging consumption estimates triangulated on volume figures.
Segmentation dimensions modeled include resin chemistry tier, closure mechanism precision, end-use regulatory cluster, and packaging size format across the projection horizon. CAGRs were derived from elasticity-adjusted demand projections incorporating virgin resin price volatility assumptions and recycled content mandate compliance trajectories. Industry-specific forecast inputs rest on deposit-return system participation rates and Health Canada Letters of No Objection approval velocity.
Material uncertainties — federal single-use plastics prohibition expansion, provincial deposit-return harmonization delays, and rPET flake quality degradation through multiple reheat cycles — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock collection infrastructure investment. Recalibration cycles align with material shifts in Health Canada guidance document revisions and provincial extended producer responsibility threshold adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Disposable Straw Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
Global Molded Plastic Packaging Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
US Lubricant Contaminated HDPE Container Waste Market
Plastic Packaging
HDPE Jug Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
South Africa Plastic Packaging Market