
 Corrugated Wrap Around Market | 2026-2036
Corrugated Wrap Around Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Wrap Around Market Outlook
E-commerce fulfillment is reorganizing demand patterns across buyer archetypes in the corrugated wrap around space. Food and beverage manufacturers sustain bulk procurement volumes through long-term supply agreements. WestRock Company leverages integrated pulp-to-box operations across North American mills. Mondi Group anchors European supply with specialty kraft linerboard capacity.
Corrugated wrap around denotes a sleeve-style paperboard enclosure formed from fluted medium bonded to linerboard faces, typically manufactured through steam-heated corrugation and scored for fold-around application. The structure protects palletized or bundled goods during transit while reducing material versus full six-panel alternatives. Single wall configurations dominate high-velocity consumer goods lanes where cost-per-unit governs selection. Double wall grades lead electronics shipping for crush resistance on international routes. Triple wall remains concentrated in industrial machinery segments with mature growth profiles but durable margin pools.
The EPA enforces recycled fiber thresholds under Comprehensive Procurement Guidelines, directly elevating post-consumer content requirements for domestic producers. ISO 186 and TAPPI T 811 standards govern burst strength and edge crush test methodologies that determine qualification for pharmaceutical transport and medical supplies. Stakeholders must monitor how state-level extended producer responsibility frameworks in California and New York reshape recovery infrastructure and material cost structures.
Market Dynamics
Automated packaging line investments across e-commerce fulfillment networks are compressing lead times and reshaping supplier qualification criteria for corrugated wrap around formats.
Growth Catalysts
- E-commerce fulfillment acceleration:Distribution centers in the United States and Germany are retrofitting lines for sleeve-style formats that reduce material handling steps. Automated case erectors now accept wrap around blanks at velocities exceeding six-panel alternatives.
- EPA recycled content mandates:Post-consumer fiber thresholds under Comprehensive Procurement Guidelines are forcing domestic mills to reconfigure pulp blends. Suppliers achieving 35% recycled content access federal procurement channels.
- Lightweighting technology:High-performance fluting grades from European producers enable source reduction without sacrificing edge crush performance. Food and beverage packers adopt these specifications for outbound pallet containment.
Market Restraints
- Recycled fiber cost volatility:OCC pricing fluctuations in North American spot markets compress converter margins unpredictably. Mills without captive pulp supply face quarterly restatement of contract rates.
- Supplier concentration in linerboard:Integrated producers control 70% of kraft liner capacity across the southeastern United States. Independent converters encounter allocation constraints during peak agricultural harvest windows.
- Dimensional limitations versus rigid alternatives:Wrap around formats fail to protect high-aspect-ratio products against lateral compression. Electronics manufacturers retain six-panel cases for displays exceeding 55 inches diagonal.
Strategic Opportunities
- Indian pharmaceutical cold chain:Temperature-sensitive biologics distribution requires insulated wrap around configurations with phase-change lining. CDSCO serialization mandates create entry points for track-and-trace-enabled packaging.
- EU Green Deal packaging targets:The 2030 recyclability requirements favor mono-material paperboard over multi-layer flexible formats. Brand owners accelerate wrap around trials for dry grocery categories.
- Digital print convergence with corrugation:Single-pass inkjet systems enable lot-specific graphics without plate changeover. Short-run promotional packaging for craft beverage producers becomes economically viable.
Industry Challenges
- Die-making skill scarcity:Precision scoring for complex fold patterns requires experienced tooling engineers. Southeast Asian converters report 18-month backlogs for qualified pattern development.
- ISO 186 certification timelines:Burst strength validation for pharmaceutical applications demands extended laboratory scheduling. Third-party testing capacity constraints delay product launches by two to three quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Wrap Around Market |
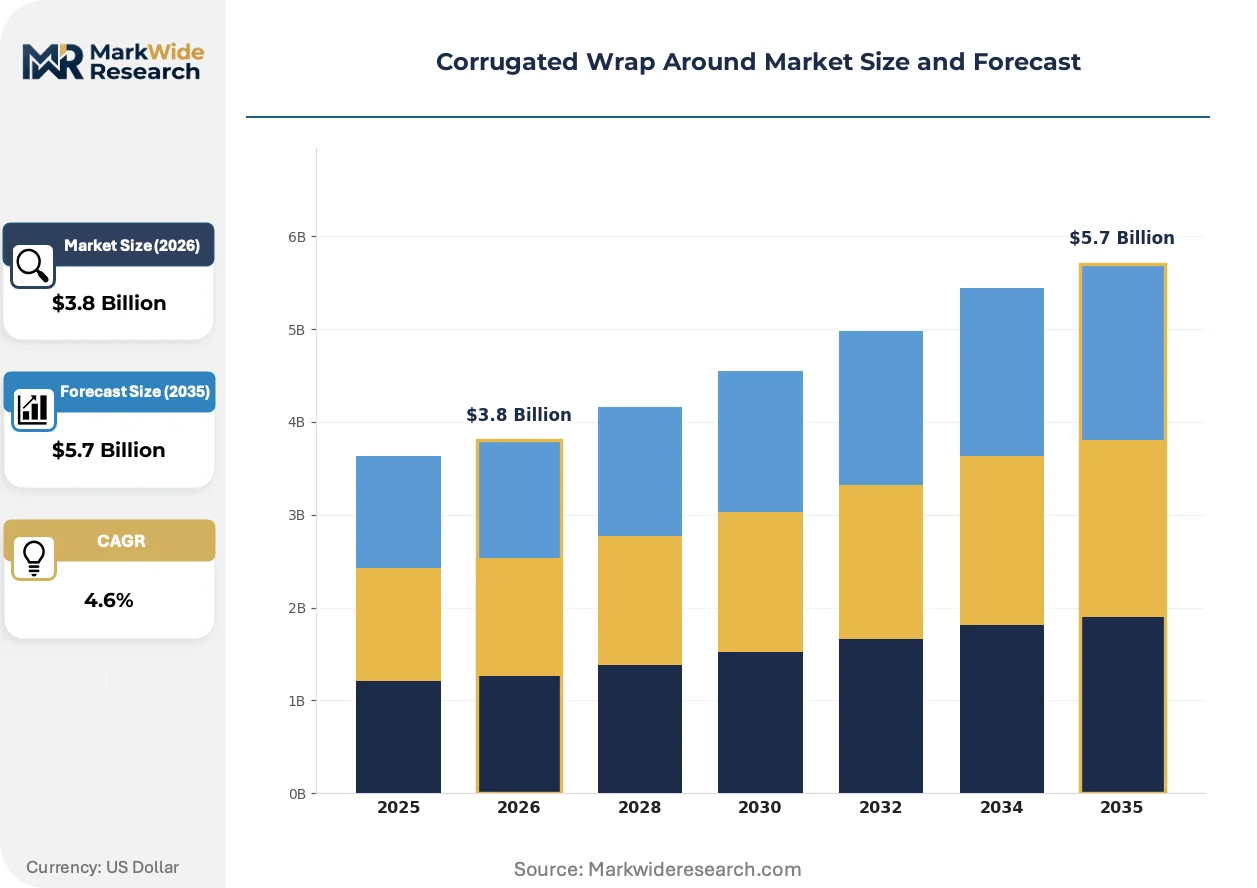
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Wall, Double Wall, Triple Wall, Kraft Paper Application: Food Packaging, Consumer Goods, Electronics Shipping, Pharmaceutical Transport End User Industry: Food & Beverage Manufacturers, E-commerce Fulfillment, Medical Supplies, Consumer Electronics Producers Distribution Channel: Direct Sales, Distributors, Online Platforms, Retail Packaging Suppliers |
| Companies Covered | International Paper, WestRock Company, Mondi Group, DS Smith, Smurfit Kappa Group, Georgia-Pacific, Packaging Corporation of America, Amcor, Sealed Air, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Wrap Around Market Strategic Shifts
Material science advances and regulatory compliance automation are converging to redefine performance benchmarks and procurement workflows across the corrugated wrap around value chain.
Micro-flute constructions are supplanting traditional C-flute profiles in consumer electronics fulfillment. Smartphone and laptop manufacturers specify E-flute and F-flute grades for direct-to-consumer shipments. The technology is supplanting foam-in-place cushioning while maintaining drop-test compliance through engineered flute geometry and selective adhesive reinforcement.
REACH restrictions on persistent organic pollutants in recycled fiber streams are compelling European mills to upgrade de-inking and screening infrastructure. The regulation forces substitution of certain wet-strength additives previously common in beverage packaging. German automotive parts suppliers now require full material disclosure documentation extending through tertiary packaging tiers.
Consolidated buying desks at multinational food retailers are compressing supplier rosters from twelve to three approved converters per region. Category managers demand integrated design-to-delivery platforms with real-time order tracking. The transformation is most advanced in the United Kingdom, where Tesco and Sainsbury's have completed vendor rationalization programs for ambient grocery packaging.
Corrugated Wrap Around Market Segmentation
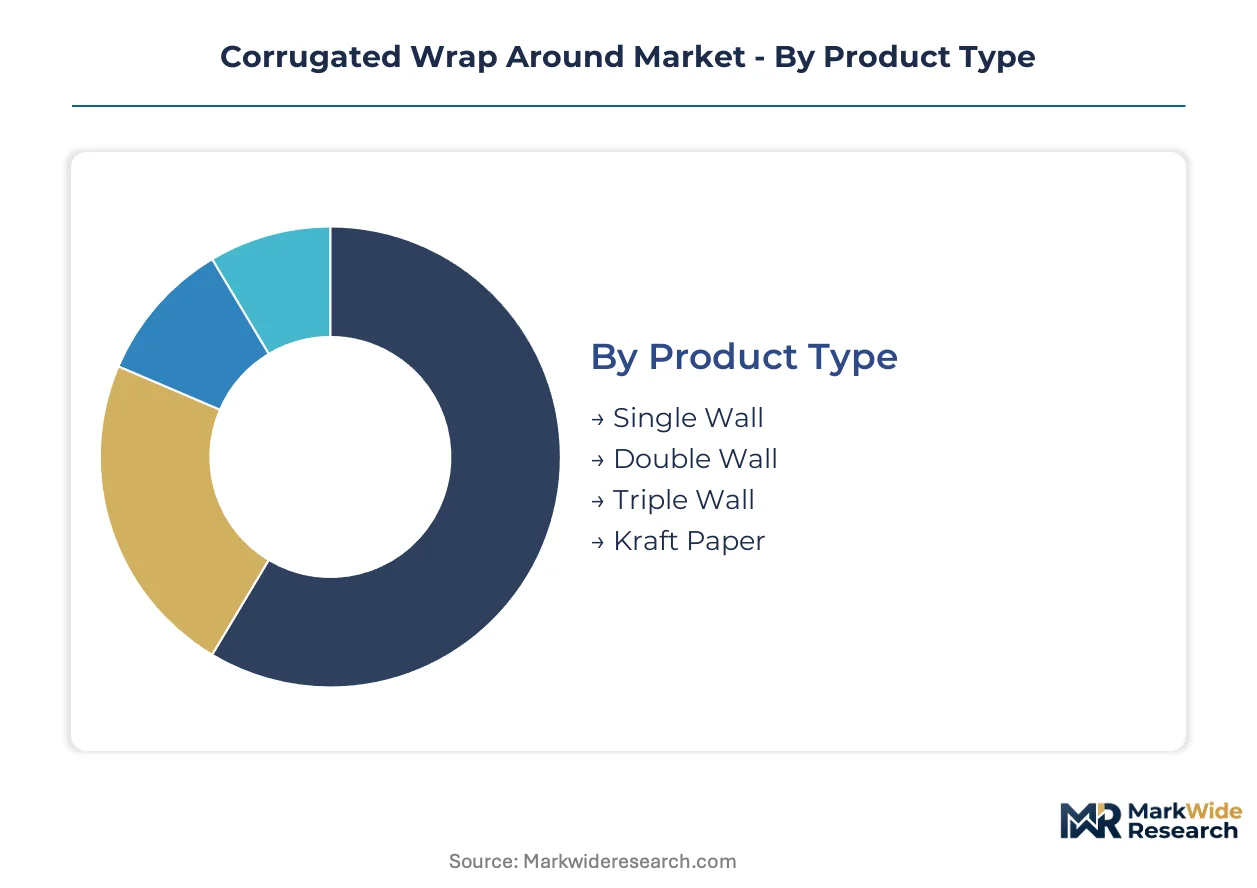
Corrugated wrap around formats flow through distinct procurement channels depending on structural grade and end-use compliance requirements. Understanding these segment pathways reveals where converter investments concentrate and which qualification barriers limit supplier entry.
Product Type:
Single wall and double wall grades dominate direct mill relationships with high-volume food packers, while triple wall and specialty kraft paper move through distributor networks serving fragmented industrial accounts.
- Single Wall:C-flute and B-flute configurations bonded to recycled linerboard faces serve high-velocity consumer goods lanes. E-commerce fulfillment centers in the United States specify these grades for automated case erectors processing over 30,000 units hourly.
- Double Wall:BC-flute combinations with reinforced medium layers provide crush resistance for international electronics routes. German automotive parts suppliers mandate this grade for export shipments to assembly plants in Mexico and China.
- Triple Wall:Heavy-duty industrial containment for machinery and metal components.
- Kraft Paper:Virgin fiber specialty grades for pharmaceutical cold chain applications requiring moisture barriers.
Single wall dominates installed base by volume. Double wall is where expansion concentrates as electronics direct-to-consumer channels scale.
Application:
Cost tier stratification separates commodity food packaging from premium pharmaceutical and electronics segments where certification overhead elevates pricing.
- Food Packaging:Pallet containment for ambient grocery and beverage outbound logistics. Long-term supply agreements with multinational retailers lock in converter capacity across twelve- to twenty-four-month contracts.
- Consumer Goods:Personal care and household product bundling. Indian pharmaceutical distributors specify insulated wrap around with phase-change lining for temperature-sensitive biologics.
- Electronics Shipping:Micro-flute E-grade and F-grade profiles with engineered geometry replace foam cushioning for smartphones and laptops. Drop-test compliance without resin-based protection aligns with EU Green Deal recyclability mandates.
- Pharmaceutical Transport:Burst strength validation under ISO 186 governs qualification. Third-party testing capacity constraints delay product launches by multiple quarters.
Food packaging anchors volume throughput. Electronics shipping is climbing the fastest as direct-to-consumer channels disassemble traditional retail distribution.
End User Industry:
Customer type determines whether procurement flows through centralized buying desks or fragmented spot purchasing, reshaping converter sales force deployment.
- Food & Beverage Manufacturers:Bulk procurement through integrated pulp-to-box suppliers with captive linerboard supply. Consolidated vendor rosters compress independent converter access.
- E-commerce Fulfillment:Automated line retrofits favor sleeve-style formats reducing material handling steps. Distribution centers prioritize suppliers with real-time order tracking platforms.
- Medical Supplies:Sterile barrier requirements and serialization mandates under FDA and CDSCO frameworks create specialized qualification pathways.
- Consumer Electronics Producers:Direct-to-consumer shipment specifications drive micro-flute adoption and digital print compatibility for lot-specific graphics.
Food and beverage manufacturers dominate installed base. E-commerce fulfillment is gaining share fastest as distribution center automation accelerates.
Distribution Channel:
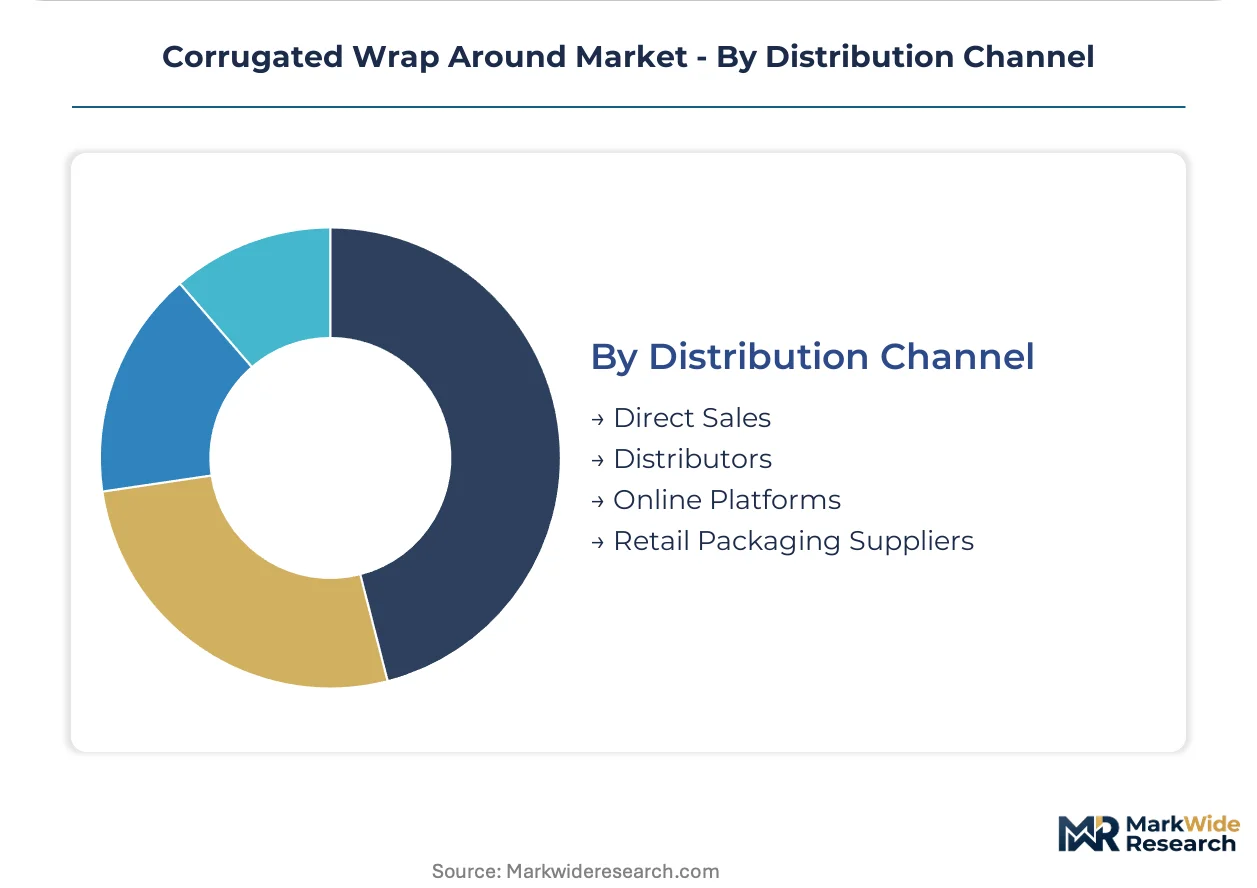
Geographic supply concentration shapes channel viability, with direct sales viable only where mill density supports freight economics.
- Direct Sales:Integrated producers with southeastern United States mill networks serve high-volume accounts without intermediary markup. Allocation constraints emerge during peak agricultural harvest windows.
- Distributors:Regional inventory buffering for mid-tier food processors and industrial machinery shippers without container-load purchasing power.
- Online Platforms:Digital procurement portals for small-batch craft beverage producers and specialty pharmaceutical distributors.
- Retail Packaging Suppliers:Last-mile consolidation for independent converters serving fragmented local accounts.
Direct sales dominates volume concentration. Distributors represent the steepest expansion trajectory as vendor rationalization programs push midsize accounts toward intermediary relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive parts suppliers export BC-flute wrap around configurations to assembly plants in Mexico and China, establishing a transatlantic trade corridor that shapes European linerboard capacity planning.
United States
E-commerce fulfillment centers in California and Texas retrofit automated case erectors for sleeve-style formats processing over 30,000 units hourly. EPA Comprehensive Procurement Guidelines enforce 35% post-consumer fiber thresholds for federal packaging contracts. Southeastern mill networks in Georgia and Alabama concentrate integrated pulp-to-box operations serving high-volume food packers.
Germany
Automotive export demand for double-wall crush resistance drives specification standardization across supplier tiers. REACH restrictions on persistent organic pollutants compel mill upgrades to de-inking infrastructure. The Baden-Württemberg industrial corridor hosts specialty kraft linerboard capacity anchoring European pharmaceutical cold chain supply.
China
Direct-to-consumer electronics channels accelerate micro-flute adoption for smartphone and laptop shipments. GB standards govern corrugated performance testing for domestic distribution. The Yangtze River Delta manufacturing cluster scales E-flute and F-flute production for brand-owner sustainability mandates.
India
Temperature-sensitive biologics distribution creates insulated wrap around demand with phase-change lining requirements. CDSCO serialization mandates open track-and-trace packaging entry points. Maharashtra pharmaceutical distributors consolidate procurement through regional inventory hubs serving cold chain networks.
United Kingdom
Consolidated retail buying desks at Tesco and Sainsbury's compress approved converter rosters from twelve to three per region. EU Green Deal 2030 recyclability targets accelerate mono-material trials for dry grocery categories. Midlands distribution infrastructure supports vendor rationalization programs for ambient grocery packaging.
Corrugated Wrap Around Market Competitive Environment
Player mix skews toward integrated pulp-to-box conglomerates controlling captive linerboard supply. Tier-one producers dominate high-volume food and beverage contracts through direct mill relationships. Three archetypes define competitive positioning: integrated giants with southeastern US mill networks, European specialty kraft specialists, and regional converters serving fragmented industrial accounts. Capacity expansion and strategic partnerships constitute the dominant competitive moves as participants defend allocation priority during peak agricultural windows.
Among North American integrated producers, International Paper and WestRock Company exemplify scale-driven archetypes with backward control over pulp supply. Mondi Group anchors European positioning through specialty kraft linerboard capacity serving pharmaceutical and automotive export specifications. These three entities represent the structural concentration governing qualification criteria for automated packaging line retrofits across e-commerce fulfillment networks.
| Leading Market Players |
|---|
| International Paper |
| WestRock Company |
| Mondi Group |
| DS Smith |
| Smurfit Kappa Group |
| Georgia-Pacific |
| Packaging Corporation of America |
| Amcor |
| Sealed Air |
| Others |
Value Chain & Pricing Dynamics
EPA Comprehensive Procurement Guidelines gate federal packaging contracts through recycled fiber thresholds, simultaneously filtering supplier qualification and stratifying price premiums across post-consumer content tiers. Food and beverage manufacturers leverage long-term supply agreements to lock converter capacity, while independent distributors absorb spot-market volatility for fragmented industrial accounts.
Pricing Analysis
Micro-flute technology-generation pricing gaps separate E-flute and F-flute direct-to-consumer specifications from legacy C-flute commodity grades. Three-tier pricing structure across pharmaceutical-grade kraft linerboard, food-grade recycled content, and industrial double-wall standard governs contract negotiations. Cost compression in single-wall consumer goods lanes intensifies as automated case erector compatibility becomes table stakes. E-commerce fulfillment centers exhibit highest price sensitivity, while pharmaceutical cold chain buyers prioritize burst strength certification over unit economics.
Supply Chain Analysis
The United States, Germany, and China anchor global linerboard and fluting medium production for corrugated wrap around formats. Virgin kraft pulp, old corrugated containers, and wet-strength additives constitute primary input dependencies. Single-source vulnerability concentrates in southeastern United States integrated mill networks during peak agricultural harvest windows. Distribution runs through direct mill relationships for high-volume food packers and regional distributor networks for mid-tier industrial machinery shippers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated wrap around penetration sits in early-cycle expansion as e-commerce fulfillment center automation retrofits accelerate sleeve-format adoption. Direct-to-consumer electronics channels disassemble traditional retail distribution, creating sustained demand tailwinds.
For Market Incumbents: Fortify allocation priority during seasonal harvest windows through captive linerboard supply and backward integration into pulp production. Invest in ISO 186 certification infrastructure to defend pharmaceutical contract access against emerging specialty converters. Expand E-flute and F-flute capacity in Yangtze River Delta manufacturing clusters to capture consumer electronics micro-flute specifications.
For New Entrants and Emerging Players: CDSCO serialization fast-track certification opens insulated wrap around entry points for Indian pharmaceutical cold chain distributors. Target temperature-sensitive biologics segments with phase-change lining capabilities as the most penetrable white-space. Pursue digital print convergence partnerships with single-pass inkjet system providers for craft beverage short-run promotional packaging.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated packaging line integration and de-inking infrastructure upgrades for REACH compliance. Five-to-ten year viability favors specialty kraft linerboard producers with pharmaceutical and automotive export qualification. Monitor OCC spot market volatility as the primary inflection signal for integrated versus independent converter margin divergence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive linerboard production secures allocation priority during peak agricultural harvest windows. |
| Micro-Flute Capacity Expansion | E-flute and F-flute specifications capture consumer electronics direct-to-consumer shipment demand. |
| ISO 186 Certification Investment | Burst strength validation opens pharmaceutical transport contracts with extended laboratory scheduling. |
| Digital Print System Partnership | Single-pass inkjet enables lot-specific graphics for craft beverage promotional packaging. |
| Cold Chain Insulation Development | Phase-change lining configurations address CDSCO-mandated temperature-sensitive biologics distribution. |
Study Parameters
A standing panel of corrugated converter operations managers, e-commerce fulfillment center procurement leads, pharmaceutical packaging engineers, and food and beverage supply chain directors provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from EPA Comprehensive Procurement Guidelines documentation, TAPPI technical standards, FEFCO industry statistics, and customs trade data for linerboard and medium flows. Bottom-up volume modeling and top-down value reconciliation triangulated segment outputs.
Consistency checks validated projections against external benchmarks including mill capacity utilization reports and automated packaging line investment disclosures across major distribution networks. Segmentation dimensions spanned structural grade tier, end-use compliance requirement, procurement channel type, and regional production hub clustering. CAGRs derived from elasticity-adjusted demand curves incorporating e-commerce shipment velocity trends and recycled fiber cost trajectory assumptions.
Underlying assumptions cover EPA recycled content threshold stability and REACH persistent organic pollutant restriction enforcement timelines, with deviation risk concentrated in OCC spot market volatility and state-level extended producer responsibility framework adoption. Recalibration cycles align with material shifts in e-commerce fulfillment automation investment and pharmaceutical serialization mandate implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
Bulb Packaging Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Cutterbox Films Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Die Cut Support Pads Market
Packaging Materials
Cement Packaging Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Twist Tie Market
Packaging Materials
Thermoformed Tubs Market