
 Packaging Lacquering Market | 2026-2036
Packaging Lacquering Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Lacquering Market Insights
Performance-based coating service contracts is hardening as the dominant commercial model in packaging lacquering, shifting capital allocation from equipment ownership to guaranteed output specifications. Amcor leverages its integrated film-to-coating infrastructure to lock in multi-year supply agreements with beverage bottlers. Crown Holdings anchors North American metal can demand through captive lacquering lines at its manufacturing plants. Constantia Flexibles differentiates via specialty high-barrier lacquer formulations for pharmaceutical blister foils.
Packaging lacquering applies thin protective or decorative coatings—typically 2–12 micrometers thick, composed of acrylic, epoxy, or polyester resins cured by thermal, UV, or electron-beam processes—to substrates in order to enhance chemical resistance, printability, and shelf-life integrity. Water-based lacquers now lead volume in food-contact applications as processors eliminate solvent recovery costs, while UV lacquers capture premium personal care and electronics packaging segments where instant cure and scratch resistance command price premiums. Metal cans remain the largest packaging material category for lacquering, though composite materials growth is accelerating in aseptic dairy and ready-to-drink coffee formats.
EPA regulations in the United States enforce National Emission Standards for Hazardous Air Pollutants on can coating operations, compelling facility upgrades and solvent substitution programs. REACH in Europe mandates substance registration and restricts candidate list chemicals in lacquer formulations, directly influencing R&D pipelines at formulators serving export markets. India's BIS certification requirements for food-contact coatings add a compliance layer for multinational suppliers entering domestic supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation fragmentation that strains manufacturing economics.
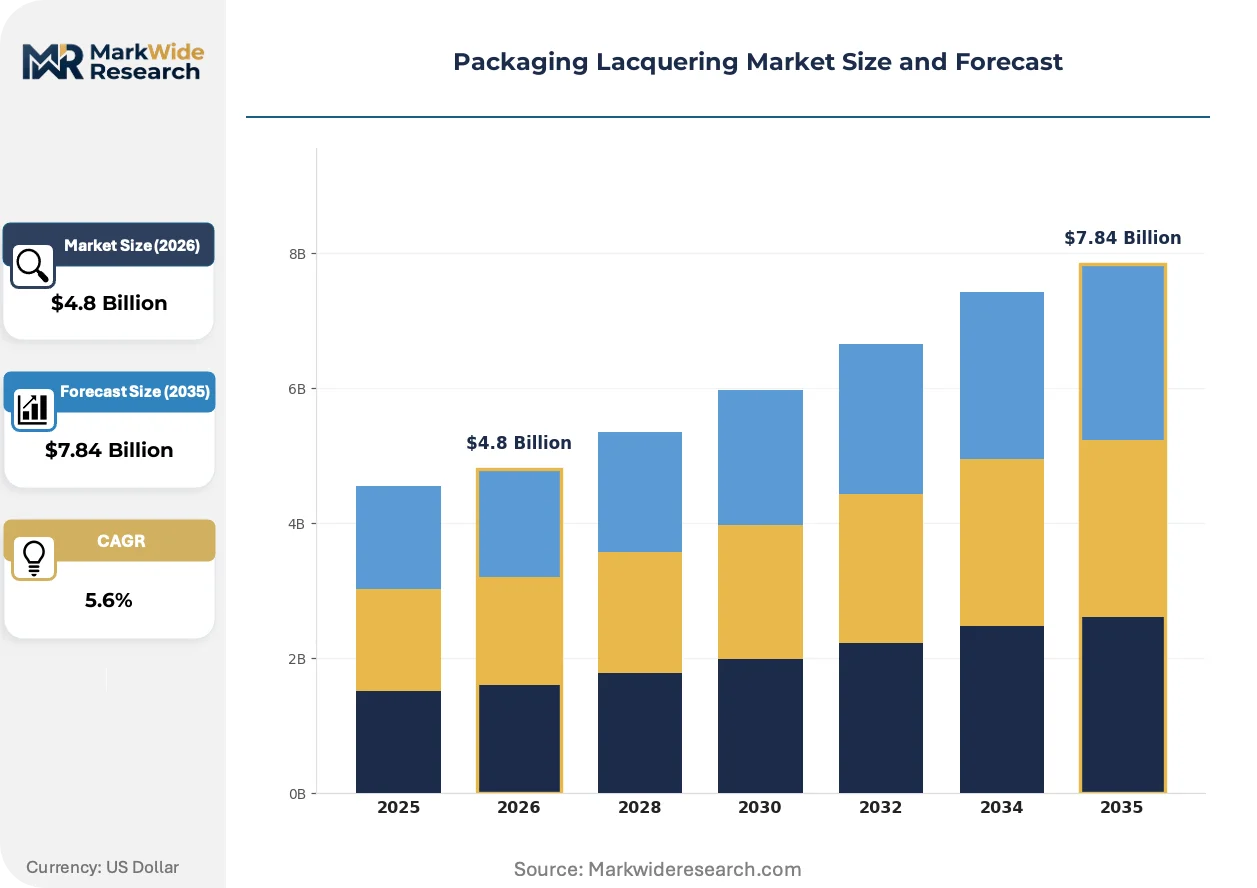
Market Dynamics
Water-based lacquer substitution for solvent-borne coatings is compressing capital recovery timelines for can coating lines while redrawing supplier qualification criteria across food-contact packaging networks.
Growth Catalysts
- REACH VOC thresholds:ECHA-mandated volatile organic compound reductions in Europe are accelerating water-based formulation R&D and creating first-mover advantages for compliant suppliers.
- Processed food output in India:Domestic canning capacity expansion is generating pull-through demand for BIS-certified food-contact lacquers from multinational formulators.
- UV electron-beam curing:Instant cure properties are displacing thermal ovens in personal care and electronics packaging, reducing energy intensity and floor space requirements.
Market Restraints
- Epoxy resin supply concentration:Bisphenol-A feedstock sourcing depends on a narrow supplier base in East Asia, exposing formulators to input cost volatility and qualification delays.
- REACH registration burdens:ECHA substance registration requirements impose fixed compliance costs that disproportionately burden small-batch specialty lacquer producers.
- Substitution by flexible pouches:Retortable multilayer films are capturing shelf-stable food volume, constraining metal can demand growth in ready-meal segments.
Strategic Opportunities
- Aseptic dairy formats:Composite carton and cup lacquering for ambient yogurt and coffee drinks represents underpenetrated white space in North American packaging.
- India PLI scheme:Production-linked incentives for domestic manufacturing are lowering entry barriers for coating operations serving processed food exporters.
- Digital printing convergence:Inkjet-compatible lacquer formulations that enable variable-data decoration are opening premium customization channels for craft beverage brands.
Industry Challenges
- Formulation chemist scarcity:Expertise in food-contact polymer science and migration testing is concentrating at a handful of technical institutes, lengthening hiring cycles for new product development teams.
- Dual certification timelines:Simultaneous FDA food-contact notification and EU migration compliance testing extends commercialization schedules by 18-24 months for novel resin systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Lacquering Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Lacquers, Solvent-Based Lacquers, UV Lacquers, Powder Coatings, Nitrocellulose Lacquers Application: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Packaging, Industrial Goods Packaging Material: Metal Cans, Paperboard, Plastics, Glass Containers, Composite Materials End User Industry: Consumer Goods Manufacturers, Chemical Producers, Cosmetic Brands, Specialty Packaging Firms |
| Companies Covered | Amcor, Ball Corporation, Crown Holdings, Silgan Holdings, Sonoco Products Company, Huhtamaki, Constantia Flexibles, CCL Industries, Bericap, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Lacquering Market Trends and Innovations
Active coating functionality—barrier enhancement, antimicrobial properties, and temperature indication—is displacing passive protection as the primary value proposition in premium packaging segments.
Electron-beam curable lacquers are electrifying high-speed can coating lines by eliminating thermal curing ovens and enabling inline quality verification. Beverage canners in Germany and Japan are retrofitting EB units to compress changeover times and reduce energy consumption per thousand units. The technology is compressing the traditional capital-intensity gap between metal and flexible packaging.
EPA National Emission Standards for Hazardous Air Pollutants enforcement is compelling US can coating facilities to install thermal oxidizers or switch to water-based formulations. Compliance deadlines are compressing capital allocation decisions for mid-sized independent coaters. Food-contact applications face the steepest retrofit costs due to stringent FDA migration limits on alternative resin systems.
Brand procurement teams are consolidating coating supply under performance-guarantee contracts that transfer formulation risk to suppliers. Beverage bottlers in Mexico and Spain are replacing spot purchasing with multi-year agreements specifying defect rates and migration compliance. This shift is compressing the supplier base and rewarding integrated formulators with captive resin production.
Packaging Lacquering Market Segmentation
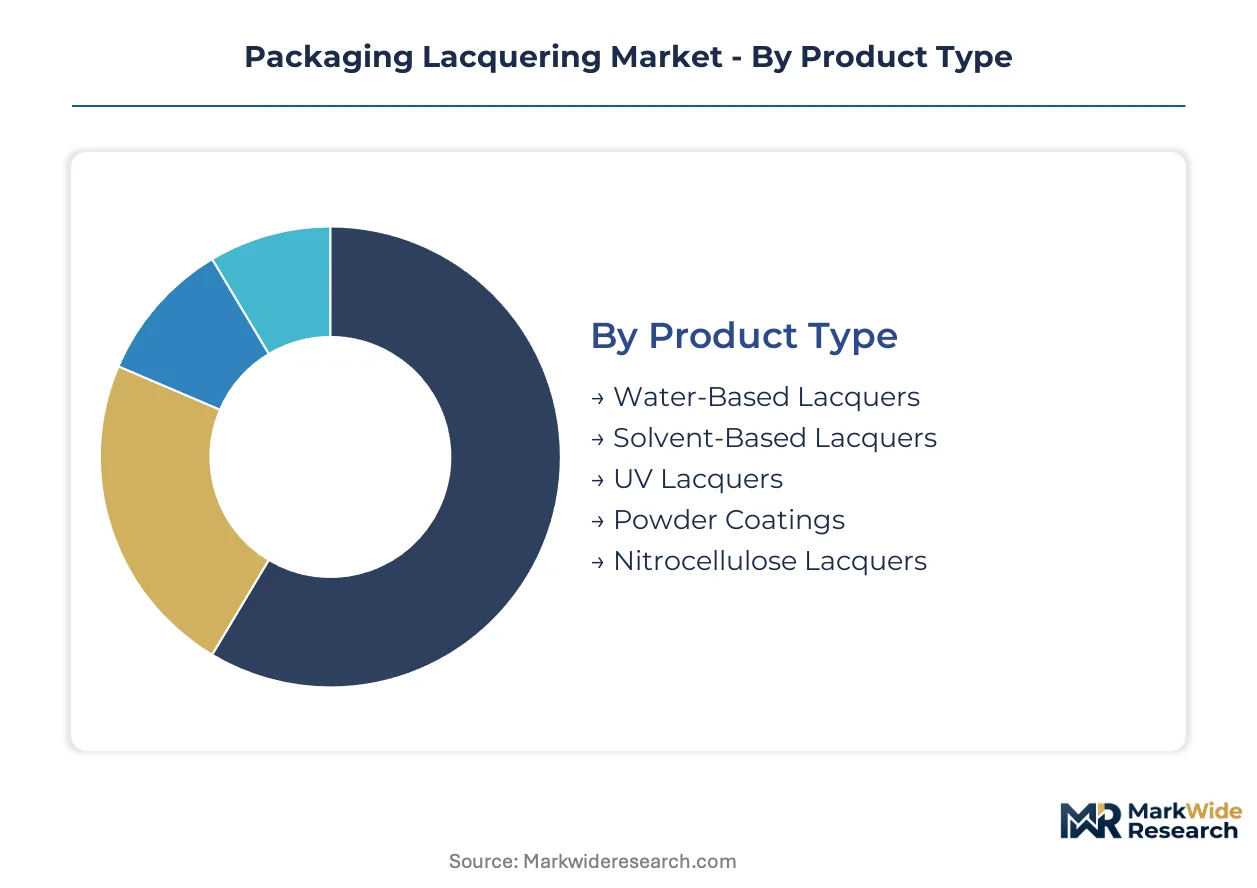
Packaging lacquer selection hinges on cure chemistry, substrate compatibility, and migration compliance thresholds. Formulators align product portfolios with upgrade cycles in can coating lines and emerging composite packaging formats.
Product Type:
Replacement of thermal curing infrastructure with electron-beam and UV systems is redrawing the competitive map among lacquer chemistries.
- Water-Based Lacquers:Acrylic and polyester emulsions dominate food-contact metal can lines where EPA NESHAP compliance eliminates solvent recovery costs. Beverage canners in the United States and Germany are retrofitting lines to capture lower energy intensity and reduced volatile organic compound emissions.
- Solvent-Based Lacquers:Epoxy and polyester formulations retain grip in high-speed decorative applications requiring superior adhesion to treated aluminum. REACH-mandated VOC thresholds in Europe are compressing addressable market scope to specialty industrial segments with exempted process requirements.
- UV Lacquers:Photoinitiated acrylates enable instant cure for premium cosmetics and electronics packaging. Personal care brands in Japan and South Korea specify these for scratch-resistant finishes on rigid plastic containers.
- Powder Coatings:Thermoset epoxy-polyester hybrids serve industrial drum and pail applications where film build exceeds liquid lacquer practical limits.
- Nitrocellulose Lacquers:Cellulose ester solutions persist in specialty decorative paperboard and cigar packaging where rapid solvent release and hand-rubbed aesthetics command niche premiums.
Water-based lacquers sit at the top of the volume ranking, with UV lacquers climbing the fastest as personal care brands specify instant-cure performance.
Application:
Migration testing protocols and shelf-life specifications create divergent margin profiles across end-use categories.
- Food & Beverage:Internal and external coatings for two-piece and three-piece metal cans face dual FDA food-contact notification and EU migration compliance. Retortable dairy and ready-to-drink coffee formats are expanding addressable substrate scope beyond traditional beverage cans.
- Personal Care:High-gloss decorative finishes on glass and rigid plastics command formulation premiums for scratch resistance and chemical compatibility with aggressive product chemistries.
- Pharmaceuticals:Blister foil and vial seal lacquers require EMA and FDA drug master file alignment for barrier integrity and extractables control.
- Electronics Packaging:Antistatic and moisture-barrier coatings for semiconductor and component shipping media specify low-outgassing epoxy and acrylic systems.
- Industrial Goods:Drum, pail, and intermediate bulk container coatings prioritize chemical resistance over aesthetic finish in chemical and lubricant logistics.
Food and beverage coatings generate the largest revenue pool, while pharmaceuticals delivers the steepest expansion trajectory driven by serialization and barrier enhancement requirements.
Packaging Material:
Substrate thermal tolerance and surface energy dictate compatible cure mechanisms and resin selection.
- Metal Cans:Aluminum and tinplate beverage and food cans constitute the installed base for high-speed roll-coating and spray lines. Electrochemical treatment compatibility and weld-bond integrity specifications constrain qualified formulation portfolios.
- Paperboard:Liquid packaging cartons and cup stocks require extrusion-laminated or direct-coated barrier layers for aseptic dairy and juice applications.
- Plastics:Polyethylene terephthalate, polypropylene, and polystyrene containers for cosmetics and electronics demand UV-curable or thermally cured systems with controlled adhesion promotion.
- Glass Containers:Decorative and protective coatings for perfume and spirit bottles specify organosilane or acrylic systems with thermal shock resistance.
- Composite Materials:Multi-layer cartons and cups for ambient yogurt and coffee drinks represent underpenetrated white space in North American packaging infrastructure.
Metal cans anchor current volume leadership, with composite materials gaining share fastest as aseptic dairy formats expand beyond European and Asian strongholds.
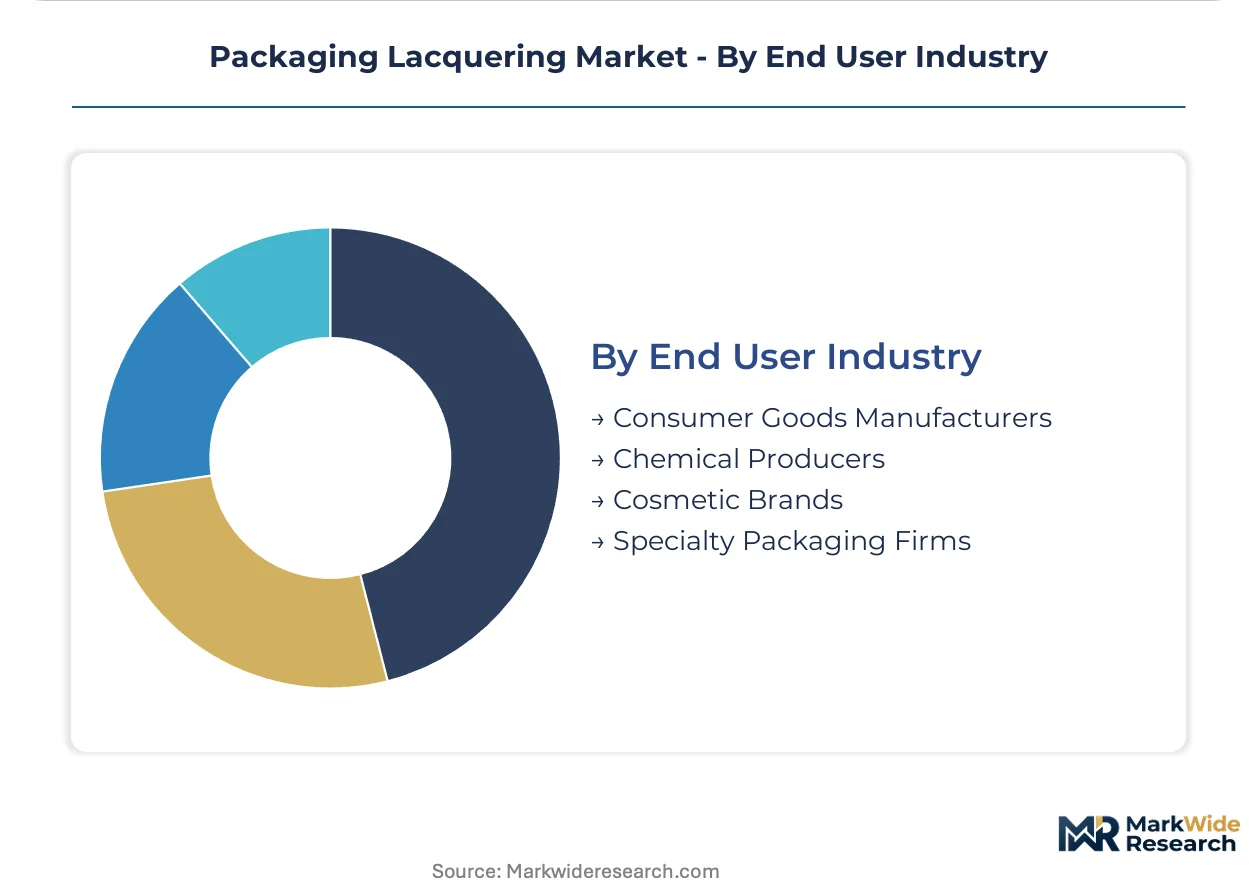
End User Industry:
Procurement consolidation and performance-guarantee contracting are compressing the qualified supplier base across customer categories.
- Consumer Goods Manufacturers:Multinational beverage and food processors specify multi-year coating supply agreements with defect-rate and migration-compliance guarantees. Mexico and Spain bottlers have shifted from spot purchasing to integrated service contracts.
- Chemical Producers:Industrial packaging buyers prioritize drum and pail coating durability for hazardous material logistics, with less sensitivity to decorative finish specifications.
- Cosmetic Brands:Premium fragrance and skincare houses demand customized decorative effects and rapid changeover capabilities for limited-edition launches.
- Specialty Packaging Firms:Independent converters serving pharmaceutical and electronics niches require small-batch flexibility and dual FDA-EU certification support from formulator partners.
Consumer goods manufacturers command the largest procurement scale, with specialty packaging firms expanding most quickly as serialization and customization requirements fragment order profiles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting lacquer formulation investment toward jurisdictions where REACH-equivalent compliance costs remain lower, while EPA enforcement in the United States compresses margins for solvent-dependent operations.
United States
Beverage canners in Texas and the Midwest are retrofitting thermal oxidizers to meet EPA National Emission Standards for Hazardous Air Pollutants deadlines. FDA food-contact notification requirements for alternative resin systems extend qualification timelines. Chicago and Pittsburgh anchor metal can coating capacity where Crown Holdings operates captive lacquering lines.
Germany
Electron-beam curing installations in Bavaria and North Rhine-Westphalia are displacing thermal ovens for high-speed beverage lines. ECHA-mandated VOC thresholds under REACH accelerate water-based formulation R&D at formulators serving export markets. The Rhine-Ruhr industrial corridor concentrates coating chemical production and migration testing laboratories.
India
Domestic processed food output expansion in Maharashtra and Gujarat generates pull-through demand for BIS-certified food-contact lacquers. Production-linked incentive schemes lower entry barriers for coating operations serving processed food exporters. The Mumbai-Pune industrial belt hosts emerging can manufacturing clusters requiring qualified lacquer supply.
Japan
Personal care brands in Osaka and Tokyo specify UV-curable lacquers for scratch-resistant finishes on rigid plastic containers. METI industrial standards influence formulation specifications across electronics packaging applications. The Kansai region maintains specialty coating R&D concentration for premium cosmetic and semiconductor shipping media.
Mexico
Beverage bottlers in Mexico City and Nuevo León have shifted from spot purchasing to multi-year performance-guarantee contracts with coating suppliers. Proximity to United States export markets attracts formulation facilities seeking tariff-advantaged supply positions. The Bajío region hosts expanding can manufacturing capacity requiring compliant lacquer inputs.
Packaging Lacquering Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated packaging conglomerates commanding food-contact volume while independent formulators capture pharmaceutical and electronics niches. Three archetypes dominate: resin-integrated multinationals with captive raw material supply, regional specialists with BIS or FDA dual-certification capabilities, and equipment-integrated service providers offering performance-based coating contracts. Competitive moves center on backward integration into epoxy resin production and geographic expansion through qualification partnerships with emerging market canners.
Among resin-integrated packaging conglomerates, Amcor, Crown Holdings, and Constantia Flexibles exemplify distinct strategic positions. Amcor leverages integrated film-to-coating infrastructure to anchor multi-year supply agreements. Crown Holdings represents the captive lacquering model with in-house coating lines at manufacturing plants. Constantia Flexibles occupies the specialty formulation tier with high-barrier lacquer development for pharmaceutical applications.
| Leading Market Players |
|---|
| Amcor |
| Ball Corporation |
| Crown Holdings |
| Silgan Holdings |
| Sonoco Products Company |
| Huhtamaki |
| Constantia Flexibles |
| CCL Industries |
| Bericap |
| Others |
Pricing and Supply Chain Analysis
Beverage bottlers in Mexico and Spain have consolidated procurement under multi-year performance-guarantee contracts, compressing the supplier base and transferring formulation risk to lacquer formulators with captive resin production.
Pricing Analysis
Capacity additions in India are reshaping price floors for BIS-certified food-contact lacquers as domestic can manufacturing clusters expand. Contract-based long-term offtake dominates, with price differentiation hinging on FDA-EU dual certification status and volume scale. Cost compression in solvent-based tiers is intensifying because REACH-mandated VOC thresholds in Europe disqualify non-compliant formulations. Mid-sized independent coaters show highest price sensitivity due to thermal oxidizer retrofit burdens, while resin-integrated multinationals absorb compliance costs through captive feedstock supply.
Supply Chain Analysis
Dual FDA-EU certification requirements gate qualified supplier status, elongating commercialization timelines for novel resin systems. Raw material sourcing draws from epoxy resin concentration in East Asia, acrylic emulsion supply in Germany, and photoinitiator production in Japan. Bisphenol-A feedstock dependency creates single-source vulnerability for high-barrier formulations. Distribution runs through integrated packaging conglomerates with captive coating lines, supplemented by independent formulators serving pharmaceutical and electronics niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packaging lacquering market functions as a geographic-arbitrage play where ECHA-mandated REACH compliance costs in Europe exceed BIS certification burdens in India by a substantial margin, redirecting formulation investment toward South Asian manufacturing corridors.
For Market Incumbents: Deploy backward integration into epoxy resin production to insulate margins from Bisphenol-A feedstock volatility. Anchor multi-year supply agreements with beverage bottlers through performance-guarantee contracts specifying defect rates and migration compliance. Crown Holdings and Amcor demonstrate the captive lacquering model that locks out independent formulators from high-volume food-contact segments. For New Entrants and Emerging Players: The premium-economy price gap in UV-curable lacquers for personal care packaging creates entry opportunity for mid-tier formulators with inkjet-compatible capabilities. Target aseptic dairy composite formats in North America where incumbent coating infrastructure remains underdeveloped. Pursue qualification partnerships with emerging market canners in the Mumbai-Pune industrial belt to bypass saturated European supply chains. For Investors and Strategic Acquirers: Packaging conglomerates with film-to-coating integration are the most active acquirer in this space, seeking specialty formulation capabilities for pharmaceutical blister foils. Long-term viability hinges on water-based and electron-beam curable technology transitions over the next decade. Watch for EPA enforcement actions against solvent-dependent coaters as inflection signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Epoxy Resin | Crown Holdings reduces Bisphenol-A cost volatility through captive feedstock supply. |
| Electron-Beam Curing Retrofit | German beverage canners eliminate thermal ovens and compress energy consumption per thousand units. |
| Dual FDA-EU Certification Investment | Specialty formulators unlock pharmaceutical blister foil contracts requiring EMA and FDA drug master file alignment. |
| Performance-Guarantee Contracting | Mexico bottlers transfer formulation risk to suppliers through multi-year defect-rate specifications. |
| India PLI Scheme Participation | Coating operations serving processed food exporters capture production-linked incentive benefits in Maharashtra. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with coating formulators, can manufacturing plant managers, beverage procurement leads, and regulatory affairs specialists at ECHA and FDA with secondary validation from REACH registration databases, EPA NESHAP enforcement records, BIS certification listings, and customs trade data for epoxy resin and acrylic emulsion flows. Bottom-up volume modeling triangulated against top-down market sizing across cure chemistry, substrate compatibility, and migration compliance tiers.
Historical reference periods anchored the projection horizon to capture cyclical capital expenditure patterns in can coating line upgrades. Segmentation dimensions modeled include lacquer chemistry type, packaging material substrate, end-use application, and regional regulatory cluster. CAGRs derived from installed base analysis of thermal curing infrastructure displacement rates and electron-beam adoption curves. Forecast inputs incorporated EPA compliance deadline schedules and India PLI scheme uptake trajectories.
Caveats apply where ECHA substance registration burden revisions or FDA alternative resin system guidance could materially shift the outlook. Forecasts reflect assumptions about water-based formulation R&D timelines and UV electron-beam curing equipment deployment rates. A model refresh is warranted upon material change in REACH VOC threshold enforcement or BIS certification requirement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Sterilization Roll Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Production Page Volume Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
Europe Single-Use Packaging Market
Packaging Materials
Coconut Wraps Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
PET Material Packaging Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Global Strapping Market
Packaging Materials
EPE Liner Market
Packaging Materials
Global Anti Counterfeit Automobile Packaging Market