
 Flexible End-Load Cartoner Market | 2026-2036
Flexible End-Load Cartoner Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible End-Load Cartoner Market Foresight
A shortage of qualified mechatronics technicians is reorganizing how European OEMs structure their assembly and commissioning operations. Bosch Packaging leverages its captive training academies in Germany to sustain engineering throughput across servo-driven carton lines. Syntegon Technology differentiates through vertical integration into motion control hardware, reducing dependency on third-party drive suppliers. Marchesini Group anchors its competitive position in pharmaceutical-grade end-load systems through Italian manufacturing scale and cleanroom-compatible designs.
A flexible end-load cartoner erects and seals paperboard cartons through a horizontal loading motion, typically achieving speeds from 50 to 500 cartons per minute depending on servo drive configuration and product stability requirements. The machine forms cartons from flat blanks, loads products through the open end, and closes flaps via mechanical or hot-melt adhesive systems, serving industries where product orientation and gentle handling constrain loader design. Fully automatic systems lead installed base value due to labor substitution economics in high-volume food and beverage operations, while servo drive technology captures the fastest growth trajectory as packagers replace mechanical camshafts with programmable motion profiles for format change flexibility. Hybrid technology configurations are gaining traction where pneumatic actuators persist for low-cost flap folding while electric servos handle precision loading axes.
FDA 21 CFR Part 11 and EU Machinery Directive 2006/42/EC impose validation documentation and safety integrity requirements that elevate engineering costs for pharmaceutical and food-contact applications. OSHA machine guarding standards in the United States and CE marking obligations in Europe collectively shape regional product architectures, with North American builds emphasizing interlocked perimeter guarding and European designs prioritizing integrated safety PLCs. Stakeholders must monitor how evolving Ecodesign regulations and state-level extended producer responsibility frameworks in California and New York reshape material specifications and end-of-life obligations for carton forming equipment.
Market Dynamics
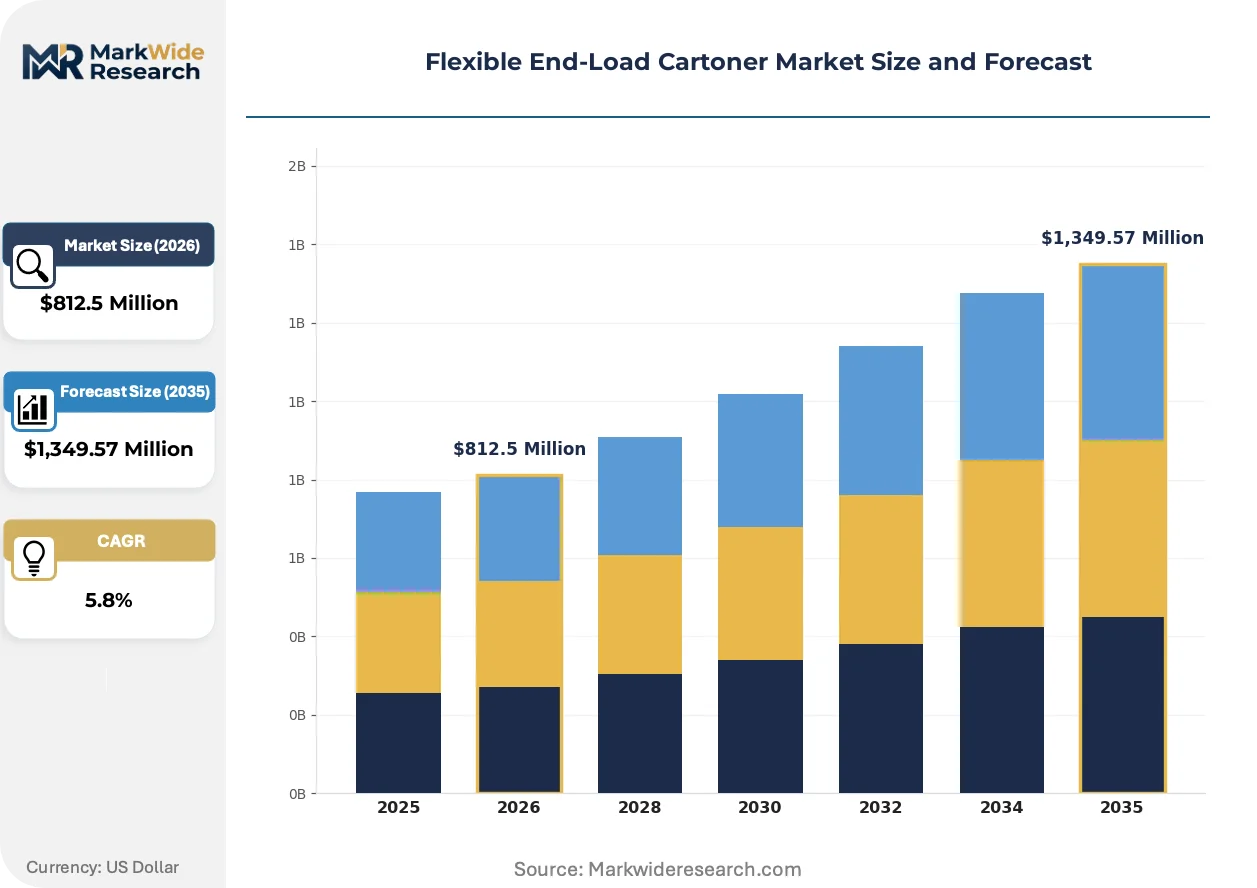
Mechanical camshaft-to-servo retrofits are compressing replacement cycles as packagers prioritize format flexibility over machine longevity. This hardware transition is redistributing value capture toward motion control suppliers and system integrators with mechatronics depth.
Growth Catalysts
- FDA 21 CFR Part 11 validation mandates:Pharmaceutical serialization requirements are forcing upgrades of legacy end-load lines, creating replacement demand for compliant servo-driven systems with full audit trails.
- Packaged food throughput pressures:Ready-meal and snack producers are automating end-load operations to hit 300+ cartons per minute with minimal changeover downtime between SKUs.
- German supplier cluster density:Concentrated engineering talent around Stuttgart and Dresden enables rapid commissioning support for export markets, shortening project timelines for multinational food brands.
Market Restraints
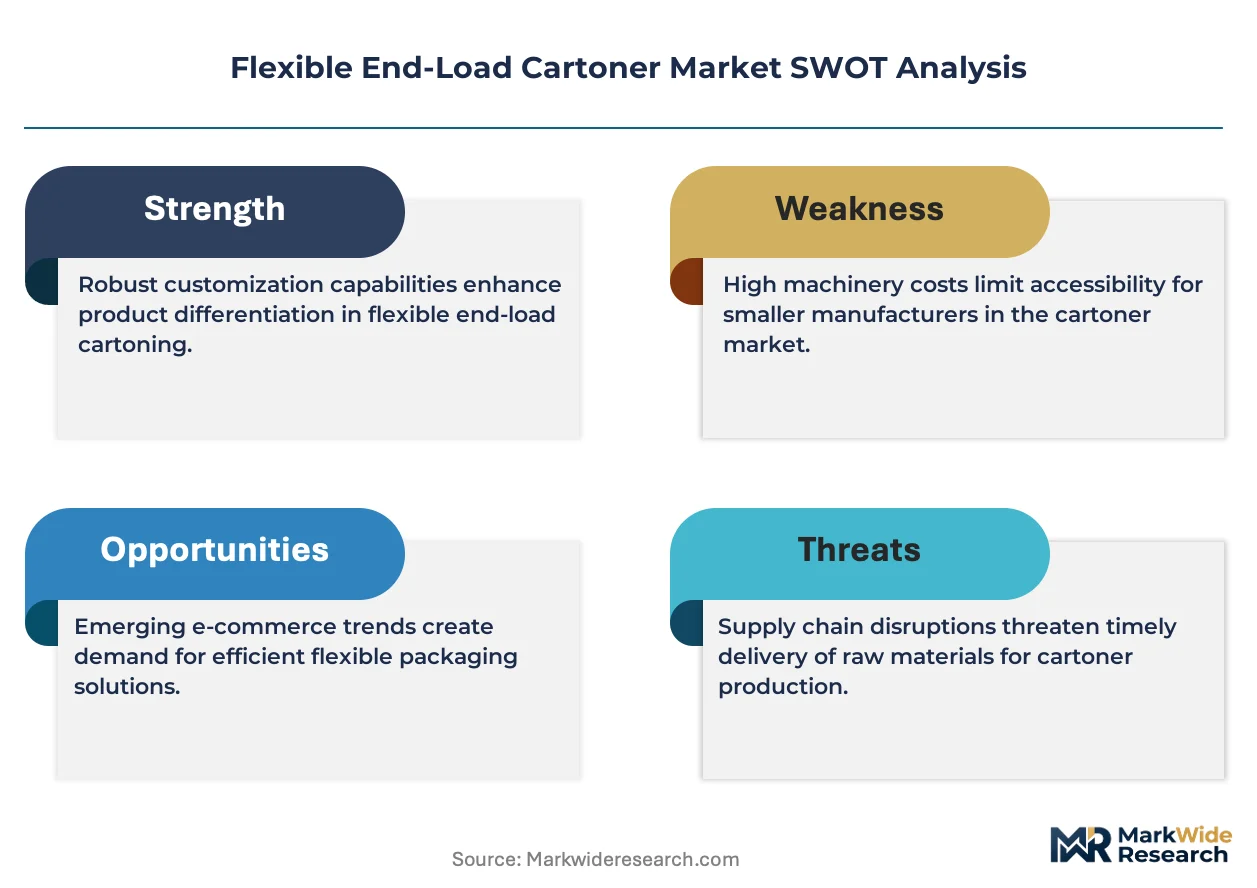
- Stainless steel and servo motor cost volatility:Food-grade 316L stainless and rare-earth magnet prices fluctuate with energy and mining output, squeezing margins on pharmaceutical-spec builds.
- Motion control supplier concentration:Dependency on a narrow set of European drive vendors for high-precision linear motors creates vulnerability when lead times extend.
- Mechanical camshaft persistence in low-speed lines:Pneumatic-mechanical hybrids under 100 cartons per minute resist full electrification due to capital recovery math at smaller packagers.
Strategic Opportunities
- India pharmaceutical packaging expansion:CDSCO serialization deadlines and export-oriented generic drug production are creating first-time demand for validated end-load cartoners in Ahmedabad and Hyderabad.
- CE marking and EU Machinery Directive convergence:Integrated safety PLC architectures that satisfy both European and emerging market standards open single-platform export strategies.
- Digital twin commissioning:Virtual servo tuning and collision detection before physical installation is cutting startup time for complex multi-axis loader configurations.
Industry Challenges
- Mechatronics technician scarcity:European OEMs face 6-12 month backlogs for qualified commissioning engineers who can integrate servo drives, safety PLCs, and vision systems.
- FAT/SAT documentation burden:Pharmaceutical customers demand exhaustive factory and site acceptance testing protocols that extend project timelines and tie up engineering resources.
- Legacy Allen-Bradley and Siemens PLC integration:Retrofitting servo axes into existing control architectures requires custom gateway development, complicating brownfield upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible End-Load Cartoner Market |
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,349.57 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Servo Drive, Servo Assisted Technology: Mechanical, Pneumatic, Electric, Hybrid Application: Pharmaceuticals, Cosmetics, Food & Beverage, Personal Care End User: Contract Packaging, In-House Packaging, Third-Party Packers, Packing Distributors |
| Companies Covered | Bosch Packaging, Bradman Lake Group, LEAD Packaging Technologies, Unista, KHS, 3 SL Pactec, Syntegon Technology, Marchesini Group, AFA Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible End-Load Cartoner Market Shifts & Advancements
Servo-electric architectures are displacing mechanical indexing across all speed tiers. This transition is fragmenting the supplier base between full-system builders and motion component specialists, while reshaping how packagers contract for maintenance and spare parts.
Hybrid pneumatic-electric actuation is fragmenting the mid-speed segment where cost-sensitive food producers need precision loading without full servo price tags. Pneumatic actuators handle flap folding while electric servos manage product placement, cutting capital outlay 15-25% versus all-electric alternatives. European dairy and bakery packagers are piloting these configurations to bridge the gap between mechanical reliability and format flexibility.
EU Machinery Directive 2006/42/EC safety integrity requirements are elevating engineering costs for pharmaceutical-grade builds. The directive mandates documented risk assessments and integrated safety PLCs for machines with collaborative loading stations. German and Italian OEMs are responding with pre-certified safety architectures that reduce customer validation burden but lock in premium pricing tiers.
After-sales service unbundling is compressing traditional maintenance contract structures. Packagers are separating spare parts procurement from technical support, sourcing drives and sensors directly from component vendors while retaining OEMs for specialized mechatronics troubleshooting. This bifurcation is most pronounced in North American beverage operations with in-house automation teams capable of self-servicing servo systems.
Flexible End-Load Cartoner Market Segmentation
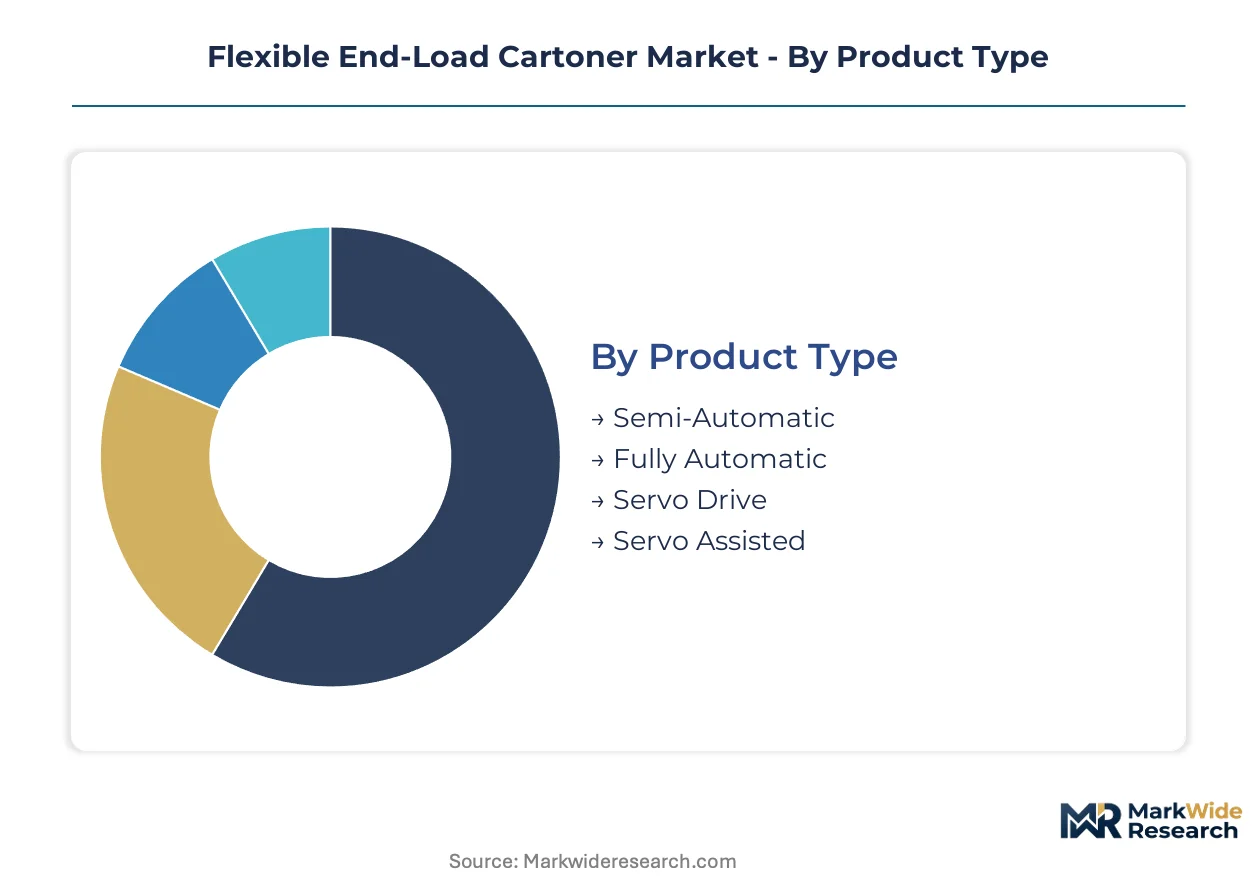
Segmentation in flexible end-load cartoners reveals how capital allocation priorities diverge between pharmaceutical validation requirements and food-sector throughput economics. Machine builders configure servo architectures, safety systems, and material specifications differently across each slice, creating distinct margin profiles and aftermarket service opportunities.
Product Type:
Fully automatic and servo drive configurations command the widest margin spreads, while semi-automatic systems compete primarily on capital recovery timelines for smaller packagers.
- Fully Automatic:These systems integrate carton forming, loading, and sealing into continuous motion architectures achieving 300-500 cartons per minute. Demand concentrates at multinational food and beverage producers in Germany and the United States where labor substitution economics justify premium capital outlay.
- Servo Drive:Programmable motion profiles replace mechanical camshafts, enabling format changeovers without tooling swaps. Pharmaceutical packagers in Italy and Switzerland specify these for validated serialization lines requiring full audit trails under FDA and EMA mandates.
- Semi-Automatic:Operator-fed loading stations suit contract packagers with volatile SKU mixes and sub-100 cartons per minute volumes.
- Servo Assisted:Hybrid configurations deploy servos on critical axes while retaining pneumatics for flap folding, bridging cost and precision for mid-tier dairy operations.
The dominant share belongs to Fully Automatic, while Servo Drive is closing the gap fastest.
Technology:
Technology selection tracks the speed-precision tradeoff, with electric architectures displacing legacy mechanical systems across all but the lowest-volume installations.
- Electric:All-servo architectures deliver programmable motion with 0.1mm repeatability for pharmaceutical blister loading. German OEMs source linear motors and drives from captive supply chains to shield margin from rare-earth price volatility.
- Hybrid:Pneumatic actuators handle flap folding while electric servos manage product placement, cutting capital outlay 15-25% versus all-electric alternatives. European dairy and bakery packagers pilot these configurations to balance reliability with format flexibility.
- Mechanical:Camshaft and linkage systems persist in emerging market food operations where uptime simplicity outweighs changeover speed.
- Pneumatic:Compressed-air actuation dominates legacy installations under 100 cartons per minute, though energy costs and maintenance intensity erode its position.
Electric architectures hold the revenue base, while Hybrid systems are expanding most quickly in mid-speed food applications.
Application:
Application segmentation maps directly to regulatory burden and material specification intensity, with pharmaceutical and food sectors driving divergent engineering priorities.
- Pharmaceuticals:FDA 21 CFR Part 11 and EU MDR compliance mandate integrated safety PLCs, stainless steel 316L contact surfaces, and serialized track-and-trace integration. Italian OEMs anchor this segment through cleanroom-compatible designs validated for export to regulated markets.
- Food & Beverage:Throughput pressure dominates, with ready-meal producers specifying 300+ cartons per minute and rapid format change. German supplier clusters around Stuttgart deliver commissioning support that shortens project timelines for pan-European brands.
- Cosmetics:Premium presentation requirements drive gentle handling systems for fragile glass and irregular shapes, with French and Italian packagers prioritizing aesthetic finish over raw speed.
- Personal Care:Moderate speed requirements and diverse packaging formats favor flexible servo configurations for wipes, cotton products, and oral care items.
Food & Beverage maintains the installed base lead, though Pharmaceuticals shows the steepest expansion trajectory on serialization-driven replacement cycles.
End User:
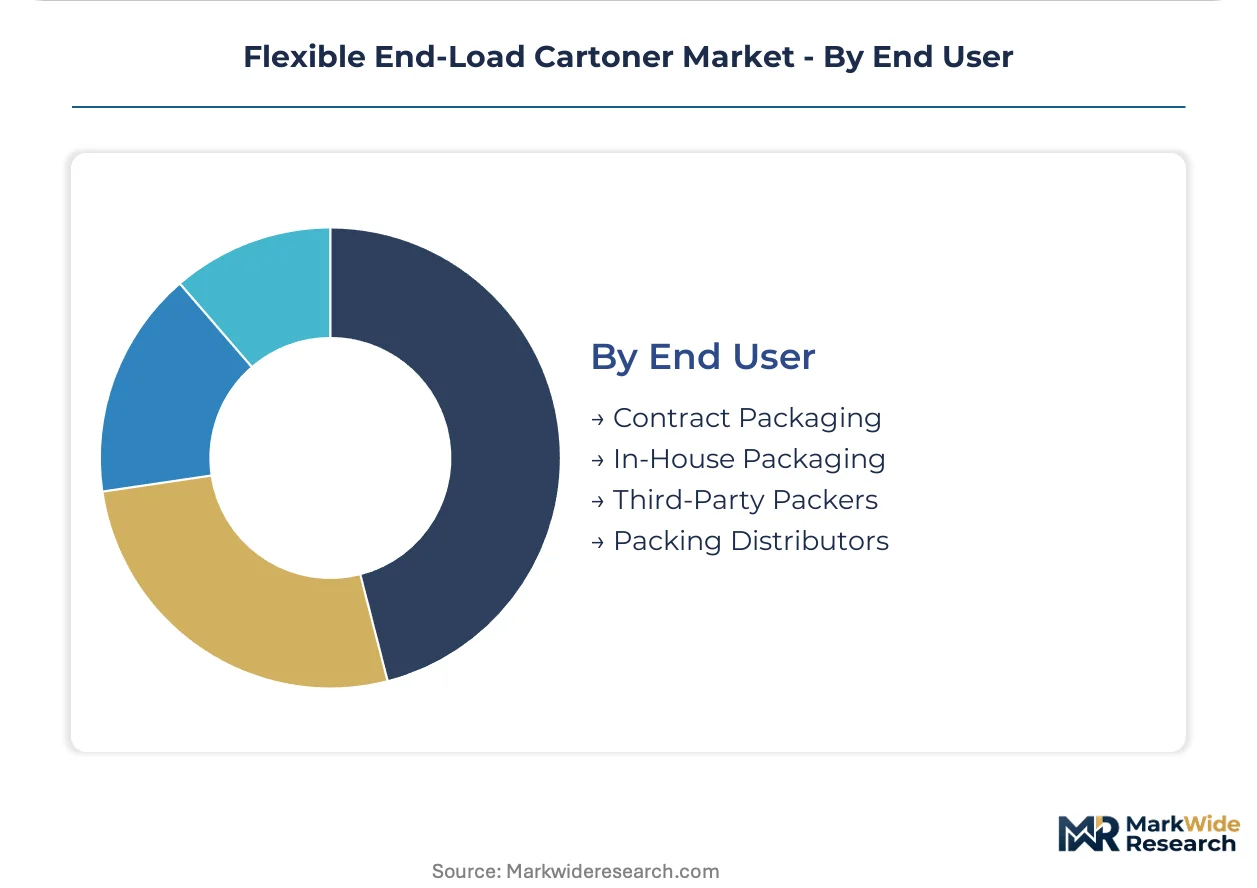
End user structure determines service contract economics and spare parts procurement patterns, with in-house operations and contract packagers diverging on technical self-sufficiency.
- In-House Packaging:Multinational food and pharmaceutical producers with captive automation teams separate spare parts procurement from technical support, sourcing drives and sensors directly from component vendors. North American beverage operations lead this unbundling trend.
- Contract Packaging:Third-party packagers demand turnkey solutions with bundled maintenance to offset mechatronics technician scarcity. These customers prioritize uptime guarantees over capital cost minimization.
- Third-Party Packers:Regional specialists serving fragmented local markets specify semi-automatic systems for SKU flexibility with limited engineering staff.
- Packing Distributors:Equipment resellers and integrators aggregate demand across smaller end users, concentrating procurement leverage for mid-speed hybrid configurations.
In-House Packaging commands the dominant revenue position, while Contract Packaging is gaining share fastest on outsourced manufacturing trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs command pricing premiums on validated pharmaceutical systems, while Indian fabricators compete on capital recovery timelines for emerging market food operations.
United States
FDA 21 CFR Part 11 serialization mandates and OSHA machine guarding standards drive pharmaceutical and food-sector upgrade cycles. The FDA enforces electronic records and audit trail requirements that elevate engineering costs for compliant servo-driven lines. Chicago and New Jersey pharmaceutical corridors concentrate demand for stainless steel 316L systems with integrated safety PLCs.
Germany
EU Machinery Directive 2006/42/EC safety integrity requirements and dense supplier engineering talent sustain export competitiveness. The Stuttgart and Dresden industrial clusters anchor Bosch Packaging and Syntegon Technology operations serving pan-European food brands. German OEMs leverage captive training academies to offset mechatronics technician scarcity.
Italy
Pharmaceutical-grade cleanroom-compatible designs and EMA validation protocols position Italian builders for regulated export markets. Marchesini Group anchors Emilia-Romagna manufacturing scale for blister-to-carton integration. Italian OEMs concentrate in Bologna and Modena corridors serving Swiss and German pharmaceutical multinationals.
India
CDSCO serialization deadlines and export-oriented generic drug production create first-time demand for validated systems in Ahmedabad and Hyderabad. The country's national pharmaceutical regulator enforces track-and-trace mandates that force upgrades of legacy mechanical lines. Gujarat and Telangana industrial zones attract German and Italian OEMs seeking local assembly partnerships.
Switzerland
Swissmedic pharmaceutical oversight and precision manufacturing heritage sustain premium positioning for high-repeatability servo architectures. Basel and Zurich pharmaceutical corridors demand 0.1mm placement accuracy for fragile blister loading. Swiss packagers specify integrated safety PLCs that satisfy both EU and FDA export requirements.
Flexible End-Load Cartoner Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the flexible end-load cartoner market. The supplier base concentrates around German engineering-intensive OEMs and Italian pharmaceutical specialists, with mid-tier Asian fabricators competing on capital recovery timelines. Three archetypes dominate: vertically integrated motion control developers, cleanroom-validated pharmaceutical builders, and hybrid pneumatic-electric system integrators. Competitive moves center on M&A for mechatronics talent acquisition and geographic expansion into Indian pharmaceutical corridors.
Among Germany-based engineering-intensive OEMs, Bosch Packaging GmbH and Syntegon Technology GmbH exemplify the integrated motion control archetype, while Marchesini Group S.p.A. anchors Italian pharmaceutical-grade specialization. These three entities occupy positions that reflect divergent strategic bets on servo drive depth versus cleanroom validation heritage.
| Leading Market Players |
|---|
| Bosch Packaging |
| Bradman Lake Group |
| LEAD Packaging Technologies |
| Unista |
| KHS |
| 3 SL Pactec |
| Syntegon Technology |
| Marchesini Group |
| AFA Systems |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 validation tiers gate both supplier qualification and price differentiation simultaneously, with pharmaceutical-grade servo systems commanding substantial premiums over food-sector mechanical alternatives while excluding uncertified fabricators from regulated procurement pools. This dual-gating mechanism concentrates margin capture among German and Italian OEMs with pre-certified safety architectures.
Pricing Analysis
German-built pharmaceutical systems trade at 40-60% premiums over Indian-assembled food-grade alternatives, with price differentiation anchored in CE marking depth and stainless steel 316L specification grade. Three-tier pricing structure across premium, standard, and economy levels separates validated serialization lines from mid-speed dairy hybrids and pneumatic-mechanical legacy units. Pricing pressure stems from rare-earth magnet cost volatility squeezing servo motor margins. Contract packagers exhibit highest price sensitivity due to capital recovery timelines, while multinational pharmaceutical producers prioritize compliance over procurement cost.
Supply Chain Analysis
Six-month lead times for high-precision linear motors from European drive vendors have forced OEMs to hold elevated safety stock of servo controllers and motion encoders. Component sourcing draws from Germany for safety PLCs, China for processed rare-earth magnets, and Japan for precision bearings. Single-source vulnerability concentrates in linear motor supply where two European vendors dominate pharmaceutical-grade specifications. Distribution runs through direct OEM sales for large pharmaceutical accounts and machinery distributors serving mid-tier food producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service unbundling is accelerating faster than hardware shipments, with spare parts procurement and digital commissioning support now representing recurring revenue streams that outpace unit sales growth in mature European markets.
For Market Incumbents: Secure captive mechatronics training pipelines to offset technician scarcity threatening commissioning throughput. Anchor position through backward integration into motion control hardware, reducing exposure to drive vendor lead time volatility. Defend against Indian fabricators by embedding digital twin capabilities that shorten customer startup timelines. For New Entrants and Emerging Players: Lead with hybrid pneumatic-electric architectures targeting mid-speed European dairy operations underserved by full-servo pricing. Concentrate initial deployment in Indian pharmaceutical corridors where CDSCO serialization deadlines are forcing first-time automation investments. Pursue local assembly partnerships with Gujarat-based fabricators to bypass import duty structures. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across servo drive component manufacturing as rare-earth processing scales and safety PLC platforms commoditize. Five-to-ten year viability favors acquirers of mechatronics talent pools over pure hardware assemblers. Monitor German OEM training academy expansion rates as inflection signal for sustainable engineering throughput.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motion Control | Bosch Packaging and Syntegon Technology shield margins from rare-earth price volatility through captive drive production. |
| Digital Twin Commissioning Platform | Virtual servo tuning cuts physical startup time for multi-axis pharmaceutical loader configurations. |
| Local Assembly Partnership in India | Gujarat and Telangana industrial zones enable German and Italian OEMs to satisfy CDSCO localization preferences. |
| Mechatronics Training Academy Expansion | Bosch Packaging sustains engineering throughput across export markets through captive technician certification programs. |
| Hybrid Pneumatic-Electric System Launch | Mid-speed dairy configurations bridge cost-precision gap for European bakery producers. |
Research Methodology
Initial hypotheses were tested against primary input from packaging line engineers, pharmaceutical validation specialists, food sector procurement managers, and aftermarket service directors, and refined through secondary validation against EU Machinery Directive implementation guidance, FDA 21 CFR Part 11 compliance documentation, customs trade data for packaging machinery imports, and OEM technical specification sheets. Bottom-up unit economics triangulated against top-down industry spend estimates across the analysis window.
Variance decomposition across product type, technology architecture, application sector, and end-user structure informed segment-level growth trajectories throughout the forecast period. CAGRs were derived from installed base replacement cycles, serialization mandate deadlines, and servo adoption curves. Forecast inputs incorporated pharmaceutical track-and-trace regulatory timelines and food sector labor substitution economics.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11 and EU Machinery Directive enforcement; material policy shifts would require re-modeling. Rare-earth supply disruptions or extended producer responsibility framework expansions represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Burnisher Market
Packaging Equipment
Loose Fill Packaging Systems Market
Packaging Equipment
Volumetric Filing Lines Market
Packaging Equipment
Multihead Weighers Market
Packaging Equipment
Loading Spout Market
Packaging Equipment
Semi-Automatic and Manual Filling Equipment Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Bottle-Capping Equipment Market
Packaging Equipment
Flatbed Die Cutters Market
Packaging Equipment
Corrugated Equipment Market
Packaging Equipment
Beverage Packaging Equipment Market
Packaging Equipment
Refrigerated Display Cases Market
Packaging Equipment
Table Top Band Sealer Market
Packaging Equipment
Tray Loader Market
Packaging Equipment
Shrink Sleeve Labeling Equipment Market