
 Insulated Thermal Box Liners Market | 2026-2036
Insulated Thermal Box Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Thermal Box Liners Market Foresight
REACH compliance is recalibrating the cost-of-entry calculus for European suppliers of insulated thermal box liners, forcing reformulation of polyurethane-based foams and expanded polystyrene alternatives. Sealed Air Corporation leverages its global manufacturing footprint to navigate multi-jurisdictional chemical safety standards, while ACH Foam Technologies anchors its position through captive supply of EPS substrates. Polar Tech Industries, Inc. specializes in precision-cut foam configurations for pharmaceutical clients requiring validated cold-chain performance.
Insulated thermal box liners are engineered enclosures fabricated from expanded polystyrene, polyurethane foam, or multi-layer reflective composites, designed to maintain designated temperature ranges typically between 2°C and 8°C or frozen conditions for 48–96 hours during transit. Their primary purpose is to protect temperature-sensitive payloads from ambient thermal excursions in pharmaceutical distribution, meal-kit delivery, and precision electronics logistics. Foam liners dominate current volume due to established supply chains and lower unit costs, while vacuum insulated liners command premium positioning where extended duration or extreme temperature maintenance is required. Composite liners are gaining traction as converters blend recycled content with conventional substrates to meet sustainability procurement criteria from multinational pharmaceutical distributors.
The EPA governs chemical emissions from foam manufacturing facilities under the Clean Air Act, while FDA guidelines on pharmaceutical distribution validate liner performance for drug stability assurance. ISO 23412 for temperature-controlled transport containers shapes product testing protocols and international market access. Stakeholders must monitor evolving state-level extended producer responsibility laws in California and New York, as these will determine whether liner take-back obligations shift cost structures toward reusable or recyclable designs.
Market Dynamics
Pharmaceutical cold-chain validation requirements are compressing product development cycles and forcing converters to pre-qualify liner configurations against FDA and EMA stability guidelines before commercial release. This regulatory front-loading is redistributing competitive advantage toward manufacturers with in-house thermal testing laboratories and documented qualification protocols.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of high-GWP blowing agents is accelerating converter migration to pentane-based and water-blown polyurethane systems, expanding addressable demand for compliant liner suppliers.
- mRNA vaccine distribution:Ultra-cold storage requirements for temperature-sensitive biologics are extending validation periods and increasing specification stringency for multi-day thermal protection.
- German pharmaceutical clustering:Concentrated manufacturing in Rhine-Main and Upper Bavaria is driving localized liner procurement and dedicated cold-chain infrastructure investment.
Market Restraints
- Polystyrene feedstock volatility:Benzene price swings transmit directly to expanded polystyrene substrate costs, compressing converter margins on standard-duty liner contracts.
- REACH compliance timelines:ECHA substance evaluation windows for isocyanates and flame retardants are extending reformulation cycles and freezing product line extensions.
- Aerogel substitution threat:Thin-profile silica aerogel blankets are capturing premium pharmaceutical accounts requiring sub-2°C deviation tolerance over 120-hour durations.
Strategic Opportunities
- Indian cold-chain buildout:CDSCO pharmaceutical export requirements and FSSAI food safety mandates are creating first-mover openings for validated liner suppliers in Mumbai and Hyderabad corridors.
- Reusable liner systems:Reverse logistics platforms for meal-kit and precision electronics segments are displacing single-use EPS in high-frequency delivery routes.
- California EPR legislation:Extended producer responsibility frameworks are incentivizing recyclable PET-fiber composite designs that converters can position against foam incumbent alternatives.
Industry Challenges
- Thermal modeling talent scarcity:Computational fluid dynamics expertise for predictive cold-chain performance simulation is concentrated among a narrow specialist pool, elongating R&D hiring cycles.
- ISO 23412 certification backlog:Accredited laboratory capacity for temperature-controlled transport container validation is creating queue delays that stall product launches.
- Legacy ERP integration:Track-and-trace requirements for pharmaceutical serialization are forcing liner suppliers to retrofit manufacturing execution systems without disrupting just-in-time delivery commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Thermal Box Liners Market |
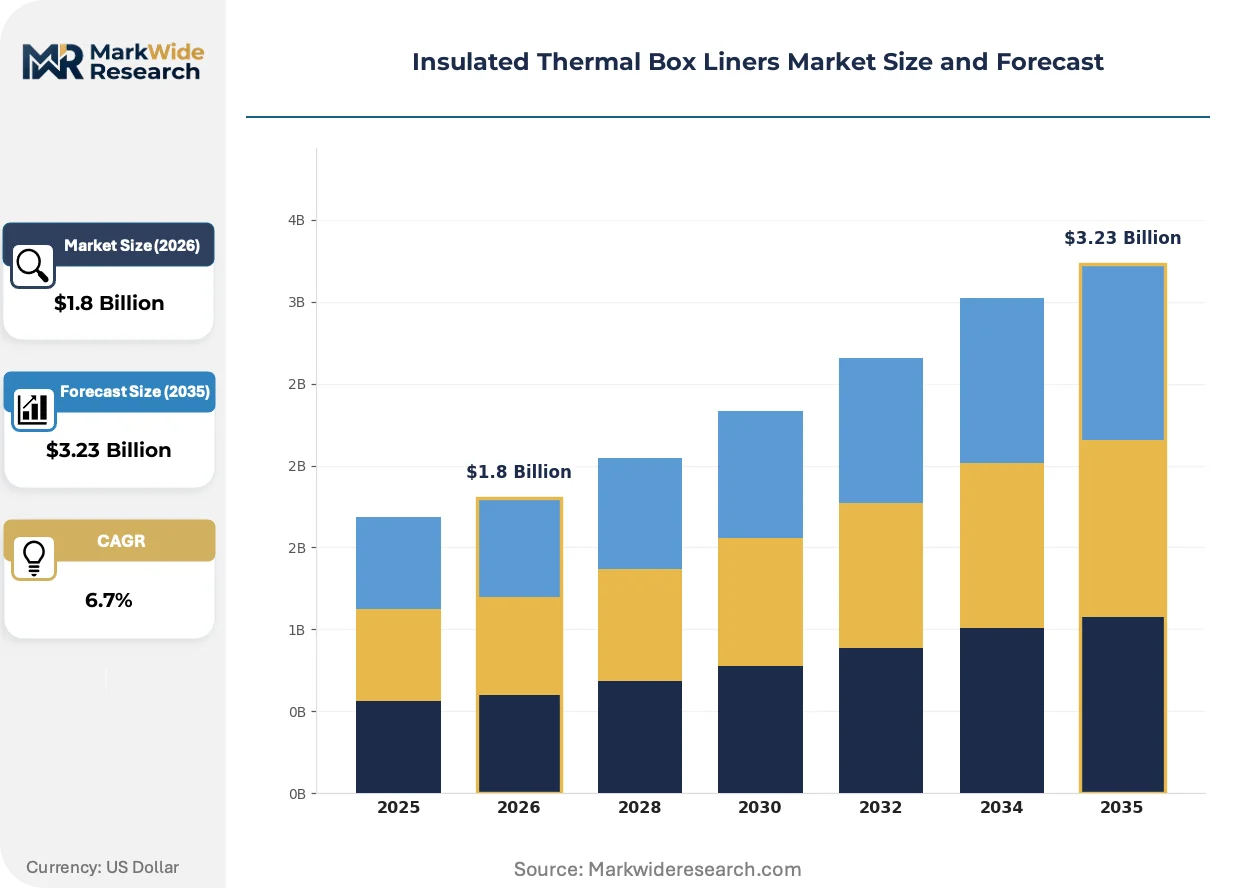
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Liners, Composite Liners, Reflective Liners, Vacuum Insulated Liners Material: EPS, Polyurethane, Mylar, Polypropylene End User: Pharmaceuticals, Food & Beverage, Electronics, Logistics Capacity: Small, Medium, Large, Custom |
| Companies Covered | Sealed Air Corporation, Uline Inc., ACH Foam Technologies, Insulated Products Corporation, Polar Tech Industries, Inc., Coldkeepers LLC, Great Pacific Packaging, Inc., Nortech Laboratories, Inc., PAC Worldwide, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Thermal Box Liners Market Shifts & Advancements
Vacuum insulation panel technology is compressing thermal protection into thinner profiles, while regulatory chemistry constraints are rewiring material selection criteria. Demand-side procurement patterns are simultaneously consolidating toward performance-guaranteed supply agreements.
Multi-layer metallized film composites with nano-porous silica cores are rewriting the performance-to-thickness ratio for pharmaceutical shippers. Large molecule distributors in Belgium and Switzerland are specifying these configurations for intercontinental lanes where dimensional weight penalties dominate freight economics. The technology is compressing competitive differentiation around validated duration claims rather than material origin.
REACH Annex XIV authorization requirements for diisocyanates are forcing polyurethane foam converters toward aliphatic formulations or alternative chemistries entirely. ECHA restriction proposals on expanded polystyrene microplastics are accelerating R&D investment in starch-based loose-fill and molded fiber substitutes. German packaging converters are responding with dual-track qualification programs that preserve existing capacity while building next-generation substrate expertise.
Performance-guaranteed contracting is displacing unit-price procurement in pharmaceutical verticals. Distributors now require temperature excursion liability transfer and automated documentation rather than standalone product supply. This shift is most visible in the Netherlands and Denmark, where centralized hospital procurement organizations are unbundling liner sourcing from third-party logistics arrangements and direct-awarding to validated manufacturers.
Insulated Thermal Box Liners Market Segmentation
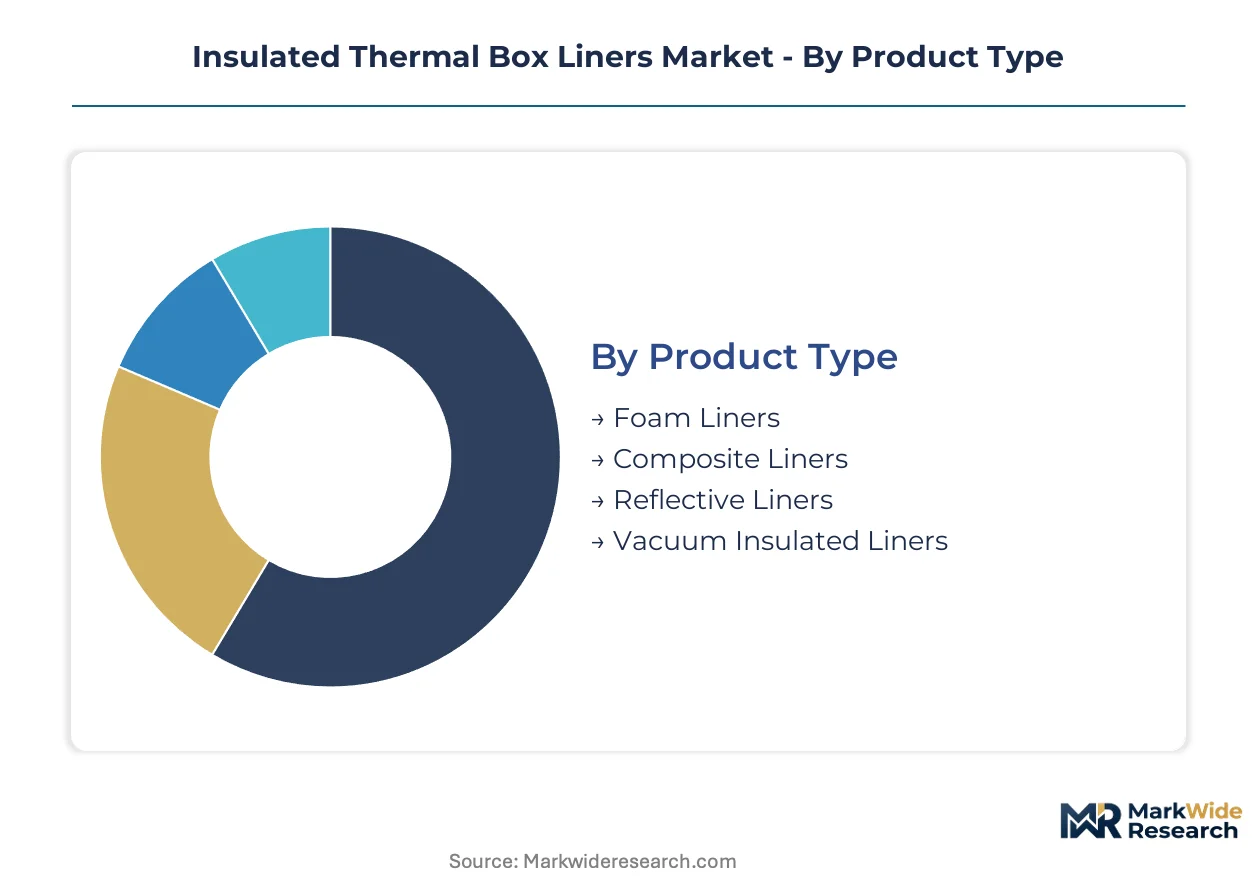
Converters configure insulated thermal box liners across four intersecting dimensions that determine cold-chain performance, regulatory compliance, and total cost of ownership. Material chemistry and liner architecture shape thermal duration claims, while end-use validation requirements and payload capacity dictate manufacturing scale economics.
Product Type:
Buyers select liner architecture based on required thermal duration, dimensional constraints, and disposal obligations under emerging extended producer responsibility frameworks.
- Foam Liners:Expanded polystyrene or polyurethane foam shells deliver 48–72 hour thermal protection at the lowest unit cost. Pharmaceutical distributors in Germany specify these for domestic vaccine lanes where reverse logistics infrastructure remains underdeveloped.
- Vacuum Insulated Liners:Nano-porous cores sealed within metallized barriers compress R-value into sub-20mm profiles. Swiss biologics shippers deploy these for intercontinental routes where dimensional weight penalties dominate freight economics and 120-hour duration is mandatory.
- Composite Liners:Multi-layer substrates blending recycled PET fibers with conventional insulation meet sustainability procurement criteria from multinational pharmaceutical distributors.
- Reflective Liners:Metallized film barriers with air-gap insulation provide lightweight thermal protection for meal-kit delivery segments prioritizing outbound freight efficiency over extended duration.
Foam liners lead on scale; vacuum insulated liners lead on momentum.
Material:
Feedstock selection now hinges on REACH compliance timelines and F-Gas Regulation phase-down schedules rather than purely thermal performance metrics.
- EPS:Molded expanded polystyrene dominates volume through established supply chains and processing familiarity. Benzene price volatility transmits directly to converter margins, compressing profitability on standard-duty contracts.
- Polyurethane:Water-blown and pentane-based formulations are displacing HFC-blown systems under EU F-Gas Regulation mandates. Aliphatic isocyanate variants are emerging to bypass REACH Annex XIV authorization requirements.
- Mylar:Metallized polyethylene terephthalate films serve as barrier layers in composite and reflective configurations.
- Polypropylene:Injection-molded or fiber-based polypropylene substrates offer recyclability advantages in jurisdictions with stringent packaging waste directives.
Polyurethane is gaining share fastest; EPS retains volume leadership.
End User:
Validation requirements and liability frameworks vary sharply across verticals, forcing converters to maintain parallel qualification protocols.
- Pharmaceuticals:FDA and EMA stability guidelines mandate documented thermal performance for drug distribution. Pre-qualified liner configurations command premium positioning against unvalidated alternatives.
- Food & Beverage:FSSAI and state-level cold-chain mandates in India are creating first-mover openings for validated suppliers in Mumbai and Hyderabad corridors.
- Electronics:Precision components require protection against thermal shock during transit.
- Logistics:Third-party cold-chain operators specify interchangeable liner systems across multi-client networks.
Pharmaceuticals leads on specification stringency; food and beverage climbs the fastest.
Capacity:
Payload volume determines manufacturing automation feasibility and inventory carrying costs for converter operations.
- Small:Precision-cut configurations for clinical trial samples and personalized medicine shipments.
- Medium:Standardized dimensions for regional pharmaceutical distribution and meal-kit subscription boxes.
- Large:Pallet-scale thermal enclosures for bulk biologics and international vaccine consignments.
- Custom:Engineered-to-order profiles for irregular payload geometries or extreme duration requirements.
Medium capacity leads on shipment volume; custom configurations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cold-chain engineering talent clusters in German pharmaceutical manufacturing hubs, Swiss precision logistics corridors, and Indian export-processing zones. These workforce concentrations anchor regional competitive advantages in validated thermal packaging design and regulatory compliance execution.
Germany
Rhine-Main and Upper Bavaria pharmaceutical manufacturing clusters drive liner procurement for domestic vaccine distribution and biologics export. The EU F-Gas Regulation accelerates converter migration to pentane-blown polyurethane systems. Bavarian packaging converters operate dual-track qualification programs preserving existing EPS capacity while building next-generation substrate expertise.
Switzerland
Large-molecule biologics distributors in Basel and Geneva specify vacuum-insulated configurations for intercontinental lanes. Swissmedic validation requirements compress product development cycles toward pre-qualified liner architectures. Zürich-based cold-chain operators consolidate procurement through performance-guaranteed contracting with documented thermal excursion liability transfer.
United States
FDA pharmaceutical distribution guidelines and state-level extended producer responsibility laws in California and New York reshape liner design criteria. Greater Boston and Research Triangle Park biotech clusters demand precision-cut foam configurations for clinical trial sample shipments. EPA Clean Air Act enforcement governs chemical emissions from domestic foam manufacturing facilities.
India
CDSCO pharmaceutical export requirements and FSSAI food safety mandates create first-mover openings in Mumbai and Hyderabad corridors. Domestic cold-chain infrastructure investment accelerates validated liner demand for temperature-sensitive agricultural exports. Maharashtra and Telangana packaging converters build qualification protocols against WHO prequalification standards.
Netherlands
Centralized hospital procurement organizations in Amsterdam-Rotterdam unbundle liner sourcing from third-party logistics arrangements. REACH compliance timelines for isocyanates extend reformulation cycles among Dutch polyurethane converters. Rotterdam port logistics operators specify interchangeable liner systems across multi-client pharmaceutical distribution networks.
Insulated Thermal Box Liners Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: multinational material science conglomerates with global manufacturing footprints, regional foam fabricators with captive substrate supply, and precision engineering boutiques serving validated pharmaceutical segments. Consolidation pressure intensifies as performance-guaranteed contracting displaces unit-price procurement. Geographic expansion and technology licensing represent dominant competitive moves for scale players seeking EMA and FDA pre-qualification credentials.
Within the diversified conglomerate tier, Sealed Air Corporation occupies a position exemplifying multi-jurisdictional chemical safety navigation. ACH Foam Technologies anchors the regional fabricator archetype through captive EPS substrate supply. Polar Tech Industries, Inc. represents the precision specialist segment with engineered configurations for pharmaceutical cold-chain validation. These three company structures illustrate competitive positioning across scale, supply control, and technical specialization vectors.
| Leading Market Players |
|---|
| Sealed Air Corporation |
| Uline Inc. |
| ACH Foam Technologies |
| Insulated Products Corporation |
| Polar Tech Industries, Inc. |
| Coldkeepers LLC |
| Great Pacific Packaging, Inc. |
| Nortech Laboratories, Inc. |
| PAC Worldwide, Inc. |
| Others |
Supply & Pricing Matrix
Centralized hospital procurement organizations in the Netherlands and Denmark anchor demand concentration, pushing pharmaceutical distributors toward performance-guaranteed contracting with embedded temperature excursion liability transfer rather than transactional unit-price purchasing.
Pricing Analysis
Service bundling separates validated liner supply from standalone product sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 23412 certification grade and documented thermal duration claims. Cost compression in standard-duty EPS contracts is intensifying because benzene feedstock volatility transmits directly to converter margins. Meal-kit delivery operators exhibit highest price sensitivity, while Swiss biologics shippers prioritize validated performance over unit cost.
Supply Chain Analysis
EMA and FDA pre-qualification requirements gate market access, concentrating qualified converter capacity in Germany, Switzerland, and the United States. Supply chains draw from benzene derivatives for EPS substrates, aliphatic isocyanates for polyurethane formulations, and metallized PET films for barrier layers. Single-source vulnerability runs through specialized nano-porous silica core suppliers for vacuum insulation panels. Distribution feeds from converter direct sales to pharmaceutical distributors and third-party logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical cold-chain logistics operates as a stable compounder, with biologics distribution expansion and vaccine validation requirements delivering steady specification upgrades and recurring procurement cycles.
For Market Incumbents: Cement market position through captive supply of REACH-compliant polyurethane substrates and in-house thermal testing laboratory accreditation. Aerogel substitution threats in premium pharmaceutical accounts demand accelerated R&D in thin-profile composite alternatives. Capacity addition in Bavaria preserves proximity to Rhine-Main pharmaceutical clusters while building next-generation substrate expertise. For New Entrants and Emerging Players: E-commerce direct procurement channels offer lower customer acquisition costs for meal-kit and precision electronics segments. Indian cold-chain buildout in Mumbai and Hyderabad corridors represents the most penetrable geography, with CDSCO export requirements creating first-mover validation openings. Position reusable liner systems with reverse logistics platforms against single-use EPS incumbents. For Investors and Strategic Acquirers: Packaging conglomerates with pharmaceutical verticals are the most active acquirer in this space, seeking EMA and FDA pre-qualification credentials through technology licensing. Five-to-ten year viability rests on converter capabilities spanning regulatory compliance execution and thermal modeling talent retention. Target acquisition profile centers on precision engineering boutiques with documented qualification protocols and in-house CFD simulation capacity. Watch for California and New York extended producer responsibility implementation as inflection signal for recyclable composite demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Migration | Aliphatic isocyanate variants bypass ECHA Annex XIV authorization timelines for polyurethane converters. |
| In-House Thermal Testing Laboratory Buildout | FDA and EMA pre-qualification credentials compress pharmaceutical customer acquisition cycles. |
| Reusable Liner Reverse Logistics Platform | California EPR frameworks incentivize recyclable PET-fiber composite designs displacing single-use EPS. |
| Vacuum Insulation Panel Technology Licensing | Swiss biologics shippers specify sub-20mm profiles for intercontinental dimensional weight optimization. |
| Indian Cold-Chain Infrastructure Partnership | CDSCO export requirements and FSSAI mandates create validated liner demand in Mumbai-Hyderabad corridors. |
Research Methodology
Direct dialogue with pharmaceutical supply chain directors, cold-chain logistics operators, packaging converter plant managers, and thermal packaging R&D heads grounded qualitative findings. Secondary validation drew from ECHA substance evaluation databases, FDA pharmaceutical distribution guidelines, EU F-Gas Regulation implementation reports, and ISO 23412 certification records. Bottom-up shipment data triangulated against top-down pharmaceutical cold-chain infrastructure investment flows.
Bottom-up modeling segmented volume and value across material chemistry, liner architecture, end-use validation tier, and payload capacity class. Top-down verification cross-checked against pharmaceutical manufacturing cluster expansion patterns and regulatory compliance cost trajectories. CAGRs derived from regression analysis of historical liner procurement against biologics pipeline expansion and vaccine distribution infrastructure deployment.
The model assumes a particular technology adoption path; alternative pathways for silica aerogel blanket substitution would alter the outlook. Forecasts reflect assumptions on REACH enforcement intensity and F-Gas Regulation phase-down adherence. A model refresh is warranted upon material change in EMA stability guideline revision timelines or California extended producer responsibility implementation scope.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Cash Management Supplies Packaging Market
Packaging Materials
Organic Substrate Packaging Material Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Brightness Enhancement Films Market
Packaging Materials
Transit Packaging Market
Packaging Materials
Liquid Encapsulation Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Myanmar Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Asia-Pacific Airless Packaging Market
Packaging Materials
Tertiary Packaging Market