
 Cutterbox Films Market | 2026-2036
Cutterbox Films Market Size, Share, and Industry Trends Forecast 2026-2036
Cutterbox Films Market Outlook
A capital-intensity divergence between integrated resin producers and downstream converters is reorganizing competitive tiers in the Cutterbox Films Market. Berry Global leverages captive polypropylene supply chains across North American manufacturing corridors. Amcor anchors its position through R&D intensity in barrier coating technologies for food-grade applications. Sealed Air differentiates via automated dispensing equipment paired with film substrates.
Cutterbox Films are precision-slit polymer webs, typically 50 to 150 microns thick, supplied in boxed rolls for automated or manual dispensing in wrapping, sealing, and surface protection operations. Polypropylene variants dominate volume due to balanced clarity and seal strength, while BOPP grades command margin pools in high-clarity decorative laminating. Food Industry end users represent the most structurally entrenched demand segment, though Pharmaceutical applications are expanding fastest as barrier specifications tighten.
EPA regulations on volatile organic compound emissions from adhesive laminating processes constrain coating line configurations in the United States. REACH compliance in Europe mandates full substance disclosure across PVC and polyethylene formulations, elevating documentation costs for exporters. FDA food contact notifications govern polymer selection for direct food applications, creating a dual-track compliance burden. Stakeholders must monitor evolving extended producer responsibility frameworks that threaten to shift end-of-life collection costs upstream to film manufacturers.
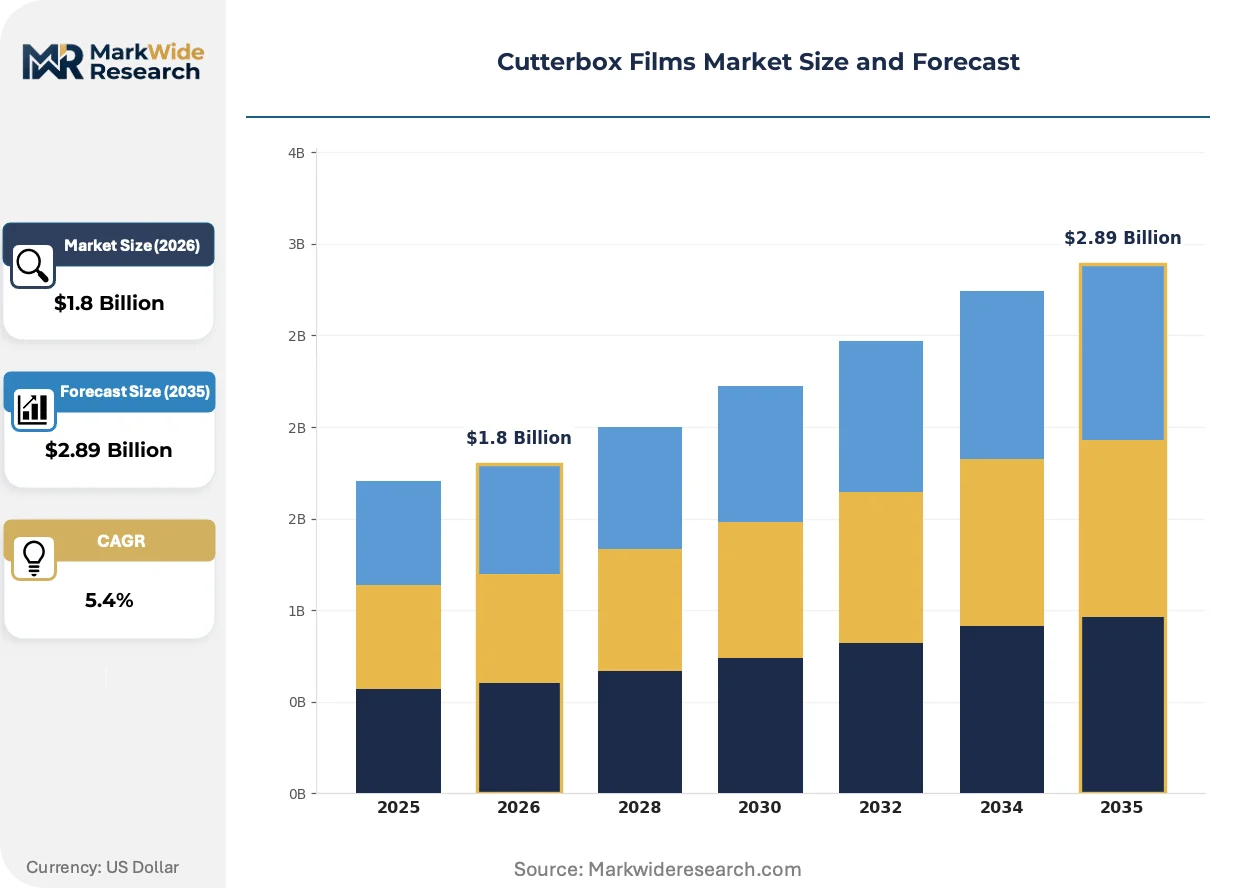
Market Dynamics
Europe's REACH regulation on chemical safety is forcing a wholesale reformulation of cutterbox film substrates, as converters face mandatory substance disclosure across PVC and polyethylene supply chains. This compliance burden is accelerating consolidation among smaller compounders unable to absorb documentation costs.
Growth Catalysts
- Flexible packaging adoption:Food manufacturers across Germany, France, and Italy are replacing rigid containers with precision-slit polymer webs for portion-controlled wrapping applications.
- REACH-driven material innovation:ECHA's expanded candidate list is compelling resin suppliers to develop phthalate-free plasticizers for food-contact grades.
- Barrier coating advances:SiOx and AlOx deposition technologies are extending shelf life in modified-atmosphere packaging for fresh protein segments.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics in Rotterdam and Antwerp create margin compression for non-integrated converters.
- Coating line capital intensity:Vacuum metallization and plasma-enhanced chemical vapor deposition equipment requires seven-figure euro outlays with extended payback periods.
- Mono-material substitution threat:Paper-based barrier boards from Nordic pulp suppliers are capturing premium chilled ready-meal applications.
Strategic Opportunities
- Pharmaceutical serialization mandates:EU Falsified Medicines Directive compliance is creating demand for tamper-evident cutterbox films with integrated track-and-trace functionality.
- Central European converting clusters:Poland and Czech Republic offer labor cost arbitrage for German-brand owners seeking nearshored supply.
- Digital print compatibility:Water-based ink adhesion on corona-treated BOPP is enabling short-run customization for craft food brands.
Industry Challenges
- Multilayer delamination expertise:Adhesive laminating technicians with solventless PUR experience command premium wages in the Rhine-Ruhr industrial zone.
- FDA dual-track compliance:Exporters to the United States must maintain parallel formulation databases to satisfy food contact notification requirements distinct from EFSA evaluations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cutterbox Films Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.89 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Film Type: Polypropylene, Polyethylene, BOPP, PVC Thickness: 50 Micron, 75 Micron, 100 Micron, 150 Micron Application: Packaging, Decorative, Adhesive, Laminating End User: Food Industry, Electronics, Pharmaceutical, Cosmetics |
| Companies Covered | Berry Global, Amcor, Anchor Packaging, Ajover S.A.S., The Griff Network, Sealed Air, Innovia Films, Taghleef Industries, Treofan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cutterbox Films Market Strategic Shifts
Digitalization of converting operations is compressing order-to-delivery cycles while enabling mass customization at unit economics previously reserved for long runs. Three developments are restructuring competitive advantage.
Water-based barrier coatings are decomposing the historical dominance of solvent-based acrylics in high-humidity applications. Mid-sized Italian converters serving Parma's cured meat cluster are adopting these formulations to preempt EPA-equivalent emission restrictions. The technology is decomposing incumbent coating houses' volume-based pricing power by enabling in-house application at smaller scale.
EU Green Deal packaging regulations are mandating minimum recycled content thresholds for plastic films by 2030. EFSA's evolving safety opinions on post-consumer recyclate in food contact are forcing brand owners to secure mass-balance certified feedstock ahead of rule enforcement. German retail chains are responding by specifying ISCC PLUS certification in procurement tenders.
Consolidation of European retail buying power is compressing supplier margins and extending payment terms. Discounters Aldi and Lidl now dictate film specifications across their private-label networks, displacing converter-direct relationships with national brands. This concentration is most pronounced in the Netherlands and Belgium, where centralized distribution hubs serve cross-border store networks.
Cutterbox Films Market Segmentation
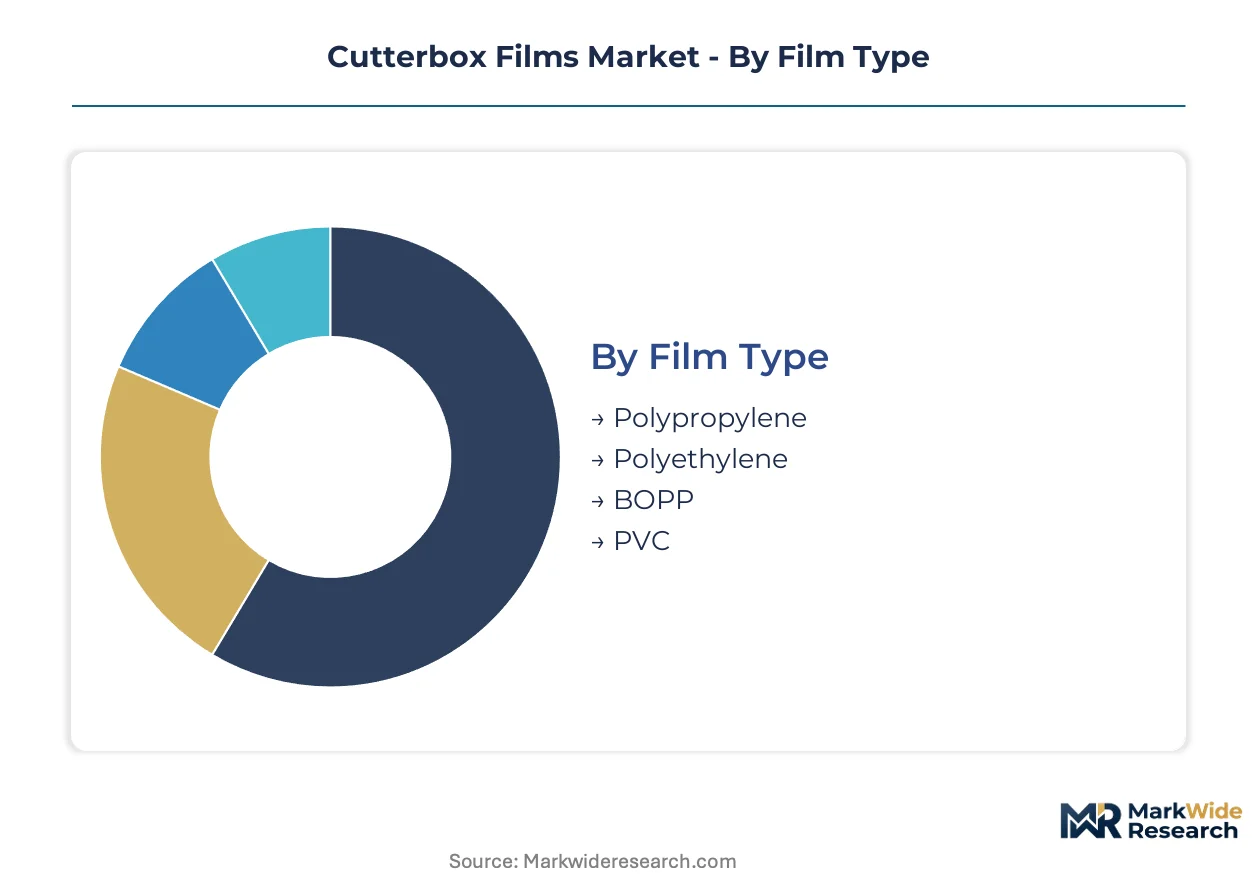
Cutterbox film procurement patterns diverge sharply by segment, with food-grade specifications driving standardization while pharmaceutical and electronics applications demand customized thickness and barrier configurations. Understanding these segment boundaries clarifies where converters can leverage scale economies versus where specialist positioning commands premium pricing.
Film Type:
Polypropylene variants dominate domestic consumption across German and Italian converting clusters, while BOPP and specialty polyethylene grades anchor export-oriented production from Benelux ports serving North African and Middle Eastern distributors.
- Polypropylene:Balanced clarity and seal strength make this the workhorse substrate for portion-controlled food wrapping. Demand concentrates in Germany's Rhine-Ruhr corridor, where automated dispensing equipment at meat processing facilities requires consistent slit-width tolerance.
- BOPP:Biaxially oriented grades deliver the optical clarity required for decorative laminating in premium confectionery. Italian converters around Bologna export these films to North African markets, though ECHA's expanded candidate list is forcing reformulation of slip additives.
- Polyethylene:LDPE and LLDPE variants serve chilled ready-meal applications requiring puncture resistance.
- PVC:Remains entrenched in pharmaceutical blister pack formats despite REACH-driven substitution pressure.
Polypropylene commands the established base. The steepest expansion runs through BOPP as barrier coating advances unlock modified-atmosphere protein packaging.
Thickness:
Mid-gauge specifications concentrate volume in high-throughput food operations, while thin-gauge precision slitting serves electronics and cosmetic segments where material yield per roll directly impacts unit economics.
- 50 Micron:Ultra-thin precision webs minimize material consumption in electronics surface protection and cosmetic sampler wrapping. German automotive component suppliers specify this gauge for automated dispensing lines at Stuttgart-area assembly plants.
- 100 Micron:Structural rigidity suits heavy-duty pallet wrapping and industrial adhesive applications. French logistics operators around Lyon have standardized on this thickness for automated stretch-wrapping systems.
- 75 Micron:Balances cost and performance for standard foodservice cling film.
- 150 Micron:Reserved for specialty laminating and protective masking in construction.
100 Micron specifications anchor current procurement volumes. 50 Micron formats are climbing the fastest as electronics manufacturers reduce packaging mass.
Application:
Packaging applications generate predictable recurring demand through retail supply chains, while laminating and adhesive segments expose converters to project-based volatility in industrial manufacturing cycles.
- Packaging:Modified-atmosphere and vacuum skin formats dominate fresh protein and ready-meal segments. Italian cured meat producers in Parma specify SiOx-coated films to extend shelf life without preservatives.
- Decorative:High-clarity BOPP enables premium confectionery and gift wrap presentation. Belgian chocolate brands source these films through specialized converters in Antwerp's port zone.
- Adhesive:Pressure-sensitive tape substrates serve logistics and construction sectors.
- Laminating:Multi-layer constructions combine barrier and aesthetic functions for specialty food.
Packaging commands the established base. Decorative applications are gaining share fastest as craft food brands invest in shelf differentiation.
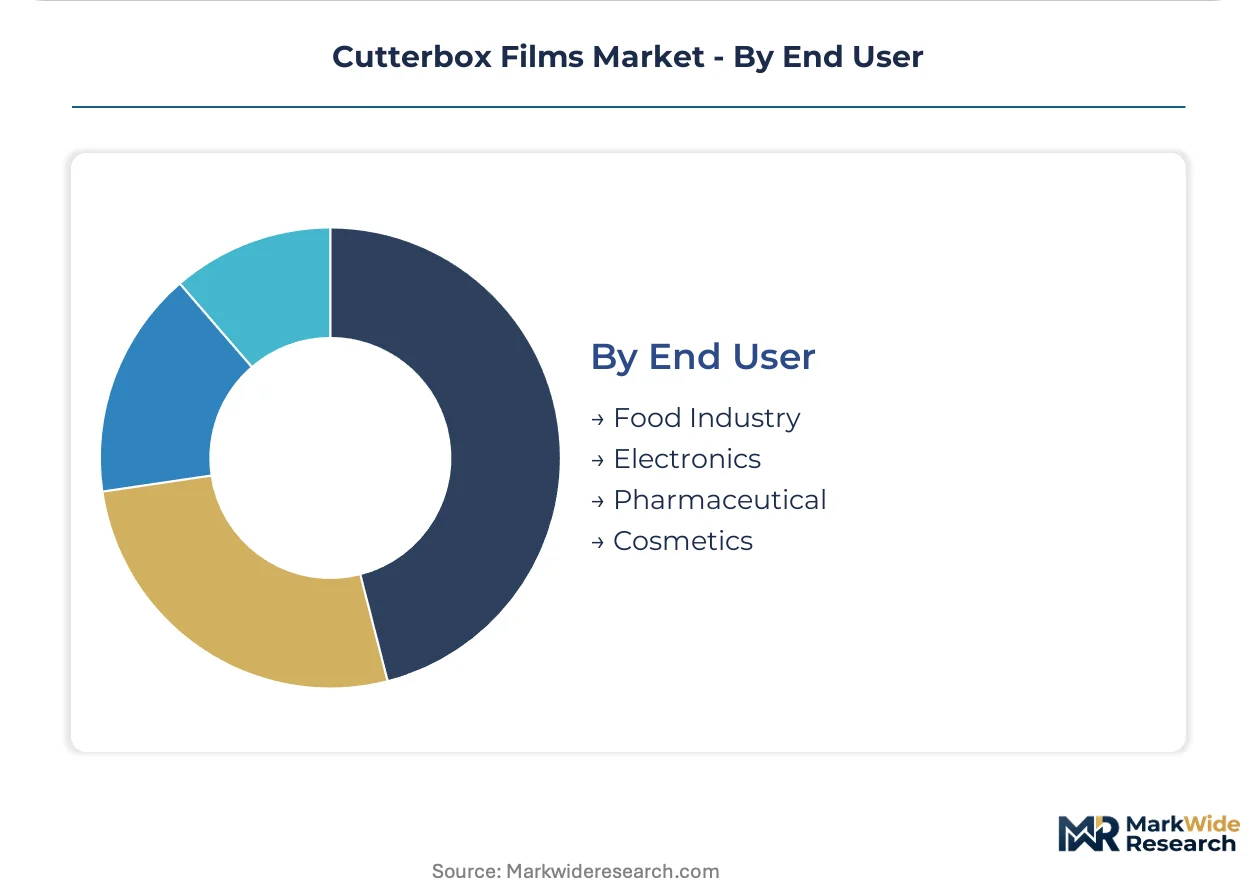
End User:
Food industry procurement runs through centralized retail buying offices, while pharmaceutical and electronics demand channels through qualified supplier programs with audit-intensive onboarding.
- Food Industry:Discounters Aldi and Lidl now dictate specifications across private-label networks, displacing converter-direct relationships. German retail chains increasingly require ISCC PLUS certification ahead of EU Green Deal enforcement.
- Pharmaceutical:EU Falsified Medicines Directive compliance is creating demand for tamper-evident formats with integrated track-and-trace. Irish contract manufacturers serving continental European markets are consolidating supplier bases to reduce audit burden.
- Electronics:Cleanroom-compatible static-dissipative films protect components during assembly.
- Cosmetics:Premium brands specify high-clarity wraps for sampler and travel-size formats.
Food Industry commands the established base. Pharmaceutical represents the fastest-growing trajectory as barrier specifications tighten and serialization mandates expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German converters command premium pricing power over Mediterranean suppliers due to REACH-compliant certification and automated slitting capabilities, while Polish and Czech producers compete on labor arbitrage for standard food-service grades.
Germany
Modified-atmosphere packaging for fresh protein and automated dispensing at meat processing facilities drive demand. ECHA's expanded candidate list mandates phthalate-free plasticizers in food-contact grades. Rhine-Ruhr corridor converters supply precision-slit webs to Central European distribution networks.
Italy
Parma's cured meat cluster specifies SiOx-coated films for shelf-life extension without preservatives. EU Green Deal packaging regulations push brand owners toward mass-balance certified feedstock. Bologna-area exporters ship high-clarity BOPP grades to North African markets.
France
Logistics operators around Lyon standardize on 100-micron films for automated stretch-wrapping systems. EFSA safety opinions on post-consumer recyclate in food contact shape procurement criteria. Paris basin retail buying offices consolidate specifications for private-label networks.
Poland
German-brand owners nearshore production to exploit labor cost differentials in converting operations. REACH documentation costs disadvantage smaller domestic compounders. Warsaw and Łódź industrial zones attract investment in slitting and rewinding capacity.
Belgium
Antwerp port-zone converters serve Belgian chocolate brands with decorative laminating films. Aldi and Lidl centralized procurement dictates specifications across Benelux store networks. Vacuum metallization equipment clusters near petrochemical feedstock terminals.
Cutterbox Films Market Competitive Environment
Concentration sits with integrated resin producers and specialized coating houses that control barrier technology IP. Three archetypes define competitive positioning: multinational packaging conglomerates with captive polymer supply, mid-sized European converters with regional brand relationships, and niche specialists in pharmaceutical-grade certification. M&A activity targets coating-line assets and ISCC PLUS certification capabilities.
Within the multinational tier, Berry Global exemplifies backward integration into polypropylene supply chains, while Amcor anchors positioning through R&D intensity in barrier formulations. Sealed Air occupies a distinct position pairing automated dispensing equipment with film substrates. These three represent divergent strategic bets on whether competitive advantage derives from resin economics, coating innovation, or equipment-film bundling.
| Leading Market Players |
|---|
| Berry Global |
| Amcor |
| Anchor Packaging |
| Ajover S.A.S. |
| The Griff Network |
| Sealed Air |
| Innovia Films |
| Taghleef Industries |
| Treofan |
| Others |
Value Chain & Pricing Dynamics
ISCC PLUS certification gates supplier qualification and price differentiation simultaneously, as German retail chains now mandate mass-balance certified feedstock ahead of EU Green Deal enforcement. This dual function compresses margins for uncertified converters while elevating premium tiers for compliant producers serving Central European distribution networks.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade barrier films commands substantial premiums over standard food-service grades. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and barrier coating complexity. Cost compression in standard polypropylene grades is intensifying because Aldi and Lidl centralized procurement extends payment terms across private-label networks. Food manufacturers represent the most price-sensitive segment, while pharmaceutical contract manufacturers absorb premium pricing for tamper-evident serialization compliance.
Supply Chain Analysis
Rotterdam-Antwerp petrochemical corridor chokepoints tether resin supply to naphtha-cracking economics, exposing non-integrated converters to margin volatility. Feedstock draws from Belgium, Germany, and the Netherlands, with specialty additives sourcing from Italian compounders around Bologna. Slitting and rewinding capacity concentrates in Poland and the Czech Republic, where labor arbitrage attracts German-brand owner investment. Single-source vulnerability runs through vacuum metallization equipment suppliers, as seven-figure euro outlays for SiOx deposition lines create extended payback risk. Distribution feeds from Rhine-Ruhr converting clusters through Central European logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automated dispensing equipment service contracts represent a recurring-revenue layer expanding faster than film substrate sales, as meat processing facilities prioritize uptime guarantees over unit procurement. This service-attach dynamic restructures competitive advantage toward bundled equipment-film offerings.
For Market Incumbents: Secure captive polypropylene supply chains through backward integration into resin production, insulating margin position from Rotterdam naphtha-cracking volatility. Invest in ISCC PLUS certification capabilities ahead of EU Green Deal recycled content mandates, as uncertified competitors face exclusion from German retail procurement tenders. Channel control through direct equipment-film bundling with automated dispensing lines defends against specialty coating house disruption. For New Entrants and Emerging Players: Differentiate on pharmaceutical serialization compliance, where EU Falsified Medicines Directive mandates create qualification barriers for established food-grade converters. Target Polish and Czech converting clusters for nearshored supply to German-brand owners seeking labor cost arbitrage without REACH documentation burden. A go-to-market angle pairing water-based barrier coating expertise with Parma cured meat cluster relationships unlocks premium positioning. For Investors and Strategic Acquirers: EU Green Deal packaging regulations reshape the acquisition landscape toward mass-balance certified feedstock capabilities and coating-line assets with barrier technology IP. Long-term viability over the next decade hinges on exposure to pharmaceutical-grade certification rather than commodity food-service volumes. The signal to watch is EFSA safety opinion evolution on post-consumer recyclate in food contact, which will determine recycled content premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Resin | Captive supply from Rotterdam-Antwerp corridor insulates converters from naphtha-cracking margin compression. |
| ISCC PLUS Certification Investment | Mass-balance certification secures procurement eligibility with Aldi and Lidl centralized buying offices. |
| Pharmaceutical Serialization Capability Buildout | EU Falsified Medicines Directive compliance opens tamper-evident film demand with track-and-trace integration. |
| Water-Based Barrier Coating Adoption | EPA-equivalent emission preemption in Italian cured meat cluster displaces solvent-based acrylic incumbent pricing power. |
| Central European Converting Cluster Expansion | Poland and Czech Republic labor arbitrage captures German-brand owner nearshoring without REACH documentation cost burden. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across regulatory and trade databases. Converting plant managers, procurement leads at German retail chains, resin supplier technical directors, and pharmaceutical contract manufacturing executives contributed operational perspective. Secondary sources encompassed ECHA candidate list updates, EFSA safety opinions on post-consumer recyclate, customs data from Benelux ports, and SEC filings from multinational packaging conglomerates. Bottom-up volume modeling from slitting capacity and top-down demand segmentation triangulated market sizing.
Across the analysis window, forecasts reflect analytical framework segmentation by film type, thickness specification, end-use industry, and regional converting cluster. CAGRs were derived from elasticity modeling against propylene feedstock price scenarios and flexible packaging substitution rates. Modeled inputs included REACH compliance cost trajectories, barrier coating technology diffusion curves, and retail buying power concentration indices.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or EFSA recyclate approval would require recalibration. Forecasts reflect assumptions on propylene feedstock volatility and pharmaceutical serialization mandate timelines. Practitioners should keep alternative scenarios live as ECHA candidate list expansion and extended producer responsibility framework evolution reshape compliance cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Microwave Packaging Market
Packaging Materials
Foam Trays Market
Packaging Materials
Squeeze Tube Market
Packaging Materials
Card Films Market
Packaging Materials
Graphene Infused Packaging Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Fiber Lids Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Thermoformed Trays Market
Packaging Materials
Africa Packaging Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Mylar Market
Packaging Materials
Battery Packaging Material Market
Packaging Materials
MDO Films Market
Packaging Materials
Cargo Moisture Control Products Market