
 Cast Polymers Market | 2026-2036
Cast Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Cast Polymers Market Intelligence
A shift from single-source procurement to multi-sourcing for polyester and acrylic resins is broadening the material options available to fabricators. Cosentino S.A. leverages its extensive distribution network to supply large-scale commercial projects. Caesarstone differentiates through premium branding and design-led product development for residential markets. The R.J. Marshall Company specializes in providing specific fillers and raw materials to the industry.
Cast polymers are a class of materials produced by mixing mineral fillers with liquid polymer resins, such as polyester or acrylic, and casting the mixture into molds. These composites cure to form solid, non-porous surfaces that mimic the appearance of natural stone but offer greater design flexibility and stain resistance. Polyester-based materials continue to hold a significant share, but acrylic resins are gaining traction in high-value applications like countertops and sinks. While residential builders drive volume, demand from commercial contractors for durable wall panels and flooring represents a key growth area.
Product safety and material composition standards are governed by bodies like the U.S. Environmental Protection Agency (EPA) concerning volatile organic compound (VOC) emissions. In Europe, compliance with REACH regulations on chemical substances and CE marking for construction products dictates market access for manufacturers. Future material selection will be influenced by evolving sustainability criteria and the circular economy principles being adopted by residential and commercial specifiers.
Market Dynamics
The central structural force shaping the cast polymers market is the architectural shift toward engineered materials that offer superior performance and design freedom over natural stone. This movement is driven by commercial specifiers in hospitality and healthcare seeking durable, non-porous, and customizable surfaces.
Growth Catalysts
- Indian Urbanization:Rapid construction of commercial and high-end residential buildings in metropolitan areas like Mumbai and Bangalore creates sustained demand for cast polymer products, particularly for countertops, bathroom vanities, and wall cladding.
- Acrylic Resin Innovation:Advances in acrylic resin chemistry enable the production of lighter, more thermoformable solid surface materials, allowing designers to specify complex curves and seamless forms for retail and corporate interiors.
- Healthcare Sector Demand:The requirement for hygienic, non-porous, and easily cleanable surfaces in hospitals and clinics to control infection spread provides a significant catalyst for cast polymer wall panels, sinks, and transaction counters.
Market Restraints
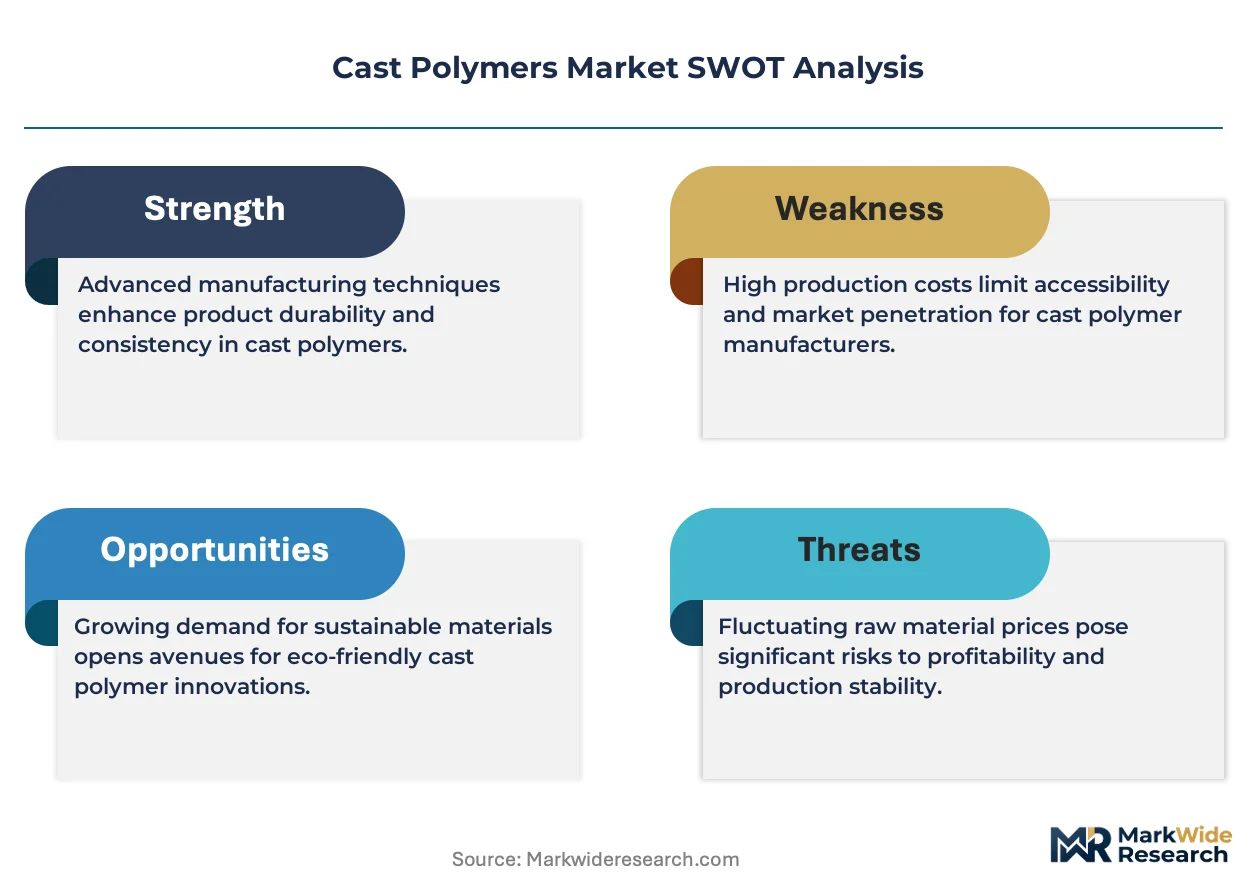
- Input Cost Volatility:The market is exposed to price fluctuations in petrochemical derivatives, such as polyester and acrylic resins, which can compress fabricator margins and impact final product pricing.
- Substitution from Quartz Surfaces:Engineered quartz slabs represent a significant substitution threat, competing directly in high-end countertop applications with a strong brand presence and established distribution channels in the residential sector.
- Regulatory Compliance Costs:Adhering to environmental regulations like the EPA's standards on VOC emissions in the United States and Europe's REACH framework adds complexity and cost to the manufacturing process.
Strategic Opportunities
- Middle East Infrastructure Projects:Large-scale hospitality, commercial, and public infrastructure developments in Saudi Arabia and the UAE offer significant growth potential for cast polymer manufacturers able to meet project specifications for durability and aesthetics.
- Exterior Cladding Applications:Developing new formulations with enhanced UV stability and weather resistance opens opportunities for cast polymers in exterior facade systems, offering a lightweight alternative to traditional materials like stone or concrete panels.
- Circular Economy Materials:Incorporating recycled fillers, such as post-consumer glass or industrial mineral waste, and developing bio-based resins allows manufacturers to meet demand from specifiers prioritizing materials with high recycled content for green building certifications.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of trained fabricators and installers capable of executing complex, custom installations limits the ability of firms to take on large-scale or intricately designed commercial projects.
- Lack of Global Standards:The absence of universally accepted performance and testing standards across different types of cast polymers can create uncertainty for architects and designers when specifying materials for international projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cast Polymers Market |
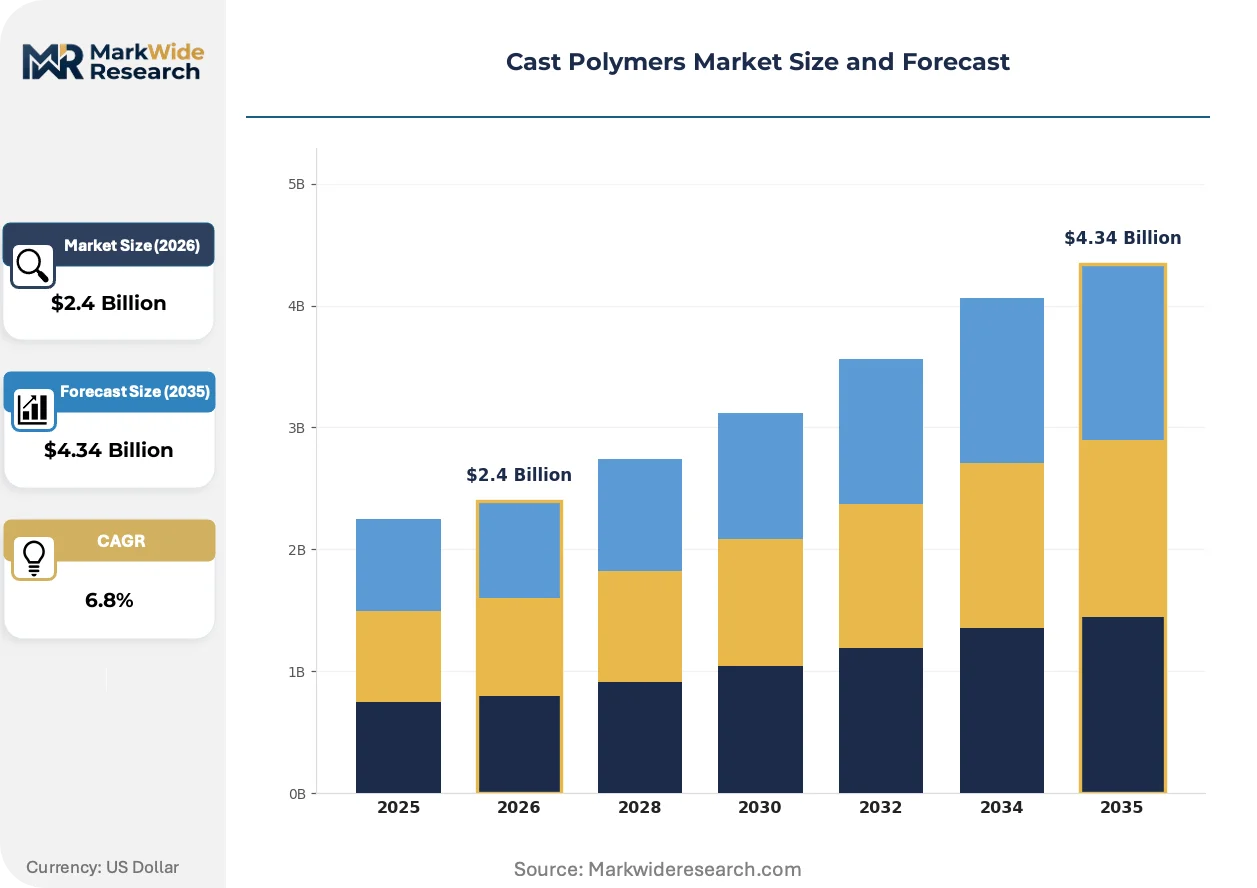
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, Acrylic, Epoxy, Vinyl Ester, Polyurethane Application: Countertops, Wall Panels, Bathtubs, Sinks, Flooring End User: Residential Builders, Commercial Contractors, Interior Designers, Fabricators Packaging Type: Sheets, Blocks, Molded Components, Custom Shapes |
| Companies Covered | Link Composites Pvt. Ltd., Cosentino S.A., The R.J. Marshall Company, Caesarstone, E. I. Du Pont De Nemours and Company, Swan Corporation, Bradley Corporation, Breton S.P.A, Huber Engineered Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cast Polymers Market Strategic Shifts & Innovations
Material science advancements are intersecting with sustainability mandates, pushing cast polymer development toward formulations with improved environmental profiles and enhanced fabrication potential. This evolution is redefining product value beyond simple aesthetics to include lifecycle performance and design integration.
Digital fabrication tools, including computer numerical control (CNC) machining and advanced thermoforming, are transforming design possibilities with acrylic-based solid surfaces. High-end architectural firms and commercial interior designers are specifying these processes to create unique, monolithic forms. This technology is absorbing the demand for bespoke architectural elements that were previously impractical to produce, compressing the timeline from digital design to physical installation.
In Europe, the Corporate Sustainability Reporting Directive (CSRD) is compelling manufacturers to provide transparent, verifiable data on their products' environmental impact. This regulation necessitates comprehensive lifecycle assessments, covering everything from raw material sourcing to end-of-life recyclability. The solid surface segment is most affected, with leading manufacturers now investing in Environmental Product Declarations (EPDs) to maintain specification status in commercial projects.
A significant behavioral change is the move by large hotel chains and retail brands toward establishing direct, multi-year specification agreements with cast polymer manufacturers. This model bypasses traditional, fragmented regional distribution for high-volume, standardized components like vanities and service counters. The trend is most prominent in North America, where ensuring brand and material consistency across a national portfolio is a primary objective.
Cast Polymers Market Segmentation
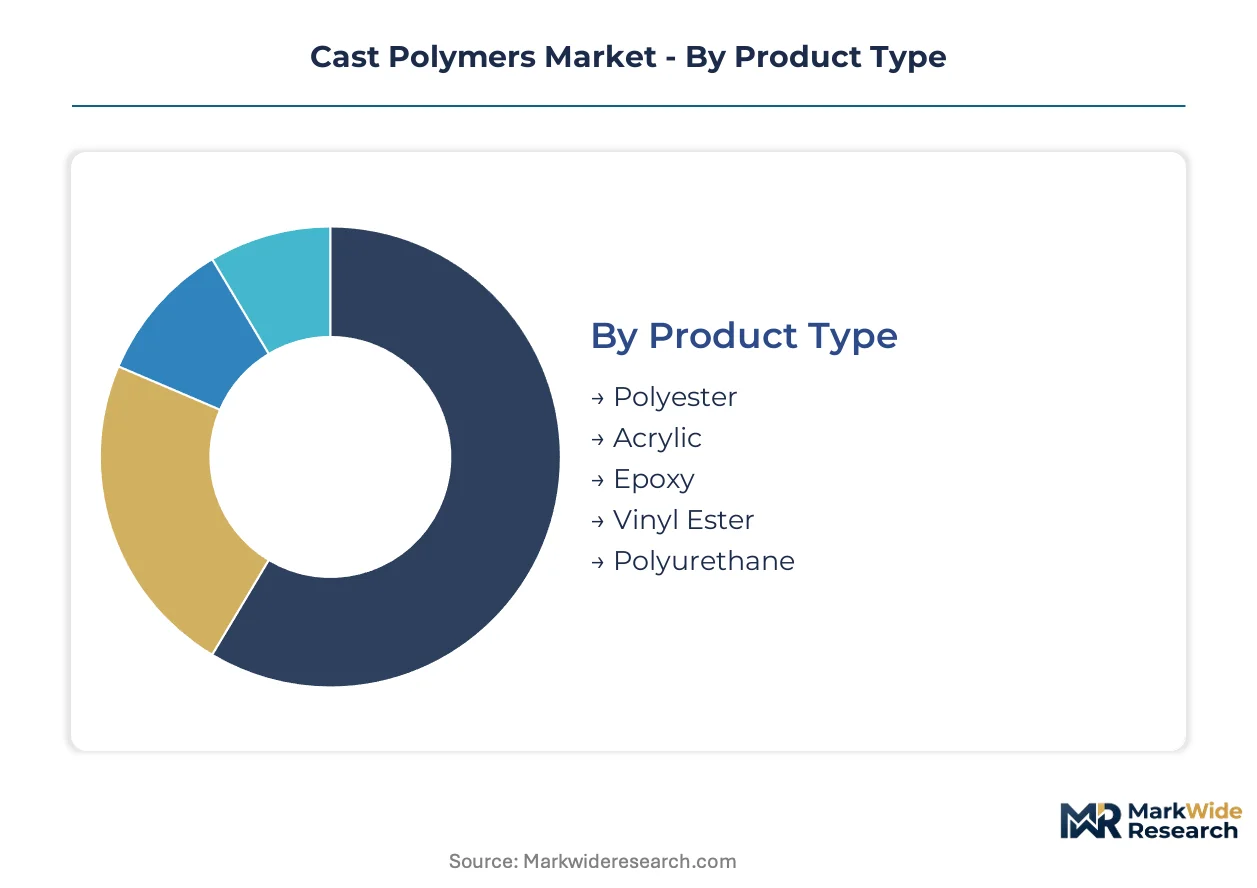
The cast polymers market exhibits diverse segmentation reflecting varied material compositions, functional applications, end-user requirements, and product forms. Understanding these distinct segments allows manufacturers to tailor product development and market strategies effectively. Each category highlights specific performance attributes and commercial opportunities within the industry.
Product Type:
The product type segmentation highlights the spectrum from highly customizable, specialized formulations to more standardized, volume-driven material choices.
- Acrylic:This type of cast polymer uses acrylic resins, offering superior thermoformability, UV stability, and intricate design possibilities for solid surface materials. Demand concentrates in high-value applications like retail interiors and healthcare environments seeking seamless, hygienic surfaces.
- Polyester:Polyester-based cast polymers combine polyester resins with mineral fillers, providing a cost-effective and durable solution with good stain resistance. Residential construction and commercial projects in India frequently specify polyester for bathroom vanities and countertops due to its balance of performance and price.
- Epoxy:Epoxy resins are known for their high strength, chemical resistance, and excellent adhesion, making them suitable for industrial flooring and specialized coatings.
- Vinyl Ester:Vinyl ester polymers offer enhanced corrosion resistance and mechanical properties, often employed in demanding industrial applications like chemical tanks and pipes.
- Polyurethane:Polyurethane cast polymers provide flexibility, impact resistance, and abrasion durability, finding use in components requiring resilience and cushioning.
Leading the category by volume: Polyester. Growing fastest: Acrylic.
Application:
Application segmentation reveals how different functional requirements drive material selection and product design across various end-use environments.
- Countertops:Cast polymer countertops provide a non-porous, aesthetically versatile, and durable surface solution, mimicking natural stone while offering greater design flexibility. Residential builders and hospitality projects in metropolitan areas like Mumbai frequently specify these for kitchens and bathroom vanities.
- Wall Panels:These panels offer hygienic, impact-resistant, and aesthetically pleasing surfaces, particularly valued for their ease of cleaning and infection control properties. Commercial contractors in healthcare facilities and public infrastructure projects in the UAE represent a significant demand base.
- Bathtubs:Cast polymer bathtubs offer design freedom and warmth to the touch, providing an alternative to traditional materials with improved insulation properties.
- Sinks:Non-porous and stain-resistant, cast polymer sinks integrate seamlessly with countertops, offering a hygienic and visually continuous surface solution.
- Flooring:Cast polymer flooring systems provide seamless, durable, and chemical-resistant surfaces, suitable for high-traffic commercial and industrial settings.
Countertops consistently represent a high-volume application. Wall panels are expanding most quickly due to hygiene demands.
End User:
The end-user segmentation differentiates market demand based on the purchasing power and project scale of various customer types.
- Commercial Contractors:These users require durable, high-performance, and often custom-engineered cast polymer solutions for large-scale projects in hospitality, healthcare, and public infrastructure. Their demand emphasizes longevity, regulatory compliance, and consistent material supply for projects across Saudi Arabia.
- Residential Builders:Driving significant volume, residential builders prioritize cost-effectiveness, ease of installation, and aesthetic appeal for standard and semi-custom cast polymer products. Demand from new housing developments in India significantly influences this segment.
- Interior Designers:Interior designers specify cast polymer products for their aesthetic versatility, design flexibility, and ability to create bespoke architectural elements.
- Fabricators:Fabricators purchase raw materials and semi-finished cast polymer products to produce custom components and installations for various end-users.
Residential Builders account for the largest volume consumption. Commercial Contractors are gaining share with specialized project requirements.
Packaging Type:
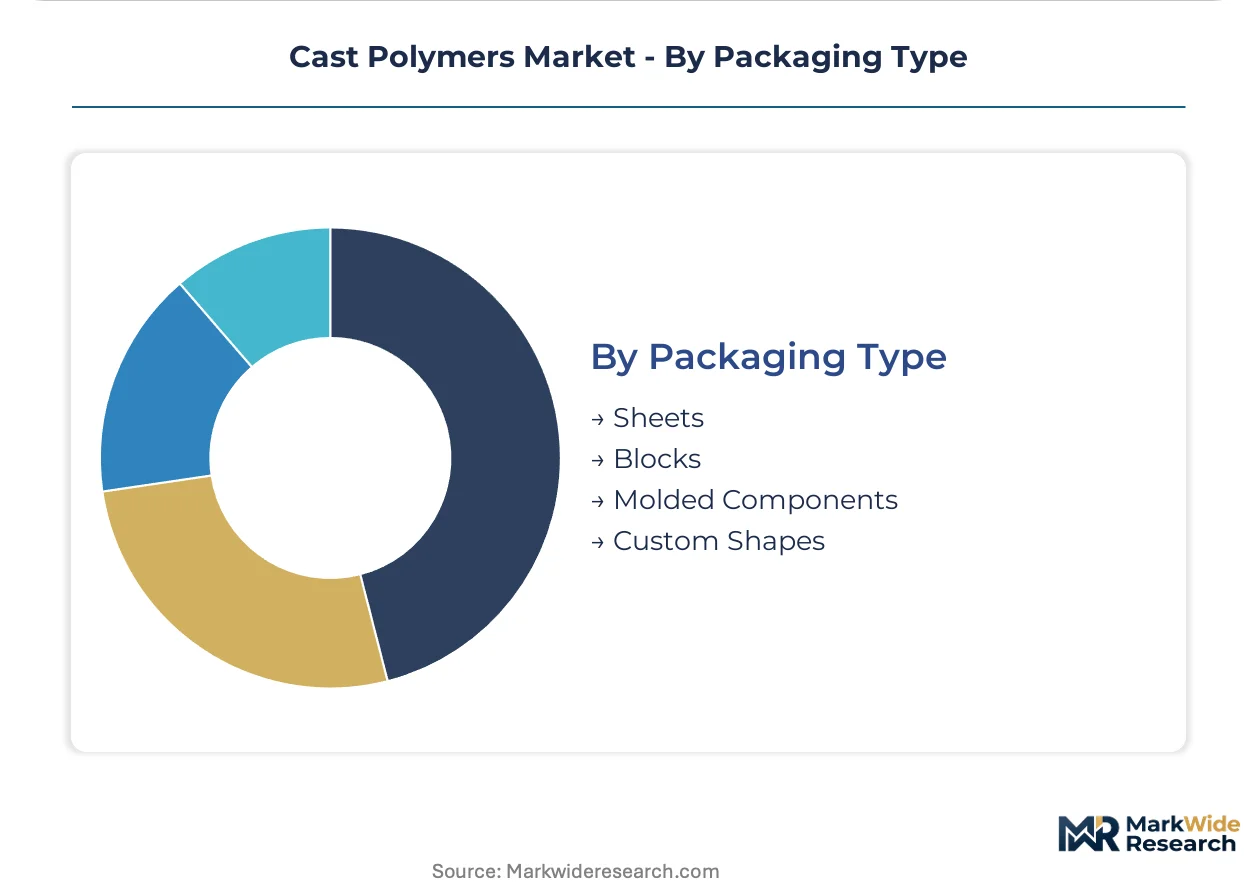
Segmentation by packaging type reflects the manufacturing process and the degree of pre-fabrication, ranging from raw material forms to finished components.
- Sheets:Cast polymer sheets are standardized, flat panels used as raw material for further fabrication into countertops, wall cladding, and other surfaces. They offer versatility for cutting and thermoforming into various designs.
- Custom Shapes:These are unique, pre-engineered cast polymer components molded to specific architectural or design specifications, allowing for intricate geometries and seamless integration. Demand for these is rising in commercial interiors requiring bespoke elements.
- Blocks:Cast polymer blocks serve as larger, raw material forms, allowing fabricators to machine or cut them into specific dimensions for custom projects.
- Molded Components:These are pre-formed cast polymer items, such as sinks or shower bases, produced directly from molds to reduce fabrication time and ensure consistency.
Sheets maintain a dominant position in terms of material volume. Custom Shapes are experiencing the steepest expansion trajectory due to design innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical production hubs in the Middle East anchor significant raw material supply for the cast polymers market. Demand for durable and aesthetic engineered surfaces is expanding across diverse global construction markets. Regulatory frameworks in major economies influence product development and market access for manufacturers.
India
Rapid construction of commercial and high-end residential buildings drives demand for cast polymer products in India. The Bureau of Indian Standards (BIS) influences material quality and product specifications for construction materials. Metropolitan areas like Mumbai and Bangalore experience sustained demand for countertops and wall cladding in new developments.
United States
The healthcare sector's need for hygienic surfaces and hospitality projects requiring durable countertops fuels demand in the United States. The U.S. Environmental Protection Agency (EPA) sets standards for volatile organic compound (VOC) emissions, impacting product formulations. Commercial centers across the United States see large hotel chains establishing direct specification agreements.
Saudi Arabia
Large-scale hospitality and public infrastructure projects in Saudi Arabia create substantial opportunities for cast polymer manufacturers. Project specifications for durability and aesthetics guide material selection in these developments. The NEOM project and Riyadh developments offer significant growth potential for specialized applications.
Germany
High-value applications and sustainability criteria influence cast polymer demand in Germany and wider Europe. Compliance with REACH regulations and CE marking is essential for market access for construction products. Manufacturers in design hubs are investing in EPDs to meet CSRD requirements.
UAE
Commercial contractors in the UAE drive demand for durable wall panels and flooring in public infrastructure projects. Meeting stringent project specifications for aesthetics and durability is critical for market participation. Developments in Dubai and Abu Dhabi represent a significant demand base for wall panels and transaction counters.
Cast Polymers Market Key Industry Players
Product differentiation and distribution network leverage dominate the current landscape, shaping the competitive dynamics in the cast polymers market. The market exhibits a tiered structure, with large integrated players coexisting with specialized material suppliers and custom fabricators. Strategic archetypes include global brand leaders, regional specialists, and raw material providers. Companies pursue geographic expansion and portfolio diversification to capture new opportunities.
Specialists in raw material supply, such as The R.J. Marshall Company, provide critical fillers and resins to the industry. Global brand leaders like Cosentino S.A. leverage extensive distribution networks to serve large-scale commercial projects. Firms such as Caesarstone exemplify a strategy of premium branding and design-led product development, particularly targeting residential markets. These players occupy distinct positions across the value chain, from raw material provision to finished product distribution.
| Leading Market Players |
|---|
| Link Composites Pvt. Ltd. |
| Cosentino S.A. |
| The R.J. Marshall Company |
| Caesarstone |
| E. I. Du Pont De Nemours and Company |
| Swan Corporation |
| Bradley Corporation |
| Breton S.P.A |
| Huber Engineered Materials |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material supply anchors both the supply position and the pricing power for large cast polymer manufacturers. This strategic control mitigates exposure to petrochemical derivative fluctuations.
Pricing Analysis
Warranty and service bundling often differentiate premium cast polymer offerings from standard products in the market. Project-based pricing dominates for commercial applications, while residential builders typically engage in contract-based long-term offtake agreements. Customization level and strong brand premium drive price differentiation for high-value acrylic products. Cost compression stems from input cost volatility, particularly for polyester resins. Residential builders exhibit the highest price sensitivity, whereas commercial contractors prioritize performance and consistency over marginal cost savings.
Supply Chain Analysis
Logistics and freight costs significantly influence the delivered price of cast polymer components, especially for large-scale projects. Geographic supply concentration for key raw materials centers on petrochemical hubs in the Middle East and resin producers in Asia. The market draws from polyester resins, acrylic resins, and mineral fillers as primary material dependencies. Commodity price volatility in petrochemical derivatives represents a structural supply chain risk. Distribution runs through both direct specification agreements with large commercial clients and extensive regional networks for smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a vertical-integration race, with players pursuing upstream control over raw material supply to secure competitive advantage.
For Market Incumbents: Cement long-term resin supply contracts to stabilize input costs against petrochemical price volatility. Invest in advanced fabrication technologies, including CNC machining, to enhance design flexibility and production efficiency. Focus R&D on sustainable formulations, incorporating recycled fillers to counter the substitution threat from quartz surfaces. Expand distribution networks in high-growth regions like India to capture new residential and commercial volume.
For New Entrants and Emerging Players: A price-point gap exists between premium design-led acrylic products and cost-effective polyester options. Target specialized industrial applications requiring enhanced chemical or abrasion resistance, offering custom shapes with rapid prototyping capabilities. Focus on commercial projects in emerging markets, such as the Middle East, where large infrastructure developments create white-space opportunities. Develop bio-based resin formulations to appeal to specifiers prioritizing green building certifications.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized fabricators with strong intellectual property in acrylic formulations and digital fabrication expertise. The long-term viability of the market is strong, driven by sustained demand for engineered materials offering superior performance over natural stone. Target mid-cap companies demonstrating robust R&D in sustainable materials and established relationships with commercial specifiers. The adoption rates of bio-based resins and the expansion of exterior cladding applications serve as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Long-Term Resin Contracts | Stabilizes input costs for fabricators, enabling more predictable pricing for commercial projects. |
| Invest in Digital Fabrication | Enhances design flexibility and allows for intricate custom shapes, meeting architectural demands. |
| Develop Bio-Based Resin Formulations | Addresses evolving sustainability criteria and circular economy principles for green building certifications. |
| Expand Distribution in Emerging Markets | Captures new demand from rapid construction activity in regions like India and the Middle East. |
| Acquire Specialized Fabricators | Integrates advanced fabrication capabilities and proprietary material formulations, strengthening market position. |
Research Approach
Construction industry reports, government economic surveys, and patent databases formed the secondary backbone of this study. This was complemented by primary interviews with commercial contractors, residential builders, material scientists, and architectural specifiers. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market coverage.
Historical trendline analysis informed the analytical framework across the analysis window, modeling segmentation dimensions including product type, application, end user, packaging type, and regional construction activity. Compound Annual Growth Rates were derived from an assessment of historical data and projected market drivers. Urbanization rates in India and healthcare infrastructure spending served as critical industry-specific forecast inputs.
Inputs from industry associations and regulatory bodies were available through the study window; gaps in specific regional consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding economic stability and technological adoption. Stakeholders should weigh assumptions against their own operating context, considering factors like petrochemical price volatility and evolving regulatory changes concerning VOC emissions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphenylene Oxide (PPO) Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Plastic Calendering Resins Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Global Fluoropolymer Market
Polymers & Resins
Europe Polymer Emulsion Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Asia-Pacific Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Redispersible Polymer Powder Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Global Polyphthalamide Market