
 Quartz Kitchen Countertops Market | 2026-2036
Quartz Kitchen Countertops Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Kitchen Countertops Market Analysis
Aftermarket fabrication and installation services revenue is tilting toward certified silica-safe workshops as regulatory liability reshapes the value chain. Cambria sustains its position through captive North American manufacturing and strict color consistency protocols. Caesarstone leverages its Israeli R&D base to develop thinner-profile slabs that reduce freight costs per square meter. MSI Q Quartz dominates the distributor channel in the United States through volume pricing and rapid SKU turnover.
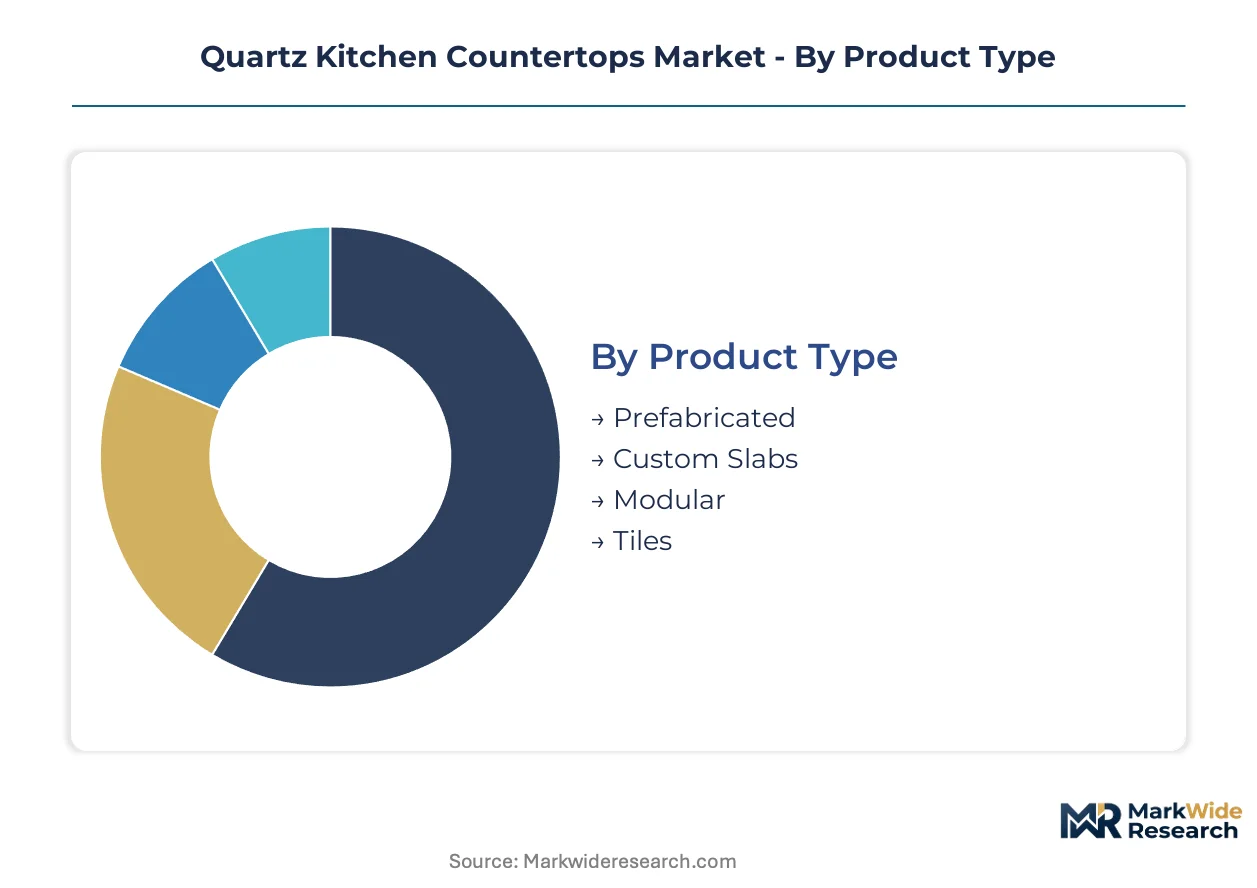
Quartz kitchen countertops are engineered stone surfaces comprising approximately 90 percent ground natural quartz bound with polymer resins, then cast under vacuum vibration and cured at controlled temperatures to achieve non-porous, flexural strength exceeding 25 MPa. Custom slabs command premium positioning in luxury residential and hospitality specifications where unique dimensions and edge profiles justify longer lead times. The polished finish category retains volume leadership across kitchen applications, while honed surfaces are gaining share in bathroom and workplace segments where subdued reflectivity aligns with contemporary design palettes. Prefabricated options anchor the mass-market residential channel through standardized sizing that reduces both material waste and installation labor.
The EPA enforces crystalline silica exposure limits that mandate wet-cutting methods and respiratory protection in fabrication facilities, directly elevating compliance costs for smaller workshops. OSHA workplace safety standards and California's Proposition 65 warning requirements further shape product labeling and liability exposure across the United States supply chain. Stakeholders must monitor evolving silica classification debates in Europe and Asia-Pacific, as harmonized restrictions would compress margin structures for exporters serving multiple regulatory jurisdictions simultaneously.
Market Dynamics
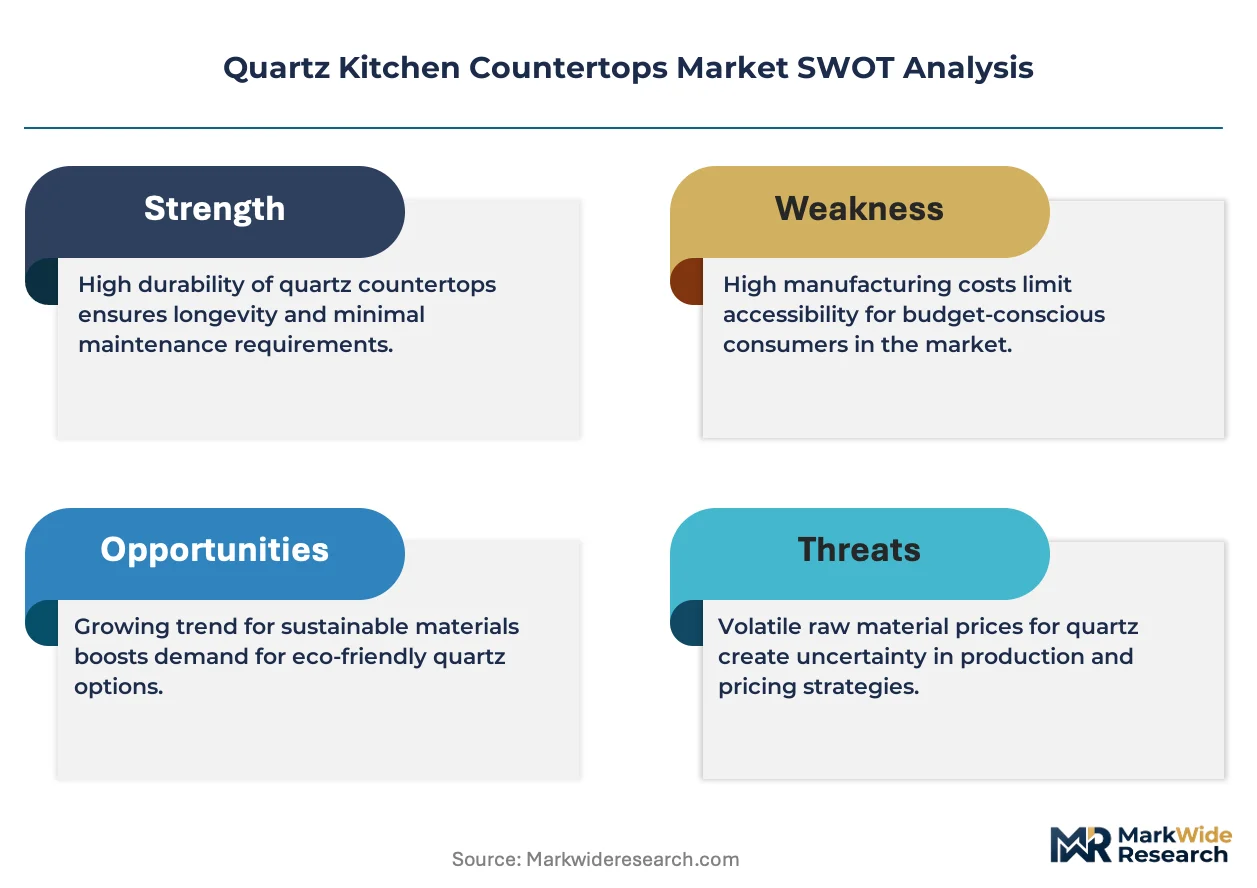
EPA crystalline silica enforcement is restructuring fabrication economics, forcing capital investment in wet-cutting infrastructure and respiratory systems across North American workshops while compressing margins for non-compliant operators.
Growth Catalysts
- Renovation intensity in Indian metros:Tier-one cities Mumbai, Delhi, and Bangalore are driving replacement demand as aging residential stock undergoes kitchen modernization.
- REACH-aligned material standards:European resin formulation protocols are enabling cleaner supply chains that qualify for green building certifications.
- Thin-slab manufacturing advances:Vacuum vibration compaction technology reduces freight density and opens air-cargo distribution to remote luxury projects.
Market Restraints
- Petrochemical resin volatility:Polymer binder costs fluctuate with crude oil derivatives, compressing margin predictability for slab producers.
- Fabrication labor concentration:Skilled wet-cutting technicians cluster in coastal manufacturing belts, creating geographic supply bottlenecks.
- Porcelain slab substitution:Sintered stone surfaces are capturing specification share in high-traffic commercial applications.
Strategic Opportunities
- Saudi luxury residential pipeline:Giga-project developments around NEOM and the Red Sea are specifying engineered stone at scale for premium installations.
- Direct-to-installer digital platforms:B2B marketplaces are disintermediating traditional distributor layers in fragmented renovation markets.
- California Proposition 65 compliance premiums:Warning-label-exempt formulations command pricing power in liability-conscious segments.
Industry Challenges
- Silica-safe technician certification backlog:OSHA-compliant training programs face capacity constraints, delaying workshop licensing timelines.
- Legacy inventory obsolescence:Pre-regulation slab stock requires costly reprocessing to meet emerging respirable dust standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Kitchen Countertops Market |
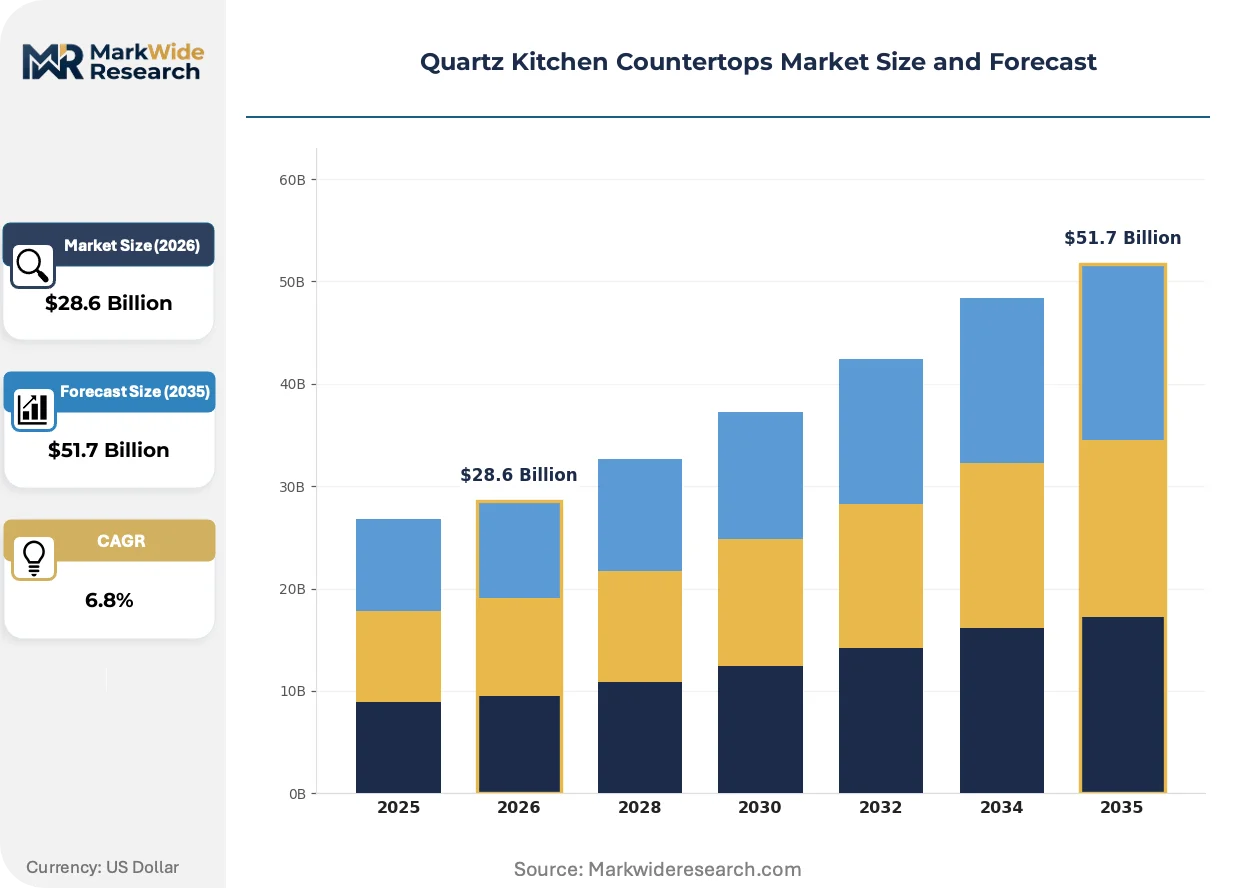
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prefabricated, Custom Slabs, Modular, Tiles End User: Residential, Commercial, Hospitality, Retail Application: Kitchens, Bathrooms, Outdoor Spaces, Workplaces Finish Type: Polished, Honed, Textured, Matte |
| Companies Covered | MSI Q Quartz, HanStone Quartz, Caesarstone, Daltile ONE Quartz, Santa Margherita Quartz, Cambria, Viatera, Pental, Silestone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Kitchen Countertops Market Emerging Trajectories
Digital templating and augmented visualization tools are compressing the specification-to-fabrication cycle while reshaping how designers and homeowners finalize surface selections.
Computer-numerical-control waterjet cutting is virtualizing traditional manual edge profiling, enabling complex mitered and waterfall configurations at production scale. Luxury residential developers in Miami and Dubai are specifying these digitally fabricated profiles for signature installations. The technology is virtualizing the artisan labor pool that previously constrained custom geometry throughput.
EPA respirable crystalline silica standards are mandating wet-cutting infrastructure and medical surveillance programs across fabrication facilities. Smaller workshops face capital barriers to compliance while larger operators capture market share through certified production capacity. California's Proposition 65 warning requirements add labeling complexity for imported slabs lacking compliant resin formulations.
Specification decisions are migrating earlier in the construction cycle as BIM-integrated material libraries enable real-time quartz surface visualization. Architects are locking surface selections during schematic design rather than deferring to contractor procurement. This compression is most visible in Dubai's luxury residential tower segment where developer-controlled design-build contracts eliminate traditional trade bidding.
Quartz Kitchen Countertops Market Segmentation
Quartz kitchen countertops serve divergent construction workflows, from mass-market renovation rollouts requiring rapid turnaround to bespoke luxury installations demanding dimensional precision. Segmentation reveals how material form factors, surface finishes, and end-use specifications create distinct margin profiles and compliance obligations across the value chain.
Product Type:
Kitchen and bath workflows span from standardized replacement projects to architect-driven signature installations, with each product format carrying distinct lead-time and tooling requirements.
- Prefabricated:Standardized dimensional slabs cut to common cabinet depths and lengths, enabling same-day installation for renovation contractors. Demand clusters in United States suburban retrofit markets where homeowners prioritize speed over customization.
- Custom Slabs:Cast-to-order surfaces exceeding standard widths or incorporating proprietary edge profiles, requiring CNC waterjet fabrication. Luxury residential towers in Dubai and Miami specify these for waterfall islands and integrated backsplashes where dimensional uniqueness justifies extended lead times.
- Modular:Interlocking panel systems designed for rapid field assembly without wet-cutting, reducing silica exposure liability for installers. Gaining traction in commercial workplace fit-outs where phased occupancy demands minimize construction duration.
- Tiles:Smaller format units for backsplashes, accent walls, and transitional surfaces where full slabs prove economically inefficient. Popular in Indian metro renovation segments for budget-conscious kitchen modernization.
Established volume favors Prefabricated; emerging adoption favors Custom Slabs.
End User:
Customer archetypes range from individual homeowners making discrete replacement decisions to institutional procurement teams managing multi-unit specifications.
- Residential:Single-family homeowners and multi-family unit owners driving replacement demand in aging housing stock. Indian tier-one metros Mumbai, Delhi, and Bangalore concentrate activity as kitchen modernization accelerates in 15-25 year old developments.
- Commercial:Corporate workplace and healthcare facility managers specifying surfaces for durability and maintenance efficiency. REACH-aligned resin formulations increasingly gate entry to European Union green building certifications.
- Hospitality:Hotel operators and cruise lines requiring consistent batch-to-batch color matching across hundreds of identical installations. Thin-slab manufacturing advances enable air-freight distribution to remote luxury projects.
- Retail:Food service chains and showroom operators balancing aesthetic differentiation with vandalism resistance. Porcelain slab substitution poses competitive pressure in high-traffic configurations.
Residential commands absolute volume; Hospitality climbs fastest on luxury pipeline expansion.
Application:
Surface performance requirements vary dramatically across moisture exposure, thermal cycling, and mechanical load conditions.
- Kitchens:Primary application demanding heat resistance, stain immunity, and seamless integration with sinks and cooktops. Polished finishes retain dominance here for reflectivity and cleanability.
- Bathrooms:Secondary spaces where honed surfaces gain specification share for subdued reflectivity aligning with contemporary wellness design palettes.
- Outdoor Spaces:Patios and outdoor kitchens requiring UV-stable resin formulations and thermal shock resistance. California Proposition 65 warning-exempt formulations command pricing premiums in liability-conscious segments.
- Workplaces:Corporate pantries and amenity spaces prioritizing durability under intensive use. Direct-to-installer digital platforms are disintermediating traditional distributor layers in this fragmented specification environment.
Kitchens anchor revenue; Outdoor Spaces expand most quickly on residential lifestyle extension trends.
Finish Type:
Surface texture determines both aesthetic character and functional maintenance burden across installation environments.
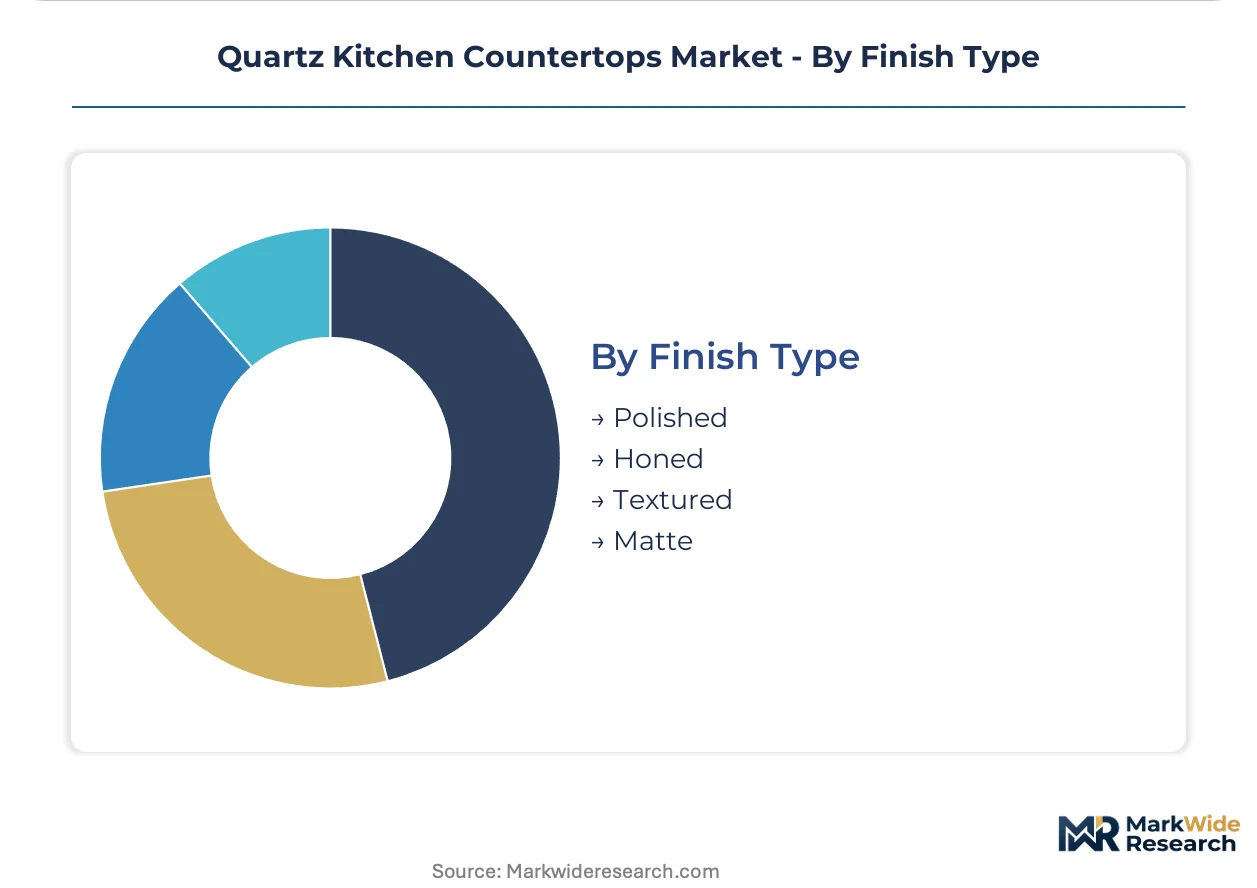
- Polished:High-gloss surfaces achieved through progressive diamond abrasive polishing, maximizing reflectivity and perceived depth. Dominates kitchen specifications where light distribution and cleanability outweigh slip concerns.
- Honed:Satin-smooth finish with muted reflectivity, concealing water spots and fingerprints in bathroom and workplace applications. Gaining share fastest among designers specifying contemporary material palettes.
- Textured:Embossed or leathered surfaces providing tactile grip and disguising wear patterns. Specified for outdoor kitchen installations where wet conditions demand slip resistance.
- Matte:Ultra-low sheen finish achieved through modified curing protocols, minimizing glare in daylight-intensive hospitality lobbies and retail showrooms.
Polished retains volume leadership; Honed shows steepest expansion trajectory on bathroom and workplace specification migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. United States buyers prioritize rapid-install prefabricated formats for suburban renovation, while Indian and Middle Eastern markets favor custom slabs for luxury new-build specifications.
United States
Suburban retrofit contractors drive prefabricated volume through big-box retail channels. OSHA silica enforcement compresses margins for non-compliant fabrication shops in Florida and California. Dallas-Fort Worth fabrication clusters are consolidating around certified wet-cutting infrastructure.
India
Tier-one metro renovation in Mumbai, Delhi, and Bangalore accelerates replacement demand in aging residential stock. BIS standards for engineered stone surface quality are tightening import gatekeeping. Gujarat manufacturing corridors are scaling domestic slab casting capacity.
Germany
Commercial workplace fit-outs specify REACH-aligned resin formulations for green building certification compliance. ECHA monitoring of silica classification creates formulation uncertainty for imported slabs. North Rhine-Westphalia distribution hubs are pivoting toward certified silica-safe inventory.
United Arab Emirates
Luxury residential towers in Dubai specify custom slabs with CNC-fabricated waterfall profiles. MOHAP building material safety protocols are extending to engineered stone surface emissions testing. Sharjah fabrication zones are investing in medical surveillance programs for silica compliance.
Saudi Arabia
NEOM and Red Sea giga-projects are sourcing thin-profile slabs for air-freight delivery to remote sites. SFDA building product registration requirements are extending to resin-bound surface materials. Riyadh-based procurement teams are consolidating supplier qualification around silica-safe certification.
Quartz Kitchen Countertops Market Vendor Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base stratifies between captive-manufacturing specialists and distributor-channel volume players. Three archetypes dominate: North American captive producers, Israeli R&D-driven innovators, and distributor-anchored volume brands. Competitive moves center on silica-safe certification racing and thin-slab manufacturing licensing.
Within the captive-manufacturing tier, Cambria anchors North American production scale. Caesarstone occupies a position exemplifying R&D-driven thin-slab innovation from its Israeli base. MSI Q Quartz represents distributor-channel dominance through volume pricing and rapid SKU turnover. These three illustrate how geographic manufacturing strategy and channel control differentiate positioning.
| Leading Market Players |
|---|
| MSI Q Quartz |
| HanStone Quartz |
| Caesarstone |
| Daltile ONE Quartz |
| Santa Margherita Quartz |
| Cambria |
| Viatera |
| Pental |
| Silestone |
| Others |
Supply Flow & Price Mechanics
Gujarat manufacturing corridors in India are scaling domestic slab casting capacity, compressing landed costs for Middle Eastern buyers and shifting pricing power toward volume-anchored distributors in the United States. This geographic rebalancing forces legacy European producers to defend margin through REACH-aligned formulation premiums or surrender share in price-sensitive renovation segments.
Pricing Analysis
Long-term offtake contracts dominate procurement for hospitality and giga-project developers, insulating slab producers from petrochemical resin volatility while spot-market transactions govern mass-market residential channels. Three-tier pricing structure across premium, standard, and economy levels separates silica-safe certified slabs from legacy inventory and import alternatives. Cost compression in the prefabricated tier is intensifying because wet-cutting compliance investments concentrate fabrication capacity among fewer certified workshops. Renovation contractors in United States suburban markets exhibit highest price sensitivity, whereas Dubai luxury developers prioritize color consistency and lead-time certainty over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with captive producers in the United States and Israel, where Cambria and Caesarstone maintain in-house casting and finishing infrastructure rather than outsourcing to third-party fabricators. Raw material sourcing draws from Brazilian quartz deposits, German resin formulations, and Chinese polishing abrasives. Single-source vulnerability concentrates in respiratory protection equipment for silica-safe workshops, where OSHA-compliant supplier qualification creates bottlenecks. Distribution runs through big-box retail channels for prefabricated formats and direct-to-installer digital platforms for custom slab specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around crystalline silica certification creates defensive moats for compliant operators, as workshop licensing timelines and capital barriers delay competitive replication. Switching costs rise for architects and developers locked into BIM-integrated material libraries that embed specific supplier specifications.
For Market Incumbents: Entrench position through backward integration into captive resin formulation, eliminating Proposition 65 liability exposure while capturing margin from imported slab competitors. Accelerate wet-cutting infrastructure deployment in Dallas-Fort Worth and Sharjah fabrication zones to absorb market share from non-compliant workshops facing OSHA enforcement. Porcelain slab substitution in high-traffic commercial applications demands defensive specification partnerships with hospitality procurement teams. For New Entrants and Emerging Players: Build out digital templating capabilities targeting Indian tier-one metro renovation segments, where fragmented contractor networks create white-space for platform-mediated installer matching. Saudi giga-projects around NEOM offer the most penetrable geography for thin-slab air-freight specialists lacking established distributor relationships. Direct-to-installer marketplaces disintermediate traditional layers without requiring legacy inventory investment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors certified silica-safe fabrication capacity over raw slab casting, as regulatory enforcement converts compliance into scarce production assets. Acquisition targets should demonstrate OSHA-compliant workshop licensing and medical surveillance program implementation. The signal to watch is ECHA crystalline silica classification harmonization, which would compress margin structures for exporters serving multiple regulatory jurisdictions simultaneously.| Strategic Initiative | Industry Significance |
|---|---|
| Silica-Safe Certification Investment | OSHA-compliant workshop licensing captures market share from non-compliant fabrication competitors in Florida and California. |
| Thin-Slab Manufacturing Scale-Up | Vacuum vibration compaction technology enables air-cargo distribution to remote Saudi giga-project sites. |
| Direct-to-Installer Platform Launch | B2B marketplaces disintermediate traditional distributor layers in fragmented Indian metro renovation markets. |
| REACH-Aligned Resin Backward Integration | In-house formulation eliminates Proposition 65 warning requirements and captures green building certification premiums. |
| CNC Waterjet Fabrication Partnership | Digital templating alliances with Miami and Dubai luxury developers lock specifications during schematic design phases. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of trade customs data, SEC filings from publicly listed surfacing companies, EPA regulatory dockets, and BIS standard documentation. Primary interviews engaged slab casting plant managers, wholesale distribution channel partners, wet-cutting fabrication technicians, and luxury residential procurement directors across the United States, India, and United Arab Emirates. Bottom-up demand modeling from renovation permit data and top-down supply validation from import-export statistics were triangulated against manufacturer capacity disclosures.
Forecast inputs include petrochemical resin price indices, silica regulation enforcement timelines, and hospitality construction pipeline tracking across the projection horizon. Segmentation dimensions span product format, finish type, end-user archetype, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules. Industry-specific inputs incorporate OSHA compliance cost trajectories and thin-slab freight density improvements.
Stress conditions across resin volatility bands, silica classification scenarios, and substitution elasticity thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and giga-project completion rates. Quarterly review of EPA inspection data, ECHA classification proceedings, and Saudi procurement tender awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Global Ti-6Al-4V Titanium Alloy Market
Advanced Alloys
Cermet Market
Advanced Alloys
Forgings Market
Advanced Alloys
Global Corrosion Resistant Alloys Market
Advanced Alloys
Master Alloys Market
Advanced Alloys
Metal Replacement Market
Advanced Alloys
Middle East and Africa Aluminum Casting Market
Advanced Alloys
Aluminum Die Casting Market
Advanced Alloys
Plastic-Metal Hybrids Market
Advanced Alloys
Automotive Aluminum Alloy (OE) Market
Advanced Alloys
Global Stainless Steel Forgings Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Global Ferroalloys Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Aluminum Composite Panel Market