
 Polyethylene Terephthalate (PET) Foam Market | 2026-2036
Polyethylene Terephthalate (PET) Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate (PET) Foam Market Analytics
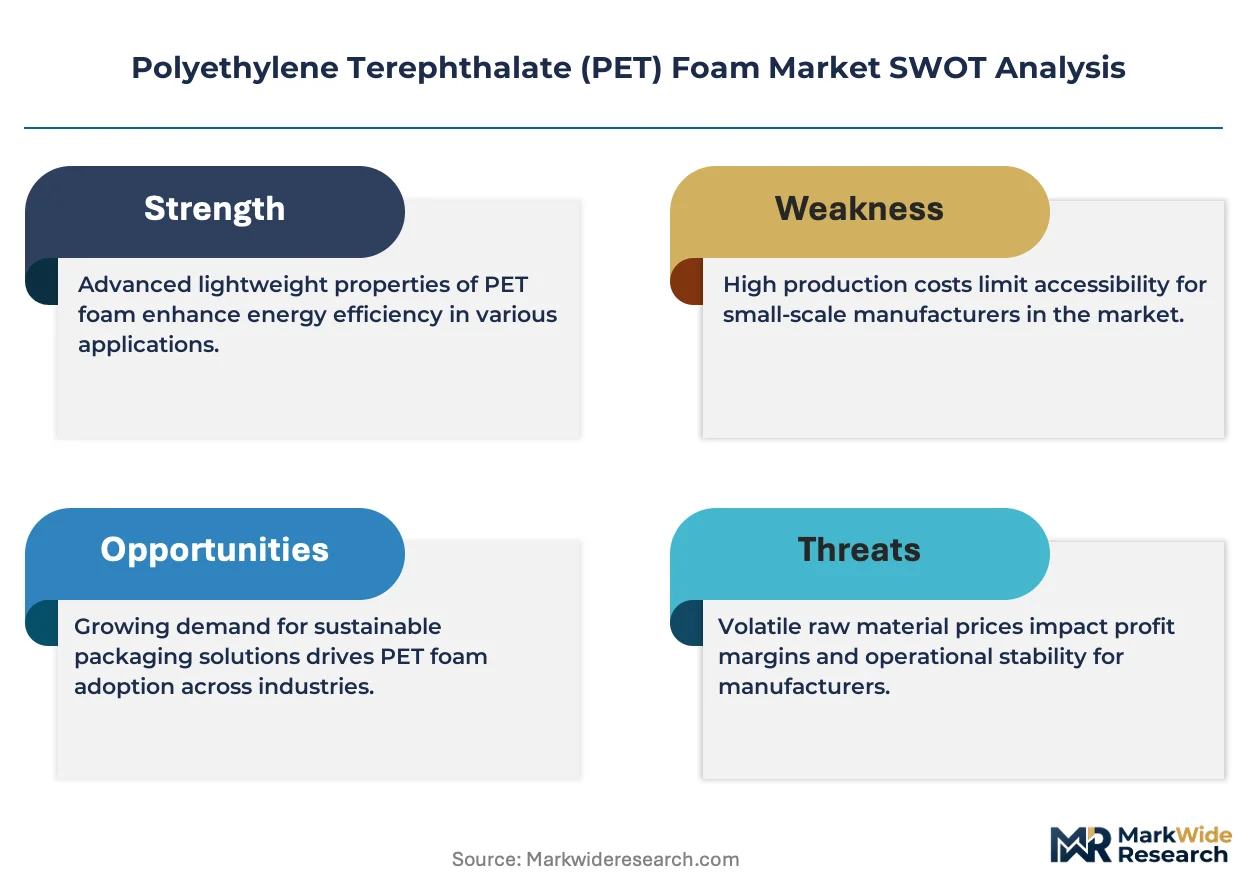
The PET foam market is pivoting on a widening split between aerospace-grade rigid foam commanding qualification-driven premiums and construction-grade sheets competing largely on density and delivered cost. Armacell leverages its European manufacturing footprint to dominate certified marine and wind core supply. DIAB Group anchors its position through captive testing facilities that accelerate customer qualification timelines. Changzhou Tiansheng New Materials Co. Ltd competes on scale in Asia-Pacific, shipping commodity sheets to regional packaging converters.
Polyethylene terephthalate foam is a closed-cell thermoplastic polymer structure produced through extrusion or batch foaming of recycled PET resin, typically achieving densities between 50 and 300 kg/m³ for structural core applications. Its primary industrial purpose centers on replacing balsa wood and PVC foam in fiber-reinforced composite sandwich panels where moisture resistance and consistent mechanical properties prove critical. Rigid foam leads volume due to entrenched wind blade specifications, while composite foam captures expanding margin pools as blade lengths exceed 90 meters and shear web complexity intensifies. Structural support applications outpace insulation in growth velocity, driven by rotor blade spar cap and nacelle housing demand.
REACH restricts residual monomer content and mandates substance-of-very-high-concern disclosure across European foam imports, directly elevating compliance costs for non-integrated suppliers. ECHA's evolving microplastic definition threatens fragmented PET foam waste streams, pushing processors toward closed-loop collection systems. FDA food-contact rules in the United States constrain recycled-content ratios for packaging-grade flexible foam, bifurcating technical requirements between structural and consumer applications. Stakeholders must weigh qualification lock-in against material substitution risk as bio-based polyamide and thermoplastic PET alternatives advance through OEM testing protocols.
Market Dynamics
Wind turbine OEMs are accelerating fiberglass-PET composite adoption as rotor diameters exceed 120 meters, forcing core material suppliers to certify higher-density foam grades for shear web integration while ECHA microplastic rules threaten post-industrial scrap economics.
Growth Catalysts
- EU Green Deal blade mandates:Renewable energy targets in Germany and Denmark require recyclable rotor materials, disqualifying balsa wood from new turbine platforms.
- Closed-cell thermoplastic chemistry:PET foam's moisture resistance eliminates rot risks in offshore wind foundations, extending blade service intervals.
- Rotor length escalation:Blade designs surpassing 90 meters demand structural cores with shear modulus above 85 MPa, a specification PET foam meets at lower mass than PVC alternatives.
Market Restraints
- Recycled PET flake volatility:Post-consumer bottle collection rates fluctuate with deposit scheme enforcement, compressing resin cost predictability for non-integrated foam producers.
- Aramid fiber substitution threat:High-performance blade tips increasingly specify thermoplastic aramid honeycomb for lightning strike protection, encroaching on PET foam's spar cap territory.
- REACH SVHC disclosure burden:ECHA's expanding candidate list forces reformulation of catalyst packages used in batch foaming, extending R&D cycles by 8-14 months.
Strategic Opportunities
- India PLI scheme alignment:Domestic content requirements for 30 GW annual wind installations create localized foam core demand that imports cannot satisfy.
- Rail interior panel retrofit:EN 45545-2 fire safety upgrades across European rolling stock fleets specify thermoplastic cores with smoke toxicity indices below 300.
- Digital twin integration:Blade manufacturers are embedding RFID tags in foam cores for lifecycle traceability, creating software-hardware service bundles.
Industry Challenges
- DNV-ST-0126 certification timelines:Type approval for new foam densities requires 18-month fatigue testing protocols that lock working capital in inventory.
- Multi-material bonding expertise:Vacuum infusion of PET cores with carbon fiber spar caps demands process engineers skilled in resin flow modeling, a talent pool concentrated at Vestas and Siemens Gamesa facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate (PET) Foam Market |
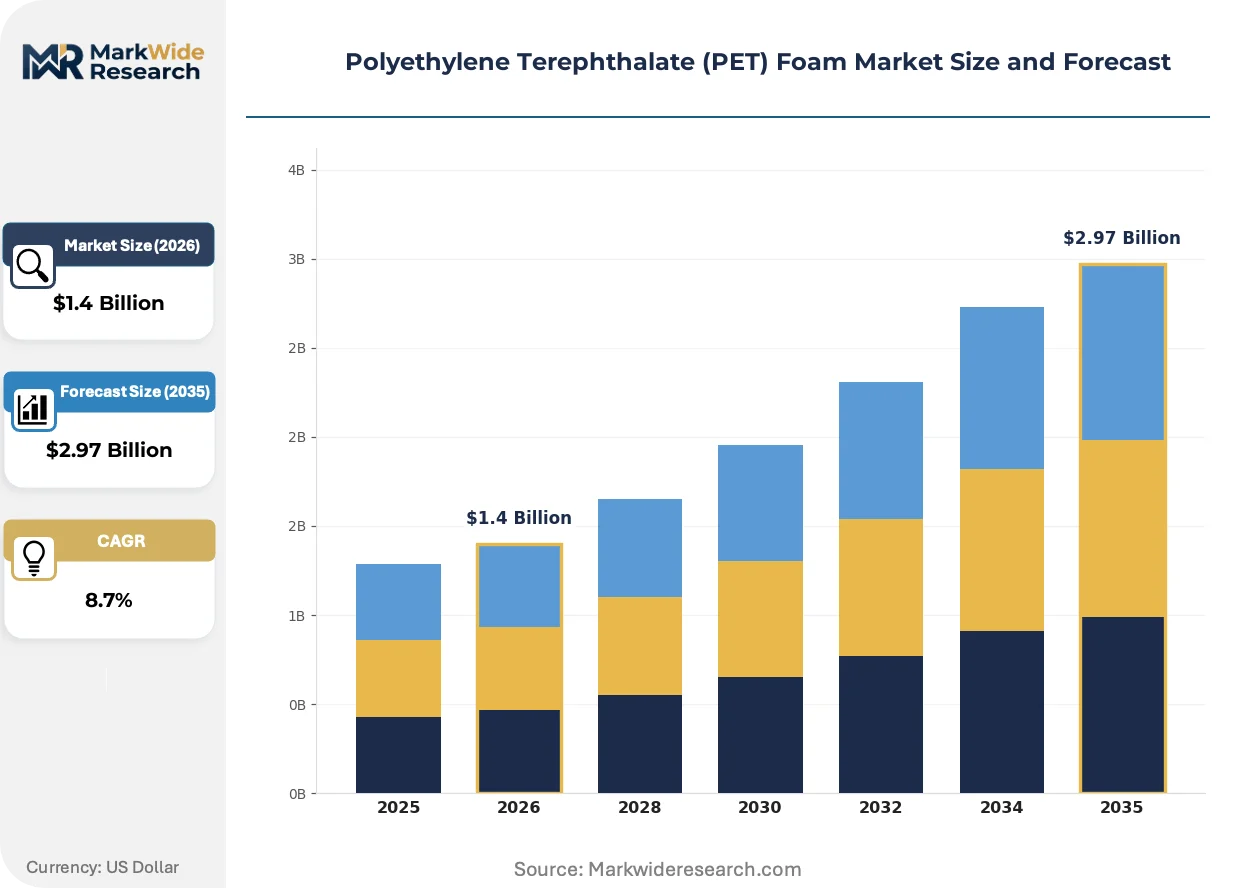
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Foam, Flexible Foam, Composite Foam, Sheets End User: Packaging, Automotive, Construction, Electronics Application: Insulation, Structural Support, Sound Absorption, Vibration Damping Distribution Channel: Direct Sales, Online Retail, Distributors, Trade Shows |
| Companies Covered | Armacell, 3A Composites, DIAB Group, Gurit Holding, Carbon-Core Corp., Changzhou Tiansheng New Materials Co. Ltd, Sekisui Plastics, Petro Polymer Shargh, CoreLite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate (PET) Foam Market Evolving Landscape
Material science advances and regulatory stringency are converging to compress qualification cycles while fragmenting the supplier base between aerospace-certified specialists and construction-grade commodity producers.
Continuous extrusion foaming with supercritical CO2 is consolidating process control across European suppliers. Armacell and DIAB Group have retrofitted German production lines to achieve cell size uniformity below 0.3 mm, a threshold Siemens Gamesa mandates for blades over 100 meters. This precision is compressing price premiums for aerospace-grade foam into wind energy applications.
REACH Article 33 disclosure obligations are tightening substance tracking through composite supply chains. ECHA's 2023 microplastic restriction proposal forces blade manufacturers to document foam waste streams from cutting operations, prompting investment in closed-loop granulation systems at rotor assembly plants in Denmark and Spain.
Specification bundling is altering procurement patterns among tier-one blade suppliers. Vestas and LM Wind Power now require foam vendors to deliver pre-shaped core kits with machined taper profiles, displacing raw sheet purchases. This shift concentrates contract awards on processors with five-axis CNC capacity, visible in supplier selection criteria for offshore projects in the North Sea.
Polyethylene Terephthalate (PET) Foam Market Segmentation
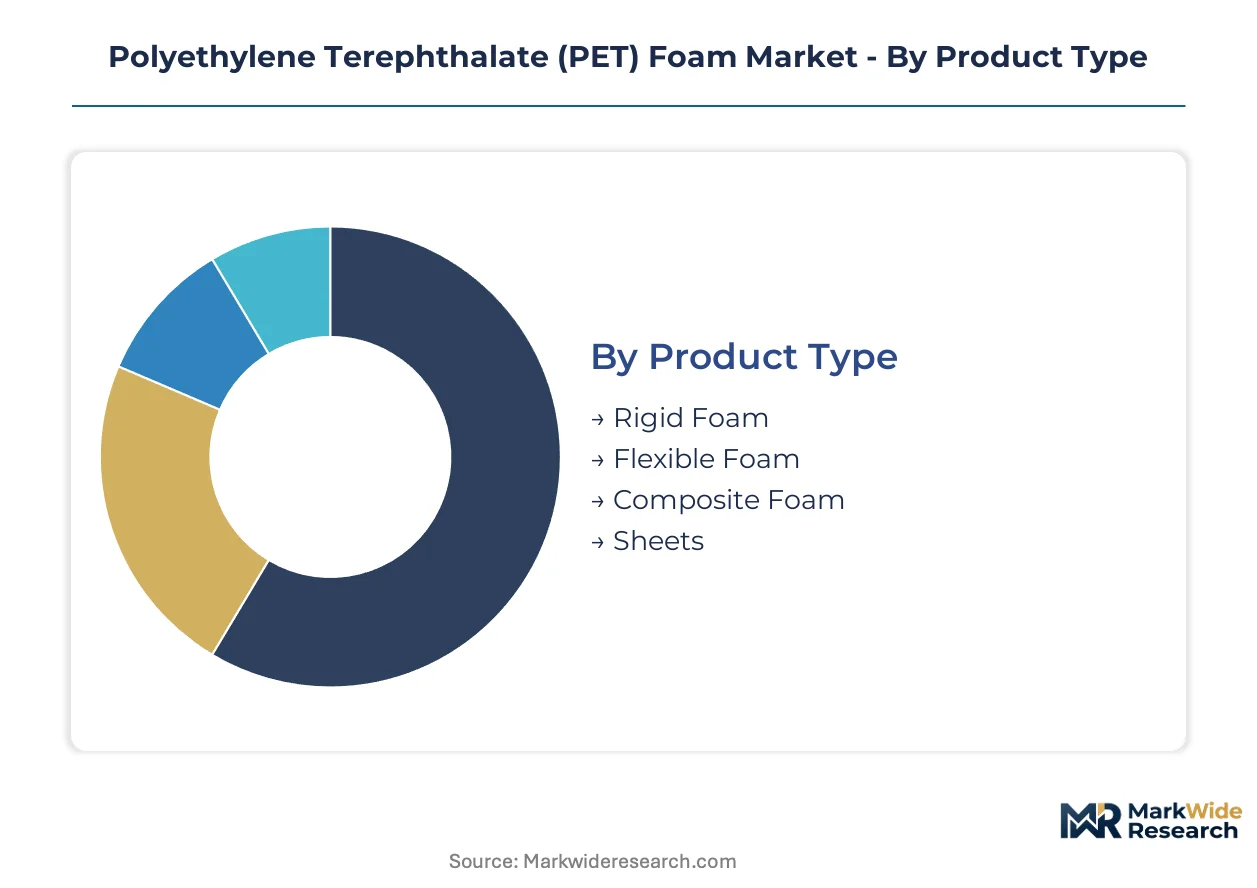
PET foam procurement patterns diverge sharply between qualification-intensive wind blade cores and commodity packaging sheets. Understanding these segment boundaries clarifies where margin pools concentrate versus where scale economics dominate competitive outcomes.
Product Type:
Blade manufacturers are upgrading from legacy PVC and balsa cores to PET foam as rotor lengths exceed 90 meters, triggering reformulation cycles across density grades and cell structures.
- Rigid Foam:Closed-cell thermoplastic structure achieving densities between 50 and 300 kg/m³ through extrusion or batch foaming of recycled PET resin. Demand concentrates in Germany and Denmark where Siemens Gamesa and Vestas blade assembly facilities specify rigid cores for spar cap integration in offshore turbines.
- Composite Foam:Engineered sandwich core material combining PET foam with fiberglass or carbon fiber skins for fiber-reinforced composite panels. Demand is climbing fastest in wind applications as blade lengths surpass 100 meters and shear web complexity intensifies, requiring higher shear modulus specifications that composite foam delivers.
- Flexible Foam:Lower-density open-cell or semi-rigid structures used in cushioning and protective packaging applications.
- Sheets:Flat-pressed or extruded panels serving construction and industrial insulation markets.
Rigid Foam sits at the top of the volume ranking, with Composite Foam climbing the fastest.
End User:
Cost tier differentiation separates aerospace-grade qualification requirements from construction commodity pricing, fragmenting supplier strategies across end-use categories.
- Packaging:Protective cushioning and void-fill applications leveraging recycled PET content for sustainability messaging. FDA food-contact rules constrain recycled-content ratios in the United States, bifurcating technical requirements between structural and consumer applications.
- Automotive:Interior trim panels, headliners, and NVH (noise, vibration, harshness) management components. EN 45545-2 fire safety upgrades across European rolling stock fleets specify thermoplastic cores with smoke toxicity indices below 300, creating retrofit demand for rail interior panels.
- Construction:Building insulation and structural sheathing competing on density and delivered cost.
- Electronics:Protective shipping solutions and component isolation for sensitive equipment.
Packaging commands the widest volume base, while Automotive gains share fastest on regulatory retrofit cycles.
Application:
Application selection hinges on whether moisture resistance or acoustic performance dominates the specification, with wind blade structural cores commanding premium qualification timelines.
- Structural Support:Load-bearing core material in sandwich panel constructions replacing balsa wood and PVC foam. Rotor blade spar cap and nacelle housing demand in Germany and Denmark is expanding most quickly as fiberglass-reinforced composites displace legacy materials.
- Insulation:Thermal barrier applications in building envelopes and industrial equipment.
- Sound Absorption:Acoustic management in transportation and industrial environments.
- Vibration Damping:Dynamic load isolation for machinery and vehicle components.
Structural Support leads absolute volume contribution, with Insulation expanding most quickly on building energy efficiency mandates.
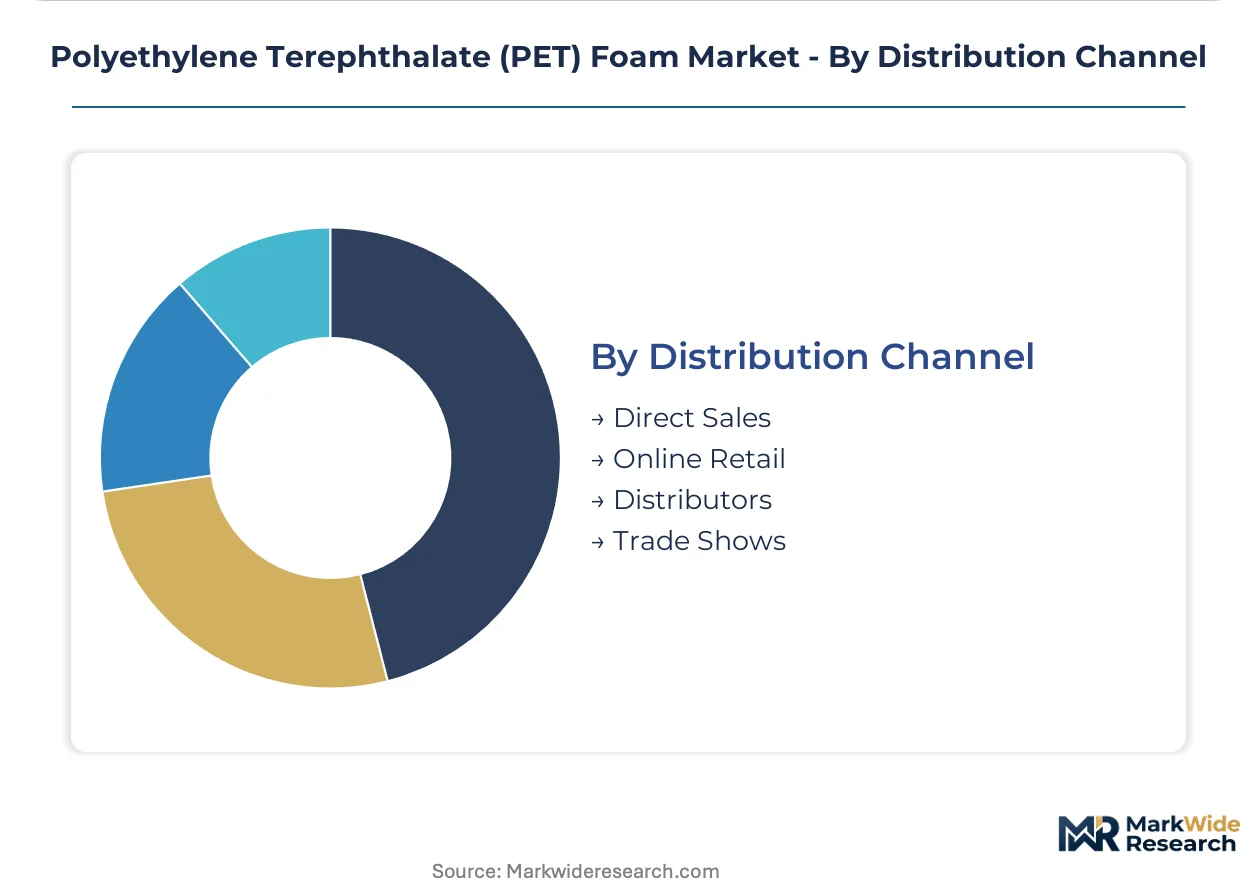
Distribution Channel:
Customer type fragmentation separates bulk blade manufacturers requiring just-in-time kit delivery from small-lot packaging converters sourcing through intermediaries.
- Direct Sales:Long-term supply agreements with wind turbine OEMs and tier-one blade manufacturers. Vestas and LM Wind Power now require foam vendors to deliver pre-shaped core kits with machined taper profiles, displacing raw sheet purchases and concentrating awards on processors with five-axis CNC capacity.
- Distributors:Regional intermediaries serving construction and packaging converters with standardized sheet products.
- Online Retail:E-commerce platforms for small-volume and prototype orders.
- Trade Shows:Industry exhibition channels for qualification and relationship development in aerospace and marine segments.
Direct Sales captures the highest value per ton, with Distributors maintaining the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Denmark concentrate wind blade manufacturing demand, while China scales commodity sheet production for Asia-Pacific packaging converters. Regulatory divergence between REACH-mandated Europe and FDA-constrained North America fragments compliance strategies across supplier networks.
Germany
Siemens Gamesa and Vestas blade assembly facilities in Rostock and Hamburg drive rigid foam consumption for offshore turbine spar caps. REACH Article 33 disclosure obligations force reformulation of catalyst packages used in batch foaming. The Northern Germany wind cluster concentrates five-axis CNC machining capacity for pre-shaped core kit delivery.
Denmark
LM Wind Power and Vestas headquarters in Aarhus and Ringkøbing anchor composite foam demand for blades exceeding 100 meters. EU Green Deal recyclable rotor material mandates disqualify balsa wood from new turbine platforms. Closed-loop granulation systems at Danish rotor assembly plants address ECHA microplastic documentation requirements.
China
Packaging converters in the Yangtze River Delta absorb commodity PET foam sheets at scale-driven price points. The country's dual carbon goals accelerate recycled-content requirements for thermoplastic structures. Changzhou-based fabricators supply regional wind energy projects with mid-density core materials.
United States
FDA food-contact rules constrain recycled-content ratios for packaging-grade flexible foam, bifurcating technical requirements from structural applications. Wind development in Texas and the Great Plains generates blade core demand that domestic converters partially serve. EPA oversight of industrial emissions shapes foam production facility siting decisions.
India
Domestic content requirements under the PLI scheme for 30 GW annual wind installations create localized foam core demand. The CEA mandates technical standards for renewable energy components that blade suppliers must meet. Gujarat and Tamil Nadu wind corridors attract foam processors seeking proximity to nacelle assembly operations.
Polyethylene Terephthalate (PET) Foam Market Competitive Landscape
Top-tier vendors anchor qualification-intensive wind and marine core supply, while mid-scale fabricators compete on sheet volume and regional logistics. The market structure concentrates around three strategic archetypes: European-certified specialists with captive testing facilities, Asia-Pacific scale producers serving commodity converters, and integrated petrochemical players leveraging resin supply security. Dominant competitive moves include backward integration into recycled PET flake sourcing and geographic expansion through five-axis CNC machining partnerships.
Within the European-certified specialist tier, Armacell and DIAB Group exemplify qualification-driven positioning through German manufacturing footprints and customer certification acceleration. Changzhou Tiansheng New Materials Co. Ltd occupies the Asia-Pacific scale-driven position, shipping commodity sheets to regional packaging converters. These three anchors illustrate how competitive positioning diverges between aerospace-grade premium capture and construction-grade cost leadership.
| Leading Market Players |
|---|
| Armacell |
| 3A Composites |
| DIAB Group |
| Gurit Holding |
| Carbon-Core Corp. |
| Changzhou Tiansheng New Materials Co. Ltd |
| Sekisui Plastics |
| Petro Polymer Shargh |
| CoreLite |
| Others |
Value Network & Pricing Analysis
Recycled PET flake indices in Hamburg and Rotterdam anchor foam producer cost structures, cascading through three-tier pricing stratification across aerospace-certified, wind-grade, and commodity packaging tiers. Buyers with captive resin sourcing command margin flexibility that non-integrated competitors cannot match, compressing price floors in construction-grade sheet markets.
Pricing Analysis
Capacity additions in China are reshaping price floors for commodity-grade PET foam sheets, forcing European specialists to emphasize certification premiums and just-in-time kit delivery. Contract-based long-term offtake dominates wind blade procurement, with price differentiation driven by DNV-ST-0126 qualification status and five-axis CNC machining capability. Cost compression in packaging-grade flexible foam intensifies as Yangtze River Delta converters expand extrusion throughput. Packaging converters exhibit highest price sensitivity, while offshore wind OEMs prioritize shear modulus consistency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale blade manufacturer demand through pre-shaped core kit delivery, while distributors serve regional construction and packaging converters with standardized sheet products. Supply concentrates in Germany, Denmark, and China, with raw material flows drawing from post-consumer bottle collection networks, supercritical CO2 feedstock, and fiberglass reinforcement suppliers. Single-source vulnerability around certified marine-grade foam creates qualification bottlenecks for new turbine platforms. Distribution runs through long-term supply agreements with Vestas and Siemens Gamesa facilities, supplemented by regional intermediaries for small-lot orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PET foam margins are expanding through rotor length escalation and REACH-driven qualification barriers that lock out commodity competitors. Cost-down drivers include continuous extrusion foaming retrofits and closed-loop granulation systems that recover cutting scrap value.
For Market Incumbents: To counter aramid fiber substitution in high-performance blade tips, deepen captive testing facility investment to compress DNV-ST-0126 certification timelines, and secure backward integration into recycled PET flake sourcing through European deposit scheme partnerships. For New Entrants and Emerging Players: Begin with India PLI scheme alignment for domestic wind installation content requirements, targeting Gujarat and Tamil Nadu nacelle assembly corridors with mid-density core materials. Rail interior panel retrofit demand under EN 45545-2 fire safety upgrades offers a secondary white-space entry point with lower qualification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with European-certified specialists possessing five-axis CNC machining partnerships and closed-loop waste handling infrastructure. Long-term viability hinges on ECHA microplastic rule compliance capabilities rather than scale economics alone. The signal to watch is specification bundling penetration rates among tier-one blade suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Flake | Captive resin supply secures margin stability against Hamburg-Rotterdam price volatility. |
| Five-Axis CNC Machining Partnership | Pre-shaped core kit capability meets Vestas and LM Wind Power procurement requirements. |
| Closed-Loop Granulation System Deployment | ECHA microplastic documentation compliance enables continued rotor assembly plant operation. |
| DNV-ST-0126 Certification Acceleration | Reduced type approval timelines unlock working capital from 18-month fatigue test inventory. |
| India PLI Scheme Manufacturing Footprint | Domestic content qualification captures 30 GW annual wind installation foam demand. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with blade manufacturing procurement leads, foam plant operations managers, wind turbine OEM platform engineers, and ECHA regulatory affairs specialists with secondary validation against customs trade data, SEC filings from listed composite material suppliers, wind industry association capacity databases, and REACH substance registration disclosures. Bottom-up segment sizing and top-down macro constraint checks were cross-referenced for triangulation.
Segment-weighting applied product type, end-use industry, application function, and distribution channel dimensions across the projection horizon, with density-grade and certification-tier splits modeled separately for wind energy versus construction demand pools. CAGRs were derived from installed wind capacity trajectories, rotor length evolution curves, and substitution elasticity estimates for balsa wood and PVC foam displacement. Forecast inputs included Siemens Gamesa and Vestas blade specification roadmaps, ECHA microplastic restriction implementation timelines, and India CEA technical standard mandates.
Several conditions sit outside the modeled scope, including abrupt REACH SVHC list expansions, breakthrough bio-based polyamide core commercialization, and major wind turbine OEM insolvency events. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Chlorinated Polyethylene Market
Polymers & Resins
Construction Polymer Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Polypropylene Copolymer Market
Polymers & Resins
Renewable PVDF Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Global Polyanionic Cellulose (PAC) Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Poly Alpha Olefin (PAO) Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Polymer Ingredients Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Europe Polyacrylamide Market