
 Global Solid Masterbatches Market | 2026-2036
Global Solid Masterbatches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Solid Masterbatches Market Foresight
Modular color-kit bundling is realigning how mid-sized packaging converters procure masterbatches, shifting from bulk single-color orders to smaller, application-specific assortments. Ampacet Corporation leverages its North American compounding network to anchor just-in-time delivery contracts with film extruders. Clariant AG differentiates through specialized additive packages for high-temperature engineering polymers. Tosaf Compounds Ltd. competes on regional manufacturing scale across Israel, Europe, and Asia to reduce freight exposure for commodity black and white grades.
Solid masterbatches are concentrated mixtures of pigments, additives, or functional agents dispersed in a polymer carrier resin, typically produced via twin-screw extrusion at loadings of 15-50% active content to color or modify base plastics during conversion. Color Masterbatch and Additive Masterbatch dominate value generation, with flame retardant and antibacterial variants capturing expanding margin pools as electrical and electronics producers face stricter fire safety and hygiene mandates. Polyethylene and Polypropylene carrier systems lead volume due to their compatibility with packaging films and automotive components, while polycarbonate-based grades command premium positioning in consumer goods and electronics housings.
REACH in Europe, FDA food-contact regulations in the United States, and GB standards under China's SAMR collectively define migration limits, substance authorization, and labeling requirements that determine which pigment chemistries and additive packages gain market access. ECHA's evolving candidate list for Substances of Very High Concern is forcing reformulation cycles, particularly for legacy halogenated flame retardants and certain heavy-metal pigments. Stakeholders must monitor regulatory divergence between jurisdictions, as compliance investments in one geography do not automatically transfer to others, and carrier resin selection increasingly hinges on multi-market registration status rather than pure cost or performance metrics.
Market Dynamics
Twin-screw extrusion throughput limits and ECHA's SVHC candidate list expansion are compressing formulation cycles, forcing compounders to revalidate carrier resin compatibility against migration limits before legacy additive packages lose market access.
Growth Catalysts
- REACH substance authorization:European packaging converters are accelerating halogen-free flame retardant adoption ahead of sunset dates for legacy brominated chemistries, expanding addressable volume for phosphorus-nitrogen additive packages.
- Automotive interior color consistency:German OEMs now specify delta-E tolerances below 0.5 for dashboard and door panel components, mandating closed-loop colorimetric dosing systems that favor pre-dispersed solid masterbatches over liquid alternatives.
- Antibacterial polymer demand:Healthcare device manufacturers in Japan and South Korea are integrating silver-ion and zinc-based masterbatches into high-touch surfaces under METI and MFDS hygiene mandates for medical equipment.
Market Restraints
- Titanium dioxide feedstock volatility:Sulphate-process rutile concentrate from Ukrainian and Russian suppliers faces export disruption, compressing margins for white masterbatch grades dependent on TiO2 loadings above 40%.
- Carrier resin concentration risk:Polyethylene and polypropylene pellet supply clusters in the US Gulf Coast and Middle East expose compounders to hurricane and geopolitical freight interruptions with limited near-term substitution options.
- Heavy metal pigment substitution:Cadmium and lead-based chemistries still deliver unmatched thermal stability in engineering polymer processing, but ECHA authorization requirements and FDA food-contact restrictions are forcing performance trade-offs in high-heat applications.
Strategic Opportunities
- India packaging film expansion:BIS certification alignment with FSSAI food-contact standards is enabling import substitution for color masterbatches previously sourced from European compounders, with domestic capacity scaling in Gujarat and Maharashtra.
- Recycled polymer carrier systems:Post-industrial polyethylene and polypropylene flake streams are achieving batch-to-batch consistency sufficient for non-critical packaging grades, opening circular feedstock positioning ahead of EU Green Deal recycled content mandates.
- Modular color-kit bundling:Mid-sized converters are abandoning bulk single-color procurement for application-specific assortments, creating service-layer differentiation opportunities around just-in-time inventory and technical color matching support.
Industry Challenges
- Colorimetric technician scarcity:Formulation laboratories lack sufficient spectrophotometry-trained chemists to support the shift from visual matching to CIELab-based quality control, extending new product development timelines.
- Multi-jurisdiction registration burden:Carrier resin selection now requires parallel FDA, EFSA, and GB standard compliance documentation, with substance-level disclosure timelines misaligned across regulatory calendars.
- Legacy extrusion line retrofit costs:Gravimetric dosing system installation for precise masterbatch let-down ratios demands capital allocation that smaller compounders struggle to justify against contract manufacturing alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Solid Masterbatches Market |
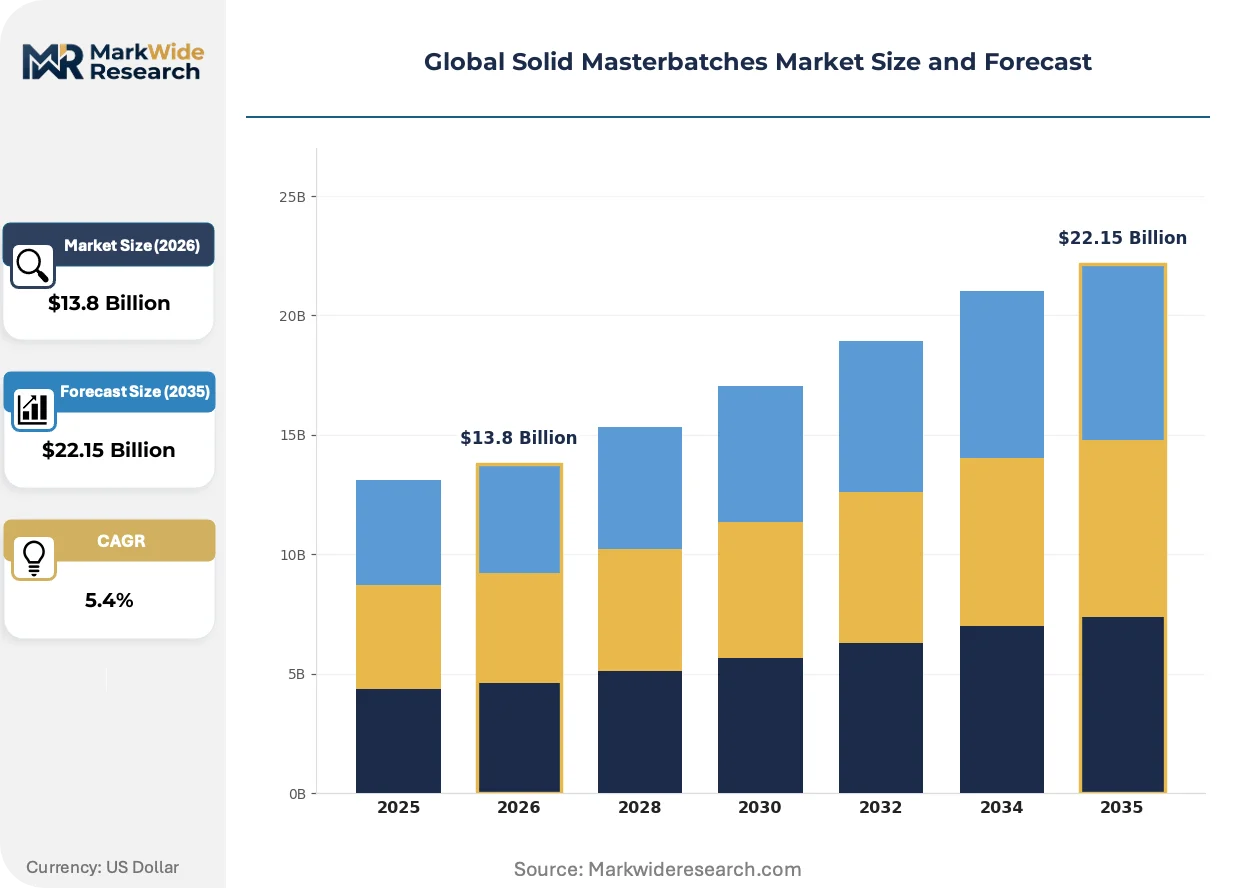
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $22.15 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Color Masterbatch, White Masterbatch, Black Masterbatch, Additive Masterbatch, Flame Retardant Masterbatch, Antibacterial Masterbatch Application: Packaging Films, Automotive Components, Construction Materials, Consumer Goods, Electrical & Electronics, Agriculture Polymer Type: Polyethylene, Polypropylene, Polystyrene, Polyvinyl Chloride, Polyethylene Terephthalate, Polycarbonate End User Industry: Packaging Manufacturers, OEMs, Plastic Product Manufacturers, Textile Firms, Electronics Producers, Household Appliances |
| Companies Covered | Clariant AG, BASF SE, Ampacet Corporation, Avient Corporation, Cabot Corporation, Plastika Kritis S.A., Tosaf Compounds Ltd., Penn Color Inc., Plastiblends India Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Solid Masterbatches Market Shifts & Advancements
Formulation science and procurement architecture are diverging from commodity scale toward precision-dispersed, application-specific solutions that compress development cycles and reconfigure converter-compounder relationships.
Micro-dosing pellet technology is modularizing. These sub-millimeter concentrate granules enable precise color and additive distribution at let-down ratios below 1%, reducing inventory carrying costs for film extruders running frequent color changeovers. Medical device manufacturers in Switzerland and Germany are adopting micro-dosing for small-batch pharmaceutical packaging with strict lot-to-lot consistency requirements.
ECHA's 2024-2025 SVHC roadmap revision is accelerating flame retardant reformulation. The candidate list expansion targets specific organophosphate esters used in electronics housings, compelling compounders to validate phosphorus-nitrogen alternatives against UL-94 and IEC 60695-11-10 test protocols. Electrical component producers in Poland and the Czech Republic are front-loading compliance investments ahead of potential authorization sunset dates.
Converter procurement patterns are fragmenting by application rather than consolidating by volume. Mid-sized packaging groups are disaggregating masterbatch sourcing across specialized compounders for barrier films, decorative layers, and sealant webs rather than relying on single-supplier portfolios. This behavioral shift is most pronounced in Italy's flexible packaging cluster around Bologna and Milan, where converters maintain parallel supplier relationships for commodity black-white grades versus high-value metallic and pearlescent effects.
Global Solid Masterbatches Market Segmentation
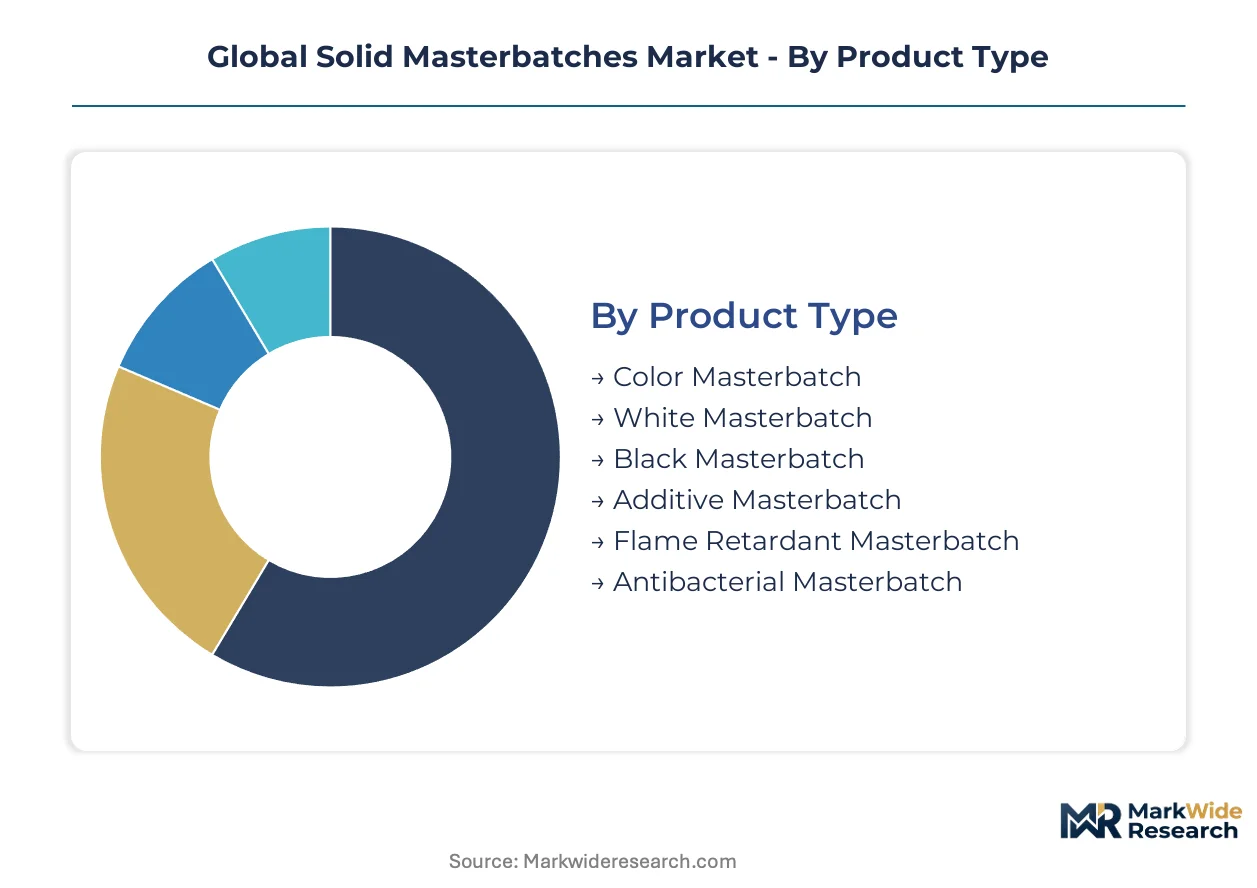
Solid masterbatches fragment across four distinct taxonomies that determine formulation complexity, regulatory exposure, and margin architecture. Each segmentation layer reveals divergent growth trajectories and competitive intensity patterns that reshape how compounders allocate R&D and manufacturing assets.
Product Type:
Volume concentrates in commodity colorants while premium pools concentrate in functional additives with regulatory moats.
- Color Masterbatch:Pigment concentrates dispersed in carrier resins at 15-50% loading, serving brand differentiation requirements across consumer-facing packaging. German automotive OEMs specify delta-E tolerances below 0.5 for interior components, mandating closed-loop colorimetric dosing systems that favor pre-dispersed solid formats over liquid alternatives.
- Additive Masterbatch:Functional packages incorporating UV stabilizers, antioxidants, or processing aids that modify polymer performance without visual alteration. REACH authorization timelines for legacy chemistries are compressing reformulation cycles, expanding addressable volume for halogen-free flame retardant and migration-compliant antioxidant packages.
- White Masterbatch:Titanium dioxide concentrates where sulphate-process rutile feedstock volatility from Ukrainian and Russian suppliers compresses margins for grades above 40% TiO2 loading.
- Black Masterbatch:Carbon black dispersions dominated by commodity competition, with regional manufacturing scale determining freight economics.
- Flame Retardant Masterbatch:Phosphorus-nitrogen alternatives gaining share as ECHA's SVHC candidate list expansion targets specific organophosphate esters in electronics housings.
- Antibacterial Masterbatch:Silver-ion and zinc-based formulations integrated into high-touch medical surfaces under METI and MFDS hygiene mandates in Japan and South Korea.
Today's leader: Additive Masterbatch. Tomorrow's challenger: Antibacterial Masterbatch.
Application:
End-use concentration follows packaging film expansion in Asia-Pacific and automotive specification tightening in Germany.
- Packaging Films:Flexible and rigid substrates for food, beverage, and pharmaceutical containment where barrier performance and shelf differentiation drive procurement. India's BIS-FSSAI alignment enables domestic capacity scaling in Gujarat and Maharashtra, displacing European import dependency.
- Automotive Components:Interior and exterior plastic parts subject to stringent color consistency and thermal stability requirements. German film extruders and tier suppliers maintain closed-loop quality systems that validate masterbatch performance across polycarbonate and polypropylene carrier systems.
- Construction Materials:Weather-resistant profiles and piping where UV stabilization and long-term color retention determine specification.
- Consumer Goods:Electronics housings and appliances facing dual pressure from ECHA SVHC restrictions and aesthetic differentiation demands.
- Electrical & Electronics:Components requiring UL-94 and IEC 60695-11-10 flame retardant compliance, with Polish and Czech producers front-loading reformulation investments.
- Agriculture:Mulch films and greenhouse sheeting where UV resistance and controlled degradation profiles align with seasonal use patterns.
Packaging Films anchor current volume. Automotive Components command the steepest expansion trajectory as electrification reshapes interior material specifications.
Polymer Type:
Carrier resin selection increasingly hinges on multi-market registration status rather than pure cost metrics.
- Polyethylene:Dominant carrier for flexible packaging films, with post-industrial flake streams achieving batch-to-batch consistency for circular feedstock positioning ahead of EU Green Deal mandates.
- Polypropylene:Automotive interior and appliance applications where talc-filled and glass-reinforced grades require specialized dispersion packages. US Gulf Coast and Middle East supply clusters expose compounders to hurricane and geopolitical freight interruptions.
- Polystyrene:Consumer goods and disposable applications facing regulatory pressure from single-use plastic restrictions.
- Polyvinyl Chloride:Construction profiles and medical tubing where plasticizer compatibility and thermal stability determine formulation.
- Polyethylene Terephthalate:Bottle and container applications requiring food-contact compliance under FDA and EFSA frameworks.
- Polycarbonate:Premium positioning in consumer electronics and automotive glazing where optical clarity and high-temperature processing command price premiums.
Polyethylene and Polypropylene jointly dominate tonnage. Polycarbonate delivers the highest margin per kilogram.
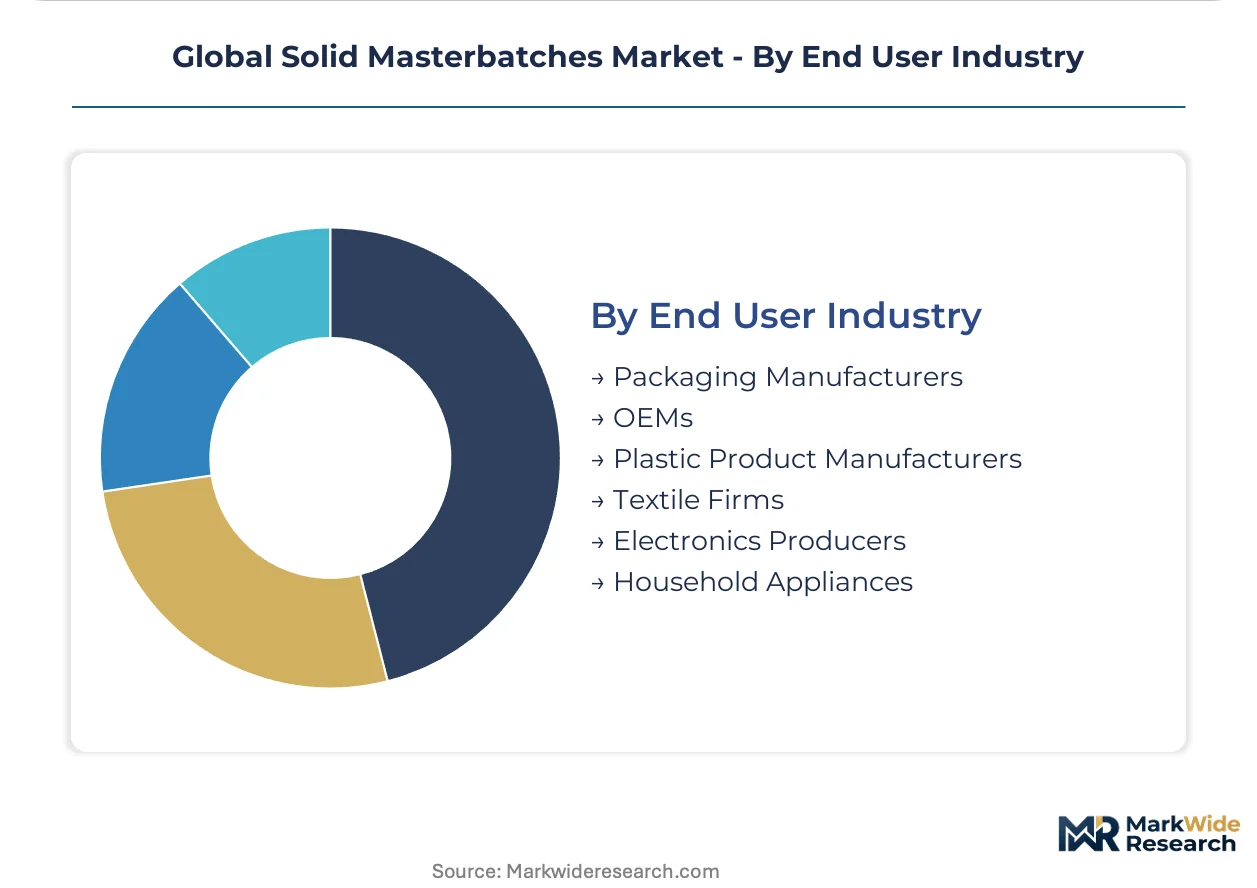
End User Industry:
Procurement authority is fragmenting from centralized bulk purchasing toward application-specific technical relationships.
- Packaging Manufacturers:Flexible and rigid converters across Italy's Bologna-Milan cluster who disaggregate sourcing across specialized compounders for barrier films, decorative layers, and sealant webs rather than consolidating with single suppliers.
- OEMs:Automotive and appliance producers specifying closed-loop colorimetric systems with delta-E tolerances that eliminate visual matching variability.
- Plastic Product Manufacturers:Mid-sized injection molders and extruders adopting modular color-kit bundling to reduce inventory carrying costs.
- Textile Firms:Fiber producers requiring UV-stable and color-fast masterbatches for outdoor and technical applications.
- Electronics Producers:Device manufacturers in Switzerland and Germany adopting micro-dosing pellet technology for small-batch pharmaceutical packaging with strict lot-to-lot consistency.
- Household Appliances:White goods producers balancing aesthetic differentiation against cost pressure in mature replacement markets.
Packaging Manufacturers drive volume concentration. Electronics Producers define the precision frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering traditions established modern masterbatch compounding during the 1960s polymer expansion, with twin-screw extrusion methods later adopted across Asia-Pacific packaging corridors. Today formulation expertise concentrates in specific national clusters where automotive specification and regulatory pressure intersect.
Germany
Automotive OEMs in Stuttgart and Munich mandate delta-E tolerances below 0.5 for interior components, driving closed-loop colorimetric dosing system adoption. REACH authorization timelines force halogen-free flame retardant reformulation ahead of sunset dates. The Rhine-Main industrial corridor hosts specialized additive compounders serving polycarbonate automotive glazing applications.
United States
Food-contact packaging converters under FDA jurisdiction expand color masterbatch procurement for shelf differentiation in beverage and prepared food segments. Hurricane exposure in the US Gulf Coast polyethylene supply cluster creates freight interruption risks for compounders dependent on regional resin feedstock. Film extruders in the Midwest maintain just-in-time delivery contracts with North American compounding networks.
China
GB standards under SAMR define migration limits for food-contact masterbatches, determining which pigment chemistries gain domestic market access. The Yangtze River Delta packaging film cluster scales domestic capacity for barrier and decorative layer applications. Electrical component manufacturers face dual pressure from domestic fire safety mandates and export market UL-94 compliance requirements.
India
BIS certification alignment with FSSAI food-contact standards enables import substitution for color masterbatches previously sourced from European suppliers. Domestic capacity scales in Gujarat and Maharashtra for flexible packaging film converters. The country's national pharmaceutical regulator maintains hygiene mandates that drive antibacterial masterbatch integration into medical device surfaces.
Japan
METI hygiene mandates for medical equipment propel silver-ion and zinc-based masterbatch adoption into high-touch healthcare surfaces. Precision dosing requirements from pharmaceutical packaging manufacturers favor micro-dosing pellet technology for small-batch production with strict lot-to-lot consistency. The Kanto region's electronics producers front-load flame retardant compliance investments against evolving IEC test protocol revisions.
Global Solid Masterbatches Market Competitive Landscape
The competitive structure tilts toward specialized additive compounders with regulatory navigation capabilities. Twin-screw extrusion throughput limits and ECHA's SVHC candidate list expansion compress formulation cycles, favoring players with parallel FDA, EFSA, and GB standard compliance documentation. Three archetypes dominate: diversified chemical conglomerates with polymer carrier integration, regional manufacturing specialists optimizing freight economics for commodity grades, and precision-dispersion boutiques serving automotive delta-E specifications. Capacity expansion and modular color-kit service architecture represent the dominant competitive vectors.
Among Swiss and German chemical conglomerates, Clariant AG and BASF SE exemplify the diversified archetype with multi-market registration capabilities spanning engineering polymer additive packages. Ampacet Corporation anchors the North American regional specialist position through compounding network density and just-in-time delivery contracting with film extruders. These three represent distinct strategic postures: regulatory breadth, geographic proximity, and service-layer bundling respectively.
| Leading Market Players |
|---|
| Clariant AG |
| BASF SE |
| Ampacet Corporation |
| Avient Corporation |
| Cabot Corporation |
| Plastika Kritis S.A. |
| Tosaf Compounds Ltd. |
| Penn Color Inc. |
| Plastiblends India Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between REACH-compliant additive packages and legacy formulations splits pricing power across European compounders and commodity importers. This bifurcation concentrates margin capture with multi-jurisdiction registrants while pressuring spot-market suppliers dependent on unverified carrier resins.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels reflects delta-E precision, regulatory registration depth, and volume commitment scale. Premium tiers command spreads based on closed-loop colorimetric dosing compatibility and parallel FDA-EFSA-GB documentation. Cost compression in white masterbatch grades intensifies because sulphate-process rutile feedstock from Ukrainian and Russian suppliers faces sustained export disruption. Mid-sized packaging converters exhibit highest price sensitivity, while German automotive OEMs prioritize specification adherence over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with US Gulf Coast and Middle East polyethylene and polypropylene pellet clusters exposed to hurricane and geopolitical freight interruptions. Raw material dependencies center on titanium dioxide concentrates, carbon black dispersions, and phosphorus-nitrogen flame retardant chemistries. Regulatory restriction risk from ECHA's SVHC candidate list expansion compounds substitution timeline pressures. Distribution runs through regional compounding networks with just-in-time contracting, favoring geographic proximity over global sourcing optimization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ECHA's evolving SVHC authorization timelines drive systematic reformulation demand across flame retardant and pigment portfolios.
For Market Incumbents: Hedge against carrier resin concentration risk by diversifying feedstock sourcing beyond US Gulf Coast and Middle East clusters. Deepen backward integration into post-industrial polyethylene and polypropylene flake streams to secure circular feedstock positioning ahead of EU Green Deal mandates. Prioritize spectrophotometry technician training programs to compress new product development timelines threatened by formulation laboratory capacity constraints. For New Entrants and Emerging Players: Regional manufacturing specialists in India's Gujarat and Maharashtra packaging corridors offer partnership pathways for import substitution plays. Modular color-kit bundling service architectures present the most penetrable white-space target, displacing bulk single-color procurement relationships with mid-sized converters. Lead with technical color matching support and just-in-time inventory capabilities rather than commodity scale. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-jurisdiction registration documentation creates compliance moats that smaller compounders cannot replicate. Long-term viability favors precision-dispersion boutiques serving automotive delta-E specifications and diversified chemical conglomerates with parallel FDA, EFSA, and GB standard capabilities. Watch ECHA authorization sunset date announcements as inflection indicators for phosphorus-nitrogen additive package demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Polymer Feedstock | Captures circular positioning ahead of EU Green Deal recycled content mandates for packaging grades. |
| Multi-Jurisdiction Regulatory Registration | Secures market access across FDA, EFSA, and GB standard frameworks without reformulation penalties. |
| Micro-Dosing Pellet Technology Deployment | Addresses pharmaceutical packaging precision requirements in Switzerland and Germany with sub-millimeter concentrate granules. |
| Regional Manufacturing Footprint Expansion | Reduces freight exposure for commodity black and white grades across Israel, Europe, and Asia. |
| Spectrophotometry Training Program Investment | Alleviates colorimetric technician scarcity compressing formulation laboratory capacity. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary engagement encompassed masterbatch compounding plant managers, automotive OEM procurement specialists, flexible packaging converter technical directors, and regulatory affairs leads navigating ECHA authorization timelines. Secondary validation drew from customs and trade flow data, SEC 10-K filings of listed chemical conglomerates, REACH substance authorization databases, and automotive production cluster reports. Bottom-up volume modeling triangulated against top-down value aggregation across carrier resin, pigment chemistry, and end-use application dimensions.
Historical reference periods anchored projection parameters to established twin-screw extrusion throughput patterns and regulatory implementation cycles. Segmentation modeling spanned product type tiers, polymer carrier systems, application-specific performance requirements, and geographic production hub concentrations. CAGRs derived from slope analysis of disclosed capacity expansions and substitution elasticity estimates for halogen-free flame retardant chemistries. Forecast inputs incorporated ECHA SVHC roadmap revision schedules and BIS-FSSAI alignment timelines for Indian import substitution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to titanium dioxide feedstock disruption duration, REACH authorization sunset date acceleration, and hurricane frequency in US Gulf Coast resin supply clusters. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
Medical Styrenic Polymers Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Propylene Terpolymer Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Global Polyphenylene Market