
 Global Fluoropolymer Market | 2026-2036
Global Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fluoropolymer Market Analysis
The EU F-Gas Regulation is expanding compliance obligations for fluorinated polymer producers, forcing reformulation of certain resin grades and accelerating investment in low-GWP alternatives. Daikin Industries sustains technology leadership through captive chlorodifluoromethane supply and proprietary melt-processable resin platforms. Solvay anchors European demand with its specialty polyamide-fluoropolymer hybrids for chemical processing equipment. Gujarat Fluorochemicals competes on integrated refrigerant-to-polymer economics at its Gujarat manufacturing complex.
Fluoropolymers comprise carbon-fluorine backbone polymers characterized by electronegativity-driven chemical inertness, with PTFE exhibiting a melting point near 327 degrees Celsius and dielectric constants below 2.1 across most grades. These properties enable service in aggressive chemical environments, high-frequency electrical systems, and extreme thermal cycling applications where hydrocarbon polymers degrade. PTFE dominates volume consumption in linings and seals for chemical processing infrastructure, while PVDF leads growth in lithium-ion battery binders and photovoltaic backsheet films where fluorinated surface stability commands premium pricing. FEP and PFA grades capture margin pools in semiconductor fabrication tubing and medical device catheters requiring melt-processability that PTFE lacks.
REACH restrictions on per- and polyfluoroalkyl substances are reshaping product registration requirements across Europe, while China's MEE enforces stricter emissions controls at fluorochemical production bases in Zhejiang and Shandong provinces. The US EPA scrutinizes long-chain perfluorinated compounds under TSCA Section 5, creating uncertainty for legacy PTFE feedstock pathways. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded formulation investments and secure alternative chemistries before supply constraints emerge.
Market Dynamics
REACH restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer producers to reformulate resin grades and accelerate investment in alternative chemistries before supply constraints emerge across European value chains.
Growth Catalysts
- Aerospace fuel system specifications:Commercial aircraft manufacturers are specifying fluoropolymer-lined fuel hoses and seals to meet FAA fire-resistance standards, expanding material volumes in narrow-body and wide-body production backlogs.
- EU F-Gas Regulation compliance:The regulation's phase-down of hydrofluorocarbons is redirecting capital toward low-GWP fluoropolymer production processes that maintain performance in chemical processing equipment.
- Lithium-ion battery binder chemistry:PVDF binder demand is accelerating as Chinese cell manufacturers scale gigafactory capacity requiring electrode adhesion stability across wide electrochemical windows.
Market Restraints
- Fluorspar supply concentration:Acid-grade fluorspar mining concentrates in Mexico, China, and South Africa, exposing resin producers to export quota volatility and geopolitical supply interruptions.
- TSCA Section 5 review timelines:The US EPA's scrutiny of long-chain perfluorinated compounds extends new substance approval periods, freezing legacy PTFE feedstock pathway investments.
- Fluorinated gas handling costs:Chlorodifluoromethane and tetrafluoroethylene monomer production requires emissions controls and destruction technology that elevates capital intensity versus hydrocarbon polymer alternatives.
Strategic Opportunities
- India chemical processing infrastructure:The country's PLI scheme for specialty chemicals and expanding refinery capacity create demand for corrosion-resistant linings in chlor-alkali and agrochemical production units.
- Melt-processable resin platforms:FEP and PFA grades are capturing semiconductor fabrication tubing applications where PTFE's sintering limitations exclude it from high-purity fluid delivery systems.
- Photovoltaic backsheet films:PVDF fluorinated films are displacing PET in utility-scale solar installations where UV resistance and hydrolytic stability command 15-20 year performance warranties.
Industry Challenges
- Fluoropolymer compounding expertise:The limited pool of technicians capable of processing high-melt-viscosity resins without thermal degradation constrains capacity expansion at contract manufacturers.
- Cross-jurisdictional registration divergence:The gap between EU REACH substance restrictions, US TSCA Section 5 requirements, and China's MEE emissions standards forces parallel compliance investments without harmonized testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fluoropolymer Market |
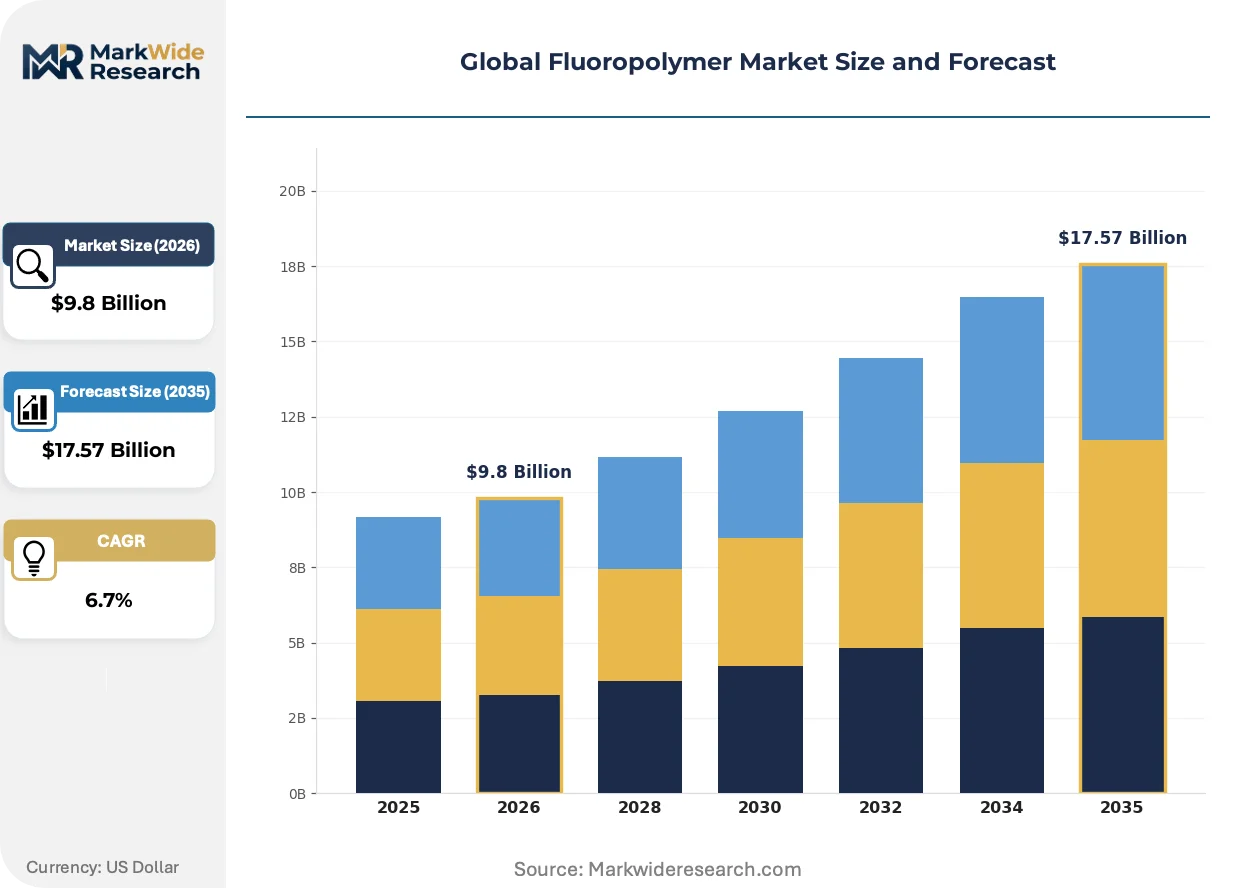
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, PVDF Application: Coatings, Seals, Gaskets, Electrical Insulation Form: Films, Sheets, Rods, Tubes End User: Aerospace, Chemical Processing, Electronics, Medical |
| Companies Covered | The Chemours Company, Daikin Industries Ltd., Dongyue Group Ltd., Solvay SA, 3M Company, Arkema Group, AGC Chemicals, Gujarat Fluorochemicals Limited, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fluoropolymer Market Emerging Trajectories
Fluoropolymer technology trajectories are diverging between legacy PTFE dominance in industrial linings and melt-processable grades capturing precision applications in electronics and medical devices.
Perfluoroalkoxy alkane (PFA) tubing is overtaking stainless steel in semiconductor high-purity chemical delivery systems. Chip fabrication facilities in Taiwan and South Korea are specifying PFA for sulfuric acid and hydrogen peroxide lines where metallic ion contamination risks yield loss. The substitution is overtaking conventional welded steel installations in sub-7nm process nodes where parts-per-trillion purity thresholds are mandatory.
The EU F-Gas Regulation's 2024 amendment tightens hydrofluorocarbon quotas and mandates leak detection in fluorochemical production equipment. European resin producers are retrofitting cracking furnaces with real-time monitoring systems to maintain operating permits. Chemical processing equipment manufacturers in Germany and Belgium face compressed certification timelines for new fluoropolymer-lined vessels.
Battery cell manufacturers are consolidating binder procurement around PVDF specifications that integrate with dry electrode coating processes. Chinese cathode producers are qualifying fluoropolymer binders that eliminate solvent recovery costs versus conventional slurry methods. The qualification cycle compression is most visible in Ningbo and Changzhou manufacturing clusters where cell makers are vertically integrating binder formulation capabilities.
Global Fluoropolymer Market Segmentation
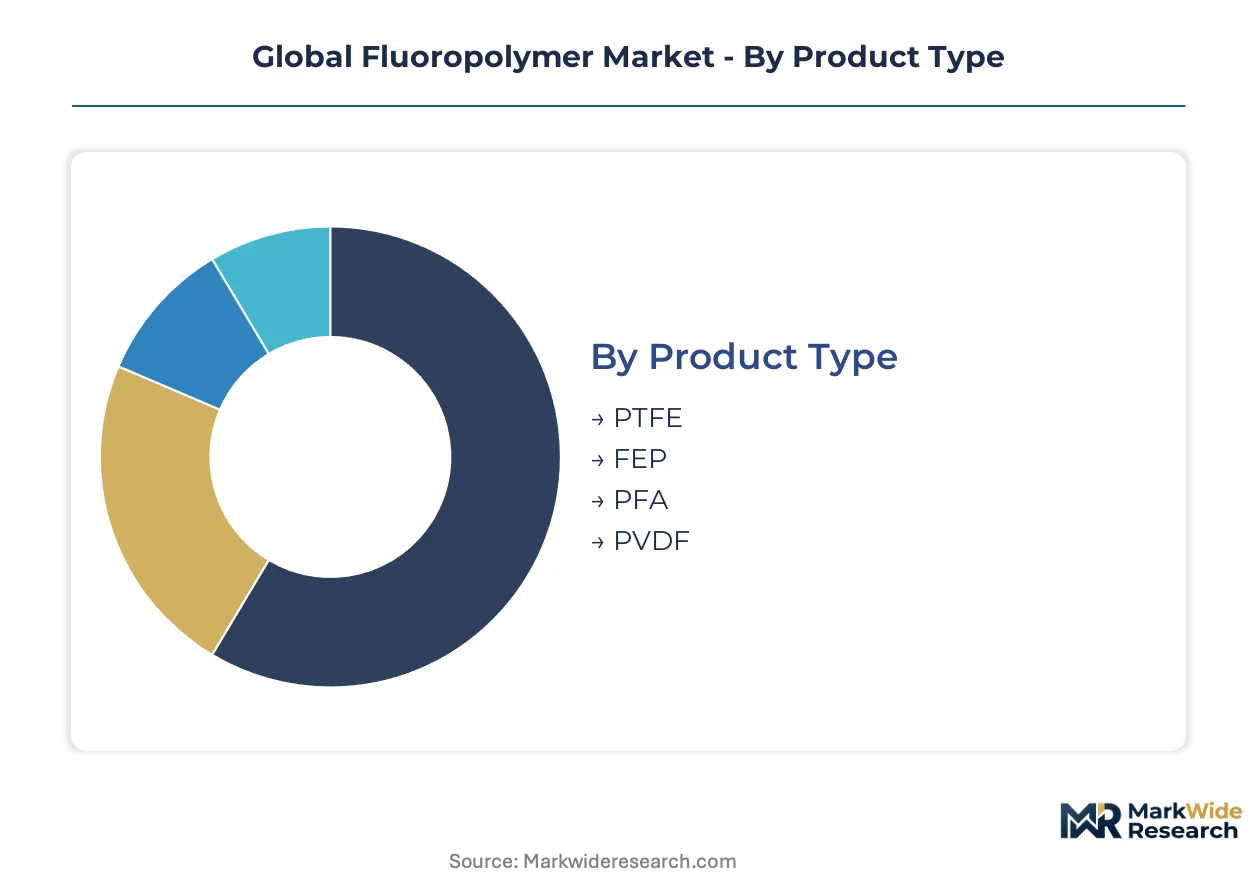
Fluoropolymer value chains fragment across molecular architecture, processing method, and end-use performance thresholds. Each segmentation axis carries distinct capital requirements, regulatory exposure, and margin structures that determine supplier positioning.
Product Type:
PTFE and PVDF demand the heaviest upfront investment in monomer cracking capacity and emissions control infrastructure, while melt-processable grades require precision polymerization reactor systems.
- PTFE:The carbon-fluorine backbone achieves a melting point near 327 degrees Celsius with dielectric constants below 2.1. Demand concentrates in Chinese chemical processing infrastructure where corrosion-resistant linings for chlor-alkali plants require sintered PTFE sheets rated for aggressive acid service.
- PVDF:Semicrystalline fluoropolymer with superior piezoelectric properties and electrochemical stability. Chinese lithium-ion battery manufacturers in Ningbo and Changzhou are scaling electrode binder specifications that integrate with dry coating processes, eliminating solvent recovery costs.
- FEP:Melt-processable copolymer enabling extrusion of thin-wall tubing for semiconductor chemical delivery systems. FDA compliance for medical device applications adds regulatory testing overhead.
- PFA:Perfluoroalkoxy resin combining PTFE's chemical resistance with thermoplastic processability. Taiwan and South Korea chip fabrication facilities specify PFA for sulfuric acid lines where metallic ion contamination risks yield loss at sub-7nm nodes.
Most installed capacity flows through PTFE. Expansion is steepest in PVDF.
Application:
Application selection determines whether suppliers compete on formulation expertise or fabrication precision, with coatings demanding compounding know-how and electrical insulation requiring cleanroom processing.
- Coatings:PTFE-based industrial finishes protect chemical processing vessels and automotive fasteners. German equipment manufacturers face compressed certification timelines under EU F-Gas Regulation amendments for new fluoropolymer-lined vessel approvals.
- Seals:Compression-molded rings and O-rings for aerospace fuel systems and semiconductor pumping equipment. FAA fire-resistance standards for commercial aircraft are expanding material volumes in narrow-body and wide-body production backlogs.
- Gaskets:Sheet goods for flange connections in aggressive chemical environments. REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of certain resin grades for European process industries.
- Electrical Insulation:Wire and cable jacketing for high-frequency signal transmission and thermal endurance. 5G infrastructure deployment and EV powertrain wiring are concentrating demand in cable extrusion facilities.
Coatings absorb the largest share of resin tonnage. Electrical insulation is climbing the fastest as high-voltage EV architectures proliferate.
Form:
Form factor selection locks in downstream processing economics, with films requiring biaxial orientation lines and tubes demanding precision extrusion with cleanroom finishing.
- Films:PVDF fluorinated films are displacing PET in utility-scale solar installations where UV resistance and hydrolytic stability command extended performance warranties. Biaxial stretching equipment represents significant capital commitment.
- Sheets:Compression-molded PTFE plates for chemical tank linings and gasketing stock. Thickness tolerance control determines qualification for semiconductor fab construction specifications.
- Rods:Extruded or molded bar stock for machining custom seals and bearings. CNC capability at contract manufacturers is expanding to serve medical device prototyping requirements.
- Tubes:PFA and FEP extrusions for high-purity fluid handling. Limited pools of technicians capable of processing high-melt-viscosity resins without thermal degradation constrain capacity expansion.
Sheets dominate tonnage throughput. Films are expanding most quickly on photovoltaic backsheet demand.
End User:
End-user concentration shapes technical service requirements and regulatory documentation burdens, with aerospace and medical demanding full material traceability.
- Aerospace:Fuel system hoses, seals, and wire insulation meeting FAA fire-resistance and smoke-toxicity standards. OEM qualification cycles extend 18-36 months for new resin formulations.
- Chemical Processing:Corrosion-resistant linings, gaskets, and pump components for chlor-alkali, agrochemical, and specialty chemical production. India's PLI scheme for specialty chemicals is creating demand for fluoropolymer-lined vessels in refinery expansion projects.
- Electronics:Semiconductor fabrication tubing, battery binders, and high-frequency cable insulation. Taiwan and South Korea wafer fabs are specifying PFA for parts-per-trillion purity chemical delivery systems.
- Medical:Catheters, implantable device components, and pharmaceutical processing equipment. FDA device master file submissions and USP Class VI biocompatibility testing add regulatory overhead.
Chemical processing anchors volume consumption. Electronics is gaining share fastest on semiconductor and battery manufacturing scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoropolymer production originated in the United States during the Manhattan Project, with DuPont's 1945 commercialization of PTFE establishing the industry's technical foundations. Manufacturing subsequently dispersed across Germany, Japan, and China as applications multiplied in chemical processing and electronics.
United States
Aerospace fuel system specifications and semiconductor fabrication equipment sustain demand for high-purity fluoropolymer tubing. The EPA scrutinizes long-chain perfluorinated compounds under TSCA Section 5, extending approval timelines for new resin formulations. Texas and Louisiana host concentrated chemical processing infrastructure where corrosion-resistant linings protect chlor-alkali and petrochemical production units.
China
Lithium-ion battery binder chemistry and photovoltaic backsheet films drive PVDF consumption as domestic cell manufacturers scale gigafactory capacity. The MEE enforces stricter emissions controls at fluorochemical production bases in Zhejiang and Shandong provinces. Ningbo and Changzhou manufacturing clusters are vertically integrating binder formulation capabilities to eliminate solvent recovery costs.
Germany
Chemical processing equipment manufacturers specify fluoropolymer-lined vessels for specialty chemical and agrochemical production. The EU F-Gas Regulation's 2024 amendment tightens hydrofluorocarbon quotas and mandates leak detection in fluorochemical production equipment. Industrial clusters in North Rhine-Westphalia and Bavaria face compressed certification timelines for new fluoropolymer-lined vessel approvals.
Japan
Semiconductor fabrication tubing and high-frequency electrical insulation command premium specifications for sub-7nm process nodes. METI oversees chemical substance management under the Act on the Evaluation of Chemical Substances. Kyushu and the Tokyo metropolitan area concentrate wafer fabrication facilities specifying PFA for parts-per-trillion purity chemical delivery systems.
India
The PLI scheme for specialty chemicals and expanding refinery capacity create demand for corrosion-resistant linings in chlor-alkali and agrochemical production units. The BIS mandates quality certification for imported fluoropolymer resins used in critical infrastructure. Gujarat's manufacturing complex leverages integrated refrigerant-to-polymer economics to serve domestic chemical processing expansion.
Global Fluoropolymer Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the fluoropolymer value chain, with integrated chlorodifluoromethane crackers holding structural advantages in monomer supply security. The market consolidates around three to five dominant resin producers controlling proprietary polymerization reactor technology and emissions control infrastructure. Two strategic archetypes predominate: integrated chemical conglomerates with captive fluorspar-to-resin operations, and specialty polymer houses focused on melt-processable grades for precision applications. Competitive dynamics center on backward integration into acid-grade fluorspar mining and forward partnerships with semiconductor fabrication equipment OEMs.
Among integrated chemical producers, Daikin Industries and Solvay exemplify divergent geographic anchoring strategies. Daikin sustains technology leadership through captive chlorodifluoromethane supply and proprietary melt-processable resin platforms. Solvay anchors European demand with specialty polyamide-fluoropolymer hybrids for chemical processing equipment. Gujarat Fluorochemicals occupies a position within the emerging-market integrated tier, competing on captive economics at its Gujarat manufacturing complex.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries Ltd. |
| Dongyue Group Ltd. |
| Solvay SA |
| 3M Company |
| Arkema Group |
| AGC Chemicals |
| Gujarat Fluorochemicals Limited |
| Honeywell International Inc. |
| Others |
Supply Flow & Price Mechanics
Melt-processable resin platforms are displacing legacy PTFE in precision applications, simultaneously compressing margins on commodity-grade sintered products while concentrating supply power among reactor-technology holders in Japan and Germany. This technology transition feeds back into raw material procurement, as chlorodifluoromethane feedstock security now determines pricing power more than scale economies.
Pricing Analysis
Three-tier pricing structure across semiconductor-grade, chemical-processing, and industrial-commodity levels dominates fluoropolymer transactions. Price differentiation rests on certification tier — FDA device master files versus standard industrial compliance — and captive chlorodifluoromethane integration. Cost compression in commodity PTFE sheet goods is intensifying because Chinese producers are flooding chlor-alkali lining markets; battery-grade PVDF commands the lowest price sensitivity due to electrode performance non-substitutability.
Supply Chain Analysis
Technician scarcity in precision extrusion constrains capacity expansion at contract manufacturers across Taiwan, South Korea, and Japan. Fluorspar mining concentrates in Mexico, China, and South Africa, while tetrafluoroethylene monomer production draws from integrated refrigerant crackers. Single-source vulnerability runs through acid-grade fluorspar export quotas. Distribution runs through authorized distributor networks serving semiconductor fabrication and chemical processing OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluoropolymer market reads as a late-cycle quality story where sub-7nm semiconductor node requirements and FAA fire-resistance specifications are filtering demand toward premium melt-processable grades with full material traceability.
For Market Incumbents: Cement technology leadership by retrofitting cracking furnaces with real-time F-Gas monitoring to preserve European operating permits, and anchor chlorodifluoromethane supply through backward integration into fluorspar offtake agreements. Emerging Chinese battery-grade PVDF producers threaten margin pools in electrode binders. For New Entrants and Emerging Players: Specialty chemical distributors in India offer the most penetrable channel partner type for corrosion-resistant lining specifications under the PLI scheme. Target dry-electrode coating qualification cycles at Ningbo and Changzhou cell manufacturers. Qualify FEP tubing for semiconductor chemical delivery as the fastest path to premium pricing. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap resin compounders lacking captive monomer supply but holding FDA device master files and USP Class VI certifications. Five-to-ten year viability hinges on REACH-compliant chemistry transitions. Monitor EU F-Gas quota allocation decisions as the inflection signal for European production asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Mining | Secures acid-grade feedstock against Mexican and Chinese export quota volatility. |
| Green Manufacturing Transition | MEE emissions compliance in Zhejiang and Shandong preserves operating permits. |
| Long-term Supply Agreement | Taiwan and South Korea wafer fabs lock in PFA tubing volumes for sub-7nm nodes. |
| Capacity Expansion | Gujarat complex scales refrigerant-to-polymer economics for Indian chemical processing. |
| Joint Venture | European equipment OEMs partner for fluoropolymer-lined vessel certification acceleration. |
Methodological Framework
Direct dialogue with fluoropolymer plant managers, procurement leads at semiconductor OEMs, technical R&D directors, and distribution channel partners grounded qualitative findings. Secondary validation drew from SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and EPA TSCA Section 5 submissions. Bottom-up resin grade demand modeling triangulated against top-down chemical processing and electronics capex forecasts.
Bottom-up volume modeling by product architecture, end-use industry, and regional production hub converged with top-down macro-industrial indicators across the analysis window. Segmentation dimensions included melt-processability tier, purity specification, and fabrication method. CAGRs derived from elasticity-adjusted demand curves incorporating fluorspar supply constraints and regulatory phase-down schedules. Semiconductor node transition timelines and battery cell capacity buildouts served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance restriction expansions, F-Gas quota tightening, and fluorspar export policy shifts. Forecasts reflect documented assumptions on regulatory implementation pacing and substitution technology readiness. Material deviation in EU F-Gas amendment enforcement or Chinese MEE emissions standard acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyvinyl Alcohol (PVA) Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Asia-Pacific Engineering Plastics Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Ethylene Copolymer Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Polymethacrylimide Foam Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market
Polymers & Resins
Expanded Polystyrene (EPS) Market
Polymers & Resins
Polybutylene Succinate (PBS) Market