

PCR Polyolefins Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Polyolefins Market Insights
Polymer chemist and mechanical recycling engineer availability is reorganizing how fast PCR polyolefin capacity scales in Europe and North America. Borealis leverages its proprietary Borcycle technology platform to sustain high-purity output from mixed post-consumer waste streams. LyondellBasell Industries anchors its MoReTec molecular recycling investments to differentiate on food-contact compliance where mechanical routes face limits. Dow competes through its Revoloop product line, positioning recycled polyethylene for flexible packaging applications with traceable chain-of-custody documentation.
PCR polyolefins denote thermoplastic resins recovered from post-consumer waste streams—primarily used packaging, agricultural film, and durable goods—then sorted, washed, extruded, and re-pelletized to achieve melt flow indices between 0.3 and 50 g/10 min for reintegration into injection molding and blown film processes. Recovered polyethylene dominates current volume throughput due to abundant feedstock from retail and e-commerce packaging waste streams, though post-consumer polypropylene commands margin premiums in automotive interior applications where odor and color consistency specifications are stringent. Packaging films as an application segment leads absolute consumption, while construction materials represents the fastest-growing outlet as geosynthetics and pipe producers adopt certified recycled content to meet green building procurement standards.
The EPA's recycled content procurement guidelines and California's SB 54 plastic pollution reduction mandates are reshaping minimum recycled content thresholds for packaging sold into the US market, while REACH and the EU Packaging and Packaging Waste Regulation enforce strict substance restrictions and extended producer responsibility schemes across European supply chains. FDA food-contact notifications and EFSA scientific opinions determine which mechanical recycling processes achieve clearance for sensitive applications, directly gatekeeping premium pricing tiers. Stakeholders must monitor evolving mass balance certification protocols and polymer-grade bale quality standards, as these will determine which recyclers capture contracted offtake from brand-owner sustainability commitments.
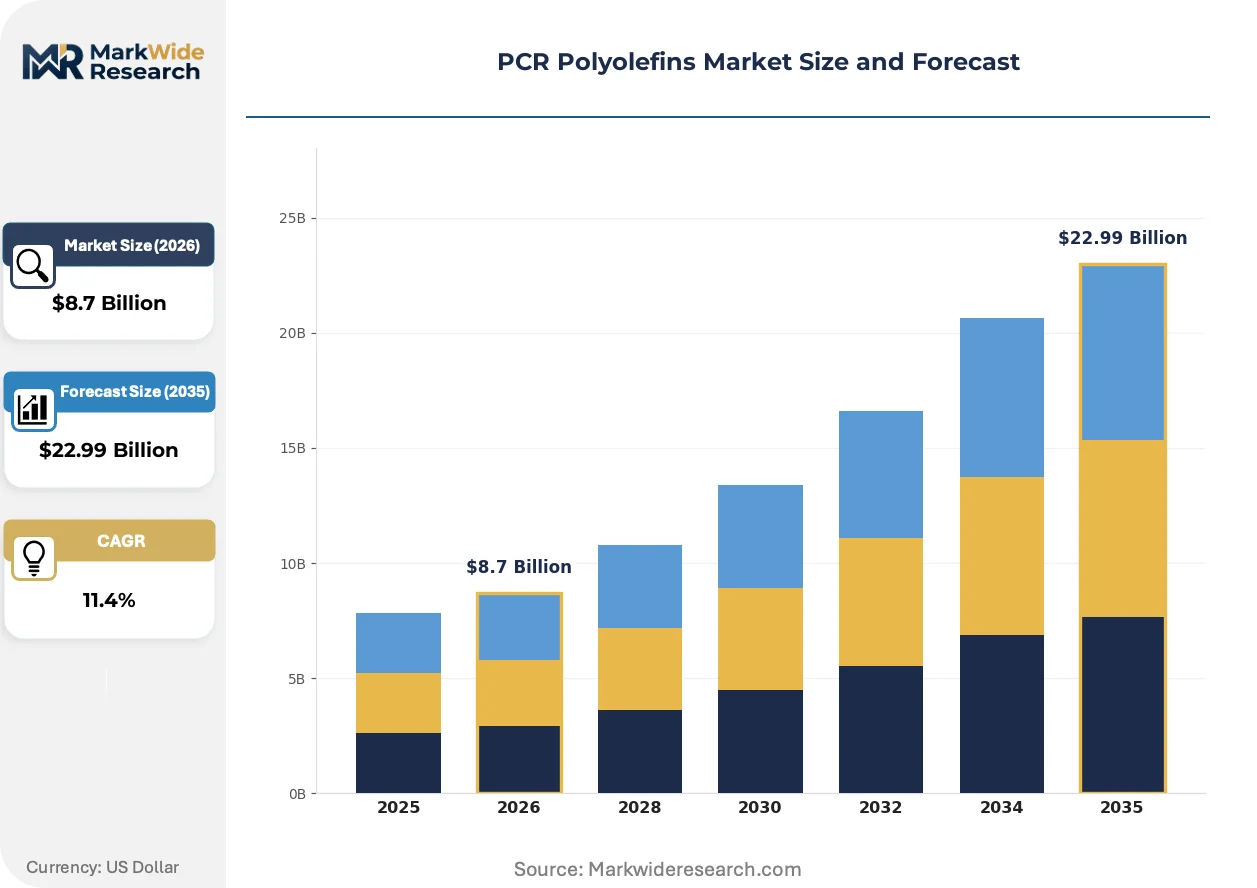
Market Dynamics
Mechanical recycling capacity bottlenecks are compressing PCR polyolefin availability against brand-owner sustainability commitments, forcing reformulation timelines to synchronize with bale quality certification rather than virgin resin procurement cycles.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content thresholds for packaging sold into European markets are pulling forward offtake contracts from converters seeking compliance certainty ahead of enforcement deadlines.
- Automotive interior specifications:Post-consumer polypropylene odor and color consistency improvements are unlocking tier-one supplier qualifications previously reserved for virgin material in dashboard and trim applications.
- Advanced mechanical recycling clusters:Co-location of sorting, washing, and extrusion infrastructure in Germany's industrial corridors is reducing feedstock-to-pellet logistics costs and improving bale traceability.
Market Restraints
- Feedstock price volatility:Post-consumer bale costs fluctuate with municipal collection contract cycles and export demand from Southeast Asian reclaimers, squeezing recycler margins when virgin polyethylene prices drop.
- Food-contact regulatory fragmentation:FDA notification requirements for mechanical recycling processes diverge from EFSA scientific opinion pathways, forcing dual-track compliance investments for suppliers serving both markets.
- Polymer-grade contamination thresholds:Presence of multilayer films and metallized barriers in retail packaging waste streams degrades re-pelletized output quality, limiting addressable market segments.
Strategic Opportunities
- Geosynthetics specification adoption:Green building procurement standards in construction are creating certified recycled content demand for geomembranes and drainage geocomposites previously specified in virgin resin.
- Mass balance certification protocols:ISCC PLUS and RSB chain-of-custody frameworks are enabling molecular recycling investments to access premium pricing tiers in flexible food packaging.
- Agricultural film recovery networks:Silage wrap and greenhouse film collection infrastructure expansion in France and Spain is concentrating feedstock supply for dedicated polyethylene recycling lines.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise for odor reduction and melt flow stabilization in mixed-waste feedstocks concentrates among specialists with legacy automotive compounding backgrounds.
- Capital intensity of optical sorting:Near-infrared and robotics-based contamination removal systems require seven-figure investments per line, favoring scaled operators over regional reclaimers.
- Legacy ERP integration:Traceability documentation requirements from brand owners force recyclers to overlay blockchain or mass-balance software onto decades-old production planning systems.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Polyolefins Market Trends and Innovations
Molecular recycling pathways are advancing from pilot demonstration toward commercial scale, compressing the technical boundaries between mechanical recycling purity limits and food-contact compliance requirements.
Pyrolysis-based polyolefin recovery is decomposing mixed plastic waste streams into synthetic crude intermediates, which LyondellBasell and Dow are upgrading back to polymer-grade feedstocks. Food packaging converters in the Netherlands and Belgium are securing offtake agreements for these outputs ahead of mechanical recycling capacity expansion. This thermal decomposition route is decomposing the historical segmentation between chemical and mechanical recycling investment strategies, forcing integrated petrochemical players to allocate capital across both technology platforms.
California's SB 54 plastic pollution reduction mandates are imposing minimum recycled content thresholds on single-use packaging sold into the state's consumer markets. Brand owners are reformulating flexible films and rigid containers ahead of compliance deadlines, driving contract negotiations with reclaimers possessing third-party certification. The flexible packaging segment faces the steepest compliance gradient, as thin-film mechanical recycling yields have historically lagged bottle-to-bottle polyethylene terephthalate recovery rates.
Buyers are consolidating procurement around reclaimers offering auditable chain-of-custody documentation from bale origin through re-pelletization. Consumer goods manufacturers in Germany and the Netherlands are displacing spot-market purchasing with multi-year supply agreements that embed sustainability reporting requirements. This contractual shift is most visible in personal care and home cleaning product packaging, where brand-owner sustainability commitments must withstand NGO supply chain audits and regulatory disclosure obligations.
PCR Polyolefins Market Segmentation
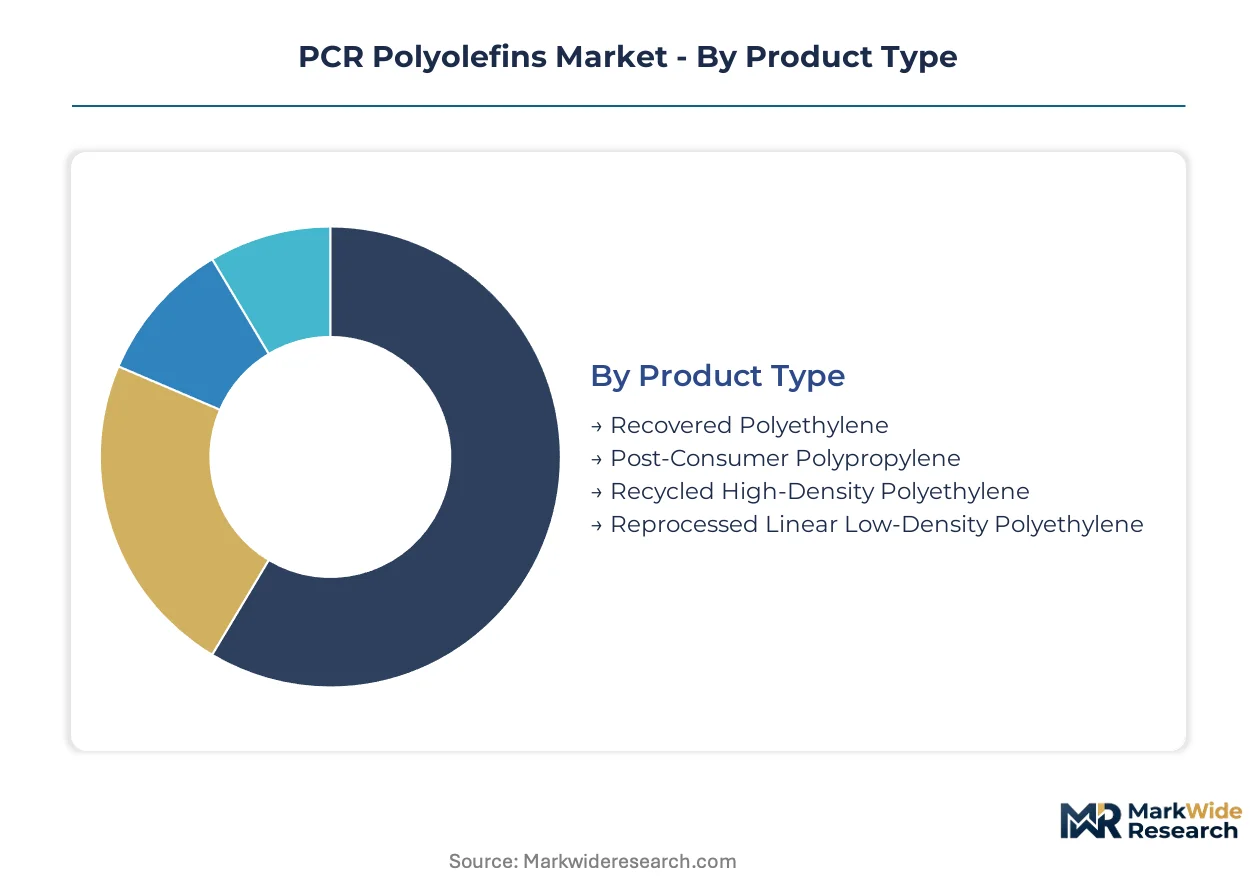
PCR polyolefin procurement decisions split across polymer chemistry, processing form, and end-use compliance requirements. Each segmentation axis carries distinct regulatory thresholds that determine addressable market tiers and pricing power.
Product Type:
REACH substance restrictions and FDA food-contact notifications create divergent qualification pathways for each polymer grade, directly gating premium pricing access.
- Recovered Polyethylene:Dominant volume stream sourced from retail and e-commerce packaging waste with melt flow indices spanning 0.3 to 50 g/10 min. Demand concentrates in German flexible packaging clusters where EU Packaging and Packaging Waste Regulation mandates are pulling forward offtake contracts from converters seeking compliance certainty.
- Post-Consumer Polypropylene:Higher-margin segment requiring advanced odor reduction and color consistency stabilization. Automotive interior specifications in Germany are unlocking tier-one supplier qualifications for dashboard and trim applications previously reserved for virgin material.
- Recycled High-Density Polyethylene:Stiff, blow-moldable grade serving construction pipe and rigid container markets.
- Reprocessed Linear Low-Density Polyethylene:Film-grade resin with superior puncture resistance for stretch and shrink wrap applications.
Recovered polyethylene handles the majority of throughput; post-consumer polypropylene is gaining share fastest on margin expansion.
Application:
Application selection determines whether mechanical recycling purity limits suffice or molecular recycling investments become necessary for regulatory clearance.
- Packaging Films:Thin-film flexible packaging leads absolute consumption but faces steepest compliance gradient under California SB 54 mandates. Dutch and Belgian converters are securing molecular recycling offtake agreements where mechanical yields historically lag bottle-grade recovery rates.
- Construction Materials:Geomembranes and drainage geocomposites are expanding most quickly as green building procurement standards enforce certified recycled content thresholds. French and Spanish agricultural film recovery networks are concentrating feedstock supply for dedicated polyethylene recycling lines serving this outlet.
- Automotive Components:Odor-critical interior parts with stringent volatile organic compound limits.
- Household Appliances:Durable goods housings with moderate aesthetic requirements.
Packaging films command the largest volume position; construction materials show the steepest expansion trajectory on specification adoption.
End User:
Procurement sophistication varies sharply across end-user categories, with sustainability audit exposure driving contract structure differentiation.
- Consumer Goods Manufacturers:Personal care and home cleaning product packagers are displacing spot-market purchasing with multi-year supply agreements embedding chain-of-custody documentation requirements. German and Dutch brand owners must withstand NGO supply chain audits and regulatory disclosure obligations.
- Transportation Equipment Producers:Automotive OEMs and tier-one suppliers co-locating near advanced mechanical recycling clusters in Germany's industrial corridors.
- Household Equipment Suppliers:White goods producers with moderate recycled content targets.
- Building Material Fabricators:Geosynthetics and pipe producers adopting certified recycled content for green building procurement standards.
Consumer goods manufacturers anchor contract volume; transportation equipment producers are climbing fastest on co-location incentives.
Form:
Form selection traces directly to downstream processing equipment compatibility and traceability documentation requirements.
- Pellets:Standardized re-pelletized form with consistent melt flow indices for injection molding and blown film processes. Brand-owner sustainability commitments are forcing recyclers to overlay blockchain or mass-balance software onto production planning systems for auditable documentation.
- Granules:Coarser feedstock for extrusion-heavy applications with lower purity requirements.
- Flakes:Intermediate washed output for compounders performing in-house re-pelletization.
- Powder:Niche rotational molding feedstock with limited addressable market.
Pellets dominate processor preference; granules are expanding most quickly on cost-sensitive construction applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across major economies: Germany concentrates automotive-grade post-consumer polypropylene demand, while the United States channels recovered polyethylene toward flexible packaging compliance mandates, and China scales mechanical recycling infrastructure for construction-grade reprocessed resins.
United States
Flexible packaging converters and beverage brand owners dominate procurement as California SB 54 mandates force reformulation timelines. The EPA's recycled content procurement guidelines establish federal minimum thresholds for government suppliers. Houston-based petrochemical corridors anchor molecular recycling investments targeting food-contact compliance gaps.
Germany
Automotive OEMs and tier-one suppliers drive premium-grade post-consumer polypropylene consumption for interior trim specifications. The EU Packaging and Packaging Waste Regulation enforces binding recycled content thresholds across all packaging categories. Industrial corridors in North Rhine-Westphalia co-locate advanced mechanical recycling clusters with automotive assembly plants.
China
Construction materials producers and geosynthetics fabricators absorb expanding volumes of reprocessed polyethylene for infrastructure applications. The country's national standards body implements polymer-grade bale quality specifications for imported post-consumer feedstocks. Yangtze River Delta recycling parks concentrate optical sorting and extrusion capacity near Shanghai port logistics.
Netherlands
Food packaging converters secure molecular recycling offtake ahead of mechanical capacity expansion for thin-film applications. EFSA scientific opinions determine clearance pathways for sensitive food-contact end uses. Rotterdam-Europoort industrial zones integrate pyrolysis upgrading with polymer-grade feedstock production.
France
Agricultural film recovery networks concentrate silage wrap and greenhouse film feedstock for dedicated polyethylene recycling lines. Extended producer responsibility schemes under EU Green Deal implementation finance collection infrastructure expansion. Auvergne-Rhône-Alpes processing hubs link Alpine agricultural regions to compounder supply chains.
PCR Polyolefins Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with petrochemical majors leveraging proprietary technology platforms against regional reclaimers focused on feedstock aggregation. The upper tier commands premium pricing through food-contact certifications and mass balance documentation, while mid-scale operators compete on logistics proximity to industrial clusters. Two strategic archetypes dominate: integrated petrochemical players with molecular recycling capabilities, and mechanical recycling specialists with advanced optical sorting infrastructure. Competitive intensity centers on capacity expansion near automotive and packaging clusters, plus technology licensing agreements that extend proprietary process reach.
Among integrated European petrochemical players, Borealis and LyondellBasell Industries exemplify the technology-platform archetype, while Dow occupies a position bridging mechanical and molecular recycling investment strategies. Borealis represents the proprietary-process specialist model with its Borcycle platform heritage. LyondellBasell Industries anchors the molecular recycling vector through MoReTec technology positioning. Dow sits within the dual-platform tier, competing through traceable chain-of-custody documentation for flexible packaging applications.
| Leading Market Players |
|---|
| Borealis |
| LyondellBasell Industries |
| Berry Global Group |
| SABIC |
| ExxonMobil |
| TotalEnergies |
| Mitsui Chemicals |
| Dow |
| ALPLA Group |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between German automotive OEMs and post-consumer polypropylene reclaimers lock in supply access and price visibility across multi-year procurement cycles. These contracts embed mass balance certification requirements that filter spot-market participants from premium-tier qualification.
Pricing Analysis
Contract-based long-term offtake structures dominate premium-grade post-consumer polypropylene, while spot transactions handle construction-grade recovered polyethylene. Price differentiation hinges on food-contact certification tier and odor consistency grade. Cost compression in mechanical recycling tiers is intensifying because virgin polyethylene price volatility squeezes recycler margins when brand-owner sustainability commitments outpace bale quality availability. Consumer goods manufacturers show highest price sensitivity due to thin flexible packaging margins, whereas automotive tier-one suppliers accept premium pricing for dashboard and trim specifications.
Supply Chain Analysis
Germany and the Netherlands anchor advanced mechanical recycling capacity for automotive and food-contact applications, while China's Yangtze River Delta parks concentrate optical sorting infrastructure for construction-grade reprocessing. Feedstock supply draws from municipal collection contracts in France and Spain, polymer-grade bale imports through Rotterdam, and agricultural film recovery networks in Auvergne-Rhône-Alpes. Single-source vulnerability concentrates around near-infrared sorting equipment suppliers. Distribution runs through compounder hubs co-located with automotive assembly corridors and flexible packaging converter clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
PCR polyolefin incumbents must defend against molecular recycling substitution threats that bypass mechanical purity limits for food-contact compliance. Virgin resin producers with pyrolysis upgrading capabilities threaten to capture premium flexible packaging segments.
For Market Incumbents: Secure multi-year bale supply contracts with French and Spanish agricultural film recovery networks before molecular recycling capacity scales. Backward integration into optical sorting infrastructure defends margin position against feedstock price volatility from Southeast Asian export demand.
For New Entrants and Emerging Players: Lead with geosynthetics specification adoption in green building procurement standards, where certified recycled content thresholds create addressable demand without food-contact regulatory barriers. Target construction-grade pellet supply to German and Dutch building material fabricators through ISCC PLUS chain-of-custody documentation.
For Investors and Strategic Acquirers: Capital is best deployed toward mechanical recycling specialists with proprietary odor reduction capabilities and established automotive tier-one qualifications. The inflection signal to watch is FDA notification clearance for mechanical recycling processes serving US flexible packaging converters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bale Aggregation | Captures feedstock cost visibility before municipal contract renewal cycles in Germany and France. |
| Mass Balance Certification Investment | Unlocks premium pricing tiers under ISCC PLUS protocols for flexible food packaging converters. |
| Co-location Near Automotive Clusters | Reduces logistics costs for odor-critical post-consumer polypropylene supply to German OEMs. |
| Optical Sorting Capacity Expansion | Improves polymer-grade contamination thresholds for food-contact qualification pathways. |
| Long-term Supply Agreement with Brand Owners | Locks in offtake volume ahead of California SB 54 compliance deadline enforcement. |
Research Methodology
Operator-level perspectives from mechanical recycling plant managers, automotive tier-one procurement leads, flexible packaging converter technical directors, and mass balance certification auditors anchored the qualitative base. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, EPA recycled content procurement guidelines, FDA food-contact notification databases, and EFSA scientific opinion records. Bottom-up capacity modeling triangulated against top-down brand-owner sustainability commitment aggregation.
Sensitivity analysis tested feedstock price volatility scenarios and regulatory enforcement timing assumptions across the analysis window. Segmentation dimensions modeled include polymer chemistry grade, application compliance tier, end-user procurement sophistication, and reprocessing form factor. CAGRs were derived from installed capacity expansion pipelines cross-referenced with offtake contract disclosure patterns and bale quality certification adoption curves.
Forecasts assume regulatory continuity in EU REACH substance restrictions and California SB 54 implementation; material policy shifts would require re-modeling minimum recycled content thresholds and extended producer responsibility financing mechanisms. Recalibration cycles align with material shifts in FDA notification clearance timelines and automotive interior specification revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.