
 Europe Polypropylene Market | 2026-2036
Europe Polypropylene Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polypropylene Market Intelligence
Multi-source resin procurement is consolidating across European compounders as energy volatility reshapes supply security calculations. Borealis AG anchors its Nordic and Benelux positions through backward integration into propane dehydrogenation. INEOS Group leverages its Grangemouth and Lavéra pipeline networks to sustain just-in-time deliveries to UK and French automotive tiers. LyondellBasell Industries NV differentiates through its Hostalen technology platform, which competes on melt-flow precision for thin-wall packaging specifications.
Polypropylene is a semi-crystalline thermoplastic polymer derived from propylene monomer, typically exhibiting a density of 0.90–0.91 g/cm³ and melting points between 160°C and 171°C depending on grade structure. Its primary commercial purpose centers on injection-molded components, biaxially oriented films, and textile fibers where chemical resistance and fatigue endurance outweigh engineering polymer costs. Homopolymer formulations dominate volume flows into rigid packaging and household goods, though random copolymer demand accelerates in medical and food-contact films where clarity and sealing performance command margin premiums. Impact copolymer grades occupy a defensible niche in automotive bumper fascias and appliance housings, where low-temperature ductility specifications exclude standard homopolymer alternatives.
REACH registration obligations and the EU Green Deal's packaging waste directives constrain virgin polymer placement while creating compliance premiums for mass-balance certified grades. ECHA's persistent organic pollutant screenings and the F-Gas Regulation's indirect pressure on process cooling costs further reshape production economics across Rotterdam-Antwerp corridor plants. Stakeholders must monitor PP recyclate qualification thresholds under impending EU Packaging and Packaging Waste Regulation amendments, as these will determine which compounders retain access to branded food-contact applications versus diversion into lower-specification construction and agricultural outlets.
Market Dynamics
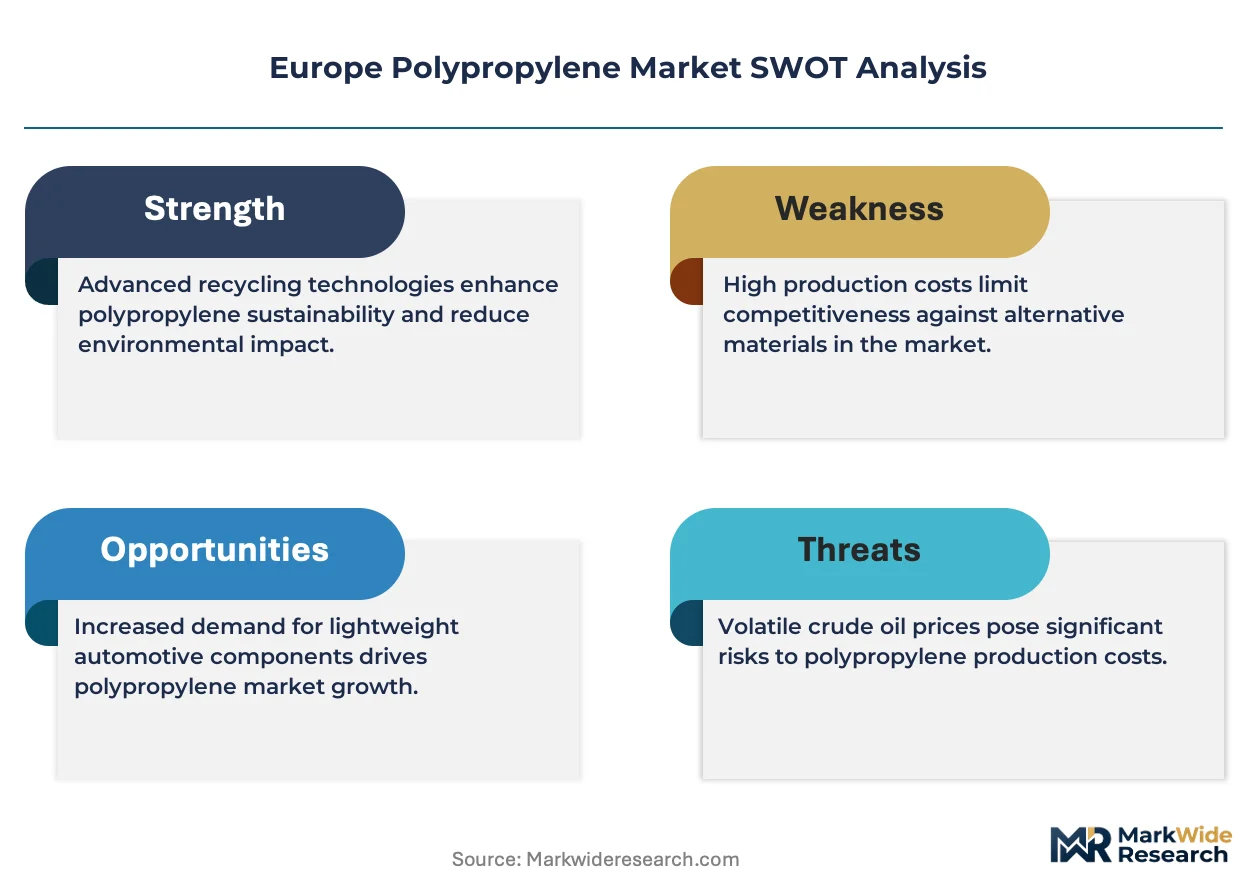
REACH registration obligations and the EU Green Deal's packaging waste directives are redirecting formulation priorities toward recycled feedstocks and mass-balance certified grades across European compounders.
Growth Catalysts
- Automotive lightweighting mandates:German and French assembly lines sustain polymer demand as OEMs substitute metals with impact copolymer grades in bumper fascias and structural components.
- EU Packaging and Packaging Waste Regulation:Pending amendments create compliance premiums for recyclate-qualified resins, accelerating investment in chemical recycling infrastructure across the Rotterdam-Antwerp corridor.
- Propane dehydrogenation backward integration:Nordic and Benelux producers secure captive propylene supply, insulating compounders from naphtha-cracker volatility.
Market Restraints
- Naphtha-propane feedstock volatility:European crackers face margin compression when propane-naphtha spreads tighten, forcing homopolymer producers into spot market exposure.
- Rotterdam-Antwerp supply concentration:Over half of European PP capacity clusters within 200 kilometers, creating single-point-of-failure risk for just-in-time automotive tiers.
- Engineering polymer substitution:Polyamide and PBT grades capture high-temperature under-hood applications where PP's thermal ceiling excludes specification.
Strategic Opportunities
- Italian packaging machinery corridor:Copolymer demand concentrates in Bologna-Modena automation clusters where thin-wall injection molding requires melt-flow precision grades.
- Mass-balance certification tailwind:ISCC PLUS and RSB frameworks enable premium placement of chemically recycled resins in branded food-contact applications.
- Digital twin convergence with AI-driven formulation:Compounders deploying predictive rheology models compress development cycles for custom automotive specifications.
Industry Challenges
- Recyclate qualification timelines:EFSA novel food contact approvals for pyrolysis-derived resins extend 18-24 months, delaying revenue recognition for circular investments.
- Process cooling retrofit capex:F-Gas Regulation phase-down forces propylene-based chiller replacements at legacy plants, stranding mid-scale producers without balance-sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polypropylene Market |
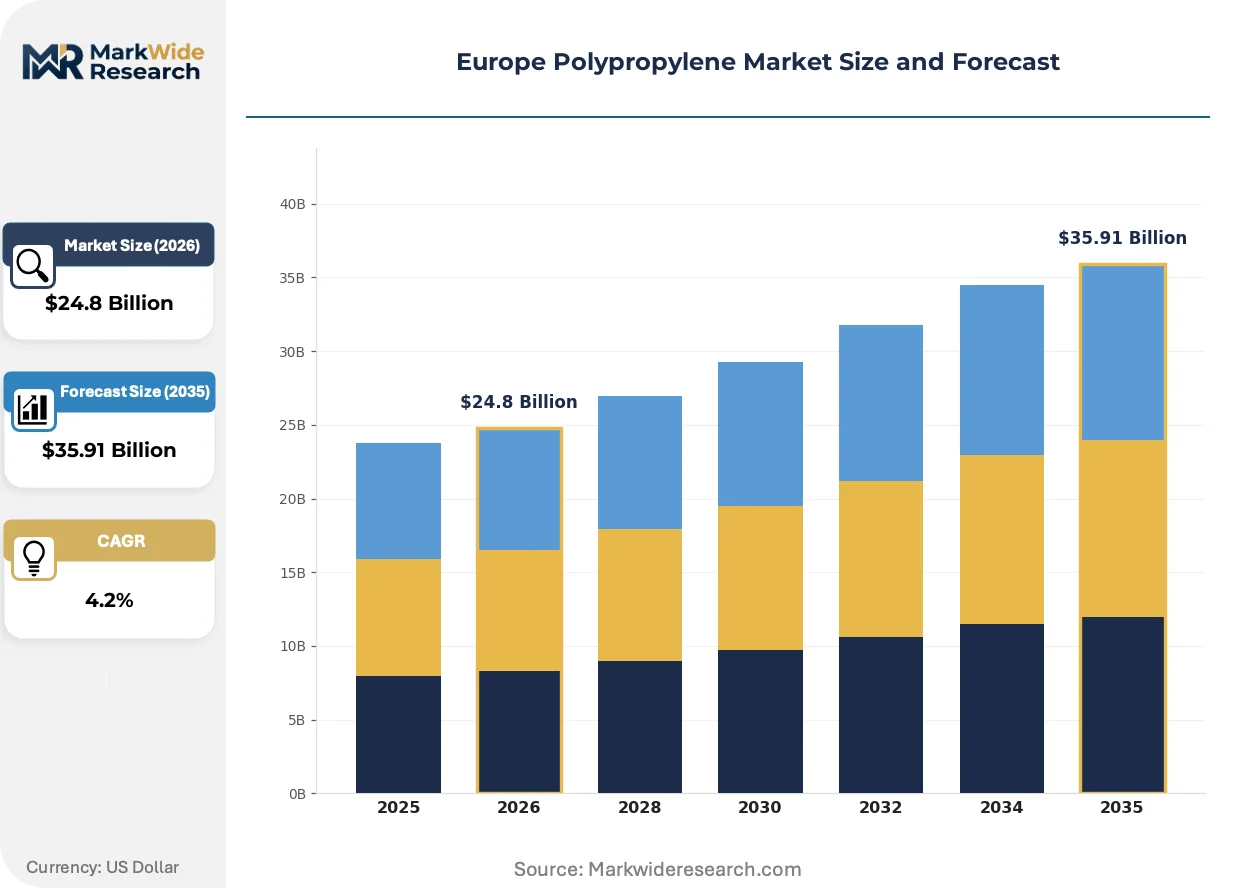
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $35.91 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Random Copolymer, Impact Copolymer End Use Industry: Automotive, Packaging, Textile, Electronics Form: Granules, Fibers, Films, Sheets Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | Versalis SpA, Solvay SA, Borealis AG, Covestro AG, BASF SE, INEOS Group, Repsol SA, Lanxess AG, LyondellBasell Industries NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polypropylene Market Strategic Shifts & Innovations
Decentralized propylene sourcing and digital formulation tools are compressing development cycles while regulatory pressure on virgin polymer placement intensifies margin stratification across the value chain.
Advanced recycling via pyrolysis and gasification is decentralizing feedstock security for European compounders. Automotive tiers in Stuttgart and Turin are qualifying chemically recycled copolymers for non-structural interior components. This technology is decentralizing procurement risk away from naphtha-cracker concentration toward distributed waste-plastic feedstock networks.
REACH authorization requirements for persistent organic pollutants are tightening impurity thresholds in recycled feedstocks. ECHA screenings now disqualify legacy additive packages from mechanical recyclate streams. Food-contact film producers in France and Germany are responding by segregating post-industrial scrap from post-consumer sources to maintain EFSA compliance windows.
Compounders are consolidating multi-source resin procurement under centralized category management functions. Large packaging converters in the Benelux are displacing spot-market purchasing with 24-36 month offtake agreements tied to mass-balance certificates. This behavioral shift is most visible in rigid dairy packaging where branded retailers demand supply-chain documentation for shelf-space allocation.
Europe Polypropylene Market Segmentation
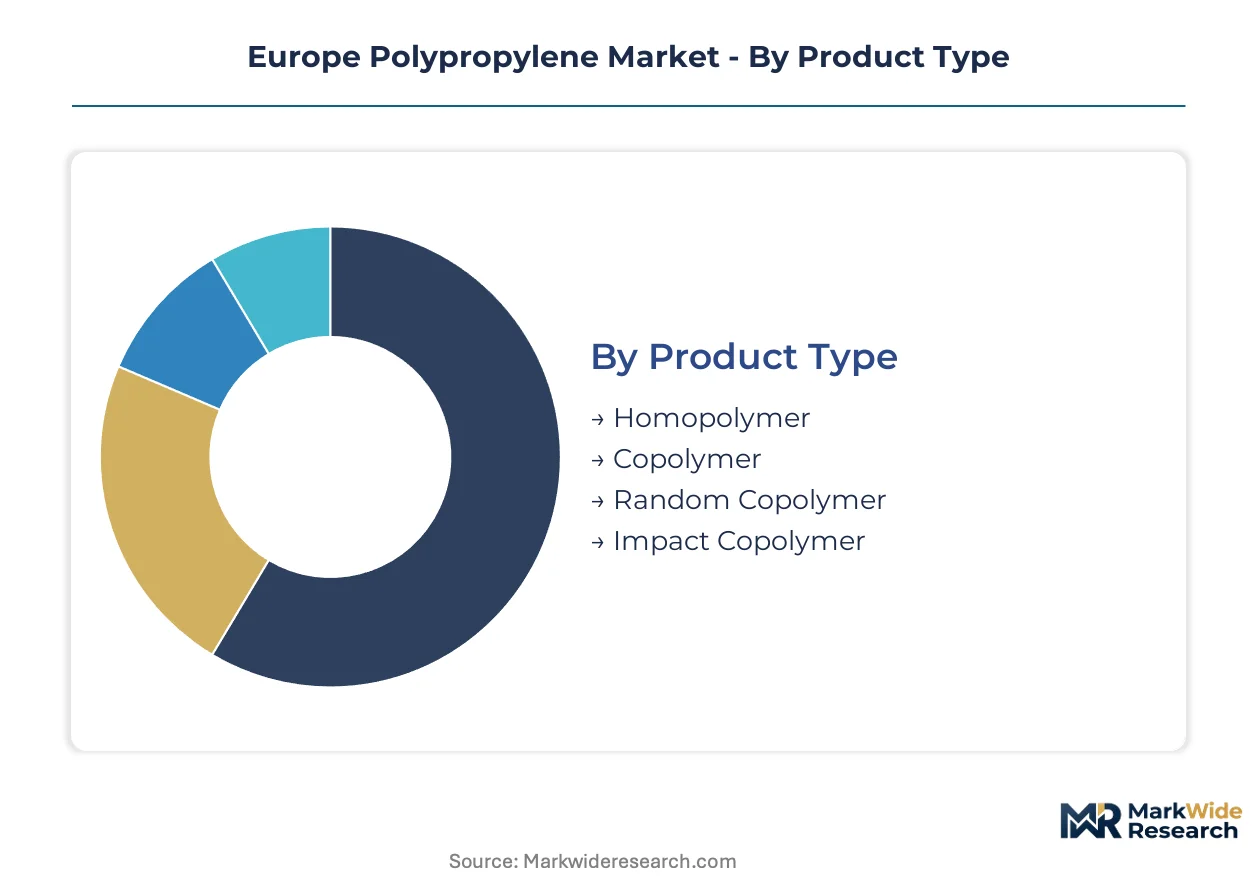
Segmentation in the Europe Polypropylene Market reveals how formulation chemistry, processing form, and channel structure stratify margin capture. Producers configure product-mix decisions against regulatory thresholds and end-use qualification requirements.
Product Type:
Customization intensity spans from commodity homopolymer to specification-driven impact grades, with formulation complexity determining price realization and customer stickiness.
- Homopolymer:High crystallinity polypropylene with isotactic chain structure delivers stiffness and heat resistance for rigid containers. Demand concentrates in Benelux dairy packaging where converters favor melt-flow consistency for high-speed injection lines. REACH registration burdens favor established suppliers with legacy dossier portfolios.
- Copolymer:Ethylene-modified chains enhance impact strength and clarity for flexible applications. Italian packaging machinery corridors in Bologna-Modena drive specification premiums for thin-wall random grades. Mass-balance certification under ISCC PLUS now gates access to branded food-contact contracts.
- Random Copolymer:Random ethylene distribution yields optical clarity and sealing performance for cast film and medical packaging.
- Impact Copolymer:Heterophasic structure with rubber domains enables low-temperature ductility for automotive bumper systems.
Most installed capacity flows through Homopolymer. Expansion is steepest in Copolymer.
End Use Industry:
Application-driven segmentation tracks how thermal, mechanical, and regulatory requirements reshape procurement patterns across manufacturing clusters.
- Automotive:Impact copolymer grades substitute metal in Stuttgart and Turin assembly lines under lightweighting mandates. KBA type-approval protocols and OEM material qualification cycles extend 18-24 months, locking in supplier relationships. F-Gas Regulation compliance costs now factor into total cost of ownership calculations for under-hood components.
- Packaging:Rigid containers, flexible films, and closures absorb half of European PP volume. German and French retailers demand EFSA-compliant recyclate documentation for shelf-space allocation, compressing margins for non-certified compounders.
- Textile:Staple fiber and filament grades serve nonwoven hygiene and industrial applications.
- Electronics:Flame-retardant modified grades address connector and housing specifications.
Volume concentration sits with Packaging. Margin expansion is climbing fastest in Automotive.
Form:
Physical presentation determines logistics economics and downstream processing capital requirements, with melt-processing forms dominating European trade flows.
- Granules:Pelletized resin enables precise dosing in compounding and injection molding operations. Rotterdam-Antwerp corridor storage and blending facilities service just-in-time delivery contracts for automotive tiers. Inventory carrying costs have risen with energy price volatility, favoring consignment arrangements.
- Films:Biaxially oriented and cast film grades command specification premiums in French food-contact applications. EFSA novel food contact approvals for recycled content films create compliance delays that advantage incumbent suppliers with established dossiers.
- Fibers:Staple and filament forms serve textile and nonwoven converters.
- Sheets:Extruded thermoforming substrates target packaging and industrial applications.
Granules handle the largest throughput volumes. Films are gaining share fastest in premium applications.
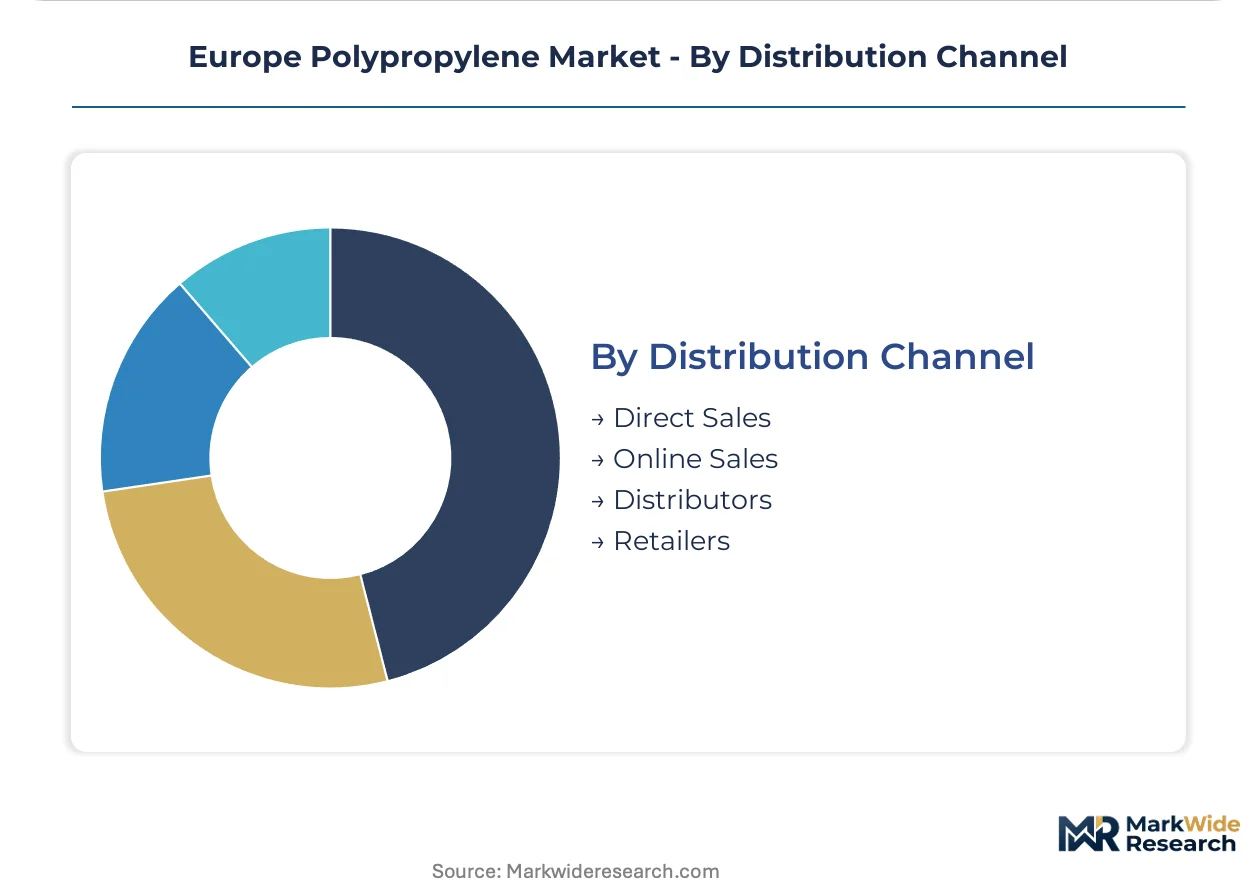
Distribution Channel:
Channel selection reflects customer scale, technical service requirements, and documentation burdens for regulatory compliance.
- Direct Sales:Large compounders and automotive tiers negotiate frame contracts with producers for volume certainty and technical support. Borealis AG and INEOS Group deploy dedicated account teams for German OEMs requiring material certification traceability. Contract tenors have extended to 24-36 months as buyers seek supply security.
- Distributors:Independent distributors service mid-scale converters with fragmented demand across multiple grades. Benelux packaging clusters rely on distributor inventory pooling to manage working capital. REACH compliance documentation flows through distributor quality systems.
- Online Sales:Digital platforms capture spot-market transactions for standard grades.
- Retailers:Limited to small-volume specialty and aftermarket applications.
Direct Sales channels capture the highest value flows. Distributors are expanding most quickly in mid-market segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rotterdam-Antwerp corridor anchors European polypropylene capacity, clustering over half of regional production within 200 kilometers. German automotive demand and Italian packaging machinery specifications drive formulation differentiation across national markets.
Germany
Stuttgart assembly lines qualify impact copolymer grades for bumper systems under KBA type-approval protocols. The EU Green Deal's circular economy mandates accelerate mechanical recycling investments in North Rhine-Westphalia. Borealis AG operates propane dehydrogenation capacity in the Benelux border region, supplying captive propylene to German compounders.
France
Lavéra pipeline networks sustain just-in-time deliveries to automotive tiers in the Lyon-Grenoble manufacturing belt. EFSA novel food contact approvals create compliance delays for pyrolysis-derived resins, favoring incumbent suppliers with established dossiers. INEOS Group leverages its southern corridor infrastructure to service French packaging converters demanding mass-balance certification.
Italy
Bologna-Modena packaging machinery corridors concentrate demand for thin-wall random copolymer grades with melt-flow precision specifications. REACH authorization requirements for persistent organic pollutants tighten impurity thresholds in recycled feedstocks. Northern Italian compounders segregate post-industrial scrap from post-consumer sources to maintain EFSA compliance windows.
Netherlands
Rotterdam storage and blending facilities service consignment arrangements for Benelux dairy packaging converters managing inventory carrying costs. The F-Gas Regulation forces propylene-based chiller replacements at legacy plants, stranding mid-scale producers. Large packaging converters displace spot-market purchasing with 24-36 month offtake agreements tied to ISCC PLUS certificates.
United Kingdom
Grangemouth pipeline networks supply Scottish and northern English automotive tiers with impact copolymer grades for lightweighting programs. ECHA screenings disqualify legacy additive packages from mechanical recyclate streams. UK compounders deploy digital twin convergence with AI-driven formulation tools to compress development cycles for custom automotive specifications.
Europe Polypropylene Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue chemical recycling and mass-balance certification as differentiation vectors. The market structure reflects moderate consolidation around integrated petrochemical groups with backward propylene supply, while specialty compounders fragment across application-specific niches. Strategic archetypes include integrated majors with PDH assets, technology licensors with proprietary catalyst platforms, and regional compounders with formulation agility. Competitive dynamics center on capacity expansion in low-carbon feedstocks and strategic partnerships for recyclate qualification.
Among Benelux and Nordic integrated producers, Borealis AG and INEOS Group exemplify the backward-integrated archetype with captive propylene supply insulating compounders from naphtha-cracker volatility. LyondellBasell Industries NV occupies a technology-licensor position, representing the catalyst-platform tier where melt-flow precision commands specification premiums. These three entities anchor the competitive structure, with European chemical conglomerates like BASF SE and Covestro AG sitting within the diversified materials tier where polypropylene constitutes one portfolio element among engineering polymers and specialties.
| Leading Market Players |
|---|
| Versalis SpA |
| Solvay SA |
| Borealis AG |
| Covestro AG |
| BASF SE |
| INEOS Group |
| Repsol SA |
| Lanxess AG |
| LyondellBasell Industries NV |
| Others |
Cost & Logistics Intelligence
German and French automotive tiers anchor procurement concentration, locking in contract-based long-term offtake agreements that insulate volume buyers from spot-market volatility. This buyer-structure dominance tilts pricing power toward producers with captive propylene supply, while converters without backward integration absorb margin compression from feedstock volatility.
Pricing Analysis
Propane-naphtha spread pass-through mechanics govern price realization across European compounders. Three-tier pricing structure across premium, standard, and economy levels separates ISCC PLUS-certified recyclate from virgin homopolymer and spot-market distressed volumes. Cost compression in standard-grade homopolymer is intensifying because naphtha-cracker margin pressure forces spot-market exposure during propane price spikes. Small-scale Italian packaging converters exhibit highest price sensitivity due to working capital constraints, while German OEMs with KBA qualification cycles show lowest sensitivity to per-kilogram differentials.
Supply Chain Analysis
EU Green Deal domestic-content mandates for recycled feedstock qualification are reshaping sourcing patterns toward segregated post-industrial scrap networks. Supply concentrates in Belgium, the Netherlands, and Germany, with over half of European capacity clustering within 200 kilometers of Rotterdam-Antwerp corridor storage and blending facilities. Raw material dependencies center on propane dehydrogenation feedstock, naphtha cracker byproduct propylene, and pyrolysis-derived recyclate oil. Single-source vulnerability runs through Rotterdam port infrastructure for just-in-time automotive deliveries. Distribution runs through producer-direct frame contracts for large compounders and independent distributor inventory pooling for mid-scale converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Packaging and Packaging Waste Regulation amendments are accelerating demand for mass-balance certified grades. The regulatory milestone creates structural premiums for qualified recyclate while disqualifying legacy additive packages from mechanical streams.
For Market Incumbents: Deepen backward integration into propane dehydrogenation assets to insulate compounders from naphtha-cracker volatility. Secure EFSA novel food contact dossiers for pyrolysis-derived resins ahead of qualification timeline bottlenecks. Chemical recycling infrastructure investment represents the critical lever for defending margin position against virgin polymer displacement. For New Entrants and Emerging Players: Mid-scale Italian packaging machinery converters in the Bologna-Modena corridor represent the most penetrable buyer archetype, underserved by technical service from integrated majors. Target this segment with melt-flow precision copolymer grades and rapid formulation turnaround. A co-development partnership model with machinery OEMs offers the strongest go-to-market angle for qualification without legacy dossier burdens. For Investors and Strategic Acquirers: Specialty chemical conglomerates with diversified materials portfolios are the most active acquirer in this space, seeking polypropylene assets to complement engineering polymer offerings. The five-to-ten-year viability window favors targets with ISCC PLUS certification infrastructure and established automotive qualification relationships. Chemical recycling technology platforms with EFSA approval progress signal inflection potential for premium recyclate placement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propane Dehydrogenation | Borealis AG's Benelux PDH assets insulate German compounders from naphtha volatility. |
| Mass-Balance Certification Investment | ISCC PLUS frameworks enable premium placement in French food-contact film applications. |
| Chemical Recycling Scale-Up | Pyrolysis infrastructure decentralizes feedstock security away from Rotterdam-Antwerp concentration. |
| Long-Term Offtake Agreements | Benelux dairy packaging converters displace spot purchasing with 24-36 month contracts. |
| Digital Twin Formulation Deployment | AI-driven rheology models compress development cycles for Stuttgart automotive specifications. |
Research Approach
Multiple input streams — primary interviews with plant managers and procurement leads at downstream OEMs, secondary validation through customs/trade data and Cefic industry reports, and technical R&D director consultations — were reconciled through bottom-up and top-down triangulation. Distribution channel partners in the Benelux provided working capital and inventory management perspectives. SEC 10-K filings from integrated petrochemical groups supplied capacity utilization and margin structure data.
Data-stream reconciliation across the projection horizon applied segmentation modeling across grade tier, end-use industry, packaging format, and regional production hub dimensions. CAGRs were derived from production capacity expansion schedules, demand elasticity coefficients by automotive and packaging verticals, and regulatory compliance cost trajectories under REACH and EU Green Deal implementation timelines.
Underlying measurement precision varies by segment; homopolymer volume flows carry tighter precision than emerging chemical recycling capacity forecasts. Pyrolysis-derived resin qualification timelines and EFSA approval progress represent key assumption sensitivities that could revise outlooks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
Solid-Grade Thermoplastic Acrylic (Beads) Resin Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
India Polyacrylamide Copolymer Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Methacrylate Monomers Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
Polyolefin (PO) Market
Polymers & Resins
North America Polyurethane Market
Polymers & Resins
South America Epoxy Resins Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Bio Based Resin Market