
 Polycarbonate Diols Market | 2026-2036
Polycarbonate Diols Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarbonate Diols Market Analysis
Asian polycarbonate diol producers is pivoting toward higher-purity grades to serve synthetic leather and optical coating applications. Covestro leverages its backward integration into phosgene chemistry to sustain margin control across European and Asian supply corridors. Tosoh anchors its position through proprietary melt-transesterification technology that reduces solvent residues in high-performance polyurethane systems. Jiangsu Chemical Research competes on scale economics in medium-molecular-weight grades for domestic Chinese coatings producers.
Polycarbonate diols are aliphatic polyester polyols synthesized via phosgenation or transesterification of alkylene carbonates with diol initiators, typically exhibiting molecular weights between 500 and 4,000 g/mol and hydroxyl values of 25–220 mg KOH/g; they impart hydrolysis resistance, optical clarity, and low-temperature flexibility to polyurethane elastomers and coatings. The product-type landscape shows linear diols dominating volume in conventional thermoplastic polyurethane applications while high-purity diols command premium positioning in medical-grade and optical-grade formulations. End-user segmentation reveals coatings and adhesives as the fastest-expanding demand pools, driven by solvent-free formulation mandates and extended durability requirements in automotive refinish and industrial maintenance applications.
REACH registration through ECHA governs substance authorization and restricts certain phosgene-derived intermediates in European manufacturing, while China's GB standards under SAMR set incremental purity benchmarks for diols used in food-contact adhesives and consumer goods. Japan's METI chemical management framework influences export compliance protocols for producers serving electronics and automotive tiers. Stakeholders must monitor evolving biocide and VOC regulations across these jurisdictions to anticipate reformulation cycles and qualify next-generation polycarbonate diol architectures.
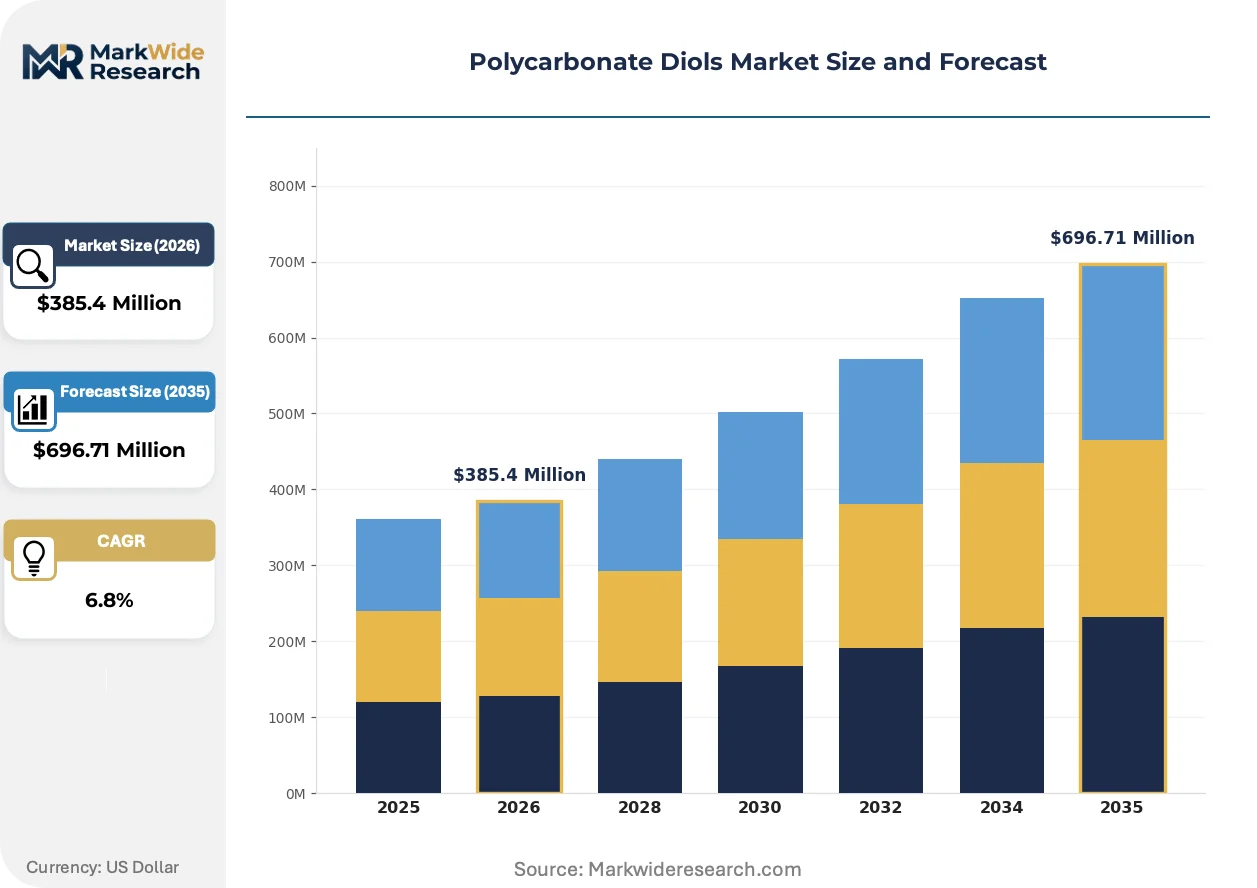
Market Dynamics
REACH compliance in Europe and China's GB standards under SAMR are redirecting formulation strategies toward low-emission polycarbonate diols, forcing polyurethane manufacturers to requalify supply chains around phosgene-derived intermediate restrictions and VOC limits.
Growth Catalysts
- Automotive Interior Mandates:OEMs are replacing conventional polyols with polycarbonate diols in polyurethane production for dashboards and seating to meet durability and hydrolysis resistance specifications.
- Solvent-Free Coating Regulations:REACH restrictions on solvent-based systems are accelerating adoption in automotive refinish and industrial maintenance applications across Germany and France.
- Phosgene Chemistry Integration:Backward integration into phosgene feedstocks allows producers to control margin compression across European and Asian supply corridors.
Market Restraints
- Feedstock Volatility:Phosgene and alkylene carbonate input costs fluctuate with chlorine and propylene oxide markets, squeezing converter margins.
- Supply Concentration Risk:High-purity grade production concentrates in Japan and Germany, creating qualification bottlenecks for medical-grade and optical-grade buyers.
- Transesterification Yield Limits:Melt-transesterification technology faces solvent residue thresholds that constrain throughput in high-performance polyurethane systems.
Strategic Opportunities
- Synthetic Leather Expansion:China's domestic synthetic leather producers are creating pull for higher-purity grades to serve automotive and consumer goods applications.
- Optical Coating Convergence:Integration of polycarbonate diols with UV-curable acrylics is opening medical device and display laminate segments.
- India PLI Incentives:India's production-linked incentive scheme for specialty chemicals offers tariff advantages for diol producers establishing local compounding operations.
Industry Challenges
- REACH Registration Timelines:ECHA substance authorization cycles extend 18-24 months, delaying new grade commercialization in European coatings markets.
- Phosgene Handling Certification:Qualified plant operators and process safety engineers remain scarce, limiting capacity expansion at existing European facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarbonate Diols Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Diols, Branched Diols, High-Purity Diols, Specialty Diols End User: Automotive, Coatings, Adhesives, Construction Application: Polyurethane Production, Flexible Foam, Rigid Foam, Thermoplastic Elastomers Quantity: Small Scale, Medium Scale, Large Scale, Bulk |
| Companies Covered | UBE Chemical, Tosoh, Covestro, Asahi Kasei, Perstorp, Caffaro Industrie, Cromogenia-Units, Kuraray, Jiangsu Chemical Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarbonate Diols Market Emerging Trajectories
Technology trajectories in polycarbonate diol production are converging around purity advancement, regulatory pre-compliance, and supply chain reconfiguration to serve dispersed end-use demand pools.
Non-phosgene melt-transesterification routes are rewriting the competitive map for high-performance polyurethane systems. Japanese and Korean elastomer compounders are adopting these solvent-reduced grades at accelerated qualification cycles. This chemistry shift is compressing the premium commanded by legacy phosgene-based optical-grade products.
REACH authorization amendments through ECHA are tightening restrictions on certain aromatic intermediates used in conventional polyol synthesis. Coatings formulators in Germany and the Netherlands are rebuilding raw material libraries to preempt substance sunset clauses. Medical-grade polyurethane producers face the steepest requalification burdens as they migrate toward aliphatic polycarbonate diol architectures.
Integrated supply relationships between diol producers and coatings manufacturers are displacing spot-market purchasing in automotive tiers. Japanese adhesive specialists now contract directly with domestic diol producers for molecular-weight-specified volumes. This channel consolidation is most visible in China where Jiangsu and Shandong coating clusters demand captive supply arrangements for medium-molecular-weight grades.
Polycarbonate Diols Market Segmentation
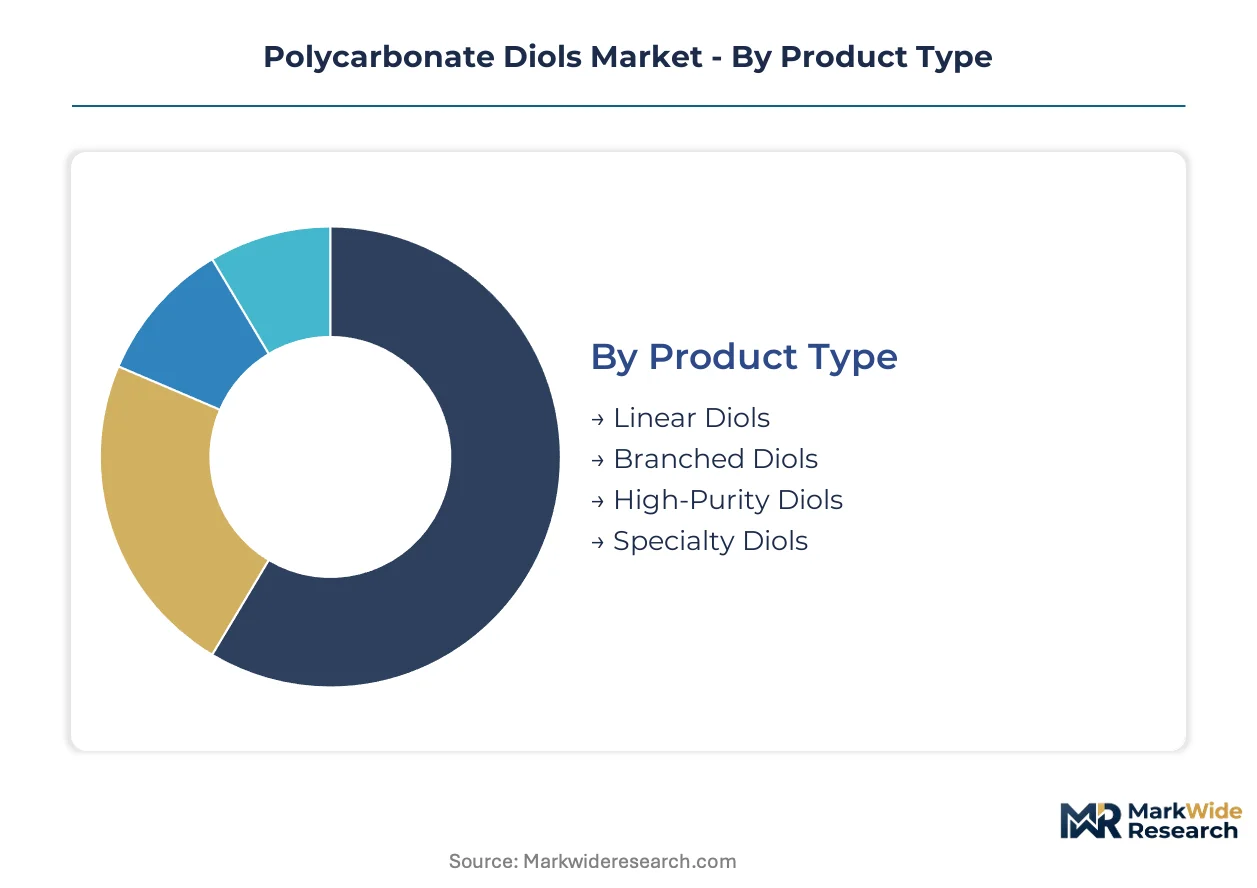
Polycarbonate diol buyers segment procurement around molecular architecture purity tiers and polyurethane system performance requirements. Supply relationships concentrate around specific end-use qualifications that lock in formulation specifications across multi-year automotive and coatings contracts.
Product Type:
Production assets for polycarbonate diol molecular architectures concentrate in Germany and Japan, with purity grades determining qualification timelines and pricing premiums.
- Linear Diols:Aliphatic polyester polyols with straight-chain molecular structures exhibit molecular weights between 500 and 4,000 g/mol. Thermoplastic polyurethane manufacturers in Germany absorb the majority of linear diol volume for dashboard and seating applications where hydrolysis resistance specifications dominate procurement decisions.
- High-Purity Diols:Grades exhibiting hydroxyl values of 25–55 mg KOH/g with minimized solvent residues serve medical-grade and optical-grade polyurethane systems. Japanese electronics and display laminate producers in Osaka and Nagoya clusters drive qualification demand for these ultra-low-impurity specifications.
- Branched Diols:Architectures incorporating pendant alkyl groups deliver enhanced low-temperature flexibility for cold-climate automotive seals and gaskets.
- Specialty Diols:Custom molecular-weight distributions tailored to specific coating viscosity requirements serve automotive refinish formulators seeking solvent-free system compatibility.
Linear diols absorb the bulk of installed capacity; high-purity diols are expanding most quickly.
End User:
Customer procurement patterns divide between specification-driven automotive tiers and price-sensitive construction segments, with coatings and adhesives occupying intermediate positions on qualification intensity.
- Automotive:OEM interior specifications mandate polycarbonate diol-based polyurethanes for dashboards, seating, and door panels to meet durability and hydrolysis resistance requirements. German and Japanese automotive manufacturers maintain direct supply relationships with diol producers for molecular-weight-specified volumes.
- Coatings:Solvent-free formulation mandates under REACH and China's GB standards redirect demand toward low-emission polycarbonate diol architectures. Automotive refinish and industrial maintenance applications in France and the Netherlands drive fastest adoption as formulators rebuild raw material libraries to preempt substance sunset clauses.
- Adhesives:Food-contact and consumer goods applications in China face incremental purity benchmarks under SAMR GB standards, requiring requalification of existing supply chains.
- Construction:Sealant and waterproofing membrane producers prioritize cost-efficient medium-molecular-weight grades, accepting longer cure times in exchange for material savings.
Automotive captures the steepest pricing premiums; coatings is gaining share fastest on regulatory momentum.
Application:
Polyurethane system types demand differentiated diol molecular weights and hydroxyl functionalities, with elastomer systems commanding the most stringent purity specifications.
- Polyurethane Production:General-purpose polyurethane systems utilize medium-molecular-weight polycarbonate diols as soft-segment precursors, with automotive interior applications dominating volume.
- Thermoplastic Elastomers:TPU compounds require precise molecular-weight control to balance processability and mechanical properties. Japanese and Korean elastomer compounders are accelerating qualification cycles for solvent-reduced transesterification grades.
- Flexible Foam:Bedding and furniture applications employ lower-molecular-weight diols to achieve target density and resilience specifications.
- Rigid Foam:Insulation panel producers incorporate polycarbonate diols for hydrolysis resistance in high-humidity climates, though volume remains constrained by cost relative to conventional polyols.
Polyurethane production holds the largest volume position; thermoplastic elastomers is climbing the fastest on medical and optical grade penetration.
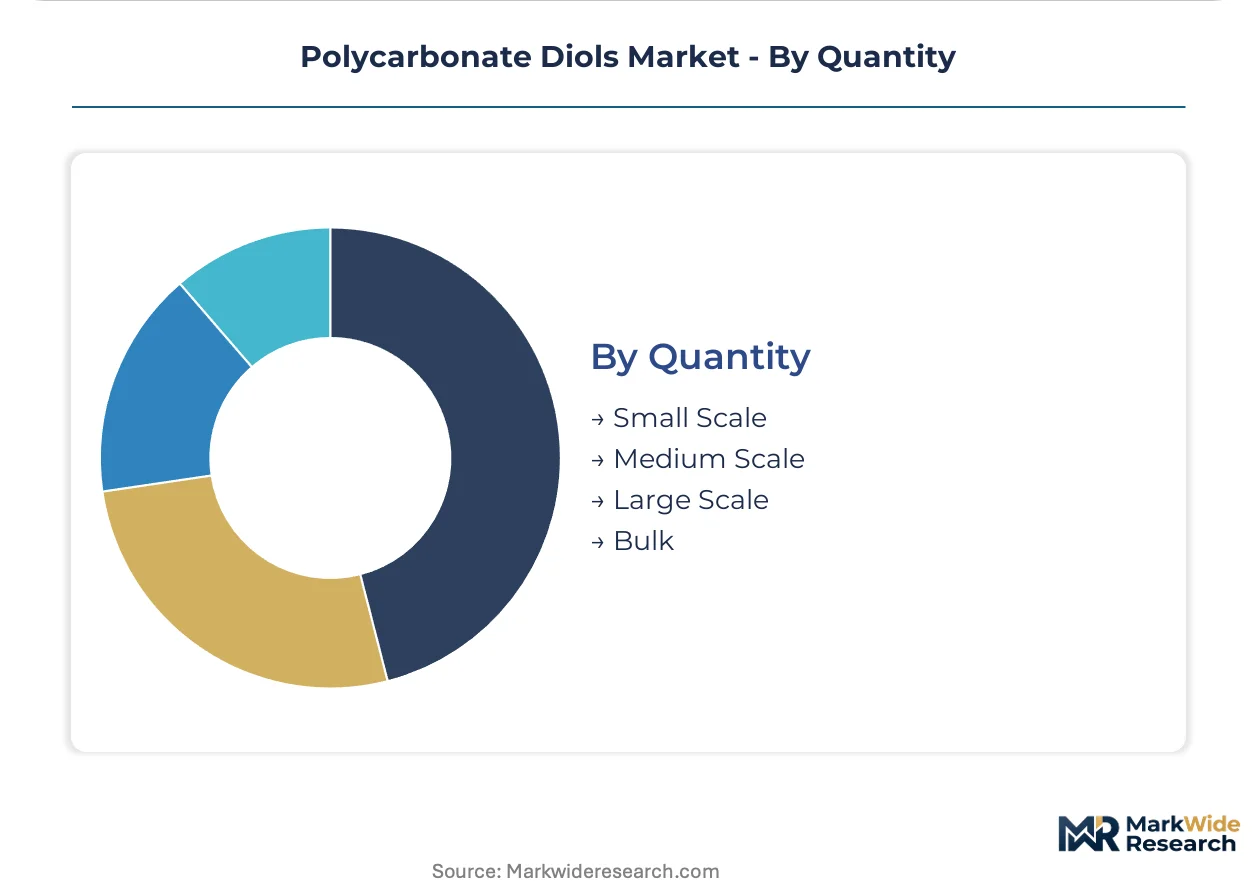
Quantity:
Packaging and logistics configurations align with customer scale and integration depth, with bulk arrangements displacing spot-market purchasing among large coatings clusters.
- Bulk:Tanker and railcar deliveries serve integrated polyurethane manufacturers and large coatings compounds with dedicated storage infrastructure. Jiangsu and Shandong coating clusters in China demand captive supply arrangements for medium-molecular-weight grades.
- Large Scale:Intermediate bulk containers and drum shipments address mid-tier adhesive and sealant producers seeking volume pricing without dedicated handling equipment.
- Medium Scale:Palletized drum configurations serve specialty coatings formulators and regional construction chemical distributors.
- Small Scale:Laboratory and pilot-scale packaging supports medical-grade polyurethane developers and optical coating R&D facilities in Japan and Germany.
Bulk quantities command the tightest supply relationships; large scale is expanding most quickly as mid-tier formulators consolidate procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phosgene chemistry clusters in Germany and Japan anchor polycarbonate diol production capacity. Automotive coating demand in China and synthetic leather growth in South Korea redirect trade flows across Asian supply corridors.
Germany
Automotive interior specifications from BMW and Mercedes-Benz drive polycarbonate diol consumption for thermoplastic polyurethane dashboards. REACH authorization through ECHA restricts phosgene-derived intermediates, forcing reformulation cycles among Cologne-area coatings compounders. The Ruhr industrial corridor hosts backward-integrated producers serving captive demand from adhesive manufacturers.
China
Domestic synthetic leather producers in Zhejiang and Guangdong provinces pull higher-purity grades for automotive seating applications. GB standards under SAMR set incremental purity benchmarks for food-contact adhesives, triggering supply chain requalifications. The Jiangsu coating cluster demands captive supply arrangements for medium-molecular-weight grades from local diol producers.
Japan
Electronics and display laminate producers in Osaka and Nagoya clusters qualify ultra-low-impurity specifications for optical-grade polyurethane systems. METI chemical management frameworks influence export compliance protocols for producers serving Korean and Taiwanese automotive tiers. The Chubu region anchors proprietary melt-transesterification technology deployment.
United States
Automotive OEMs in Michigan and Ohio specify hydrolysis-resistant polyurethanes for interior components facing durability mandates. EPA VOC regulations for industrial coatings redirect formulation strategies toward low-emission architectures. The Gulf Coast petrochemical corridor supplies alkylene carbonate feedstocks to domestic diol producers.
South Korea
Elastomer compounders accelerate qualification cycles for solvent-reduced transesterification grades in medical device applications. MFDS medical-grade polyurethane standards compress approval timelines for imported high-purity diols. The Busan-Ulsan industrial complex concentrates thermoplastic elastomer production for export markets.
Polycarbonate Diols Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue non-phosgene chemistry routes to bypass feedstock volatility. The vendor base concentrates around integrated petrochemical groups and specialty polyol specialists with captive phosgene access. Three archetypes dominate: backward-integrated chemical conglomerates, technology-specialized Japanese producers, and scale-driven Chinese compounders. Competitive moves center on capacity expansion in high-purity grades and strategic partnerships with automotive coating formulators.
Within the technology-specialized tier, Tosoh exemplifies proprietary process differentiation while Covestro anchors European supply corridors through integrated phosgene chemistry. Jiangsu Chemical Research occupies the scale-driven position serving domestic Chinese coatings clusters. These three producers represent distinct competitive vectors: solvent-reduction technology, feedstock integration, and volume economics.
| Leading Market Players |
|---|
| UBE Chemical |
| Tosoh |
| Covestro |
| Asahi Kasei |
| Perstorp |
| Caffaro Industrie |
| Cromogenia-Units |
| Kuraray |
| Jiangsu Chemical Research |
| Others |
Supply Flow & Price Mechanics
Phosgene feedstock costs transmit directly through polycarbonate diol pricing tiers, with chlorine and propylene oxide volatility compressing margins for non-integrated converters in Germany and China while backward-integrated producers sustain premium positioning in medical-grade segments.
Pricing Analysis
Technical service bundling separates premium-grade polycarbonate diol suppliers from commodity sellers, with formulation support and regulatory documentation included in optical-grade contracts but unbundled in standard thermoplastic polyurethane volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity certification and hydroxyl value precision, with REACH-registered grades commanding substantial premiums over non-registered alternatives. Pricing pressure stems from Asian scale producers compressing medium-molecular-weight segments, forcing European incumbents to defend medical-grade positioning. Coatings formulators in automotive refinish show highest price sensitivity due to reformulation cycle costs, while medical device manufacturers absorb premiums for MFDS-compliant supply security.
Supply Chain Analysis
Reverse-logistics flows for spent catalyst and solvent recovery concentrate in the Chubu region, where Tosoh and UBE Chemical operate closed-loop transesterification refineries that feed regenerated materials back into optical-grade production. Manufacturing gravity centers on Germany, Japan, and China, with high-purity asset concentration in Osaka-Nagoya and Cologne-Ruhr corridors creating single-source vulnerability for medical-grade buyers. The supply chain draws from alkylene carbonate, phosgene, and diol initiator inputs, with chlorine market volatility transmitting unpredictably through European phosgenation routes. Tariff exposure intensifies for Korean elastomer compounders sourcing Japanese high-purity grades under METI export compliance protocols. Distribution runs through direct long-term contracts displacing spot purchasing among automotive tiers and large coatings clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
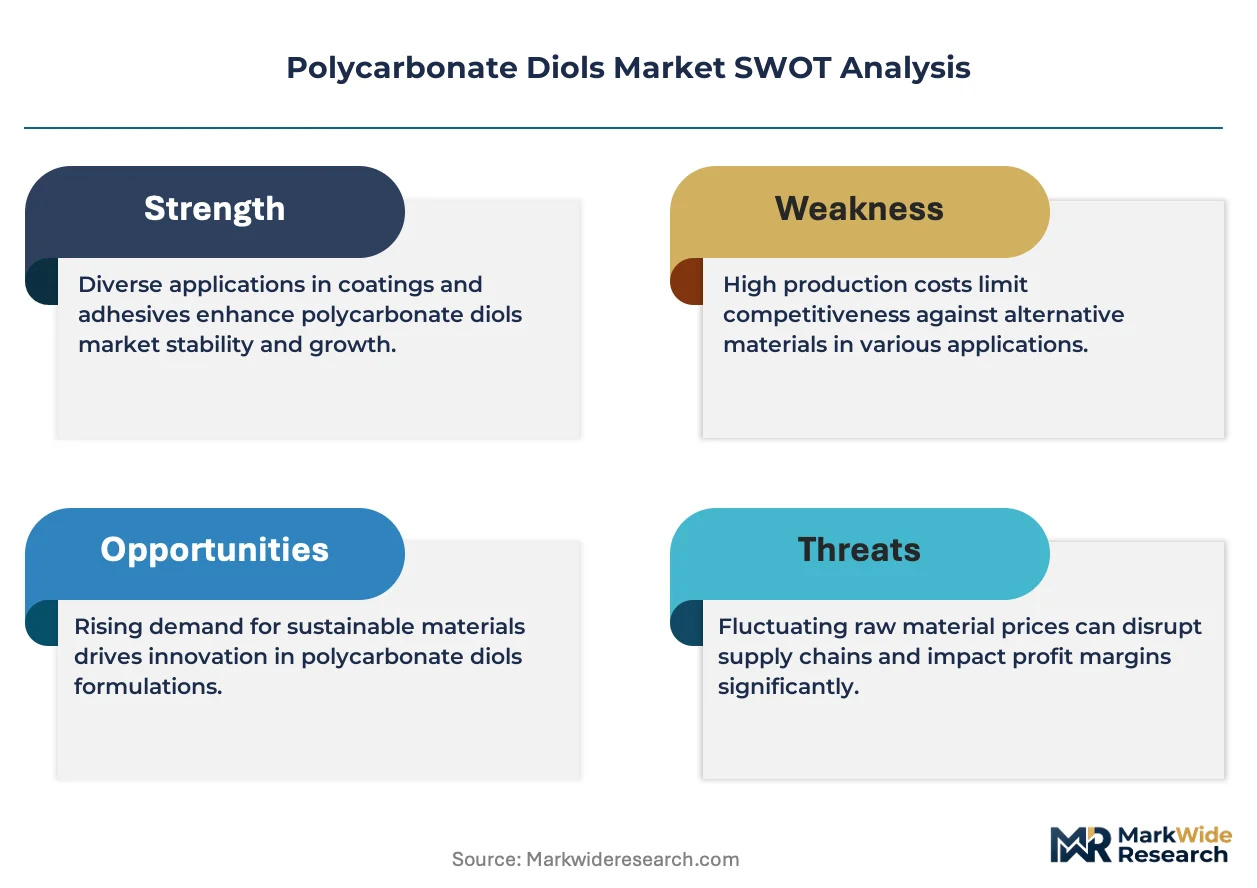
REACH authorization timelines and phosgene-handling certification requirements erect substantial compliance moats that favor incumbent producers with established ECHA registrations and qualified plant operators, marginalizing aspirants lacking 18-24 month authorization runway.
For Market Incumbents: Hedge feedstock exposure through captive alkylene carbonate supply or long-term offtake agreements with Gulf Coast petrochemical producers, while accelerating non-phosgene transesterification capacity to preempt solvent-residue regulatory tightening. Defend medical-grade positioning by deepening METI and MFDS certification depth before Korean and Chinese competitors complete qualification cycles. Prioritize channel control through integrated supply relationships with Jiangsu and Shandong coatings clusters to lock out scale-driven domestic rivals.
For New Entrants and Emerging Players: Digital-channel direct procurement platforms offer the lowest-friction entry vector for small-scale specialty diol volumes serving optical coating R&D facilities and pilot-scale medical polyurethane developers. Target India's PLI-incentivized specialty chemicals corridor for compounding operations that bypass European REACH registration burdens while serving Asian export markets. Pursue white-space capture in solvent-reduced transesterification grades for Korean elastomer compounders facing compressed approval timelines under MFDS standards.
For Investors and Strategic Acquirers: Accelerated qualification cycles for non-phosgene grades among Japanese and Korean elastomer compounders are the leading indicator that technology-specialized producers with proprietary melt-transesterification assets will command sustained premium multiples over commodity-scale competitors. Long-term viability favors integrated chemical conglomerates with backward phosgene control or technology-specialized Japanese producers with regulatory pre-compliance depth. Monitor ECHA substance authorization amendments targeting aromatic intermediates as the signal for reformulation-driven demand inflection in aliphatic polycarbonate diol architectures.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosgene | Covestro and UBE Chemical control margin compression across European and Asian supply corridors through captive feedstock production. |
| Non-Phosgene Process Transition | Tosoh's proprietary melt-transesterification technology reduces solvent residues and compresses qualification timelines for medical-grade buyers. |
| High-Purity Grade Capacity Expansion | Japanese and Korean producers capture premium positioning in optical coating and synthetic leather applications requiring ultra-low impurity specifications. |
| Integrated Supply Partnerships | Direct contracts between diol producers and automotive coating formulators displace spot-market purchasing in German and Chinese tiers. |
| Regulatory Pre-Compliance Investment | Early REACH registration and METI protocol alignment create barrier-to-entry moats against emerging Asian scale competitors. |
Methodological Framework
Multi-period observation of polycarbonate diol capacity utilization, import-export flows, and ECHA registration timelines anchored the trend analysis, supplemented by interviews with plant managers at European and Asian production facilities, procurement leads at automotive OEMs and coatings formulators, technical R&D directors at polyurethane compounders, and distribution channel partners serving specialty chemicals markets. Secondary validation drew from customs and trade data, Cefic and ACC industry reports, SEC 10-K filings of listed chemical conglomerates, and SAMR GB standards documentation. Bottom-up volume modeling triangulated against top-down value estimates derived from molecular-weight-grade pricing benchmarks.
Segment-weighting across product type, end user, application, and quantity dimensions structured the analytical framework, with linear diols, high-purity diols, automotive specifications, coatings formulations, and bulk packaging configurations each assigned demand coefficients. CAGRs were derived from regression analysis of historical consumption patterns projected across the analysis window, incorporating automotive interior mandate adoption curves, REACH reformulation cycle timing, and synthetic leather growth trajectories in China and South Korea.
The model holds under stable phosgene supply and incremental regulatory tightening; deviation in chlorine market volatility or accelerated ECHA substance sunset clauses would shift volume trajectories and pricing premiums. Forecasts reflect documented assumptions about qualification timeline durations and automotive tier procurement consolidation. Practitioners should monitor ECHA authorization amendment announcements and MFDS medical-grade standard revisions for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
Asia-Pacific Polycarbonate (PC) Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Paste PVC Resin Market