
 Carbon Fiber Coatings Market | 2026-2036
Carbon Fiber Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Carbon Fiber Coatings Market Analytics
Aerospace OEMs is reorganizing procurement priorities toward lightweight coated composites as fuel-efficiency mandates intensify. Toray Industries, Inc. leverages its integrated precursor-to-prepreg chain to dominate high-performance coating supply for aviation programs. SGL Carbon anchors European demand through its carbon fiber operations serving automotive and industrial buyers. Hexcel Corporation specializes in resin formulation chemistry that bonds protective layers to thermoset substrates under extreme thermal cycling.
Carbon fiber coatings constitute protective polymer layers applied to carbon fiber reinforced polymer substrates, typically formulated from epoxy, polyester, or polyurethane resin systems with functional additives for UV resistance, corrosion inhibition, and surface finish optimization. These coatings shield structural fibers from environmental degradation while enabling paint adhesion and electrical isolation in finished components. Epoxy coatings command the largest value share due to their superior adhesion to carbon fiber surfaces and compatibility with aerospace qualification protocols. Polyurethane coatings represent the fastest-expanding category, driven by automotive exterior panel applications requiring flexibility and weathering resistance. Spray coating technology leads volume deployment for repair and aftermarket operations, while automated fiber placement with inline coating deposition captures the highest-margin OEM contracts.
EPA regulates volatile organic compound emissions from coating operations under Clean Air Act standards, compelling formulation shifts toward waterborne and high-solids systems. REACH restricts hazardous substance content in imported coated articles entering European supply chains, affecting cross-border material certification. FAA airworthiness directives mandate flame-resistance and smoke-toxicity testing for coated cabin interior components, creating qualification barriers for unproven suppliers. Stakeholders must weigh regulatory compliance investments against the cost of exclusion from qualified supplier lists in regulated end markets.
Market Dynamics
Aerospace OEM procurement reorganization toward lightweight coated composites is compressing qualification timelines while EPA emissions standards force simultaneous reformulation of coating chemistries. This dual pressure is restructuring supplier relationships and capital allocation across the value chain.
Growth Catalysts
- REACH chemical restrictions:European regulatory pressure on hazardous substance content is accelerating waterborne epoxy formulation development for cross-border material certification.
- Automotive exterior panels:Polyurethane coating demand from vehicle manufacturers requiring flexibility and weathering resistance is pulling capacity expansion in Germany's automotive supply corridor.
- Automated fiber placement:Inline coating deposition technology is capturing high-margin OEM contracts by reducing labor content and improving thickness uniformity.
Market Restraints
- Precursor supply concentration:Acrylonitrile cost volatility and limited polyacrylonitrile fiber suppliers create input price instability for coating substrate manufacturers.
- Japanese carbon fiber dominance:Toray Industries and Mitsubishi Chemical control precursor supply, creating geographic concentration risk for European and North American coaters.
- Thermal cycling adhesion limits:Epoxy coating performance degradation under repeated extreme temperature exposure constrains reusability in high-heat aerospace applications.
Strategic Opportunities
- India automotive manufacturing:PLI scheme incentives for electric vehicle production are creating first-mover openings for polyurethane coating suppliers to domestic EV platforms.
- FAA airworthiness directives:Flame-resistance and smoke-toxicity mandates for cabin interiors are generating qualification-driven demand for certified coating systems.
- UV-curable nanocoatings:Convergence of photochemistry and nanomaterial science is enabling thin-film deposition with reduced volatile organic compound content.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise combining epoxy-polyurethane chemistry with aerospace qualification protocols is concentrated among retiring specialists.
- Multi-agency certification timelines:Simultaneous EPA, FAA, and REACH compliance processes extend product launch cycles beyond capital recovery windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carbon Fiber Coatings Market |
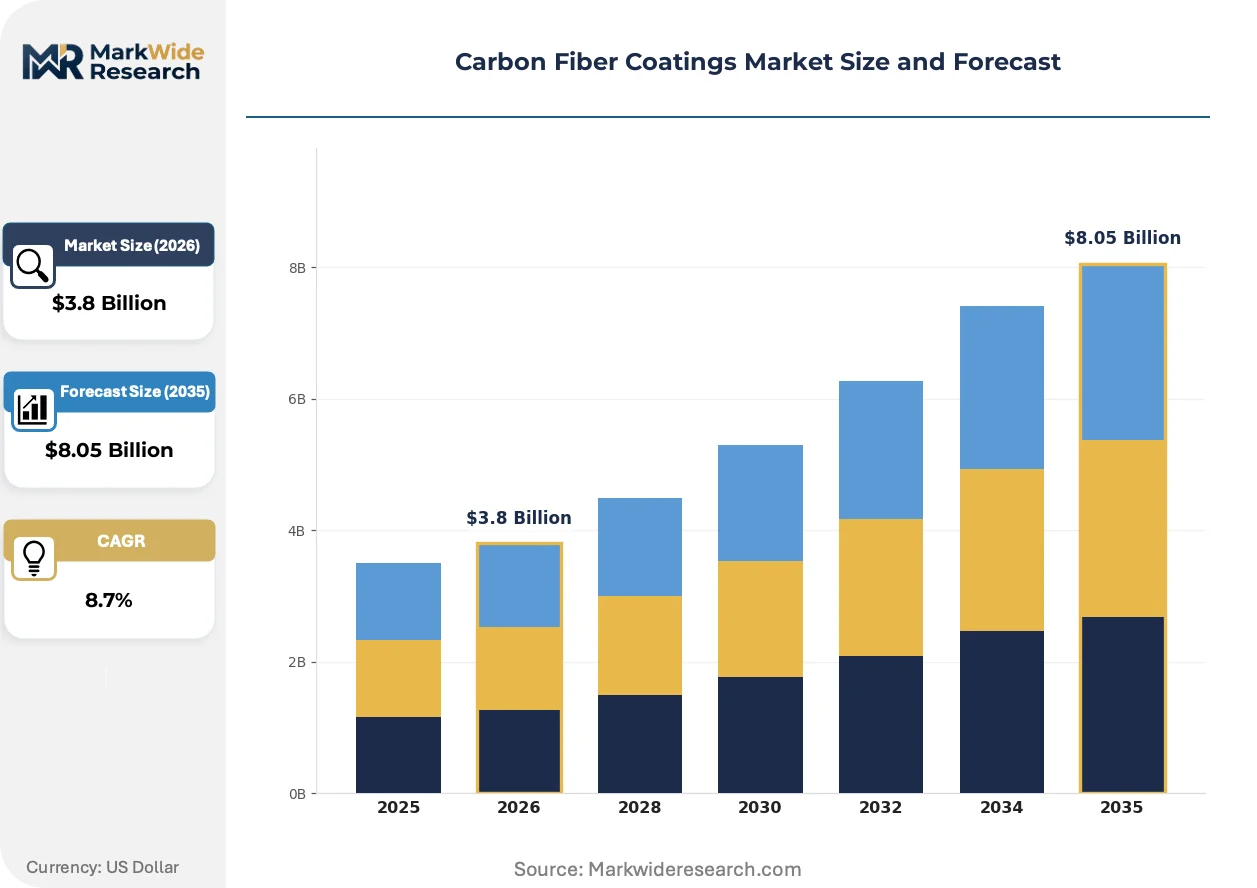
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy Coatings, Polyester Coatings, Vinyl Coatings, Polyurethane Coatings Application: Aerospace, Automotive, Marine, Industrial End User: OEMs, Tier-1 Suppliers, Manufacturing Plants, Maintenance Providers Technology: Vacuum Infusion, Spray Coating, Hand Lay-Up, Automated Fiber Placement |
| Companies Covered | Toray Industries, Inc., SGL Carbon, Teijin Limited, Mitsubishi Chemical Carbon Fiber and Composites, Inc., Hexcel Corporation, Solvay, Hyosung Advanced Materials, Formosa Plastics Corporation, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carbon Fiber Coatings Market Evolving Landscape
Coating deposition technology is fragmenting across multiple competing platforms while regulatory jurisdictions impose divergent chemical restrictions. These parallel developments are forcing suppliers to maintain parallel qualification tracks.
Solvent-borne epoxy systems are fragmenting as waterborne and high-solids alternatives achieve performance parity. Aerospace OEMs are adopting hybrid spray-electrodeposition methods for primary structure coating. This technology is fragmenting the installed equipment base and compressing margins for single-process coating houses.
EPA Clean Air Act standards on volatile organic compound emissions are tightening permissible limits for coating operations. Formulators are shifting toward waterborne systems with higher solids content. Aerospace suppliers in California and Texas are most affected, accelerating partnerships with waterborne resin specialists.
Buyer consolidation among tier-one automotive suppliers is compressing coating procurement cycles. Long-term supply agreements with volume commitments are displacing spot purchasing for exterior panel programs. Germany's Stuttgart-Munich corridor exhibits this pattern most acutely, with BMW and Mercedes-Benz centralizing coating qualification.
Carbon Fiber Coatings Market Segmentation
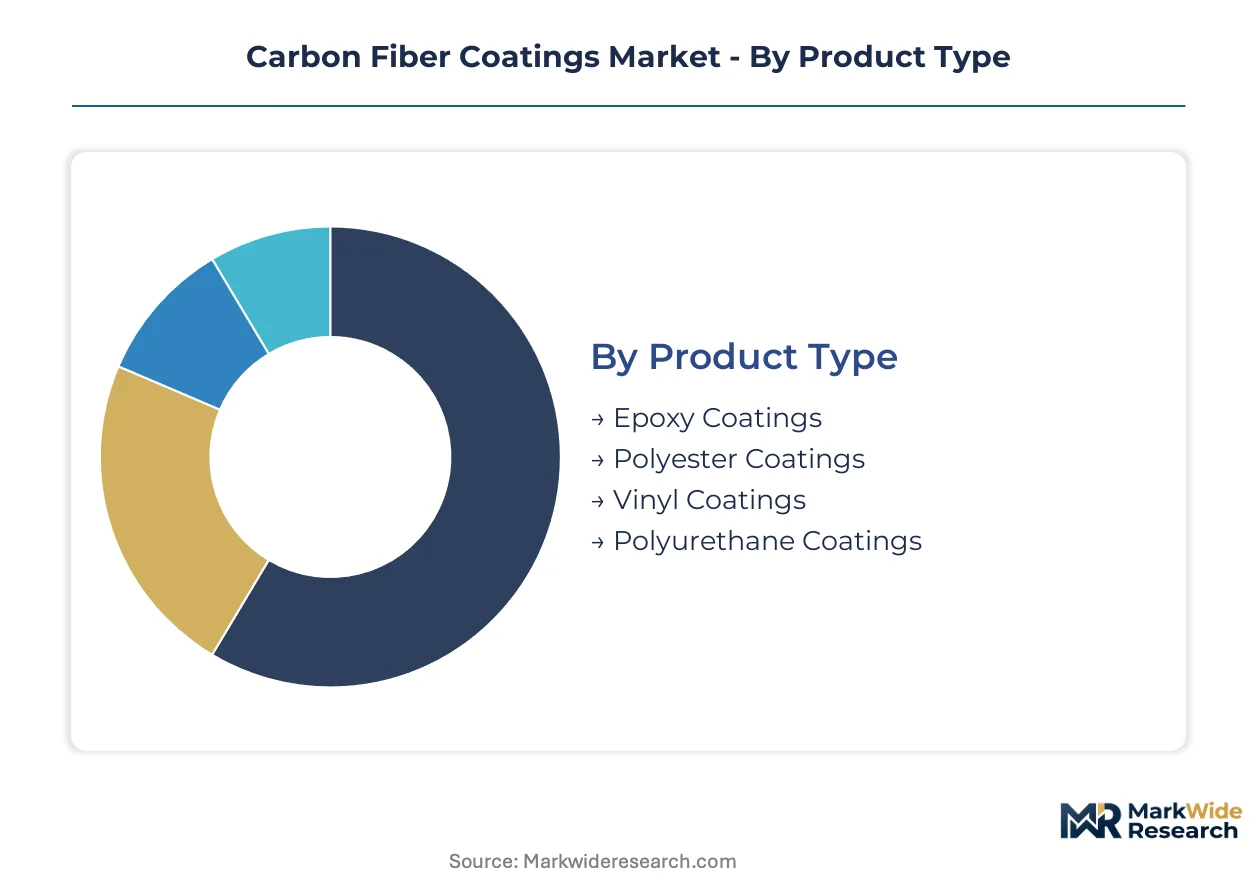
Carbon fiber coating procurement flows through distinct channel configurations that vary by volume scale, technical qualification requirements, and margin structure. Understanding these pathway differences enables suppliers to align formulation investments with the appropriate customer tier and application criticality.
Product Type:
Epoxy and polyurethane formulations dominate direct OEM supply channels, while polyester and vinyl systems flow heavily through tier-1 distributor networks serving aftermarket repair operations.
- Epoxy Coatings:Thermoset polymer systems formulated with bisphenol-A or novolac resins deliver superior adhesion to carbon fiber surfaces and compatibility with aerospace qualification protocols. Aerospace OEMs in Germany's Stuttgart corridor specify these coatings for primary structure applications where FAA flame-resistance mandates apply. Thermal cycling performance under extreme temperature exposure remains the primary constraint limiting reusability in high-heat applications.
- Polyurethane Coatings:Aliphatic and aromatic isocyanate-based systems provide flexibility and weathering resistance for exterior automotive panels. BMW and Mercedes-Benz centralized procurement in Bavaria is pulling capacity expansion for these formulations. REACH chemical restrictions on hazardous substance content are accelerating waterborne polyurethane development for cross-border material certification.
- Polyester Coatings:Unsaturated polyester resin systems with styrene monomers serve cost-sensitive industrial applications and marine gelcoat replacement. These formulations concentrate in spray-applied repair channels.
- Vinyl Coatings:Polyvinyl chloride plastisol and organosol systems provide electrical insulation and chemical resistance for specialized industrial components. Demand concentrates in manufacturing plant maintenance procurement.
Epoxy coatings dominate installed base across aerospace-qualified supply chains. Polyurethane coatings are where expansion concentrates as automotive exterior panel specifications multiply.
Application:
Cost tier stratification separates qualification-intensive aerospace programs from high-volume automotive exterior contracts and price-competitive industrial maintenance coatings.
- Aerospace:Primary and secondary structure coatings must satisfy FAA airworthiness directives for flame-resistance and smoke-toxicity in cabin interiors. Toray Industries' integrated precursor-to-prepreg supply chain anchors coating qualification for next-generation airframe programs. Multi-agency certification timelines extending beyond capital recovery windows create barriers for unproven suppliers.
- Automotive:Exterior panel applications require flexibility, UV stability, and paint adhesion compatibility for premium vehicle finishes. Germany's automotive supply corridor around Stuttgart and Munich exhibits acute buyer consolidation, with long-term supply agreements displacing spot purchasing.
- Marine:Gelcoat replacement and hull protection systems prioritize moisture barrier performance and osmotic blister resistance. These applications flow through specialized marine distributor channels.
- Industrial:Chemical processing equipment, robotics, and automation infrastructure use coatings for corrosion inhibition and electrical isolation. Procurement concentrates among maintenance providers with volume discount arrangements.
Aerospace commands premium pricing tiers through qualification barriers. Automotive represents the steepest expansion trajectory as electric vehicle platform adoption accelerates coating specification changes.
End User:
Volume scale and technical specification authority separate direct OEM relationships from tier-1 supplier consolidation and fragmented maintenance provider procurement.
- OEMs:Original equipment manufacturers in aerospace and automotive sectors control coating qualification protocols and mandate inline deposition technology for high-margin contracts. These buyers compress procurement cycles while extending qualification timelines.
- Tier-1 Suppliers:Consolidated automotive exterior panel manufacturers centralize coating procurement for BMW, Mercedes-Benz, and other premium brands. Long-term supply agreements with volume commitments dominate this channel.
- Manufacturing Plants:Industrial equipment producers and automation integrators specify coatings for in-house carbon fiber component production. Procurement patterns favor spot purchasing with technical consultation.
- Maintenance Providers:Repair shops and aftermarket service operations drive spray coating volume for damage remediation and surface refurbishment. This channel exhibits highest price sensitivity and shortest procurement cycles.
OEMs anchor margin capture through qualification control. Tier-1 suppliers are where volume concentration is accelerating.
Technology:
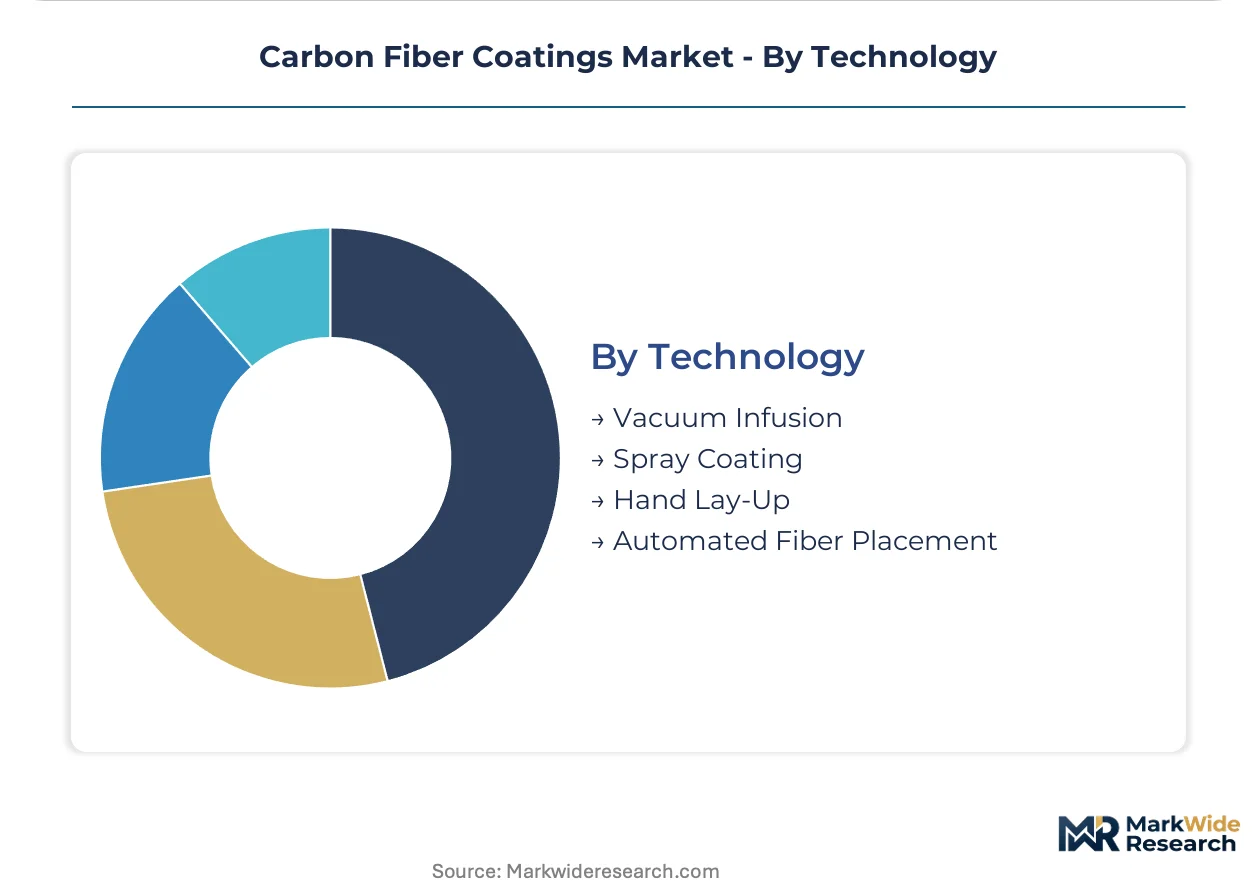
Maturity differentiation separates established manual processes from capital-intensive automated systems capturing high-margin OEM contracts.
- Vacuum Infusion:Resin transfer molding with integrated coating deposition enables complex geometry processing for marine and industrial components. This technology serves mid-volume production with moderate capital requirements.
- Spray Coating:Conventional airless and HVLP spray systems dominate repair, aftermarket, and low-volume manufacturing applications. Labor content and thickness variability limit margin expansion in this channel.
- Hand Lay-Up:Manual resin application with brush or roller coating persists in custom fabrication and prototype development. Skilled technician scarcity constrains capacity scaling.
- Automated Fiber Placement:Robotic tow placement with inline coating deposition achieves thickness uniformity and reduces labor content for aerospace primary structures. Hexcel Corporation specializes in resin formulation chemistry compatible with this platform under extreme thermal cycling conditions.
Spray coating dominates installed equipment base across repair and aftermarket channels. Automated fiber placement is where high-margin OEM contract capture concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German coating formulators export specialized epoxy systems to aerospace OEMs in France and the United Kingdom, establishing a westward trade corridor that dominates European carbon fiber coating procurement.
United States
Aerospace OEMs in Washington State and California drive demand for FAA-qualified coating systems. EPA Clean Air Act standards on volatile organic compound emissions compel formulators toward waterborne epoxy alternatives. The Pacific Northwest cluster around Seattle concentrates automated fiber placement operations for Boeing supply chains.
Germany
Automotive exterior panel specifications from BMW and Mercedes-Benz pull polyurethane coating capacity expansion. REACH chemical restrictions on hazardous substance content accelerate waterborne formulation development for cross-border certification. The Stuttgart-Munich corridor exhibits acute buyer consolidation among tier-one suppliers.
Japan
Toray Industries and Mitsubishi Chemical control polyacrylonitrile precursor supply, creating upstream concentration for coating substrate manufacturers. METI industrial standards govern carbon fiber composite quality protocols. The Tokyo-Nagoya industrial belt anchors integrated precursor-to-prepreg production chains.
China
Domestic electric vehicle platform adoption accelerates coating specification changes for lightweight body panels. MIIT manufacturing standards and GB certification requirements structure supplier qualification. The Yangtze River Delta cluster around Shanghai concentrates automotive carbon fiber component fabrication.
India
PLI scheme incentives for electric vehicle production create first-mover openings for polyurethane coating suppliers to domestic OEM platforms. BIS standards govern imported coated article compliance. The Maharashtra-Gujarat automotive corridor attracts tier-one supplier facility investments.
Carbon Fiber Coatings Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive carbon fiber operations. Market structure concentrates around precursor-to-coating supply chains where backward integration into polyacrylonitrile fiber production secures input cost stability. Three archetypes dominate: Japanese diversified materials groups with aerospace qualification heritage, European automotive-focused carbon fiber specialists, and Korean industrial conglomerates expanding through scale-driven capacity additions. Competitive moves center on strategic partnerships for waterborne formulation development and geographic expansion into Indian EV supply chains.
Within the integrated materials tier, Toray Industries, Inc. and Mitsubishi Chemical Carbon Fiber and Composites, Inc. occupy positions exemplifying Japanese precursor-to-prepreg supply chain control. SGL Carbon represents the European archetype anchoring automotive and industrial demand through its carbon fiber operations. Hexcel Corporation sits within the aerospace-specialized formulation segment, with resin chemistry expertise aligned to thermoset substrate bonding requirements.
| Leading Market Players |
|---|
| Toray Industries, Inc. |
| SGL Carbon |
| Teijin Limited |
| Mitsubishi Chemical Carbon Fiber and Composites, Inc. |
| Hexcel Corporation |
| Solvay |
| Hyosung Advanced Materials |
| Formosa Plastics Corporation |
| BASF SE |
| Others |
Value Network & Pricing Analysis
Ninety-day acrylonitrile inventory cycles at Japanese precursor producers compress margin buffers for European coaters while amplifying pricing power for integrated suppliers with captive polyacrylonitrile fiber production. This lead-time asymmetry between raw material availability and formulated coating delivery reshapes contract negotiations across aerospace and automotive procurement channels.
Pricing Analysis
Current-generation waterborne epoxy systems command substantial premiums over solvent-borne legacy formulations, while next-generation UV-curable nanocoatings remain priced at experimental tiers pending scale validation. Contract-based long-term offtake agreements dominate aerospace procurement, with price differentiation driven by FAA certification tier and volume scale commitments. Cost compression in automotive exterior panel coatings intensifies as BMW and Mercedes-Benz consolidate tier-one supplier relationships. Maintenance providers exhibit highest price sensitivity due to spot purchasing patterns and repair cycle urgency.
Supply Chain Analysis
Japan and Germany anchor carbon fiber coating supply through Toray Industries' integrated precursor-to-prepreg chain and SGL Carbon's European automotive operations. Acrylonitrile monomer, bisphenol-A epoxy resins, and aliphatic isocyanates constitute critical input dependencies. Single-source vulnerability concentrates in Japanese polyacrylonitrile precursor supply, creating geographic risk exposure for non-integrated coaters. Distribution runs through qualified OEM direct channels for aerospace, tier-one consolidated procurement for automotive, and specialized distributor networks for marine and industrial aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon fiber coatings market is recovering from cyclical compression in automotive production volumes, with electric vehicle platform adoption now restocking coating demand pipelines.
For Market Incumbents: Shield formulation expertise advantages by accelerating waterborne epoxy qualification under tightening EPA Clean Air Act standards. Deepen backward integration into polyacrylonitrile precursor supply through partnerships with Japanese suppliers or captive capacity additions in Germany's Stuttgart corridor. Certification investment for FAA flame-resistance mandates represents the critical defensive lever against emerging Asian competitors. For New Entrants and Emerging Players: Aftermarket spray coating technical service gaps where incumbent majors under-serve independent repair operators offer immediate white-space penetration. India's PLI scheme-supported electric vehicle production lines present the most penetrable geography for polyurethane coating qualification. Target tier-two automotive suppliers in the Maharashtra-Gujarat corridor with localized formulation support and rapid sample turnaround as the primary go-to-market angle. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with non-core carbon fiber coating divisions facing REACH compliance cost escalation. Long-term viability over a multi-year horizon rests on waterborne formulation transition completion and aerospace qualification heritage retention. Monitor acrylonitrile price volatility indices as the primary inflection signal for margin compression timing across coating substrate manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Waterborne Formulation Transition | EPA Clean Air Act compliance enables continued aerospace OEM contract eligibility. |
| Backward Integration into Precursor | Captive polyacrylonitrile fiber supply insulates margin from acrylonitrile volatility. |
| FAA Certification Investment | Flame-resistance qualification opens cabin interior coating procurement channels. |
| India Manufacturing Footprint | PLI scheme incentives align with domestic EV platform coating specifications. |
| Automated Deposition Partnership | Inline coating technology integration captures high-margin OEM structure contracts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with aerospace procurement directors, automotive tier-one supplier technical leads, coating formulation chemists, and marine distributor channel managers. Secondary validation drew from EPA emission standard filings, FAA airworthiness directive databases, REACH substance restriction updates, and customs trade flow records. Bottom-up volume estimates by coating type and application were triangulated against top-down value projections across the analysis window.
Across the modeling period, forecasts segment by resin chemistry, deposition technology, end-use industry, and regional regulatory cluster. CAGRs were derived from trend extrapolation of qualified supplier capacity additions and OEM program launch timelines. Key inputs include aerospace backlogs from Boeing and Airbus, automotive exterior panel content per vehicle trajectories, and waterborne formulation adoption curves in EPA-regulated jurisdictions.
Forecasts assume regulatory continuity in EPA Clean Air Act enforcement, REACH chemical restriction scope, and FAA airworthiness directive frameworks; material policy shifts would require re-modeling of waterborne transition timelines and qualification cost burdens. Recalibration cycles align with material shifts in aerospace OEM procurement reorganization, automotive platform electrification rates, and precursor supply concentration developments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Antimicrobial Coil Coating Market
Coatings
Anti-Microbial Coatings Market
Coatings
Solar Reflective Film Market
Coatings
Glazes Market
Coatings
Coating Thickness Gauge Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Polyurethane (PU) Coatings Market
Coatings
South Africa Protective Coatings Market
Coatings
UV Coatings Market
Coatings
Global Floor Coatings Market
Coatings
Global Coil Coatings Market
Coatings
Coating Resins Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Tablet Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
North America Hydrocarbon Fire Intumescent Coating Services Market