
 Plastic Calendering Resins Market | 2026-2036
Plastic Calendering Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Calendering Resins Market Intelligence
REACH compliance is broadening the cost-of-entry calculus for European resin suppliers, forcing reformulation investments before products reach German automotive Tier 1s or Italian flooring manufacturers. Formosa Plastics Corporation leverages integrated vinyl chloride monomer capacity to sustain margin control across PVC calendering grades. Westlake Corporation anchors North American supply through Gulf Coast petrochemical infrastructure. Shin-Etsu Chemical Co., Ltd. dominates specialty silicone-modified resin segments for high-performance automotive skins.
Plastic calendering resins are thermoplastic polymers, primarily polyvinyl chloride and polyethylene, that undergo continuous compression between heated rolls to achieve precise thickness tolerances of 0.05 mm to 2.0 mm for film and sheet applications. The process yields glossy, uniform surfaces used in flooring, packaging films, and automotive interior laminates where dimensional stability and weldability matter. Polyvinyl chloride occupies the largest volume share due to its established use in flooring and wall covering applications across building and construction end users. Thermoplastic elastomers represent the fastest-expanding product category as automotive OEMs seek soft-touch, low-VOC interior surfaces that meet stringent cabin air quality protocols. Packaging films maintain steady demand but face margin compression from thinner-gauge polyethylene alternatives in Asian export markets.
The EPA regulates volatile organic compound emissions from calendering operations under Clean Air Act standards, while OSHA enforces workplace exposure limits for vinyl chloride monomer in U.S. manufacturing facilities. In Europe, ECHA administers REACH substance restrictions that phase out phthalate plasticizers in consumer-facing calendered products. Stakeholders must monitor regulatory divergence between California's Proposition 65 update trajectory and EU MDR-aligned material safety requirements, as misalignment threatens to fragment product qualification costs across Atlantic supply chains.
Market Dynamics
REACH substance restrictions are forcing resin suppliers to abandon legacy phthalate plasticizers and rebuild formulation portfolios before products can access German automotive Tier 1s or Italian flooring manufacturers. This regulatory compression is reshaping competitive positioning across European supply chains.
Growth Catalysts
- Automotive lightweighting mandates:OEMs in Germany and Japan are specifying calendered PVC and TPE laminates for interior skins to reduce vehicle mass and improve energy efficiency.
- REACH plasticizer phase-outs:ECHA restrictions on phthalates in consumer-facing products are creating first-mover advantages for suppliers with bio-based or non-phthalate formulations already qualified.
- China's domestic calendering expansion:Integrated vinyl chloride monomer capacity along the Yangtze River Delta is serving both export flooring demand and local construction markets.
Market Restraints
- Vinyl chloride monomer price volatility:Feedstock costs tied to ethylene and chlorine markets create margin instability for non-integrated resin producers.
- Supply concentration in Gulf Coast petrochemicals:North American PVC resin production clusters in Texas and Louisiana, exposing buyers to hurricane-related disruption risk.
- Technical limitation in thin-gauge tolerance:Calendering below 0.05 mm remains difficult for polyethylene grades, ceding some packaging film applications to blown film alternatives.
Strategic Opportunities
- Underpenetrated medical packaging in India:CDSCO regulations are tightening sterilization standards, creating demand for high-clarity calendered films that meet USP Class VI requirements.
- Silicone-modified resin convergence:Shin-Etsu's specialty chemistry is enabling soft-touch automotive surfaces that combine TPE flexibility with silicone durability.
- EU Green Deal carbon border adjustments:CBAM implementation is incentivizing low-carbon calendering processes and renewable feedstock sourcing for European market access.
Industry Challenges
- Formulation chemist scarcity:REACH-compliant plasticizer expertise is concentrated among retiring specialists, complicating R&D timelines for mid-tier suppliers.
- Multi-jurisdiction certification burden:Simultaneous compliance with EPA Clean Air Act, ECHA REACH, and California Proposition 65 fragments product qualification costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Calendering Resins Market |
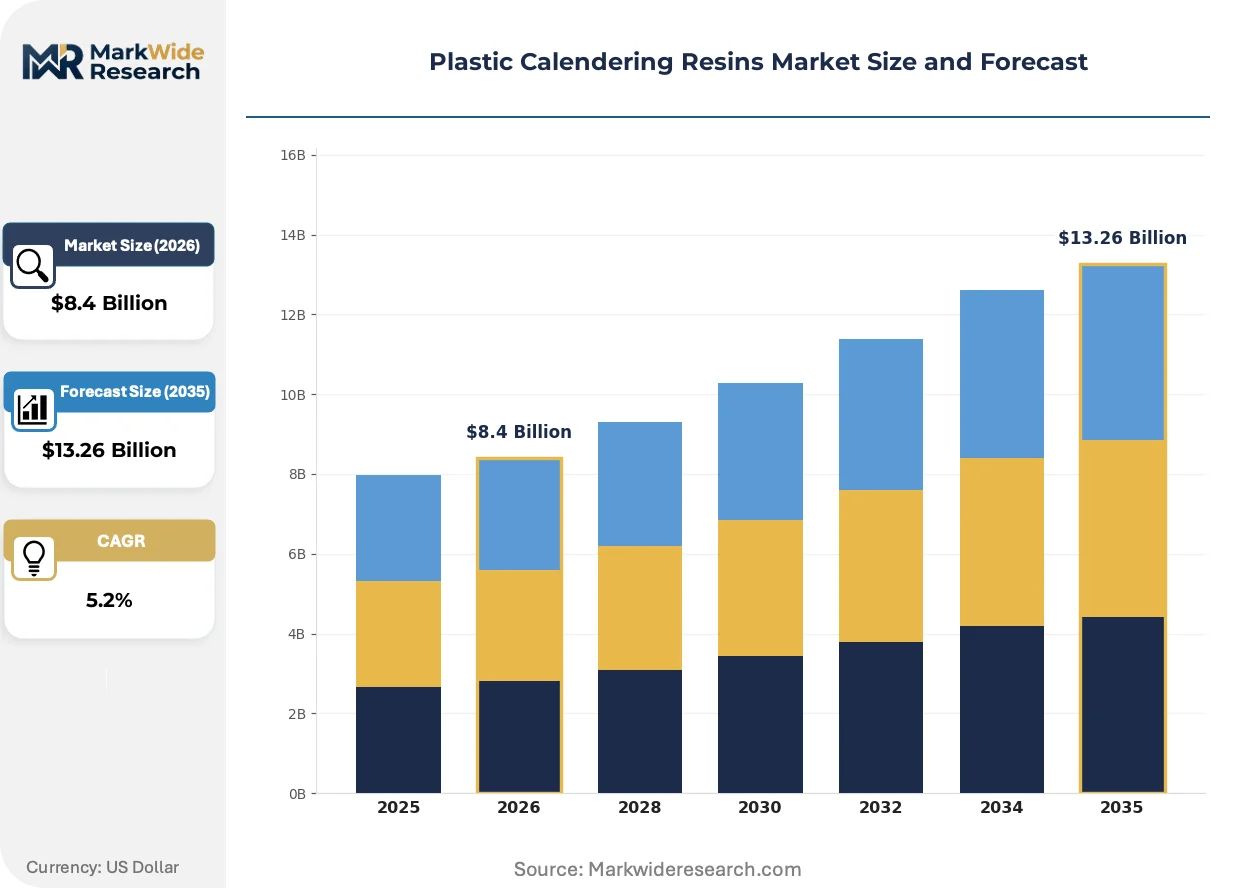
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.26 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyvinyl Chloride, Polyethylene, Polypropylene, Thermoplastic Elastomers Application: Packaging Films, Flooring, Automotive Interiors, Coatings End User: Building & Construction, Automotive, Consumer Goods, Electronics Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Formosa Plastics Corporation, Westlake Corporation, Eastman Chemical Company, Occidental Petroleum Corporation, Shin-Etsu Chemical Co., Ltd., SABIC, LG Chem, Reliance Industries Limited, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Calendering Resins Market Strategic Shifts & Innovations
Digitalization of calendering process control is compressing thickness tolerance bands and enabling real-time quality adjustment. These precision gains are opening applications previously reserved for extrusion or casting methods.
Multi-layer co-extrusion calendering is electrifying the automotive interior segment. This technology bonds dissimilar polymers into single-pass laminates with tailored surface and substrate properties. BMW and Mercedes-Benz suppliers are adopting it for dashboard skins and door panels. The process is electrifying material substitution away from spray-coated ABS toward pre-colored, low-VOC calendered films.
ECHA's 2025 REACH candidate list expansion is accelerating phthalate replacement across European flooring and wall covering applications. The regulation forces reformulation of plasticizer packages in consumer-facing products. Italian and German manufacturers are responding by qualifying bio-based adipates and trimellitates ahead of authorization deadlines.
Automotive OEMs are consolidating resin procurement through direct Tier 1 partnerships rather than distributor intermediaries. This channel compression bypasses traditional compounder networks and demands calendering resin suppliers provide formulation co-development services. The pattern is most visible in Germany, where Volkswagen and BMW have established preferred supplier programs for interior material innovation.
Plastic Calendering Resins Market Segmentation
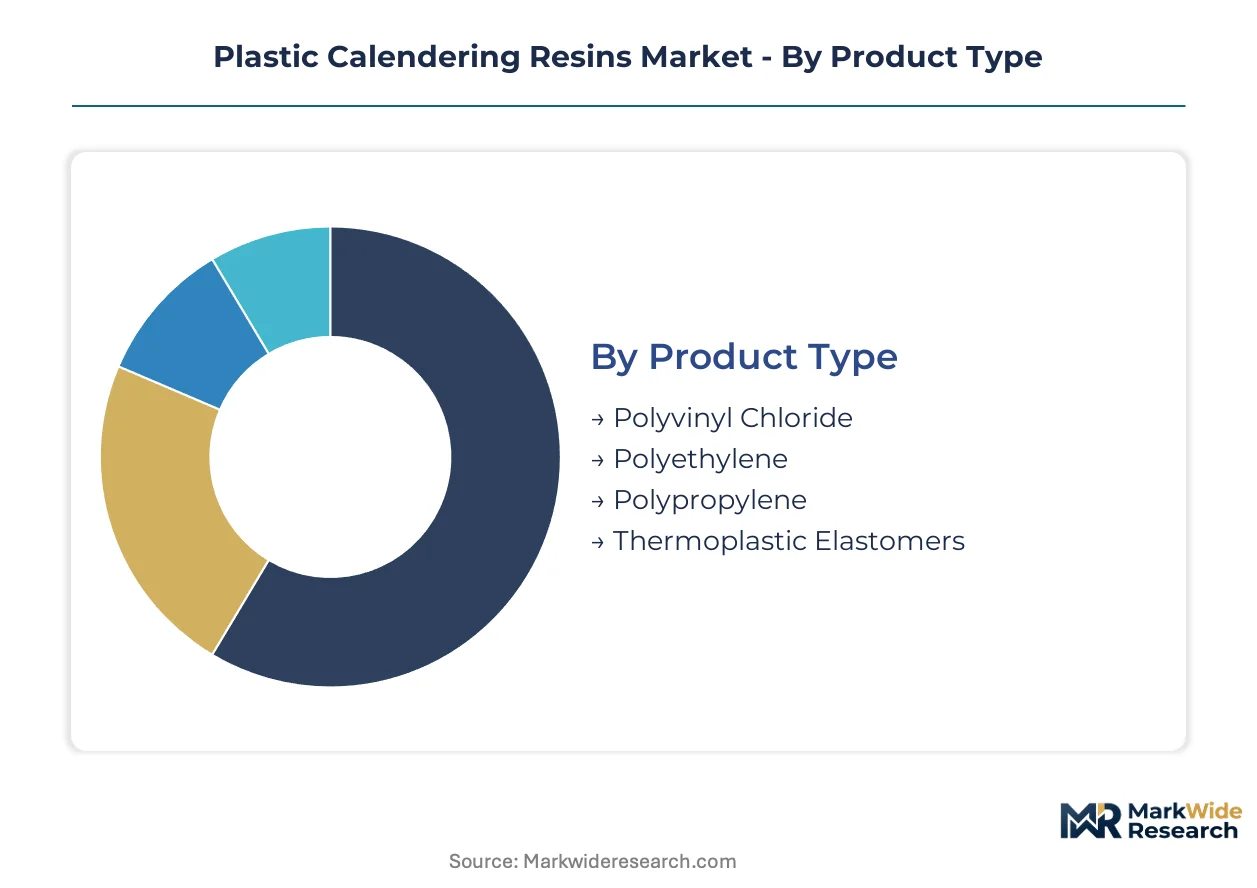
Calendering resin selection determines process economics and surface performance across film and sheet applications. Product chemistry, end-use specifications, and channel access each create distinct competitive arenas with different margin profiles and technical barriers.
Product Type:
Integration depth varies sharply: PVC and polyethylene serve as standalone calendering feedstocks with established supply chains, while thermoplastic elastomers and polypropylene often embed as co-extruded layers or specialty modifiers.
- Thermoplastic Elastomers:Soft-touch copolymers combining rubber elasticity with thermoplastic processability. Automotive OEMs in Germany and Japan specify TPE laminates for dashboard skins and door panels to meet low-VOC cabin air protocols.
- Polyvinyl Chloride:Homopolymer and copolymer grades dominate volume through established plasticizer compatibility and flame-retardant characteristics. Flooring manufacturers in Italy and wall covering producers across China source flexible and rigid PVC formulations for residential and commercial installations.
- Polyethylene:Linear low-density and high-density grades calender into packaging films and geomembranes. Thickness tolerance limitations below 0.05 mm restrict penetration into ultra-thin blown film territories.
- Polypropylene:Clarified and impact-modified grades serve automotive interior substrates and battery separator films. Higher melt temperatures demand modified roll configurations versus PVC processing.
Volume placements concentrate in Polyvinyl Chloride; the faster expansion belongs to Thermoplastic Elastomers.
Application:
Cost tier stratification separates commodity film applications from specification-driven automotive and flooring segments where formulation services command premium pricing.
- Flooring:Wear-layer and decorative films for luxury vinyl tile and sheet vinyl products. Italian manufacturers qualify REACH-compliant plasticizers ahead of ECHA authorization deadlines for phthalate restrictions.
- Automotive Interiors:Dashboard skins, door panels, and pillar trims requiring low-gloss, soft-touch surfaces. BMW and Mercedes-Benz suppliers adopt multi-layer co-extrusion calendering to bond dissimilar polymers in single-pass laminates.
- Packaging Films:Food-grade and industrial wrap applications facing margin compression from thinner-gauge polyethylene alternatives in Asian export markets.
- Coatings:Protective and decorative films for industrial substrates including metal laminates and textile backings.
Revenue concentration sits with Flooring; Automotive Interiors are climbing the fastest as lightweighting mandates accelerate material substitution.
End User:
Customer type fragmentation splits procurement patterns: automotive and electronics buyers demand co-development partnerships, while building materials and consumer goods purchasers prioritize scale and specification consistency.
- Building & Construction:Flooring, wall coverings, and waterproofing membranes for residential and commercial structures. China's domestic calendering capacity along the Yangtze River Delta serves both export demand and local construction markets.
- Automotive:Interior laminates and surface skins for mass-market and premium vehicle platforms. Volkswagen and BMW have established preferred supplier programs that bypass traditional compounder networks.
- Consumer Goods:Stationery, decorative films, and household products requiring consistent color matching and surface gloss.
- Electronics:Battery separator films and flexible circuit substrates demanding ultra-clean processing environments.
Demand gravity centers on Building & Construction; the steepest expansion trajectory runs through Automotive as OEMs consolidate direct Tier 1 partnerships.
Distribution Channel:
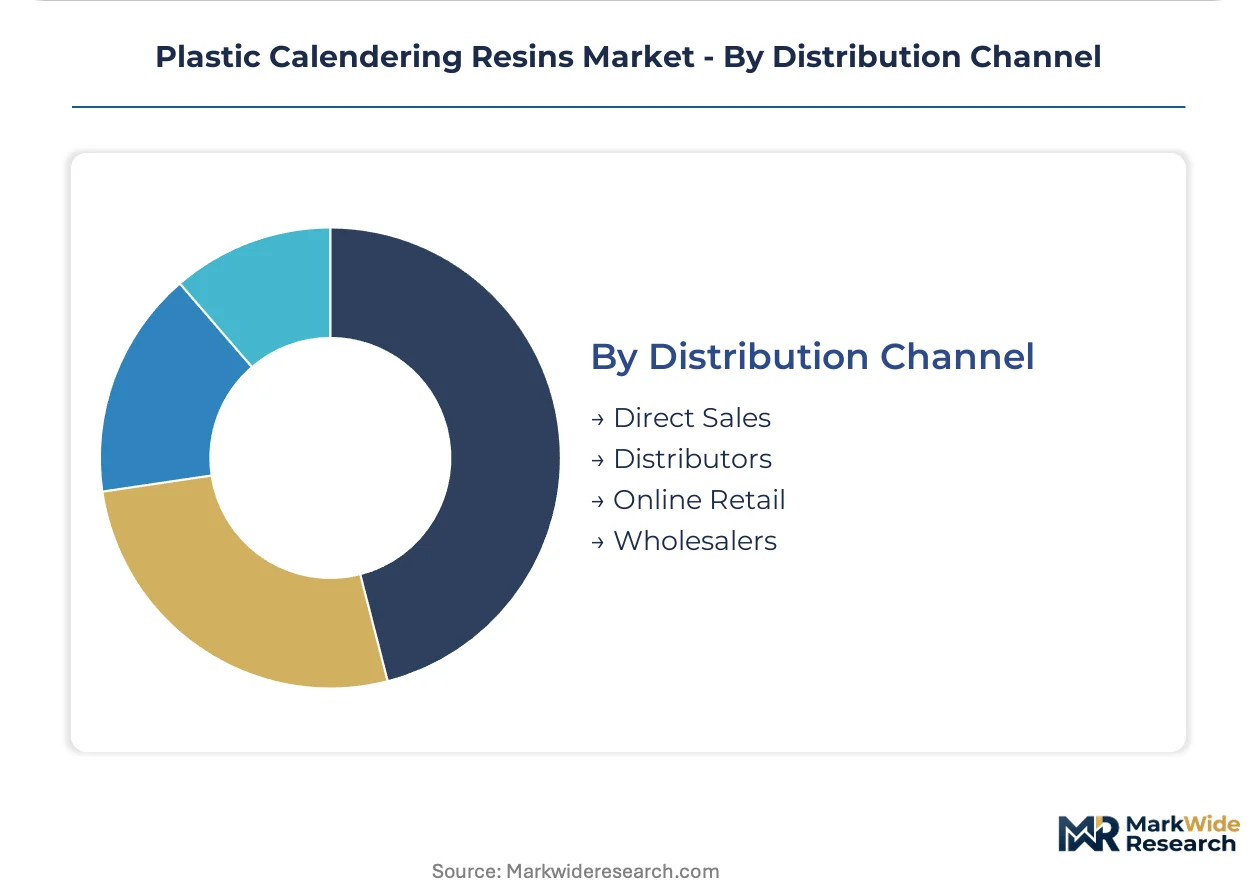
Supply concentration patterns favor direct relationships for specification-heavy automotive and electronics accounts, while distributors and wholesalers capture fragmented construction and consumer goods demand.
- Direct Sales:Long-term contracts with automotive Tier 1s and major flooring manufacturers including formulation co-development services. Formosa Plastics Corporation and Westlake Corporation anchor North American supply through integrated VCM capacity.
- Distributors:Regional stocking points serving mid-tier converters and smaller flooring operations with standard grades and technical support.
- Online Retail:Emerging channel for specialty grades and small-lot orders, particularly in Asia-Pacific markets with digital procurement adoption.
- Wholesalers:Volume aggregation for commodity PVC and polyethylene grades serving building materials retailers and consumer goods converters.
Transaction value concentrates in Direct Sales; Online Retail is gaining share fastest as procurement digitization penetrates specialty resin sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Yangtze River Delta special economic zones concentrate integrated vinyl chloride monomer capacity for calendering resin production. China's domestic calendering expansion serves export flooring demand and local construction markets simultaneously.
United States
Gulf Coast petrochemical infrastructure anchors North American PVC resin production in Texas and Louisiana. EPA Clean Air Act standards regulate volatile organic compound emissions from calendering operations. Hurricane exposure risk concentrates supply vulnerability along this coastal corridor.
Germany
Automotive lightweighting mandates from Volkswagen and BMW accelerate demand for calendered interior laminates. ECHA REACH substance restrictions phase out phthalate plasticizers in consumer-facing products. Bavarian chemical clusters host formulation co-development partnerships with Tier 1 suppliers.
China
Domestic flooring manufacturers and wall covering producers drive volume consumption of flexible and rigid PVC grades. MIIT industrial standards govern material specifications for construction applications. Yangtze River Delta integrated VCM capacity feeds both export markets and local building demand.
India
CDSCO tightening of sterilization standards creates demand for high-clarity calendered films in medical packaging. BIS certification requirements shape import substitution strategies for domestic resin producers. Maharashtra and Gujarat chemical corridors attract capacity investments for pharmaceutical-grade materials.
Japan
Automotive OEMs in Nagoya and Tokyo metropolitan areas specify low-VOC cabin air protocols for interior surface materials. METI energy efficiency guidelines incentivize lightweight material adoption. Shin-Etsu Chemical anchors specialty silicone-modified resin segments for premium automotive applications.
Plastic Calendering Resins Market Key Industry Players
East Asian producers anchor the integrated commodity tier; European and North American specialists hold formulation-intensive segments. Market structure splits between scale-driven PVC manufacturers and precision compounders serving automotive qualification requirements. Three archetypes dominate: integrated petrochemical majors with captive VCM supply, specialty chemical houses with REACH-compliant plasticizer portfolios, and regional compounders with distributor channel access. Capacity expansion and strategic partnerships constitute the primary competitive vectors as qualification timelines lengthen.
Within the integrated major tier, Formosa Plastics Corporation and Westlake Corporation exemplify geographic concentration around Gulf Coast and East Asian petrochemical infrastructure. Shin-Etsu Chemical Co., Ltd. occupies a distinct position among specialty resin architects, representing the convergence of silicone chemistry with thermoplastic processing requirements. These three anchors illustrate how supply-side configuration maps onto customer access: commodity scale versus formulation partnership versus materials science specialization.
| Leading Market Players |
|---|
| Formosa Plastics Corporation |
| Westlake Corporation |
| Eastman Chemical Company |
| Occidental Petroleum Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| SABIC |
| LG Chem |
| Reliance Industries Limited |
| Covestro AG |
| Others |
Cost & Logistics Intelligence
Multi-layer co-extrusion calendering is compressing unit economics while concentrating supply among integrated petrochemical majors with captive vinyl chloride monomer capacity. This production-method transition simultaneously elevates capital barriers for new entrants and tightens margin control for Formosa Plastics and Westlake Corporation across North American and East Asian markets.
Pricing Analysis
Short lead-time premiums of 15-20% apply to REACH-compliant formulations qualifying for German automotive Tier 1 programs, while spot inventory of standard PVC grades trades at discounts to contract offtake. Contract-based long-term offtake dominates volume transactions, with price differentiation driven by certification tier (ECHA REACH authorization status) and geographic delivery cost from Yangtze River Delta or Gulf Coast production hubs. Cost compression in commodity polyethylene packaging films is intensifying because thinner-gauge blown film alternatives displace calendered products in Asian export markets. Flooring manufacturers in Italy demonstrate highest price sensitivity due to margin pressure from phthalate reformulation investments, while automotive OEMs in Germany show lowest sensitivity given qualification lock-in effects.
Supply Chain Analysis
Vinyl chloride monomer supply rests on integrated petrochemical complexes concentrated in China, the United States, and Taiwan. Feedstock dependencies include ethylene from steam crackers, chlorine from chlor-alkali operations, and specialty plasticizers from adipic acid or trimellitic anhydride producers. Single-source vulnerability characterizes Gulf Coast production exposure to hurricane disruption risk across Texas and Louisiana corridors. Distribution runs through direct sales channels for automotive and flooring accounts, with regional distributors capturing fragmented building materials demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH substance restrictions on phthalate plasticizers create a barrier-to-entry moat for suppliers with pre-qualified bio-based formulation portfolios.
For Market Incumbents: Anticipate margin compression from emerging Chinese integrated producers by deepening captive VCM supply control and accelerating REACH-compliant plasticizer qualification ahead of ECHA authorization deadlines. Prioritize formulation co-development partnerships with Volkswagen and BMW preferred supplier programs to lock in automotive specification lock-in. Defend against silicone-modified resin substitution by Shin-Etsu Chemical through R&D investment in TPE-silicone hybrid architectures.
For New Entrants and Emerging Players: Silicone-modified resin chemistry offers a technology-first wedge into premium automotive interior segments where soft-touch durability commands specification premiums. Target underpenetrated medical packaging in India where CDSCO sterilization standard tightening creates demand for high-clarity calendered films meeting USP Class VI requirements. Pursue joint venture structures with Yangtze River Delta VCM producers to secure feedstock access without integrated capital requirements.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty compounders possessing REACH-compliant plasticizer portfolios given ECHA candidate list expansion catalysts accelerating market consolidation. Long-term viability favors acquisition targets with demonstrated automotive qualification timelines and direct Tier 1 relationships bypassing distributor intermediaries. Monitor Italian flooring manufacturer bankruptcy filings as inflection indicator for reformulation cost distress creating distressed asset opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCM | Captive vinyl chloride monomer supply insulates margin control from ethylene price volatility. |
| REACH-Compliant Formulation Investment | Bio-based plasticizer qualification ahead of ECHA deadlines secures German automotive access. |
| Multi-Layer Co-Extrusion Capacity Expansion | Single-pass laminate capability opens BMW and Mercedes-Benz dashboard skin specifications. |
| Direct Tier 1 Partnership Programs | Volkswagen preferred supplier status bypasses compounder networks and captures formulation co-development value. |
| Medical Packaging Grade Qualification | USP Class VI certification unlocks CDSCO-regulated Indian pharmaceutical packaging demand. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with resin plant managers, automotive Tier 1 procurement leads, flooring manufacturer technical directors, and distribution channel partners combined with secondary validation from ECHA authorization databases, SEC 10-K disclosures, and Cefic industry statistics. Bottom-up capacity and consumption modeling triangulated against top-down macroeconomic drivers.
Granularity-level framing applied country-specific production capacity modeling, grade-tier segmentation across flexible and rigid PVC formulations, and end-use industry splits between building materials and automotive applications. CAGRs derived from trend extrapolation of historical consumption patterns adjusted for regulatory phase-out timelines and automotive lightweighting adoption curves across the projection horizon. Industry-specific inputs included vinyl chloride monomer operating rate assumptions and REACH authorization deadline schedules.
Several conditions sit outside the modeled scope, including force majeure disruptions to Gulf Coast petrochemical infrastructure and unanticipated ECHA substance restriction accelerations. Forecasts reflect documented assumptions about automotive production trajectories and construction sector demand elasticity. A small set of named triggers warrants ongoing watch: hurricane season severity indices, ECHA candidate list update timing, and Chinese domestic calendering capacity utilization rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
Polyethylene Wax Market
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Resin Glue Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
Polycide Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Microcellular Plastics Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Global Nylon Market
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Global UV Curable Resins Market