
 Bio-Based and Synthetic Polyamide Market | 2026-2036
Bio-Based and Synthetic Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based and Synthetic Polyamide Market Analysis
The gap between certified bio-based polyamide and commodity synthetic grades is expanding. Arkema leverages its castor-derivative PA 11 portfolio to command specialty margins in medical tubing and fuel lines. DSM-Firmenich anchors European supply through fermentation-derived long-chain polyamides with ISCC PLUS certification. BASF SE competes at scale with fossil-based PA 6 and PA 66, extending backward integration into cyclohexane and adipic acid.
Bio-based and synthetic polyamides are thermoplastic polymers built from amide-linked repeating units, with bio-based variants deriving monomers from renewable feedstocks such as castor oil and synthetic variants from petrochemical benzene or butadiene precursors. These materials deliver fatigue resistance, chemical stability, and thermal performance for load-bearing components, electrical housings, and fiber applications. PA 6 dominates volume through its cost-efficient caprolactam ring-opening polymerization and broad automotive adoption. PA 11 leads margin capture in offshore and medical segments where oil-derived alternatives face substitution pressure. Application demand through automotive components outpaces textiles, as under-hood thermal management requirements tighten.
REACH registration in Europe mandates full substance dossiers for adipic acid and caprolactam imports, raising compliance costs for non-European producers. EPA toxicity assessments and state-level extended producer responsibility laws in California and New York are pushing U.S. compounders toward bio-content disclosure. Stakeholders must decide whether to build captive renewable feedstock capacity or secure offtake agreements before certification bottlenecks harden into structural supply constraints.
Market Dynamics
Automotive OEM carbon neutrality pledges are compressing the certification timeline for renewable feedstock polyamides, forcing compounders to choose between captive biorefinery investment and multi-year offtake contracting before ISCC PLUS bottlenecks harden.
Growth Catalysts
- EU Green Deal compliance pressure:German and Japanese automakers are accelerating procurement of bio-based PA grades to meet fleet emissions targets and Scope 3 reduction mandates.
- East Asian polymer cluster concentration:Integrated caprolactam-to-PA 6 operations in China and South Korea anchor regional supply security and attract downstream compounding investment.
- Offshore energy infrastructure renewal:Oil-derived PA alternatives face substitution pressure in subsea cable sheathing and riser applications, opening margin capture for long-chain bio-based grades.
Market Restraints
- Castor oil supply concentration:Over 90% of global castor bean cultivation sits in India, creating single-origin risk for PA 11 and PA 1010 monomer supply.
- REACH registration burden:Full substance dossiers for adipic acid and caprolactam imports raise compliance costs for non-European producers seeking European market access.
- Fossil-based PA 66 cost floor:Benzene-adipic acid economics maintain a persistent price advantage in commodity automotive and textile applications.
Strategic Opportunities
- Medical tubing certification gap:USP Class VI and ISO 10993 compliant bio-based PA 11 remains undersupplied relative to growing demand from single-use device manufacturers.
- Fermentation-derived long-chain polyamides:DSM-Firmenich's biotechnology platform demonstrates scalable pathways to C10-C12 lactam precursors without castor dependency.
- California extended producer responsibility:State-level bio-content disclosure mandates are pushing compounders toward certified renewable grades ahead of federal standardization.
Industry Challenges
- ISCC PLUS audit backlog:Certification body capacity constraints are extending mass-balance validation timelines from months to over a year, freezing procurement decisions.
- Polymerization equipment retrofit costs:Transitioning from fossil-based to bio-based feedstocks requires reactor cleaning protocols and catalyst system modifications that idle production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based and Synthetic Polyamide Market |
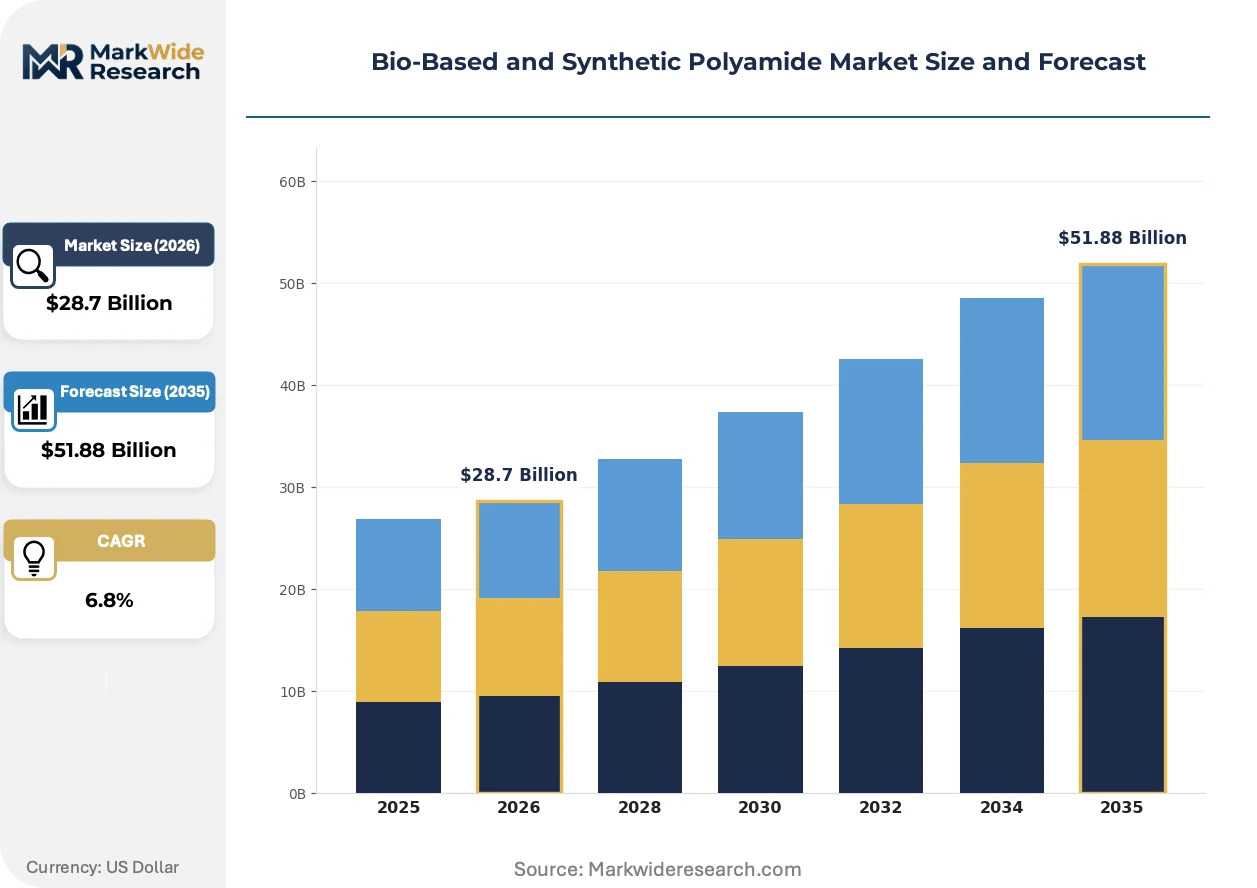
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 11, PA 12 Application: Automotive Components, Electrical Insulation, Textiles, Consumer Goods End User: Aerospace, Automotive OEMs, Electronics, Packaging Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | Arkema, DSM-Firmenich, BASF SE, Evonik Industries, Solvay, LANXESS, Cathay Biotech, Ascend Performance Materials, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based and Synthetic Polyamide Market Emerging Trajectories
Biotechnology platforms are displacing traditional petrochemical routes to polyamide monomers, while regulatory frameworks on both sides of the Atlantic harden carbon accounting requirements for material procurement.
Enzymatic catalysis for lactam ring-opening is converging with continuous polymerization reactor designs to reduce energy intensity in PA 6 production. European fiber producers are piloting these integrated systems at demonstration scale. The technology is converging with mechanical recycling streams to enable closed-loop nylon regeneration without virgin caprolactam input.
REACH registration mandates full substance dossiers for adipic acid and caprolactam imports into Europe, raising compliance costs for non-European producers. The regulation forces compounders to document supply chain carbon intensity or face market exclusion. Automotive tier suppliers in Germany and France are responding by demanding ISCC PLUS certification from all resin vendors.
Buyer concentration among automotive OEMs is compressing compounder margins through multi-year framework agreements with fixed renewable content minimums. Direct procurement relationships between Volkswagen, Toyota, and certified resin producers are displacing traditional distributor channels for high-volume grades. This pattern is most visible in Germany and Japan, where OEM sustainability targets outpace domestic bio-based production capacity.
Bio-Based and Synthetic Polyamide Market Segmentation
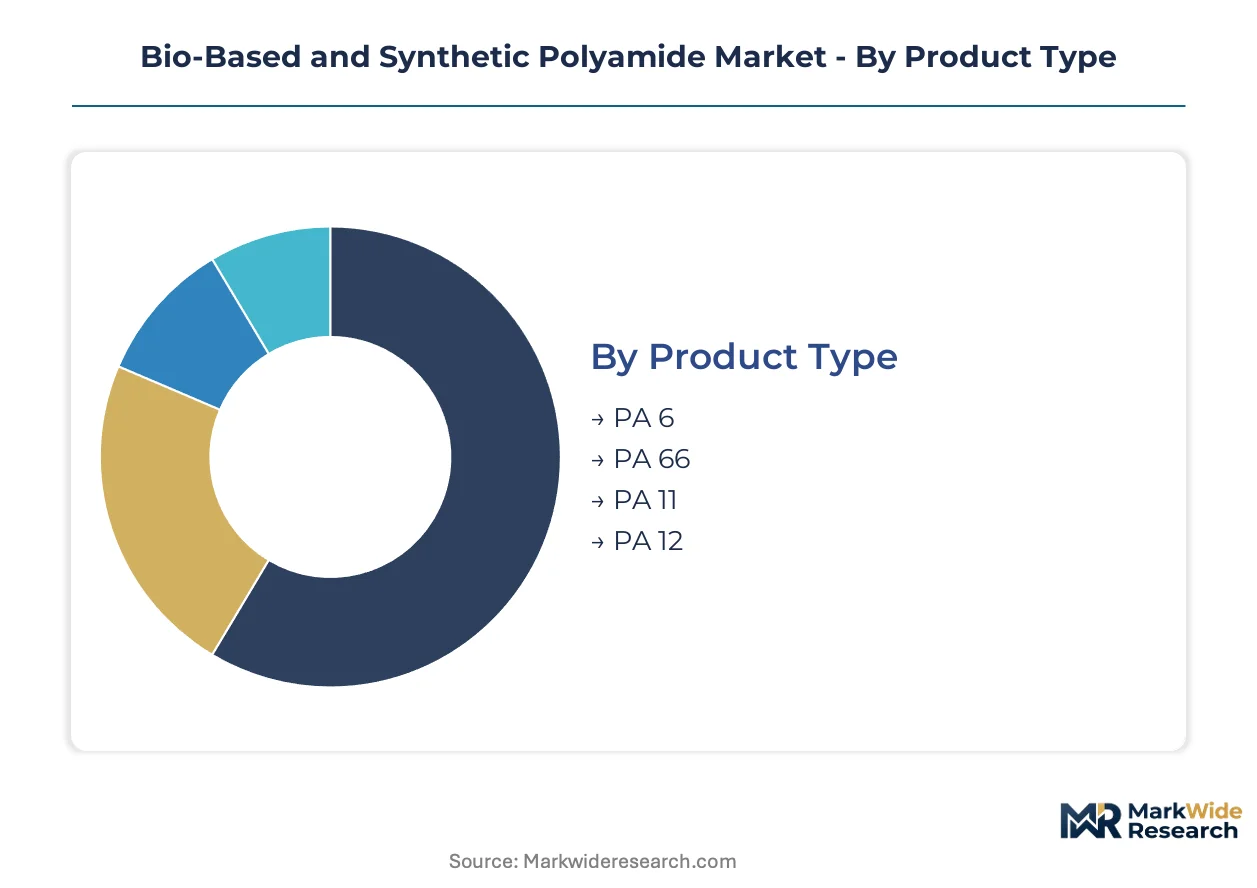
Segmentation in the polyamide market reveals divergent margin structures across fossil-derived commodity grades and certified bio-based specialties. Procurement patterns differ sharply between automotive OEMs seeking carbon-accounted resins and textile producers optimizing for unit economics.
Product Type:
Customization intensity varies from standardized bulk polymerization to precision-engineered biopolymer grades with traceable feedstock provenance.
- PA 6:Caprolactam ring-opening polymerization yields the most cost-efficient engineering thermoplastic for under-hood automotive components. Demand concentrates in East Asian polymer clusters where integrated caprolactam-to-PA 6 operations anchor regional supply security for German and Japanese automakers.
- PA 66:Adipic acid-hexamethylenediamine condensation creates high-melting-point resins ideal for thermal management applications. Benzene-adipic acid economics maintain persistent cost advantages in commodity automotive segments despite EU Green Deal compliance pressure.
- PA 11:Castor oil-derived C11 amino acid monomers deliver oil-resistant performance for subsea cable sheathing and medical tubing with USP Class VI certification.
- PA 12:Laurolactam-based long-chain polyamide offers moisture resistance and dimensional stability for pneumatic brake lines and fuel systems.
Most installed capacity flows through PA 6. Expansion is steepest in PA 11 as offshore infrastructure renewal and medical device certification gaps open margin capture opportunities.
Application:
Cost tier separation runs from premium-certified bio-based grades in regulated end-uses to economy fossil-based volumes in undifferentiated fiber markets.
- Automotive Components:Engine covers, intake manifolds, and cooling system housings demand heat-deflection temperatures above 180°C. German automakers now mandate ISCC PLUS certification from resin vendors to meet Scope 3 reduction targets.
- Electrical Insulation:Switchgear housings and connector bodies require UL 94 V-0 flame retardancy combined with tracking resistance. REACH registration mandates for adipic acid imports raise compliance costs for non-European compounders serving this segment.
- Textiles:Carpet fiber and industrial yarn applications prioritize caprolactam cost efficiency over bio-content disclosure.
- Consumer Goods:Sporting equipment and power tool housings balance impact strength with surface finish quality.
Automotive Components commands the largest volume share. Electrical Insulation is climbing the fastest as grid infrastructure investment and electric vehicle charging hardware multiply specification requirements.
End User:
Customer type determines certification burden intensity, with regulated industries imposing mass-balance documentation that commodity buyers bypass.
- Aerospace:FAA-compliant interior panels and ducting require flame-smoke-toxicity certification to FAR 25.853 standards. PA 12 dominates ducting applications for moisture-insensitive performance at altitude.
- Automotive OEMs:Volkswagen and Toyota direct procurement relationships are displacing traditional distributor channels for high-volume certified grades.
- Electronics:Connector and relay housings demand tight dimensional tolerances and surface-mount compatibility.
- Packaging:Barrier films and mono-material structures seek PA 6 oxygen barrier layers for food contact applications.
Automotive OEMs absorb the majority of certified bio-based volume. Aerospace is gaining share fastest as Boeing and Airbus sustainability targets harden material procurement specifications.
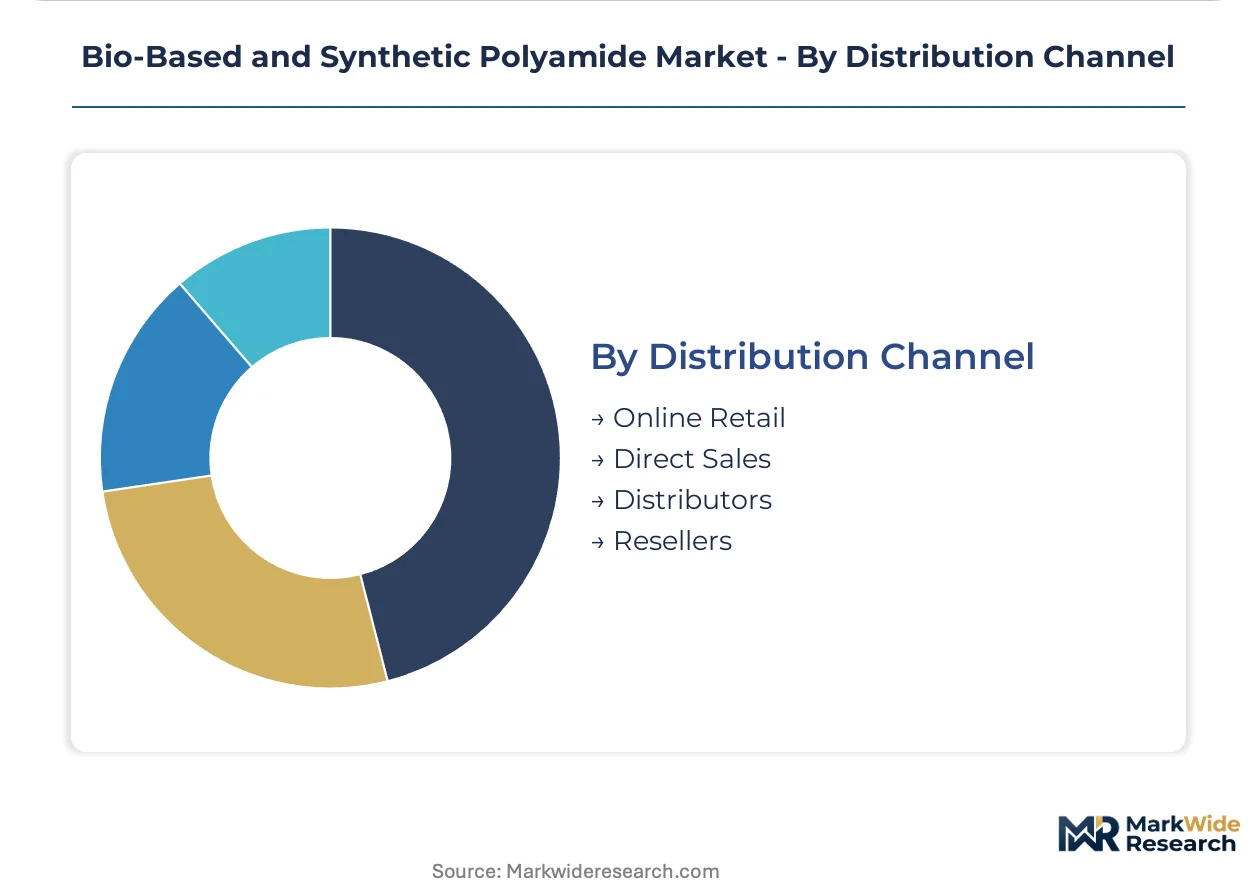
Distribution Channel:
Supply concentration shapes channel selection, with certified grades requiring traceability systems that only direct and distributor channels reliably provide.
- Direct Sales:Framework agreements with fixed renewable content minimums lock in multi-year supply relationships between resin producers and automotive tier suppliers.
- Distributors:Regional stocking locations offer technical support and just-in-time delivery for mid-volume processors lacking storage infrastructure.
- Online Retail:E-procurement platforms serve small-lot R&D sampling and 3D printing filament markets with rapid fulfillment.
- Resellers:Secondary market participants arbitrage spot availability for commodity PA 6 and PA 66 grades during supply disruptions.
Direct Sales channels handle the majority of certified bio-based volume. Online Retail is expanding most quickly as distributed manufacturing and rapid prototyping multiply small-lot demand patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer engineering talent clusters in Germany's Rhine-Ruhr corridor and Japan's Nagoya-Toyohashi belt anchor the industry's technical workforce. These concentrations feed directly into automotive OEM supply chains demanding certified bio-based grades. Migration of formulation expertise toward East Asian manufacturing hubs is redistributing regional capability.
Germany
Volkswagen and BMW procurement teams mandate ISCC PLUS certification from all resin vendors under Scope 3 reduction targets. The KBA enforces fleet emissions compliance that cascades into material specifications. The Rhine-Ruhr corridor hosts BASF SE's Ludwigshafen complex, where backward integration into cyclohexane and adipic acid secures captive supply for PA 66 production.
China
Integrated caprolactam-to-PA 6 operations in Ningbo and Shanghai attract downstream compounding investment from European and Japanese automakers. The MIIT's dual carbon goals pressure state-owned petrochemical groups to pilot bio-content disclosure systems. The Yangtze River Delta polymer cluster now supplies German OEMs with carbon-accounted grades through direct framework agreements.
United States
EPA toxicity assessments and California's extended producer responsibility laws push compounders toward bio-content disclosure ahead of federal standardization. The EPA maintains active review programs for adipic acid and caprolactam exposure limits. The Gulf Coast petrochemical corridor retains cost advantages in fossil-based PA 66, though automotive tier suppliers in Detroit increasingly specify certified renewable grades.
Japan
Toyota's direct procurement relationships with certified resin producers displace traditional distributor channels for high-volume grades. METI's carbon neutrality roadmap for the chemical sector accelerates fermentation-derived polyamide pilot programs. The Nagoya-Toyohashi engineering plastics belt concentrates compounding expertise serving domestic automotive and electronics end-uses.
India
Over 90% of global castor bean cultivation sits in Gujarat and Rajasthan, creating single-origin risk for PA 11 and PA 1010 monomer supply. The BIS maintains evolving standards for bio-based polymer content verification that lag EU certification rigor. The Gujarat chemical cluster hosts castor oil derivative processing that feeds European and Japanese specialty polyamide producers.
Bio-Based and Synthetic Polyamide Market Vendor Landscape
Top-tier vendors anchor the certified bio-based specialty segment, while diversified petrochemical incumbents dominate commodity PA 6 and PA 66 volume. The competitive structure stratifies across three archetypes: integrated petrochemical majors with backward control over benzene-adipic acid chains, biotechnology specialists leveraging fermentation platforms for long-chain lactams, and regional compounders serving automotive tier suppliers with formulation expertise. Dominant competitive moves include captive biorefinery investment to secure renewable feedstock supply and multi-year offtake contracting to lock in ISCC PLUS certification ahead of audit backlogs.
Within the biotechnology specialist tier, DSM-Firmenich and Cathay Biotech exemplify fermentation-derived pathways that reduce castor oil dependency. Arkema S.A. occupies a distinctive position through castor-derivative chemistry expertise. Among diversified petrochemical incumbents, BASF SE anchors European supply security through integrated adipic acid production, while Evonik Industries and LANXESS represent German-based engineering plastics portfolios with automotive certification depth. DuPont and Ascend Performance Materials sit within the North American competitive set, with Ascend's name signaling performance-grade positioning and DuPont's historical presence in nylon chemistry.
| Leading Market Players |
|---|
| Arkema |
| DSM-Firmenich |
| BASF SE |
| Evonik Industries |
| Solvay |
| LANXESS |
| Cathay Biotech |
| Ascend Performance Materials |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Backward integration into cyclohexane and adipic acid anchors BASF SE's pricing power in PA 66, while castor oil dependency constrains margin flexibility for bio-based PA 11 producers serving medical tubing and offshore cable markets.
Pricing Analysis
Certification-bundled pricing separates ISCC PLUS-validated grades from uncertified commodity resin. Three-tier pricing structure across premium, standard, and economy levels tracks feedstock provenance and automotive OEM compliance requirements. Cost compression in fossil-based PA 66 intensifies as benzene-adipic acid economics maintain persistent advantages. Textile producers exhibit highest price sensitivity, while German automakers accept premium positioning for Scope 3 carbon accounting.
Supply Chain Analysis
EU Green Deal domestic-content mandates reshape sourcing decisions for non-European compounders seeking German automotive market access. Raw material flows draw from Indian castor bean cultivation, Chinese caprolactam production, and Gulf Coast benzene refining. Single-origin vulnerability concentrates in Gujarat's castor oil processing, where over 90% of global PA 11 feedstock originates. Distribution runs through direct framework agreements locking multi-year offtake relationships between resin producers and automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as automotive OEM carbon neutrality pledges harden material procurement specifications across German and Japanese supply chains.
For Market Incumbents: Acquire fermentation-derived lactam technology platforms to reduce castor oil dependency. Secure ISCC PLUS certification capacity ahead of audit backlogs freezing procurement decisions. Build captive biorefinery assets in East Asian polymer clusters to anchor regional supply security for Volkswagen and Toyota direct sourcing relationships. For New Entrants and Emerging Players: Begin with medical tubing certification gaps where USP Class VI compliant PA 11 remains undersupplied relative to single-use device manufacturer demand. Target California extended producer responsibility compliance ahead of federal standardization. Pursue rapid-prototyping filament distribution through e-procurement platforms serving distributed manufacturing networks. For Investors and Strategic Acquirers: Roll-up economics work for regional compounders with formulation expertise because automotive OEM buyer concentration is displacing traditional distributor channels. Five-to-ten year viability hinges on biotechnology platform scalability displacing petrochemical routes. Watch ISCC PLUS certification body capacity expansion as the inflection signal for procurement decision unfreezing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive adipic acid production secures PA 66 supply security for German automotive OEMs under REACH compliance. |
| Biorefinery Capacity Buildout | Fermentation-derived C10-C12 lactam platforms reduce castor oil dependency for long-chain polyamide margins. |
| ISCC PLUS Certification Investment | Mass-balance validation unlocks direct procurement relationships with Volkswagen and Toyota sustainability programs. |
| Long-term Supply Agreement | Multi-year offtake contracting locks in renewable feedstock allocation before certification bottlenecks harden. |
| Joint Venture | East Asian polymer cluster partnerships anchor integrated caprolactam-to-PA 6 operations for regional supply security. |
Methodological Framework
Coverage spans Germany, China, Japan, and the United States, with primary inputs from each market's automotive procurement clusters. The research combines interviews with resin producer technical directors, automotive tier supplier procurement leads, and medical device manufacturer materials engineers alongside secondary validation through ECHA REACH registration databases, customs trade flows, and SEC chemical sector filings. Bottom-up capacity modeling triangulates against top-down OEM demand aggregation.
Granularity extends to product type, application end-use, and certification tier across the projection horizon. Segmentation dimensions include polymer grade, automotive component category, and regional regulatory cluster. CAGRs derive from production capacity expansion schedules mapped against OEM framework agreement volumes. Industry-specific forecast inputs incorporate caprolactam spot pricing volatility and castor oil harvest yield variation.
Several conditions sit outside the modeled scope, including geopolitical trade disruption scenarios and breakthrough biotechnology platform commercialization timelines. Forecasts reflect documented assumptions on certification body capacity expansion and automotive OEM sustainability target stringency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
Australia Engineering Plastics Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Organosilicon Polymers (Polysiloxane) Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Flexible Polymer Foam Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
Europe Polypropylene Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
APAC Polyethylene Terephthalate Market