
 Fluorine Polymer Films Market | 2026-2036
Fluorine Polymer Films Market Size, Share, and Industry Trends Forecast 2026-2036
Fluorine Polymer Films Market Intelligence
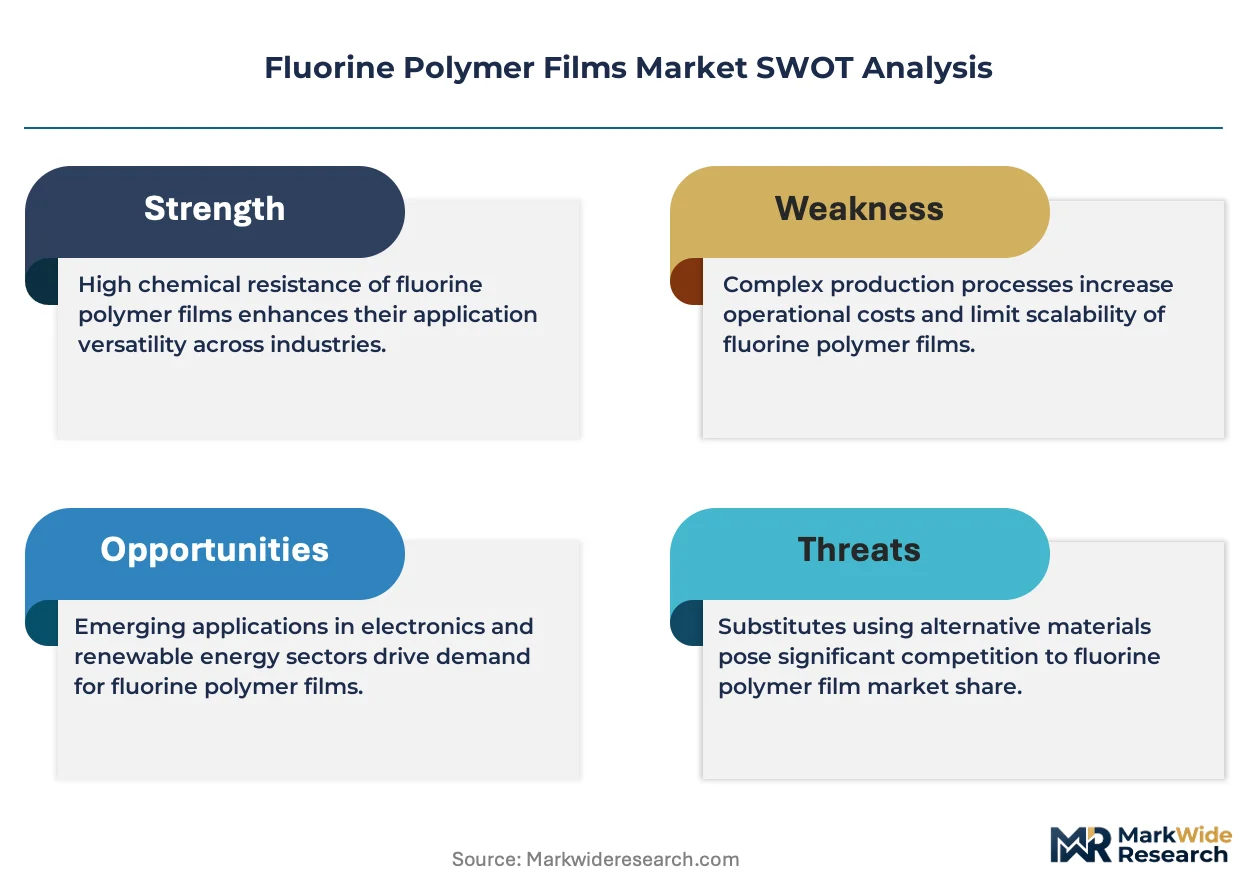
A divergence in capital investment for advanced film extrusion and calendaring capabilities is unwinding the market's competitive structure. Integrated producers like The Chemours Company leverage captive supply of raw fluoropolymers for cost advantages. In contrast, downstream specialists such as Saint-Gobain and Arkema differentiate through application-specific product development and engineering support for complex end-uses.
Fluorine polymer films are high-performance thermoplastic materials characterized by their exceptional chemical inertness and high-temperature resistance. Produced via processes like extrusion or casting, they serve as critical barriers and insulating layers in harsh environments. PTFE films dominate the market by volume for electrical insulation and chemical processing applications. PVDF and ETFE films represent the fastest-growing segments, driven by their specific utility in architectural and renewable energy sectors.
Market access and product specifications are influenced by a complex regulatory environment. The EU's REACH regulation and RoHS directive restrict certain substances, while the US FDA governs materials for medical devices. In China, compliance with GB standards is mandatory for market entry. Navigating the evolving landscape of PFAS regulations while meeting performance demands for new applications will define future market leadership.
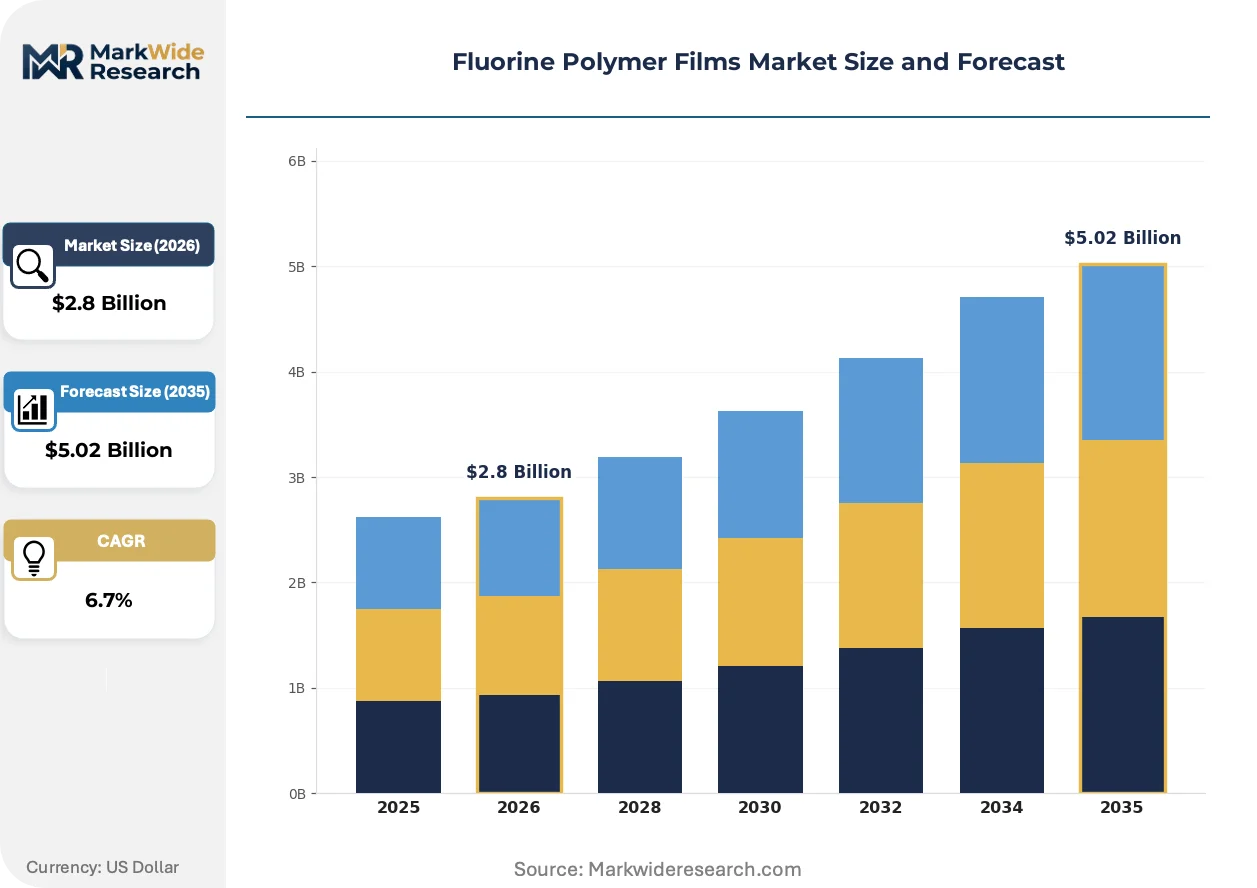
Market Dynamics
The central dynamic is the tension between escalating performance requirements from advanced industries and intensifying regulatory pressure on PFAS chemicals. This conflict, driven by actions from the US EPA and the EU's REACH framework, is forcing a re-evaluation of material selection across all end-use sectors.
Growth Catalysts
- Renewable Energy Expansion:Demand for ETFE films in photovoltaic module frontsheets and backsheets is driven by solar power installations, particularly under policies supporting renewable energy in China and Germany.
- Aerospace and Defense Modernization:The need for lightweight, high-temperature wire and cable insulation in next-generation aircraft and satellite systems creates consistent demand from the aerospace manufacturing clusters in the United States and France.
- Semiconductor Fabrication Growth:Ultra-high purity PFA and PTFE films are essential for fluid handling systems and wet bench equipment in semiconductor fabs, with demand concentrated in Taiwan and South Korea.
Market Restraints
- Raw Material Price Volatility:The market is sensitive to price fluctuations for key raw materials like fluorspar, with supply heavily dependent on mining operations and export policies in China.
- Intensifying Regulatory Scrutiny:Broad-based restrictions on PFAS chemicals, proposed under the EU's REACH regulation, create significant market uncertainty and potential obsolescence risk for established film grades.
- Threat from Alternative Polymers:In applications with less extreme temperature or chemical exposure, high-performance polymers like polyimides and PEEK present a viable substitution threat, limiting fluoropolymer film use.
Strategic Opportunities
- Medical Device Innovation:The development of ultra-thin, lubricious PTFE films creates opportunities in minimally invasive surgical devices, such as catheter liners and guidewire coatings, meeting FDA material standards.
- Green Hydrogen Infrastructure:Chemically inert PVDF and FEP films are positioned for use as membranes and liners in electrolyzers and fuel cells, aligning with green hydrogen initiatives in Germany and Japan.
- Advanced Architectural Designs:ETFE films enable lightweight, transparent building envelopes for stadiums and atriums, with significant project potential in large-scale construction in the UAE and Saudi Arabia.
Industry Challenges
- High Capital Investment:The specialized extrusion and calendaring equipment required for producing high-quality fluoropolymer films represents a significant capital barrier to entry and capacity expansion for manufacturers.
- Navigating Divergent Global Standards:Film producers face complexity and cost in certifying products to meet disparate regional requirements, such as China's GB standards, Europe's RoHS directive, and US FDA regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorine Polymer Films Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE Films, FEP Films, PFA Films, ETFE Films, PVDF Films Application: Electrical Insulation, Chemical Processing, Aerospace Components, Packaging Films, Medical Devices End User Industry: Electronics Manufacturers, Chemical Plants, Aerospace Engineers, Packaging Firms, Medical Equipment Suppliers Manufacturing Technology: Extrusion, Calendaring, Casting, Lamination, Sintering |
| Companies Covered | The Chemours Company, Daikin Industries Ltd., 3M Company, Saint-Gobain, Arkema, AGC Inc., Solvay, Dunmore, Rogers Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorine Polymer Films Market Strategic Shifts & Innovations
Innovation in the fluorine polymer films market is defined by a dual pursuit of enhanced functional properties and compliance with a rapidly evolving global regulatory environment. This drives development toward materials that solve specific application challenges while navigating environmental and health-related restrictions.
Surface-modified films provide enhanced functionalities like improved adhesion or controlled wettability. Electronics and medical device manufacturers are the primary adopters of these advanced materials for specialized components. This development is bifurcating the market, creating a distinct, high-value segment for functionalized films separate from the commodity-like standard grades.
The European Union's proposed universal restriction on PFAS chemicals under REACH is a significant regulatory development. This action compels industries like automotive and chemical processing to audit their material dependencies and actively seek out compliant alternatives or apply for critical use exemptions. The German industrial sector, a major consumer, is at the forefront of this material requalification effort.
A focus on total cost of ownership is altering procurement patterns away from simple price-per-unit metrics. Buyers in critical industries such as aerospace and chemical processing now prioritize long-term reliability and reduced downtime, favoring films with documented durability over lower-cost options. This behavioral shift is most pronounced in North American and European industrial maintenance and repair operations.
Fluorine Polymer Films Market Segmentation
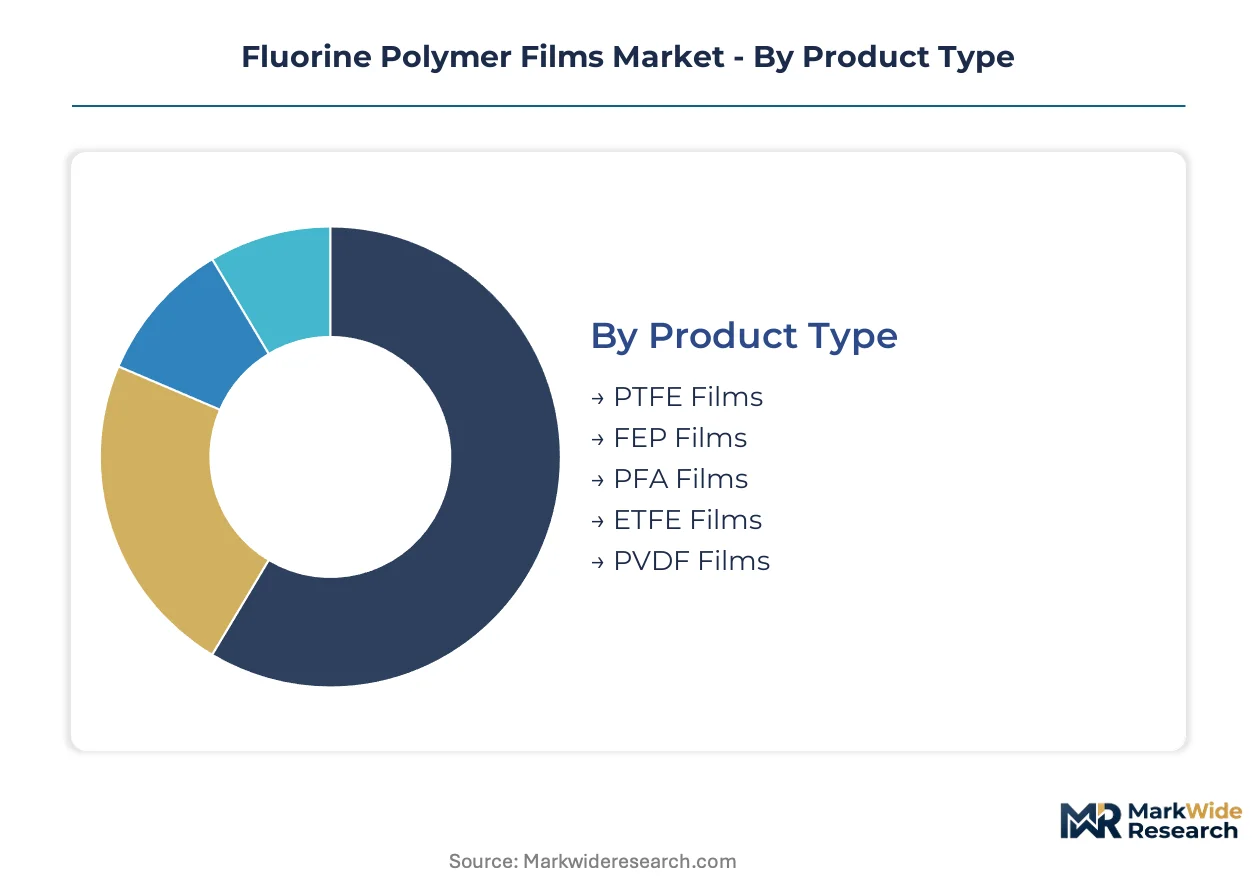
Understanding the Fluorine Polymer Films market through segmentation reveals distinct value propositions and competitive battlegrounds. Each product type, application, end-user industry, and manufacturing technology serves specific niches, influenced by performance demands and regulatory landscapes.
Product Type:
The geographic spread of manufacturing capabilities significantly influences product type availability and trade flows for fluorine polymer films.
- PTFE Films:These films offer exceptional chemical inertness and high-temperature resistance, often used for electrical insulation and chemical processing. Demand concentrates in industrial manufacturing hubs like Germany and China, where robust chemical and electronics sectors exist.
- ETFE Films:Known for transparency, durability, and lightweight properties, ETFE films are critical for architectural applications and photovoltaic module frontsheets. Their expansion is driven by renewable energy policies in China and Germany, alongside large-scale construction projects in the UAE.
- FEP Films:FEP films provide excellent non-stick properties and chemical resistance, commonly employed in wire insulation and lining applications.
- PFA Films:PFA films are used in ultra-high purity applications such as semiconductor fluid handling systems, with demand centered in Taiwan and South Korea.
- PVDF Films:PVDF films offer good weatherability and chemical resistance, finding utility in green hydrogen infrastructure and architectural coatings.
PTFE Films holds the largest share; momentum sits with ETFE Films.
Application:
The complexity of application requirements dictates the performance specifications and material selection for fluorine polymer films.
- Aerospace Components:These applications demand lightweight, high-temperature wire and cable insulation for next-generation aircraft and satellite systems. Procurement is concentrated in aerospace manufacturing clusters within the United States and France.
- Medical Devices:This segment requires ultra-thin, lubricious PTFE films for minimally invasive surgical tools like catheter liners and guidewire coatings. Compliance with US FDA material standards is paramount for market access.
- Electrical Insulation:Fluorine polymer films provide critical dielectric strength and thermal stability for wire and cable insulation, especially in harsh environments.
- Chemical Processing:Films serve as corrosion-resistant liners and barriers in tanks, pipes, and gaskets within chemical plants.
- Packaging Films:Specialized fluoropolymer films offer barrier properties for demanding packaging applications, protecting sensitive contents.
High-performance applications like Aerospace Components command premium pricing, while Electrical Insulation drives significant volume.
End User Industry:
Regulatory intensity within specific end-user industries significantly shapes material selection and compliance requirements for fluorine polymer films.
- Electronics Manufacturers:This industry requires ultra-high purity PFA and PTFE films for fluid handling systems and wet bench equipment in semiconductor fabrication. Demand is concentrated among manufacturers in Taiwan and South Korea.
- Medical Equipment Suppliers:These suppliers utilize advanced fluoropolymer films for biocompatible and lubricious components in devices like catheters and guidewires. Strict adherence to US FDA regulations is mandatory for product acceptance.
- Chemical Plants:These facilities rely on fluorine polymer films for their exceptional chemical inertness in corrosive environments.
- Aerospace Engineers:This sector integrates fluoropolymer films for lightweight, high-temperature resistant insulation in aircraft and satellite systems.
- Packaging Firms:These firms use specialized films for high-barrier packaging solutions in demanding environments.
Electronics Manufacturers represents a mature consumption base, with Medical Equipment Suppliers showing the most dynamic procurement shifts.
Manufacturing Technology:
The capital intensity and technical expertise required for different manufacturing technologies define the competitive landscape for fluorine polymer films.
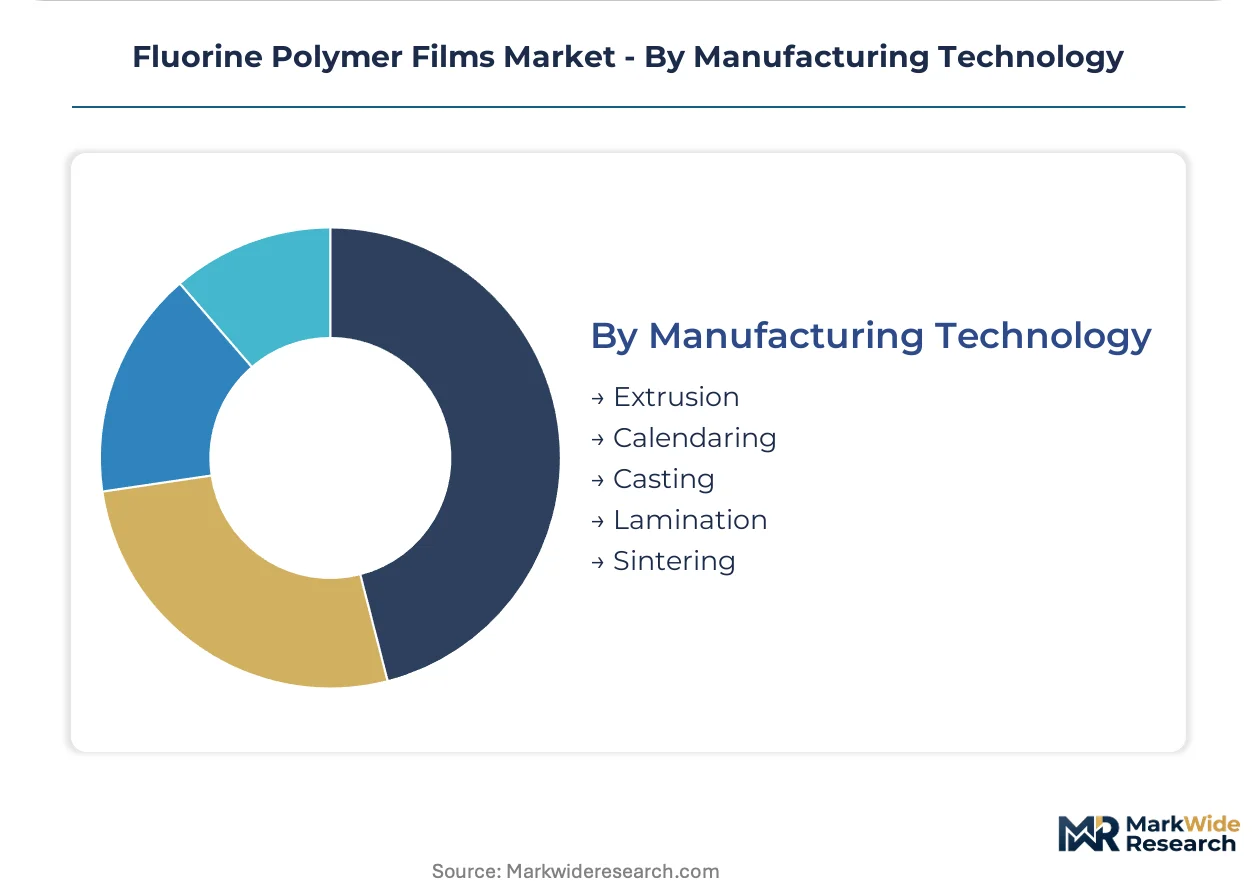
- Extrusion:This process involves melting and forcing fluoropolymer resin through a die to create continuous films, offering versatility for various thicknesses and widths. It represents a foundational technology for high-volume production.
- Calendaring:This technology uses a series of heated rollers to press and shape molten fluoropolymer into films, enabling precise thickness control and surface finishes. It is critical for producing specialized, high-performance films.
- Casting:Casting involves applying a liquid fluoropolymer solution onto a substrate, followed by solvent evaporation, producing very thin films.
- Lamination:Lamination combines multiple film layers or films with other materials to create composite structures with enhanced properties.
- Sintering:This process involves heating compacted fluoropolymer powder below its melting point to form a solid, porous film structure.
Extrusion processes are foundational for volume, with Calendaring offering specialized capabilities for advanced film structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for fluorine polymer films varies significantly across regions, with specialized applications in aerospace and medical devices exhibiting lower price sensitivity compared to high-volume electrical insulation needs. Performance requirements dictate material selection, often overriding cost considerations in critical sectors. This global market sees distinct regional concentrations of both demand and regulatory influence.
United States
Aerospace and defense modernization in the United States creates consistent demand for lightweight, high-temperature wire and cable insulation. The US FDA governs material standards for medical devices, influencing ultra-thin PTFE film adoption. Aerospace manufacturing clusters across the nation remain significant procurement hubs.
China
Renewable energy expansion drives demand for ETFE films in photovoltaic modules, supported by China's national policies for solar power. Compliance with GB standards is mandatory for market entry, shaping product specifications. Industrial manufacturing hubs within China represent a significant consumption base.
Germany
Green hydrogen initiatives in Germany position PVDF and FEP films for use in electrolyzers and fuel cells. The EU's REACH regulation intensifies scrutiny on PFAS chemicals, forcing material re-evaluation. The German industrial sector, a major consumer, leads the requalification effort for compliant film grades.
Taiwan
Semiconductor fabrication growth in Taiwan requires ultra-high purity PFA and PTFE films for fluid handling systems. The region's stringent quality controls and industry standards influence film specifications for critical applications. Demand for these specialized materials is concentrated among Taiwan's leading semiconductor manufacturers.
United Arab Emirates
Advanced architectural designs in the United Arab Emirates enable lightweight, transparent building envelopes using ETFE films. Local sustainability initiatives and ambitious urban development plans support the adoption of these innovative materials. Significant project potential exists in large-scale construction within cities like Dubai and Abu Dhabi.
Fluorine Polymer Films Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure within the fluorine polymer films market. Integrated producers leverage captive supply of raw fluoropolymers to achieve cost advantages in high-volume segments. Downstream specialists, conversely, differentiate through application-specific product development and engineering support for complex end-uses. Strategic partnerships for material innovation and capacity expansion initiatives are common competitive moves.
Within the integrated producer archetype, The Chemours Company exemplifies the strategy of leveraging upstream control over raw fluoropolymers for cost advantages, particularly in foundational film grades. Conversely, Saint-Gobain and Arkema represent downstream specialists, emphasizing application-specific product development and comprehensive engineering support for complex end-uses. These firms occupy distinct positions, with some focusing on high-volume standard grades and others on high-performance, customized film solutions for demanding industries like aerospace and medical devices. This differentiation allows for varied competitive strategies across the market spectrum.
| Leading Market Players |
|---|
| The Chemours Company |
| Daikin Industries Ltd. |
| 3M Company |
| Saint-Gobain |
| Arkema |
| AGC Inc. |
| Solvay |
| Dunmore |
| Rogers Corporation |
| Others |
Cost & Logistics Intelligence
The EU's REACH regulation gates both supply qualification and price differentiation for fluorine polymer films. This framework mandates material re-evaluation, impacting market access and premiumization for compliant products.
Pricing Analysis
Long-term reliability and reduced downtime drive lifetime value for fluorine polymer films. Pricing often follows a value-based model, particularly for specialized applications like medical devices and aerospace components, with differentiation stemming from film quality grade, specific regulatory certifications such as US FDA approval, and customization. Raw material price volatility from fluorspar and alternative polymers create pricing pressure in standard grades. Aerospace components and medical device manufacturers exhibit lower price sensitivity than high-volume electrical insulation buyers.
Supply Chain Analysis
China's export policies for fluorspar represent a critical chokepoint for the fluorine polymer films supply chain. This market primarily sources key raw materials like fluorspar and various fluoropolymers from concentrated mining operations, with specialized film production centered in industrial hubs within China, Germany, Taiwan, and South Korea. Raw material price volatility and intensifying PFAS regulatory scrutiny pose significant structural risks. Distribution typically runs through direct sales channels to large industrial manufacturers and specialized technical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fluorine polymer films market is at a platform-economics inflection, driven by the expanding renewable energy ecosystem. Interoperability with next-generation solar technologies and green hydrogen infrastructure is reshaping value creation.
For Market Incumbents: Compound investments in specialized film extrusion and calendaring capabilities to protect market share against emerging alternative polymers. The Chemours Company should deepen captive supply of raw fluoropolymers to maintain cost advantages in foundational grades. Investing in advanced R&D for PFAS-compliant materials mitigates regulatory threat from the EU's REACH framework. Pursue strategic partnerships for material innovation in high-performance applications like aerospace components.
For New Entrants and Emerging Players: Application-specific engineering support represents a service-layer gap where incumbents under-serve the market. New entrants should target niche, high-value segments like medical device innovation or green hydrogen infrastructure, which demand tailored solutions. Focus on developing ultra-thin, lubricious PTFE films for minimally invasive surgical devices, leveraging FDA material standards as a market entry barrier. A go-to-market strategy emphasizing rapid prototyping and collaborative product development with end-users can accelerate adoption.
For Investors and Strategic Acquirers: The proposed universal restriction on PFAS chemicals under EU REACH reshapes the acquisition landscape for fluorine polymer films. Long-term viability over the next decade hinges on developing compliant material portfolios or securing critical use exemptions. Target acquisition archetypes include downstream specialists with strong intellectual property in surface-modified films or established market access in green hydrogen and medical device sectors. The signal to watch is the final scope and implementation timeline of global PFAS regulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Manufacturing Transition | Develop PFAS-free or low-PFAS film grades to meet evolving global environmental regulations. |
| Capacity Expansion | Increase production of ETFE films for renewable energy projects in China and Germany. |
| Long-term Supply Agreement | Secure stable access to fluorspar and other raw fluoropolymers from key mining regions. |
| Product Launch | Introduce surface-modified films for enhanced adhesion in advanced electronics and medical devices. |
| Joint Venture | Partner with medical device manufacturers to co-develop ultra-thin PTFE films for new applications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews. These discussions involved R&D directors, procurement leads, plant managers, and regulatory compliance officers across key industries. Secondary validation drew from customs data, industry association reports, and company financial filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
The market forecast spans the entire analysis window, employing a robust analytical framework. Segmentation dimensions included product type, application, end-user industry, and manufacturing technology, alongside regional regulatory landscapes. Compound annual growth rates were derived from historical trends and projected demand. Key forecast inputs included renewable energy installation rates and semiconductor fabrication capacity expansions.
Forecasts assume regulatory continuity in EU REACH and US EPA frameworks; material policy shifts would require re-modeling. Raw material supply disruptions or accelerated PFAS restrictions are significant risk factors. Practitioners should keep alternative scenarios live as global environmental and trade policies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Vinyl Acetate Homopolymer Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Global Polyurethane Dispersions Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Polysulfide Market