
 Global Polyphthalamide Market | 2026-2036
Global Polyphthalamide Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyphthalamide Market Foresight
Automotive electrical systems is recalibrating polyphthalamide consumption patterns as vehicle assemblers replace metal housings with thermally stable polymers. Evonik Industries AG leverages its specialty polymers portfolio to dominate high-temperature connector grades across European automotive supply chains. SABIC anchors its position through backward integration into petrochemical feedstocks that stabilize copolymer cost structures. BASF SE differentiates via R&D intensity in glass-filled modified grades tailored to electric motor insulation requirements.
Polyphthalamide is a semi-aromatic polyamide synthesized from terephthalic acid and aliphatic diamines, delivering continuous service temperatures exceeding 150°C alongside resistance to automotive fluids and soldering processes. Its primary industrial purpose centers on metal replacement in thermally and chemically aggressive environments where standard nylons degrade. Copolymer formulations lead volume consumption due to balanced processability and cost positioning across injection molding operations. High-performance grades capture concentrated margin pools in electrical connectors where UL flame ratings and dimensional stability command specification premiums. Modified grades sustain growth in industrial machinery components as fabricators seek alternatives to thermosets for complex geometries.
REACH in Europe, RoHS directives, and China's GB standards collectively restrict halogenated flame retardants and heavy metal content in electrical applications, forcing compounders to reformulate additive packages. The EPA and NHTSA in the United States impose overlapping emissions and safety standards that elevate material traceability requirements across automotive supply chains. EMA's evolving medical device regulations create adjacent specification pathways for biocompatible high-performance grades. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory in cross-border component trade.
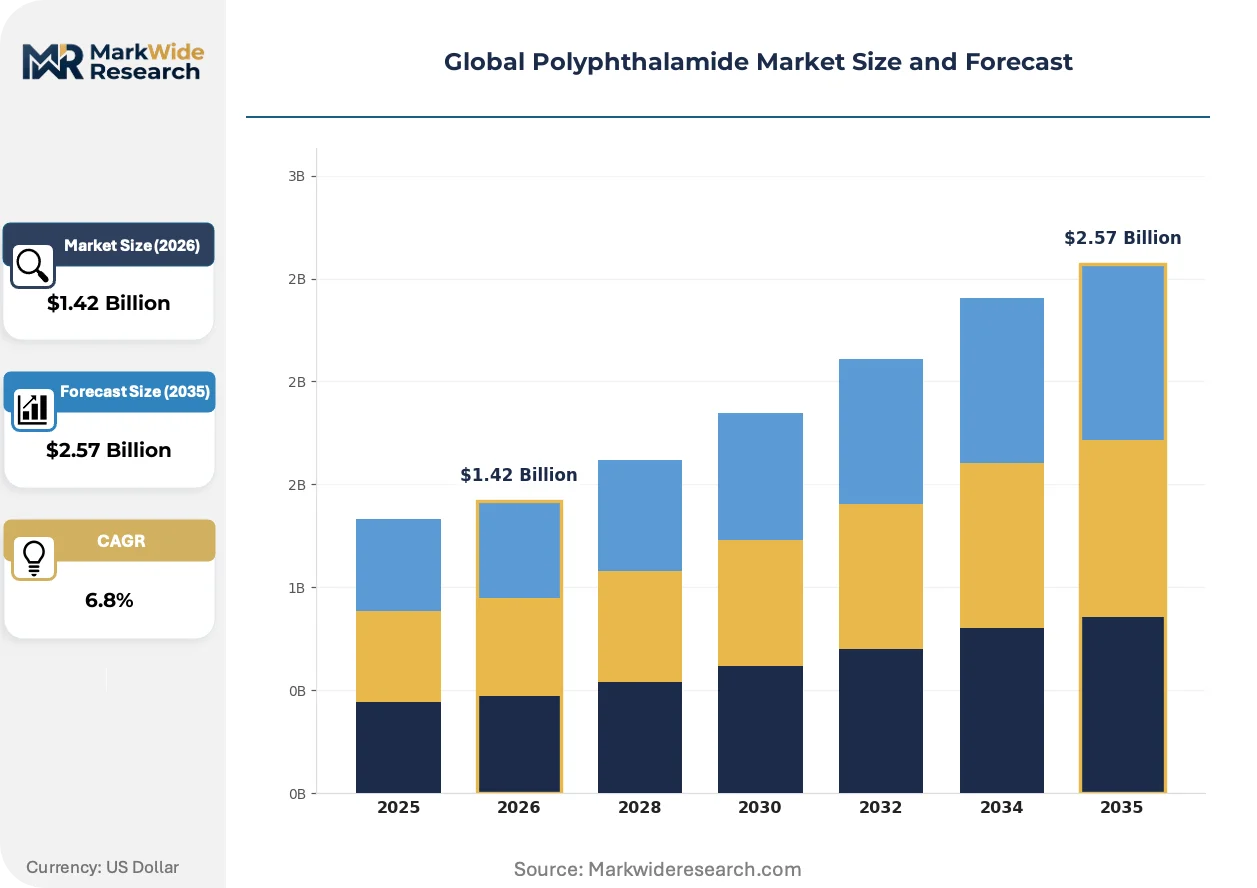
Market Dynamics
Automotive electrification is compressing material qualification timelines as OEMs simultaneously pursue thermal performance gains and copper-to-polymer substitution in high-voltage architectures. Tier-1 suppliers now face dual pressures from REACH substance restrictions and GB standard compliance for Chinese export programs, forcing parallel reformulation tracks.
Growth Catalysts
- High-Voltage Connector Demand:Battery electric vehicle platforms require continuous-use materials rated above 150°C for busbar insulation and charging inlet housings, pulling specification volumes upward across German and Chinese automotive supply chains.
- REACH Substance Restrictions:ECHA's expanding candidate list for Substances of Very High Concern is eliminating halogenated flame retardant options in legacy polyamide grades, redirecting specification authority toward PPA compounders with compliant additive packages.
- Reflow Soldering Compatibility:Surface-mount connector manufacturers specify PPA for lead-free soldering processes at 260°C peak temperatures, a requirement standard nylons cannot satisfy in telecommunications and industrial control applications.
Market Restraints
- Feedstock Concentration Risk:Terephthalic acid supply concentrates among Asian petrochemical complexes, exposing European compounders to freight cost volatility and currency fluctuation impacts on copolymer economics.
- Semi-Aromatic Polyamide Substitution:Polyarylamide and partially bio-based high-temperature nylons from specialty polymer houses capture niche specifications where carbon footprint metrics outweigh thermal ceiling requirements.
- Tooling Amortization Burden:High melt temperatures and corrosive off-gassing during PPA injection molding accelerate mold wear, elevating capital recovery thresholds for processors serving sub-scale automotive programs.
Strategic Opportunities
- India Industrial Machinery Penetration:BIS certification alignment and PLI scheme incentives for domestic manufacturing equipment create specification pathways for glass-filled grades in pump housings and valve bodies.
- EU Green Deal Procurement Mandates:Public tender requirements for recycled content in electrical infrastructure are pressuring compounders to develop post-industrial PPA regrind streams for circuit breaker applications.
- Multi-Material Overmolding Convergence:Insert molding of PPA structural frames with liquid silicone rubber seals is expanding into medical device manifolds where EMA biocompatibility requirements intersect with sterilization resistance needs.
Industry Challenges
- Color-Matching Competency Gap:Pigment stability at PPA processing temperatures requires specialized formulation expertise that concentrates among a limited pool of European masterbatch suppliers, constraining brand-differentiation timelines.
- Automotive PPAP Cycle Compression:Electric vehicle platform launches are compressing Production Part Approval Process durations from 18 months to 9 months, straining compounder laboratory capacity for full automotive fluid immersion testing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyphthalamide Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homopolymer, Copolymer, Modified Grades, High-Performance Grades Technology: Injection Molding, Extrusion, Blow Molding, Compression Molding Application: Electrical Connectors, Industrial Machinery Components, Consumer Electronics Housings, Automotive Electrical Systems End User: Electronics Manufacturers, Machinery Fabricators, Vehicle Assemblers, Consumer Appliance Producers |
| Companies Covered | Evonik Industries AG, SABIC, BASF SE, DuPont, Ems-Chemie, Arkema, Syensqo, Akro-Plastic, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyphthalamide Market Shifts & Advancements
Material science advances are fragmenting the traditional thermal-performance hierarchy as bio-based feedstocks and recycled content mandates penetrate specification criteria previously dominated by petroleum-derived grades. Compounders now compete on carbon intensity metrics alongside mechanical property tables.
Bio-based diamine feedstocks derived from castor oil are expanding into semi-aromatic polyamide formulations, delivering 30-40% renewable content without sacrificing thermal ceiling performance. European automotive OEMs specify these grades for non-structural under-hood components where marketing claims outweigh marginal cost premiums. This feedstock diversification is expanding into electrical connector housings as sustainability scorecard weighting increases in supplier selection algorithms.
China's GB standards for halogen-free flame retardancy in electrical and electronic equipment are tightening test protocol stringency, forcing reformulation of phosphorus-nitrogen synergist packages. Domestic compounders with MIIT certification laboratory partnerships capture specification authority in state-owned enterprise procurement channels. The regulatory pressure is compressing market access for imported grades lacking pre-certified test documentation.
Consolidation among automotive Tier-1 connector manufacturers is concentrating procurement authority, displacing fragmented distributor networks with direct mill relationships and annual volume commitments. Amphenol and TE Connectivity now specify global compounder qualifications valid across German, Chinese, and US fabrication sites. This buyer concentration is visible most acutely in high-voltage charging infrastructure programs where single-source material approvals reduce supply chain audit burden.
Global Polyphthalamide Market Segmentation
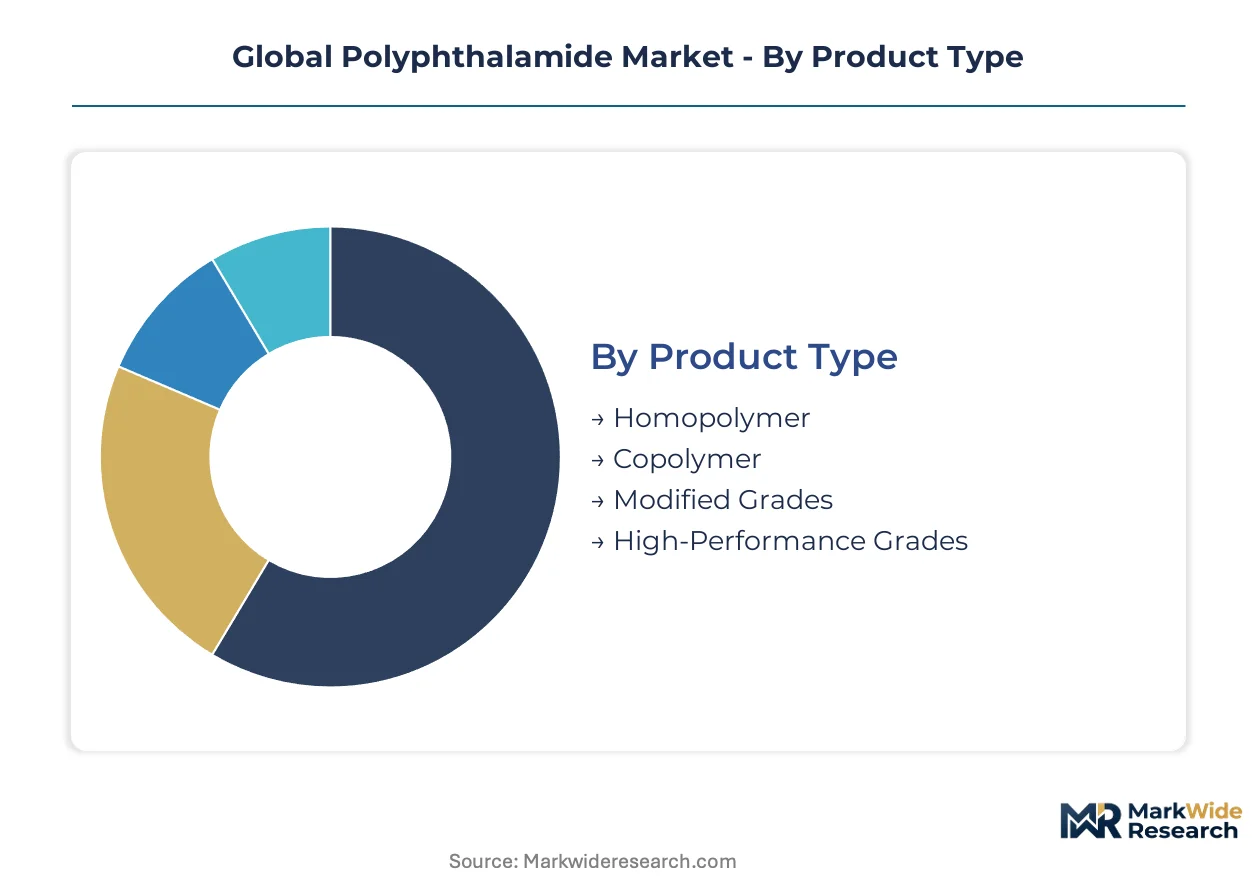
Polyphthalamide specification pathways diverge sharply across thermal ceiling requirements and regulatory compliance tiers. Compounders configure product portfolios around metal replacement cycles in automotive electrification and industrial machinery refresh programs.
Product Type:
Material substitution cycles in thermally aggressive environments drive upgrade trajectories from standard nylons toward semi-aromatic alternatives with validated fluid resistance.
- Copolymer:Balanced processability and cost positioning make this the workhorse formulation across injection molding operations serving automotive under-hood components. German connector fabricators specify copolymer grades for volume production of busbar insulation where REACH-compliant additive packages are mandatory.
- High-Performance Grades:UL flame ratings and dimensional stability command specification premiums in electrical connector applications. Chinese high-voltage charging infrastructure programs specify these grades for continuous-use temperatures exceeding 150°C in lead-free soldering environments.
- Homopolymer:Maximum thermal performance for extreme service conditions in aerospace-adjacent industrial applications.
- Modified Grades:Glass-filled variants tailored to electric motor insulation requirements and complex industrial machinery geometries.
Volume placements concentrate in Copolymer; the faster expansion belongs to High-Performance Grades.
Technology:
Processing method selection hinges on part complexity, wall thickness requirements, and capital recovery timelines for mold fabrication.
- Injection Molding:Dominant conversion technology for precision electrical connectors and under-hood automotive components. TE Connectivity and Amphenol specify injection-molded PPA for high-voltage charging inlet housings where dimensional tolerances are tight.
- Extrusion:Preferred for continuous profiles in wire insulation and cable jacketing applications serving industrial automation networks.
- Blow Molding:Limited adoption for hollow fluid handling components in specialized chemical processing equipment.
- Compression Molding:Niche deployment for thick-section industrial parts where fiber orientation control is critical.
Injection Molding commands the installed equipment base; Extrusion gains share fastest in charging infrastructure cable programs.
Application:
End-use specification authority concentrates where thermal and chemical resistance requirements exclude commodity polyamides from qualification.
- Automotive Electrical Systems:OEM electrification programs specify PPA for metal replacement in high-voltage architectures. Battery electric vehicle platforms in Germany and China require continuous-use materials rated above 150°C for busbar insulation and charging components.
- Electrical Connectors:Surface-mount manufacturing demands reflow soldering compatibility at 260°C peak temperatures. Telecommunications and industrial control applications specify these grades where standard nylons degrade.
- Industrial Machinery Components:Pump housings and valve bodies in process equipment leverage PPA as a thermoset alternative for complex geometries.
- Consumer Electronics Housings:Premium device manufacturers specify flame-retardant grades for thermal management in compact power adapters.
Automotive Electrical Systems anchor current procurement volumes; Electrical Connectors climb fastest on telecommunications infrastructure buildouts.
End User:
Buyer concentration patterns reshape supply chain access requirements, with direct mill relationships displacing fragmented distribution channels.
- Vehicle Assemblers:Tier-1 procurement authority concentrates in German, Chinese, and US automotive supply chains. Electric vehicle platform launches compress Production Part Approval Process timelines, straining compounder laboratory capacity for full automotive fluid immersion testing.
- Electronics Manufacturers:Global connector producers specify unified material qualifications across fabrication sites. State-owned enterprise procurement channels in China favor domestic compounders with MIIT certification laboratory partnerships.
- Machinery Fabricators:Industrial equipment producers in India leverage PLI scheme incentives for domestic manufacturing equipment specification.
- Consumer Appliance Producers:Premium kitchen and power tool manufacturers specify thermally stable housings for motor integration.
Vehicle Assemblers dominate contract value; Electronics Manufacturers expand most quickly on charging infrastructure scale-up.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates polyphthalamide production capacity among state-owned petrochemical complexes, while Germany and the United States absorb premium-grade volumes for automotive electrification programs. This geographic split between Asian supply origins and Western demand centers shapes freight economics and specification authority across the value chain.
China
High-voltage charging infrastructure buildouts and battery electric vehicle platform launches drive specification volumes for thermally stable connector grades. GB standards for halogen-free flame retardancy in electrical equipment tighten test protocols, favoring domestic compounders with MIIT certification laboratory partnerships. The Yangtze River Delta hosts concentrated connector fabrication clusters serving state-owned enterprise procurement channels.
Germany
OEM electrification programs specify PPA for metal replacement in busbar insulation and under-hood components requiring continuous-use temperatures above 150°C. REACH substance restrictions through ECHA's expanding candidate list eliminate halogenated flame retardant options in legacy polyamide grades. The Stuttgart and Munich automotive supply chain corridors anchor European demand for high-performance connector specifications.
United States
Tier-1 suppliers face dual pressures from EPA emissions standards and NHTSA safety requirements that elevate material traceability across automotive supply chains. Electric vehicle platform launches compress Production Part Approval Process timelines, straining compounder laboratory capacity. The Detroit automotive corridor and Southeast manufacturing belt concentrate procurement authority for high-voltage architectures.
India
Industrial machinery refresh programs and domestic manufacturing equipment incentives create specification pathways for glass-filled grades in pump housings and valve bodies. BIS certification alignment and PLI scheme incentives pressure compounders to localize technical support. The Maharashtra and Gujarat industrial corridors attract machinery fabricators seeking thermoset alternatives for complex geometries.
Japan
Telecommunications infrastructure and industrial control applications specify PPA for reflow soldering compatibility at peak temperatures standard nylons cannot satisfy. METI industrial standards and JIS certification requirements maintain rigorous material qualification protocols. The Kanto and Kansai manufacturing belts concentrate precision connector fabrication for export-oriented electronics programs.
Global Polyphthalamide Market Competitive Landscape
Top-tier vendors anchor premium-grade specification authority, while mid-scale compounders compete on cost positioning and regional certification agility. The market structure reflects concentrated R&D intensity among European and Asian majors alongside fragmented specialty compounders serving niche industrial segments. Three archetypes dominate: petrochemical-integrated producers with captive feedstock security, specialty polymer houses with automotive qualification depth, and regional compounders with regulatory certification speed. Capacity expansion and strategic partnerships represent the dominant competitive vectors as electric vehicle platform launches compress material qualification timelines.
Within the specialty polymer tier, Evonik Industries AG and BASF SE exemplify European compounders with deep automotive supply chain integration, while SABIC represents Middle Eastern petrochemical-integrated producers leveraging feedstock cost advantages. These three anchors occupy positions across the specification spectrum from high-temperature connector grades to modified formulations for electric motor insulation, reflecting divergent strategic postures between R&D intensity and upstream integration.
| Leading Market Players |
|---|
| Evonik Industries AG |
| SABIC |
| BASF SE |
| DuPont |
| Ems-Chemie |
| Arkema |
| Syensqo |
| Akro-Plastic |
| Celanese Corporation |
| Others |
Supply & Pricing Matrix
High-performance grade premiums over copolymer baselines define the pricing architecture, with UL-certified connector specifications commanding substantial markups that reflect both additive package costs and extended qualification timelines. This bifurcation manifests in supply chain configurations where European compounders with REACH-compliant additive portfolios capture specification authority in German automotive corridors, while Asian producers compete on copolymer volume deliveries to injection molders serving cost-sensitive industrial machinery segments.
Pricing Analysis
Short lead-time premiums of 15-25% apply to automotive PPAP-qualified grades where OEMs compress qualification windows from 18 months to 9 months. Contract-based long-term offtake dominates procurement, with price differentiation driven by certification tier (UL flame ratings versus industrial grades) and volume scale commitments. Cost compression in standard copolymer grades intensifies as Chinese state-owned petrochemical complexes expand terephthalic acid derivative output. Tier-1 electronics manufacturers exhibit lowest price sensitivity due to single-source material approval requirements, while Indian machinery fabricators remain most price-sensitive given PLI scheme margin constraints.
Supply Chain Analysis
Workforce availability constraints in Yangtze River Delta connector fabrication clusters and Stuttgart automotive corridors elevate labor cost differentials across manufacturing geographies. Terephthalic acid supply concentrates in China, South Korea, and Taiwan, with European compounders drawing from Asian petrochemical feedstocks. Raw material dependencies center on para-xylene derivatives, aliphatic diamines, and glass fiber reinforcements. Single-source vulnerability in halogen-free flame retardant additive packages creates supply chain risk as ECHA expands SVHC candidate listings. Distribution runs through direct mill relationships with consolidated Tier-1 connector manufacturers, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH substance restrictions and ECHA's expanding SVHC candidate list erect barrier-to-entry moats for compounders with validated additive portfolios. Regulatory divergence between European, Chinese, and US frameworks fragments specification authority, rewarding players with multi-jurisdictional certification laboratory partnerships.
For Market Incumbents: Extend certification depth across MIIT, UL, and ECHA frameworks to defend specification authority against emerging Chinese compounders with state-backed laboratory partnerships. Prioritize backward integration into petrochemical feedstocks to stabilize copolymer cost structures against freight volatility from Asian supply origins. Capacity addition in German automotive corridors reinforces proximity to OEM electrification programs compressing PPAP timelines. For New Entrants and Emerging Players: The premium-to-economy price gap in high-voltage charging infrastructure grades creates entry opportunity for compounders with phosphorus-nitrogen flame retardant expertise. Target Indian industrial machinery segments where BIS certification alignment and PLI scheme incentives outpace established European supplier response times. Go-to-market leverage rests with technical service partnerships for mold flow optimization in PPA's corrosive processing environment. For Investors and Strategic Acquirers: Re-rating potential sits with specialty polymer houses possessing automotive qualification depth given electric vehicle platform launches accelerating specification volume capture. Long-term viability favors compounders with demonstrated UL flame rating portfolios and REACH-compliant additive packages across the projection horizon. Signal to monitor: consolidation among Tier-1 connector manufacturers concentrating procurement authority into direct mill relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terephthalic Acid Feedstocks | SABIC's petrochemical integration stabilizes copolymer cost structures against Asian freight volatility. |
| MIIT Certification Laboratory Partnership | Domestic Chinese compounders capture state-owned enterprise procurement channels under tightening GB standards. |
| Post-Industrial PPA Regrind Stream Development | EU Green Deal recycled content mandates pressure compounders toward circular material pathways. |
| Multi-Material Overmolding Capability Investment | Insert molding of PPA frames with liquid silicone rubber expands into EMA-regulated medical device manifolds. |
| Automotive Fluid Immersion Testing Capacity Expansion | Compressed PPAP timelines strain compounder laboratory capacity for full thermal and chemical validation protocols. |
Research Methodology
Multi-period observation of automotive electrification program launches, REACH regulatory amendment schedules, and high-voltage charging infrastructure deployment rates anchored the trend analysis, supplemented by interviews with compounder technical directors, Tier-1 connector procurement leads, automotive OEM platform engineers, and industrial machinery fabricators. Secondary validation drew from ECHA SVHC candidate list publications, MIIT certification databases, customs trade data for terephthalic acid derivatives, and SEC filings from listed petrochemical producers. Bottom-up segment modeling triangulated against top-down macroeconomic drivers.
Input-output matrices mapped copolymer and high-performance grade consumption across injection molding and extrusion technologies, with segmentation dimensions spanning product type, processing method, application vertical, and end-user concentration. CAGRs were derived from elasticity modeling against automotive production forecasts and telecommunications infrastructure capex disclosures. Industry-specific forecast inputs included electric vehicle platform launch schedules and reflow soldering temperature specification trajectories in surface-mount connector manufacturing.
Inputs from ECHA regulatory filings and MIIT certification records were available through the study window; gaps in real-time Tier-1 procurement contract disclosures introduce uncertainty bands around specification volume capture estimates. Forecasts reflect documented assumptions regarding REACH implementation timelines and GB standard harmonization progress. Material deviation in electric vehicle platform launch schedules or ECHA SVHC candidate list expansion velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Acetal (POM) Copolymer Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Natural Polymers Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Asia-Pacific Geopolymer Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
South America Engineering Plastics Market