
 Polyolefin Foam Market | 2026-2036
Polyolefin Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Polyolefin Foam Market Intelligence
The unbundling of foam materials from pre-fabricated insulation kits is broadening customer choice in construction applications, allowing for more customized solutions. Sekisui Chemical Co., Ltd. leverages its portfolio in cross-linked foams to serve this modular demand. The Dow Chemical Company sustains a strong position through large-scale production of non-cross-linked foams. Zotefoams plc differentiates with its high-performance, nitrogen-expanded products for specialized sectors like aerospace.
Polyolefin foam is a lightweight polymer material defined by a cellular structure formed via extrusion with blowing agents. This process yields materials with specific densities used for thermal insulation, cushioning, and shock absorption. Cross-linked foam products command higher margins for their superior durability in demanding applications. The packaging sector drives volume for non-cross-linked foams, while automotive components represent a key growth area.
Regulatory frameworks significantly influence material composition and market access. The European Union's REACH regulation governs chemical substances used in foam production, while the US EPA sets standards for blowing agents. In China, GB standards dictate performance requirements for foams in construction and consumer goods. Stakeholders must now decide between investing in advanced recycling technologies or developing bio-based polyolefin alternatives to meet sustainability mandates.
Market Dynamics
The central structural force shaping the polyolefin foam market is the conflict between demand for high-performance, lightweight materials in sectors like automotive and the increasing regulatory pressure for circularity and sustainable feedstocks, governed by frameworks like the EU Green Deal.
Growth Catalysts
- Automotive Lightweighting:Demand from automotive component manufacturers for lightweight foams accelerates to reduce vehicle mass, thereby improving fuel efficiency in internal combustion engine vehicles and extending the range of electric vehicles.
- Circular Economy Mandates:The EU Green Deal and its associated policies promote materials with high recyclability, creating a pull for polyolefin foams that can be integrated into closed-loop recycling systems over less sustainable alternatives.
- Advanced Electronics Packaging:Concentrated demand within China's Pearl River Delta for high-value electronics protection requires advanced, clean-room-compatible polyolefin foams for shock absorption and cushioning during shipment.
Market Restraints
- Feedstock Price Volatility:The price of polyolefin foams is directly linked to the fluctuating costs of polyolefin resins, which are derivatives of crude oil, introducing significant margin uncertainty for foam manufacturers.
- Regulatory Compliance Burden:Complex chemical regulations, such as the EU's REACH framework, restrict the use of certain blowing agents and additives, complicating formulation and increasing compliance costs for market access.
- Threat of Substitution:In lower-performance packaging and construction applications, polyolefin foams face persistent competition from materials like expanded polystyrene (EPS) and molded pulp, which can offer a lower cost basis.
Strategic Opportunities
- Bio-Based Feedstocks:Developing and scaling production of bio-based or chemically recycled polyolefin foams presents a significant opportunity to capture demand from customers with aggressive corporate sustainability goals.
- Renewable Energy Applications:Underpenetrated applications in the renewable energy sector, such as buoyancy components for floating solar arrays or thermal insulation for battery energy storage systems, offer new growth avenues.
- Intelligent Material Systems:The convergence of foam technology with printed electronics enables the creation of smart packaging that can monitor and log impacts or temperature deviations, adding significant value.
Industry Challenges
- High Capital Intensity:The manufacturing of high-performance, nitrogen-expanded foams requires substantial capital investment in specialized high-pressure extrusion lines, creating a high barrier to entry for smaller firms.
- Recycling Infrastructure Gaps:A lack of scaled, economically viable advanced recycling infrastructure to process post-consumer cross-linked foams remains a major operational hurdle to achieving true circularity for these durable materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyolefin Foam Market |
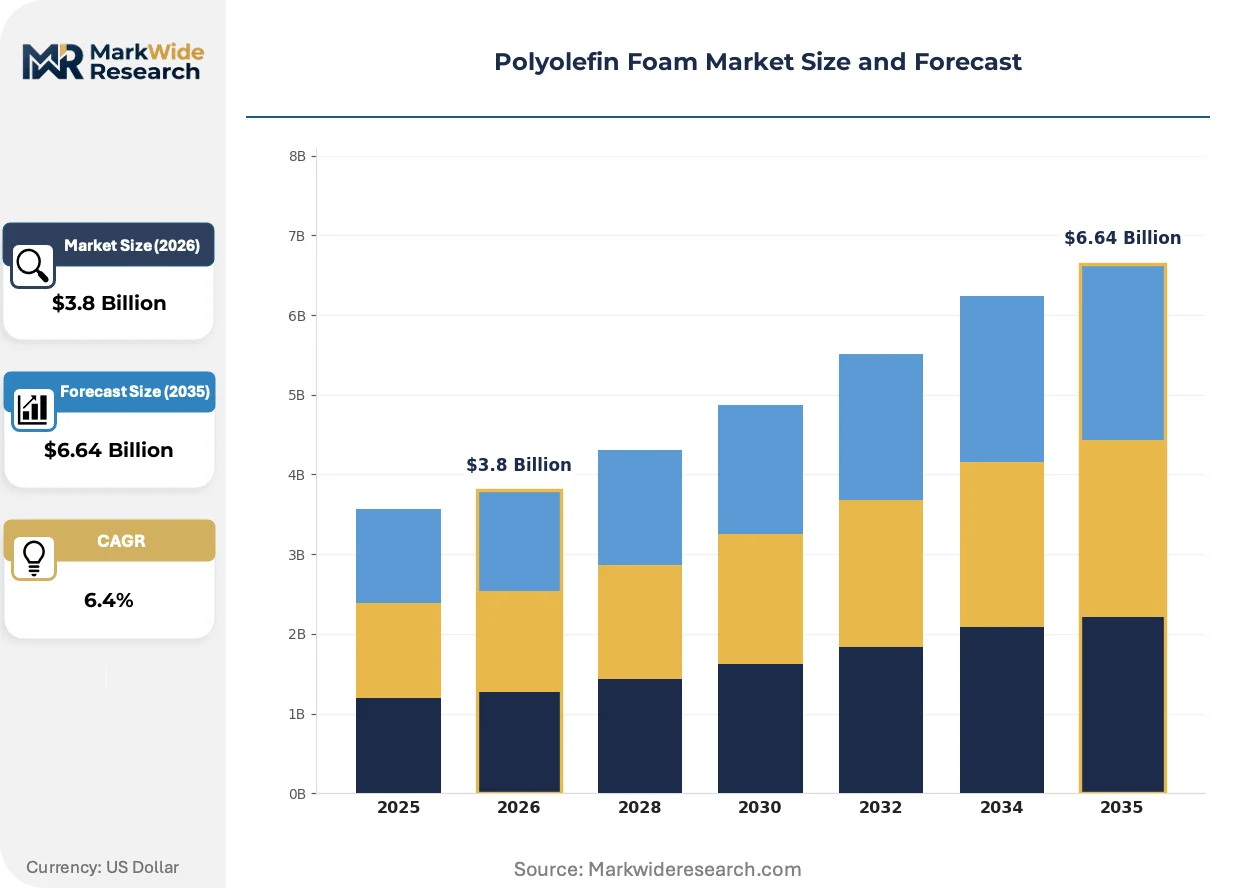
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-Cell Foam, Open-Cell Foam, Cross-Linked Foam, Non-Cross-Linked Foam, Composite Foam Application: Construction Insulation, Consumer Goods, Packaging, Sports Equipment, Automotive Components, Electronics Protection End User Industry: Building & Infrastructure, Packaging Manufacturers, Sporting Goods Makers, Vehicle Assemblers, Electrical Equipment Producers Manufacturing Process: Extrusion Process, Chemical Blowing, Physical Blowing, Compression Molding, Injection Molding |
| Companies Covered | Zotefoams plc, The Dow Chemical Company, Armacell International S.A., BASF SE, Borealis AG, Sekisui Chemical Co., Ltd., Kaneka Corporation, Toray Industries, Inc., JSP Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyolefin Foam Market Strategic Shifts & Innovations
A fundamental pivot toward materials offering superior performance and verifiable sustainability is defining the market. This shift is driven by a convergence of advanced manufacturing processes and stringent environmental regulations that prioritize lifecycle management over initial cost.
Nitrogen-expansion technology is a key process for creating high-purity foams with exceptionally uniform, fine-celled structures. The aerospace, medical, and high-end electronics sectors are steadily adopting these materials for applications where outgassing and contamination are unacceptable. This move toward specialized, high-margin products is electrifying the competitive landscape, creating a performance divide that commodity foams cannot bridge.
The US EPA's regulations under the SNAP program mandate the phase-out of blowing agents with high global warming potential. This regulatory action compels foam producers to reformulate their processes and invest in new chemistries. The non-cross-linked foam segment, used heavily in construction insulation and general packaging, is most impacted and is accelerating its shift to next-generation hydrofluoroolefin (HFO) blowing agents.
A shift toward modularity in procurement is altering supply chain dynamics, as end-users in construction increasingly buy foam material separately from prefabricated systems. This unbundling of products and services disrupts the traditional integrated-solution sales model, creating an advantage for suppliers with flexible converting capabilities. This pattern is most pronounced in North American and European building markets where customized insulation solutions are preferred.
Polyolefin Foam Market Segmentation
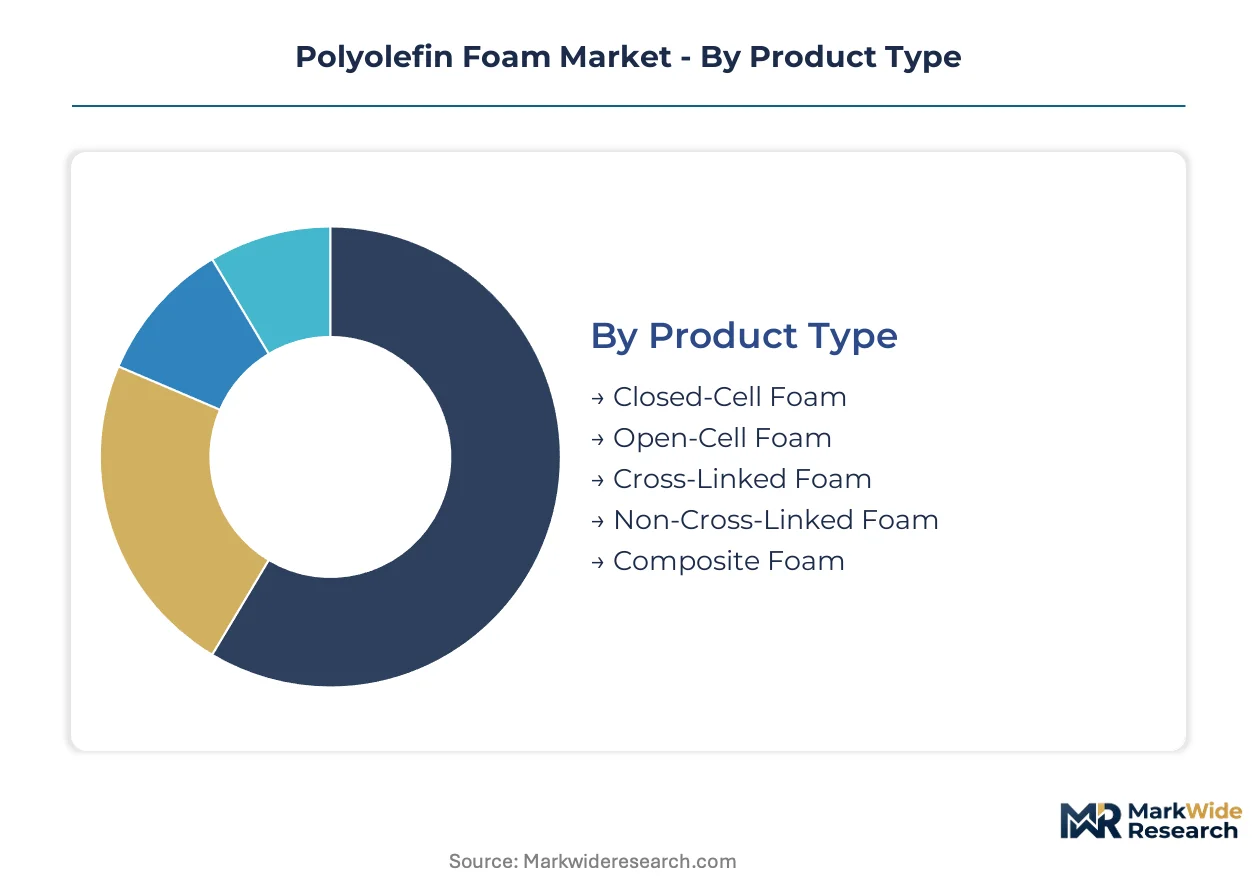
The polyolefin foam market differentiates materials based on their intrinsic properties, intended applications, and production methods. Understanding these distinctions allows stakeholders to navigate regulatory compliance and optimize material selection for specific performance requirements across diverse end-use sectors.
Product Type:
Material certification burdens vary significantly across polyolefin foam product types, with high-performance variants often requiring more stringent approvals for specialized applications.
- Cross-Linked Foam:These foams exhibit a robust, interconnected polymer structure, providing superior durability, chemical resistance, and thermal stability in demanding environments. Demand concentrates in the automotive components sector, driven by vehicle lightweighting initiatives for improved fuel efficiency and EV range.
- Non-Cross-Linked Foam:Lacking chemical bonds between polymer chains, this foam type offers greater flexibility and cost-effectiveness, making it suitable for high-volume, less strenuous applications. The packaging sector drives significant volume for these foams, particularly for general cushioning and protective inserts.
- Closed-Cell Foam:Characterized by distinct, non-interconnected cells, closed-cell foams offer excellent thermal insulation properties and moisture resistance. Construction insulation applications in European building markets leverage these properties for energy efficiency mandates.
- Open-Cell Foam:Featuring interconnected cells, open-cell foams provide superior sound absorption and flexibility, often used in acoustic dampening and comfort applications. Consumer goods, such as furniture and bedding, utilize these foams for their soft tactile properties.
- Composite Foam:These materials combine polyolefin foams with other substances, such as fabric or metal foils, to enhance specific properties like strength or barrier function. Specialized packaging solutions for sensitive electronics in China's Pearl River Delta integrate composite foams for multi-functional protection.
Leading the category by volume: Non-Cross-Linked Foam. Growing fastest: Cross-Linked Foam.
Application:
The polyolefin foam market serves a broad spectrum of applications, each demanding specific performance characteristics and driving different volume and value dynamics.
- Automotive Components:Polyolefin foams reduce vehicle mass, contributing to fuel efficiency in internal combustion engines and extending electric vehicle range. Vehicle assemblers in Germany and the US integrate these foams for interior trim, energy absorption, and NVH (noise, vibration, harshness) reduction.
- Packaging:This application segment utilizes polyolefin foams for cushioning, shock absorption, and thermal insulation, protecting goods during transit. Concentrated demand in China's electronics manufacturing hubs requires advanced packaging solutions for high-value products.
- Construction Insulation:Polyolefin foams provide effective thermal barriers in residential and commercial buildings, contributing to energy conservation and compliance with building codes. North American and European building markets increasingly specify these foams for their long-term performance and moisture resistance.
- Electronics Protection:High-purity polyolefin foams safeguard sensitive electronic devices from impact, vibration, and electrostatic discharge. Manufacturers of advanced electronics, particularly in Asia, rely on these materials for clean-room compatible packaging.
- Consumer Goods:Foams are incorporated into various consumer products for cushioning, comfort, and lightweighting, including footwear, sporting goods, and furniture. Sporting goods makers in Japan and Europe use these foams for impact protection and ergonomic design.
- Sports Equipment:Polyolefin foams are critical in sports equipment for impact absorption, buoyancy, and lightweight construction in products like protective gear and flotation devices.
The largest application segment by volume is Packaging. Automotive Components represents the fastest-growing application.
End User Industry:
The end-user industries for polyolefin foams dictate procurement patterns and material specifications, with large-scale buyers often seeking customized solutions and consistent supply.
- Vehicle Assemblers:These manufacturers integrate polyolefin foams into various automotive parts, including seating, headliners, and impact absorption systems, to meet lightweighting and safety standards. Major automotive OEMs in Europe and North America drive innovation in foam material specifications.
- Packaging Manufacturers:This industry segment converts polyolefin foam sheets and rolls into protective packaging solutions for a diverse range of products. Packaging manufacturers serving the electronics sector in China require foams with specific anti-static and cushioning properties.
- Building & Infrastructure:This sector uses polyolefin foams primarily for thermal and acoustic insulation in commercial and residential construction projects. Compliance with the EU Green Deal's energy efficiency mandates influences material selection for building insulation in Europe.
- Electrical Equipment Producers:Manufacturers in this sector use polyolefin foams for internal component protection, vibration dampening, and clean packaging for sensitive electronics. Producers of advanced electronics in South Korea and Taiwan demand high-purity foams.
- Sporting Goods Makers:Companies producing athletic equipment utilize polyolefin foams for cushioning, impact protection, and buoyancy in products like helmets, pads, and flotation devices.
Packaging Manufacturers account for the largest share of polyolefin foam consumption. Vehicle Assemblers are expanding their usage most quickly.
Manufacturing Process:
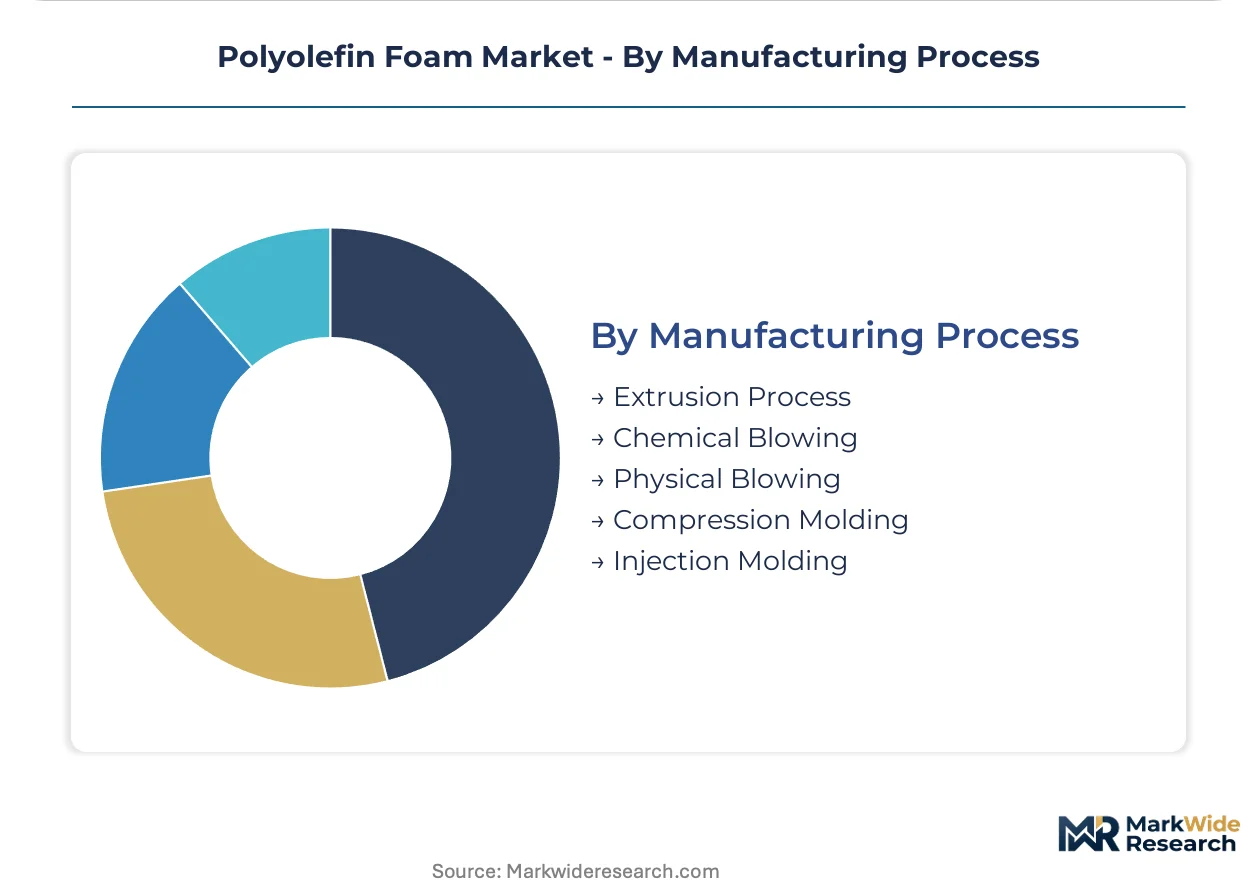
The manufacturing process significantly influences the cellular structure, density, and performance characteristics of polyolefin foams, impacting their suitability for different applications and market positioning.
- Extrusion Process:This widely used method involves melting polymer resins and forcing them through a die with blowing agents, creating a continuous foam sheet or profile. This process is fundamental for producing a broad range of polyolefin foams used in construction and packaging.
- Physical Blowing:This process uses inert gases, such as nitrogen or carbon dioxide, as blowing agents, resulting in foams with fine, uniform cell structures and often superior mechanical properties. Zotefoams plc specializes in high-performance nitrogen-expanded products for aerospace and medical sectors.
- Chemical Blowing:This method incorporates chemical blowing agents that decompose upon heating to release gases, forming the cellular structure of the foam. The non-cross-linked foam segment, particularly for packaging, heavily relies on chemical blowing processes, but faces regulatory pressure from the US EPA's SNAP program.
- Compression Molding:This process involves placing foam material into a mold and applying heat and pressure to form complex shapes with precise dimensions. Sports equipment manufacturers frequently use compression molding for protective gear components.
- Injection Molding:While less common for foams than solid plastics, injection molding can produce foamed parts with intricate designs and integrated features. This process is sometimes employed for specialized components requiring high dimensional accuracy.
Extrusion Process accounts for the highest volume of polyolefin foam production. Physical Blowing technologies are gaining share fastest due to performance and environmental advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyolefin foam production and consumption patterns vary significantly across global regions. Demand for advanced foam materials is concentrating in specific industrial hubs, while regulatory pressures for sustainability are influencing material choices worldwide. This creates a dynamic landscape where local market forces interact with global mandates.
China
China's robust electronics manufacturing sector drives demand for high-purity polyolefin foams in packaging. GB standards dictate performance requirements for foams in construction and consumer goods, ensuring quality. The Pearl River Delta concentrates demand for advanced, clean-room-compatible foams for shock absorption in electronics.
United States
United States automotive manufacturers seek polyolefin foams for vehicle lightweighting and improved fuel efficiency. The US EPA sets stringent standards for blowing agents, compelling foam producers to reformulate. Michigan's automotive industry integrates these foams for interior trim and noise reduction in new vehicle designs.
Germany
Germany's automotive sector requires high-performance polyolefin foams for lightweighting and NVH reduction. The EU Green Deal and REACH regulation influence material selection, promoting recyclability and sustainable feedstocks. Bavarian vehicle assemblers integrate advanced foams for interior components and energy absorption systems.
Japan
Japanese sporting goods makers utilize polyolefin foams for impact protection and ergonomic designs in equipment. JIS standards dictate material quality and performance for various foam applications, ensuring product safety. Tokyo's advanced manufacturing hubs increasingly adopt high-purity foams for sensitive electronics protection.
India
India's expanding construction sector demands polyolefin foams for thermal insulation and energy efficiency in buildings. BIS standards provide guidelines for construction materials, impacting foam specifications and market access. Chennai's automotive manufacturing cluster is increasingly integrating foams for lightweighting and component protection.
Polyolefin Foam Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a multi-tiered polyolefin foam market structure. Large chemical companies leverage extensive material portfolios and global distribution networks, often dominating high-volume, commodity segments. Niche manufacturers, conversely, concentrate on high-performance formulations for specialized applications, commanding premium margins through technological differentiation. Strategic partnerships and capacity expansion are dominant competitive moves among these diverse players seeking to enhance market reach and product innovation.
On the premium-tier vector, Zotefoams plc exemplifies a focus on high-performance, specialized foam solutions. The Dow Chemical Company, a US-based chemical giant, anchors the market's large-scale production of non-cross-linked foams for volume-driven applications. Sekisui Chemical Co., Ltd., a Japan-based corporation, occupies a strong position through its diverse portfolio of cross-linked foams, serving modular demand in construction. These entities represent different strategic approaches to market penetration and value creation.
| Leading Market Players |
|---|
| Zotefoams plc |
| The Dow Chemical Company |
| Armacell International S.A. |
| BASF SE |
| Borealis AG |
| Sekisui Chemical Co., Ltd. |
| Kaneka Corporation |
| Toray Industries, Inc. |
| JSP Corporation |
| Others |
Cost & Logistics Intelligence
Physical blowing technology's expansion into high-performance polyolefin foams simultaneously reshapes cost economics for specialized products and concentrates supply around specific regional manufacturing hubs. This shift necessitates strategic adjustments across the value chain.
Pricing Analysis
Cost-down pressure on commodity non-cross-linked foams accelerates because of persistent competition from expanded polystyrene and molded pulp alternatives. Pricing for polyolefin foams operates on a hybrid model, combining contract-based long-term offtake for automotive and construction applications with commodity spot pricing for high-volume packaging. Price differentiation stems from quality grade, particularly for nitrogen-expanded products, and specific regulatory certifications like REACH compliance. The packaging sector exhibits the highest price sensitivity, contrasting with the lower sensitivity observed in aerospace and medical applications.
Supply Chain Analysis
Domestic-content mandates and regional production clusters reshape sourcing patterns for polyolefin foams, particularly in automotive and construction sectors. Geographic supply concentrates in China for electronics packaging, Germany for automotive components, and Japan for sporting goods and advanced electronics. The market relies heavily on polyolefin resins, derivatives of crude oil, and specialized blowing agents like HFOs. Commodity price volatility for these raw materials represents a significant structural risk. Distribution runs through direct sales channels for large industrial buyers and extensive distributor networks for fragmented packaging and consumer goods segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polyolefin foam market is experiencing a vertical-integration race, primarily driven by players seeking upstream control over bio-based feedstock supply and advanced recycling infrastructure. This strategic pursuit aims to secure sustainable material flow.
For Market Incumbents: Acquire advanced recycling technologies or bio-based feedstock producers to mitigate future regulatory risks and secure sustainable material pipelines. Invest in research and development for next-generation HFO blowing agents to comply with US EPA SNAP program mandates, safeguarding market access. Expand high-performance nitrogen-expanded foam capacity in strategic regions like Germany and Japan to counter substitution threats from cheaper, lower-performance alternatives. Focus on certification investments for specialized aerospace and medical applications to maintain premium margins.
For New Entrants and Emerging Players: Capture niche demand in underpenetrated applications like buoyancy components for floating solar arrays or thermal insulation for battery energy storage systems. Target the rapidly growing intelligent material systems segment, focusing on smart packaging solutions that monitor impacts or temperature deviations. The bio-based polyolefin alternatives market, driven by aggressive corporate sustainability goals, offers a penetrable segment for specialized players. Partner with design-led engineering firms to co-develop customized, high-value foam solutions for specific industrial challenges.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized foam producers with proprietary technology, particularly those offering verifiable sustainability credentials. The long-term viability of the high-performance and bio-based polyolefin foam segments shows strong growth potential over a 5-10 year window. Target niche players possessing advanced physical blowing capabilities or patented bio-based material formulations for strategic acquisition. The signal to watch is increased M&A activity for advanced recycling start-ups or manufacturers of novel, environmentally compliant blowing agents.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding production of nitrogen-expanded foams supports growing demand from aerospace and automotive lightweighting initiatives. |
| Green Manufacturing Transition | Investing in hydrofluoroolefin (HFO) blowing agents ensures compliance with US EPA regulations, maintaining market access for non-cross-linked foams. |
| Long-term Supply Agreement | Securing bio-based polyolefin resin supply insulates manufacturers from feedstock price volatility and meets sustainability mandates. |
| Joint Venture | Collaborating on advanced recycling infrastructure addresses the critical gap for processing post-consumer cross-linked foams. |
| Product Launch | Introducing intelligent foam packaging systems adds significant value for sensitive electronics protection in China's Pearl River Delta. |
Research Approach
Independent corroboration across industry reports, regulatory filings, and company annual reports underwrites the qualitative findings and quantitative projections. Primary interviews with automotive component engineers, packaging procurement managers, and foam manufacturing R&D directors informed the analysis. Secondary data validation leveraged EU REACH documentation, US EPA SNAP program guidelines, and China GB standards, ensuring robust bottom-up sizing and top-down validation.
The forecast window was anchored to historical reference periods, establishing a baseline for projected market trajectories. The analytical framework modeled segmentation dimensions including product type, application, manufacturing process, and regional regulatory impact. Compound annual growth rates were derived from historical growth trends and projected demand drivers, with vehicle production forecasts and electronics manufacturing output serving as critical industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to polyolefin feedstock price volatility and unexpected regulatory shifts. Projections reflect assumptions regarding technological advancements and market adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Polyphenylene Sulfide (PPS) Resin Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Vinyl Acetate Homopolymer Emulsion Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Dispersant Polymer Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Bio-Based Polypropylene Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Nylon-6 Market