
 North America Starch Derivatives Market | 2026-2036
North America Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
North America Starch Derivatives Market Analytics
Subscription-based technical service layers for reformulation support is hardening into a core revenue stream for ingredient suppliers. Cargill leverages its Minneapolis-based food innovation centers to embed starch specialists directly into customer pilot plants. Ingredion Incorporated anchors its competitive position through backward integration into waxy corn and tapioca sourcing networks across the U.S. Gulf Coast and Mexico. Archer Daniels Midland Company sustains manufacturing scale advantages from its Decatur, Illinois complex, the largest corn-processing facility in North America.
Starch derivatives are carbohydrate-based compounds produced through physical, enzymatic, or chemical modification of native starches, yielding functional properties such as controlled viscosity, film-forming capacity, and freeze-thaw stability for industrial applications. Modified starch commands the dominant share of product-type value pools due to its tailored functionality in processed foods and pharmaceutical binders, while liquid starch experiences the fastest application growth in textile sizing operations across the southeastern United States. Food and beverage applications absorb the majority of volume, though nutraceutical companies are driving premium-margin demand for specialty maltodextrins with specific dextrose equivalent ranges.
The FDA governs starch derivative safety through GRAS notifications and food additive petitions, while Health Canada administers the Food and Drug Regulations that determine permitted modified starch categories in Canadian commerce. The EPA regulates wastewater discharge from wet-milling facilities under Clean Water Act permits, directly influencing plant location economics and capital intensity for new derivative capacity. Stakeholders must monitor evolving FDA positions on resistant starch health claims and provincial water-board rulings in Ontario and Quebec that could reshape processing cost structures across the Great Lakes basin.
Market Dynamics
Clean-label formulation mandates from major food retailers are compressing reformulation cycles across the North American processed food sector, forcing starch derivative suppliers to embed technical service teams directly within customer R&D facilities.
Growth Catalysts
- Health Canada's Food Additive Modernization:Accelerated approval pathways for novel modified starches enable faster ingredient substitution in Canadian packaged goods manufacturing.
- Midwest Corn-Processing Infrastructure:Wet-milling capacity concentration across Illinois, Iowa, and Nebraska generates feedstock cost advantages for dextrin and maltodextrin production.
- Resistant Starch Health Claims:Evolving FDA positions on dietary fiber labeling create pull for specialty derivatives in functional food applications.
Market Restraints
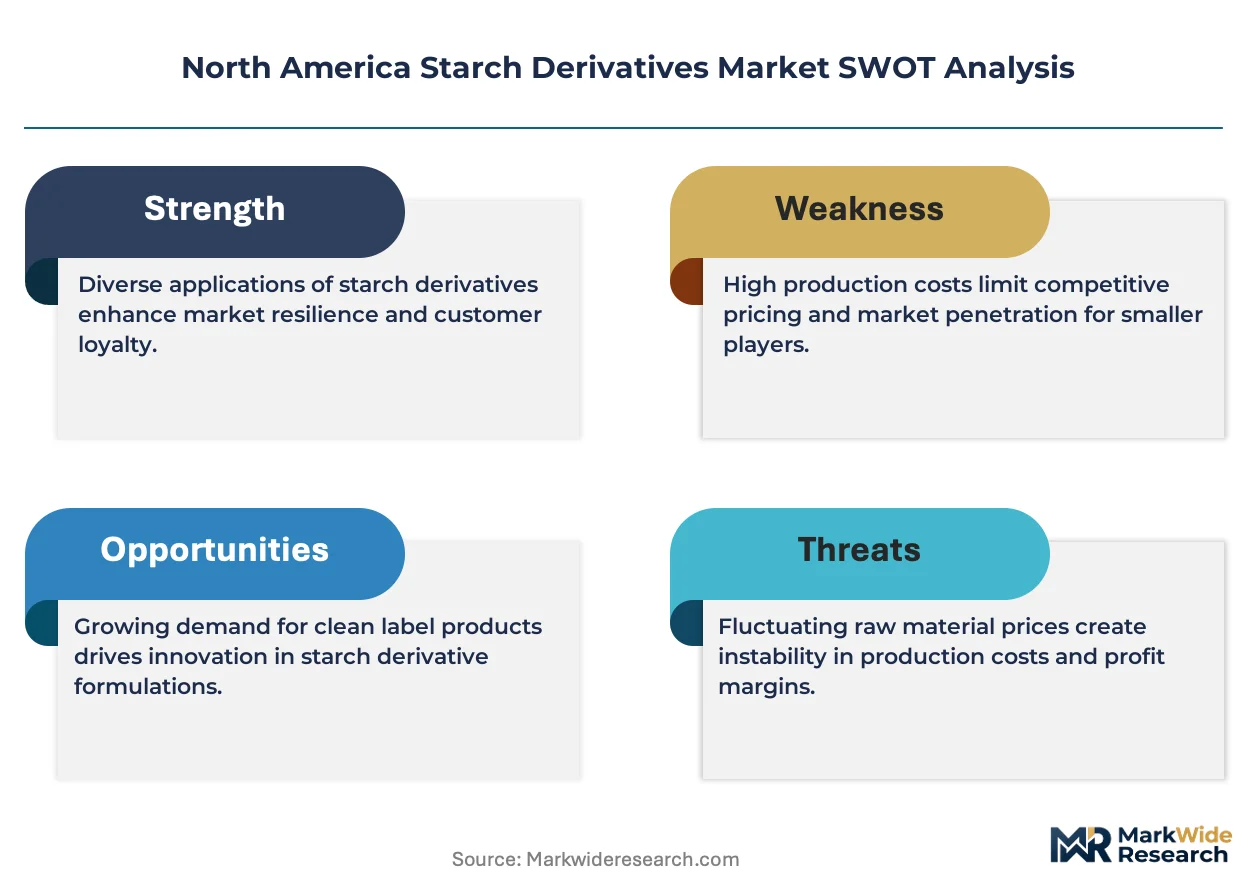
- Input Cost Volatility:Corn futures price swings tied to ethanol policy uncertainty compress margin predictability for derivative manufacturers.
- Supply Concentration Risk:Three integrated processors control majority of North American modified starch capacity, creating bottleneck vulnerability.
- Technical Substitution Limits:Clean-label starches cannot fully replicate the freeze-thaw stability of chemically modified alternatives in frozen dough systems.
Strategic Opportunities
- Underpenetrated Mexican Food Sector:Tortilla and snack manufacturers in Guadalajara and Monterrey represent untapped volume for native starch systems.
- Pharmaceutical Binder Applications:Specialty pregelatinized starches are capturing share from synthetic binders in tablet formulations.
- EPA Clean Water Act Incentives:Wastewater recovery technology investments unlock capacity expansion permits in water-stressed Great Lakes processing corridors.
Industry Challenges
- Reformulation Talent Scarcity:Food scientists with dual expertise in starch chemistry and sensory science command premium compensation and extend project timelines.
- Legacy Equipment Integration:Retrofitting continuous enzymatic conversion systems into batch-native plants requires extended shutdown windows and capital redeployment.
- GRAS Notification Timelines:FDA safety determination backlogs delay commercialization of novel modified starch variants by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Starch Derivatives Market |
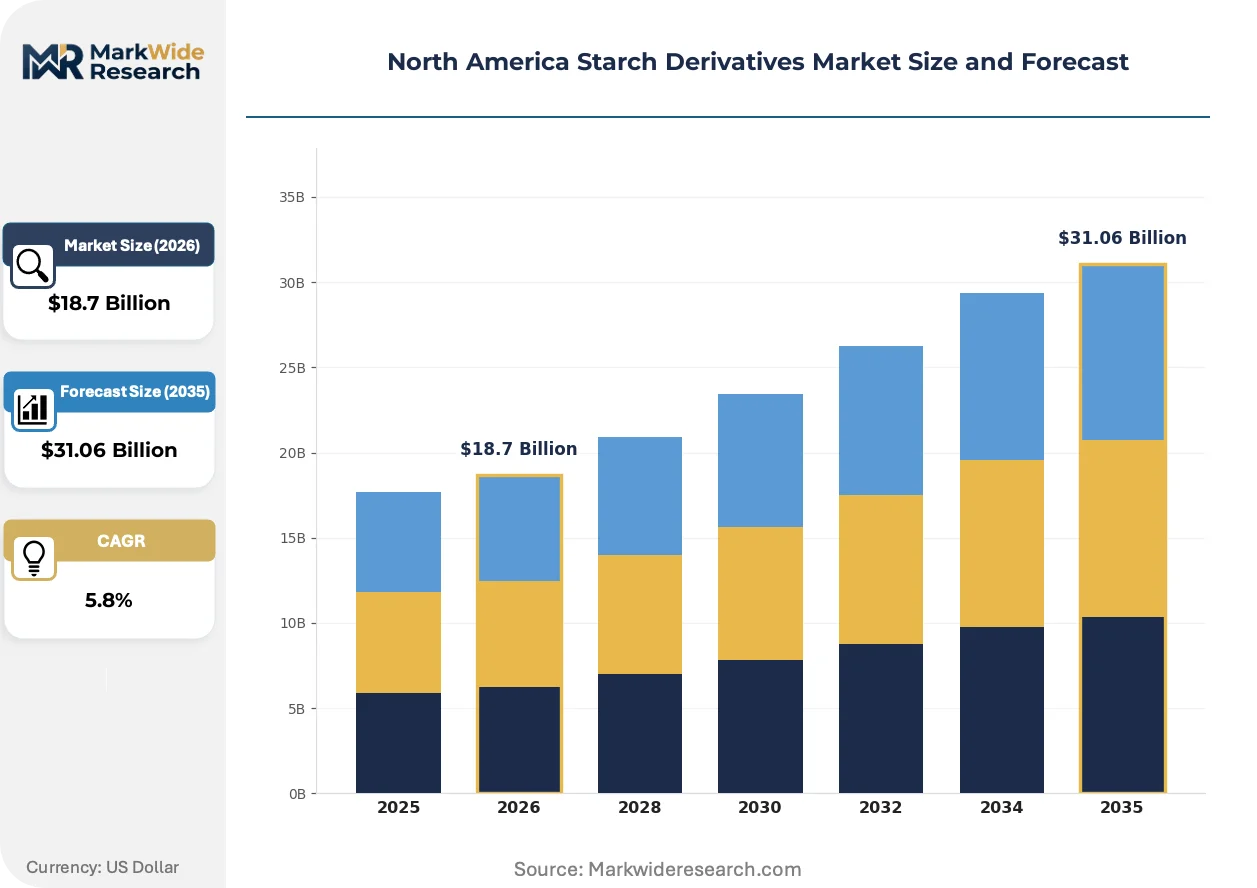
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Liquid Starch, Starch Syrup Application: Food & Beverage, Textiles, Pharmaceuticals, Cosmetics Form: Powder, Granules, Liquid, Flakes End User: Food Manufacturers, Industrial Processors, Nutraceutical Companies, Personal Care Brands |
| Companies Covered | Archer Daniels Midland Company, Cargill, Ingredion Incorporated, Tate & Lyle, Roquette, Grain Processing Corporation, Primient, Agrana Group, Beneo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Starch Derivatives Market Evolving Landscape
Enzymatic modification platforms are displacing traditional chemical processes across North American starch derivative manufacturing, compressing production cycles while satisfying clean-label procurement criteria from major food brands.
Clean-label enzymatic starch modification is unifying the previously separate functions of viscosity control and freeze-thaw stability in a single ingredient platform. Frozen prepared food manufacturers in the U.S. Southeast are adopting these systems at twice the rate of conventional modified starches. This convergence is unifying what were formerly multi-ingredient stabilizer blends into single-component solutions, reducing supplier count and simplifying label declarations.
The FDA's updated guidance on resistant starch dietary fiber classification is redirecting R&D investment toward high-amylose corn hybrids and novel thermal processing methods. Ingredient suppliers must now substantiate physiological benefits through clinical data packages that exceed prior substantiation requirements. Nutraceutical applications in the U.S. West Coast functional food corridor face the steepest compliance burden, with several firms establishing dedicated regulatory affairs functions to manage petition timelines.
Direct technical service embedding is replacing traditional distributor-mediated support across major account relationships. National bakery and snack manufacturers now expect starch specialists to maintain permanent presence at pilot plant facilities rather than periodic consultation. This pattern is most pronounced in the Minneapolis-Chicago food manufacturing corridor, where three of the five largest North American food companies maintain central R&D headquarters.
North America Starch Derivatives Market Segmentation
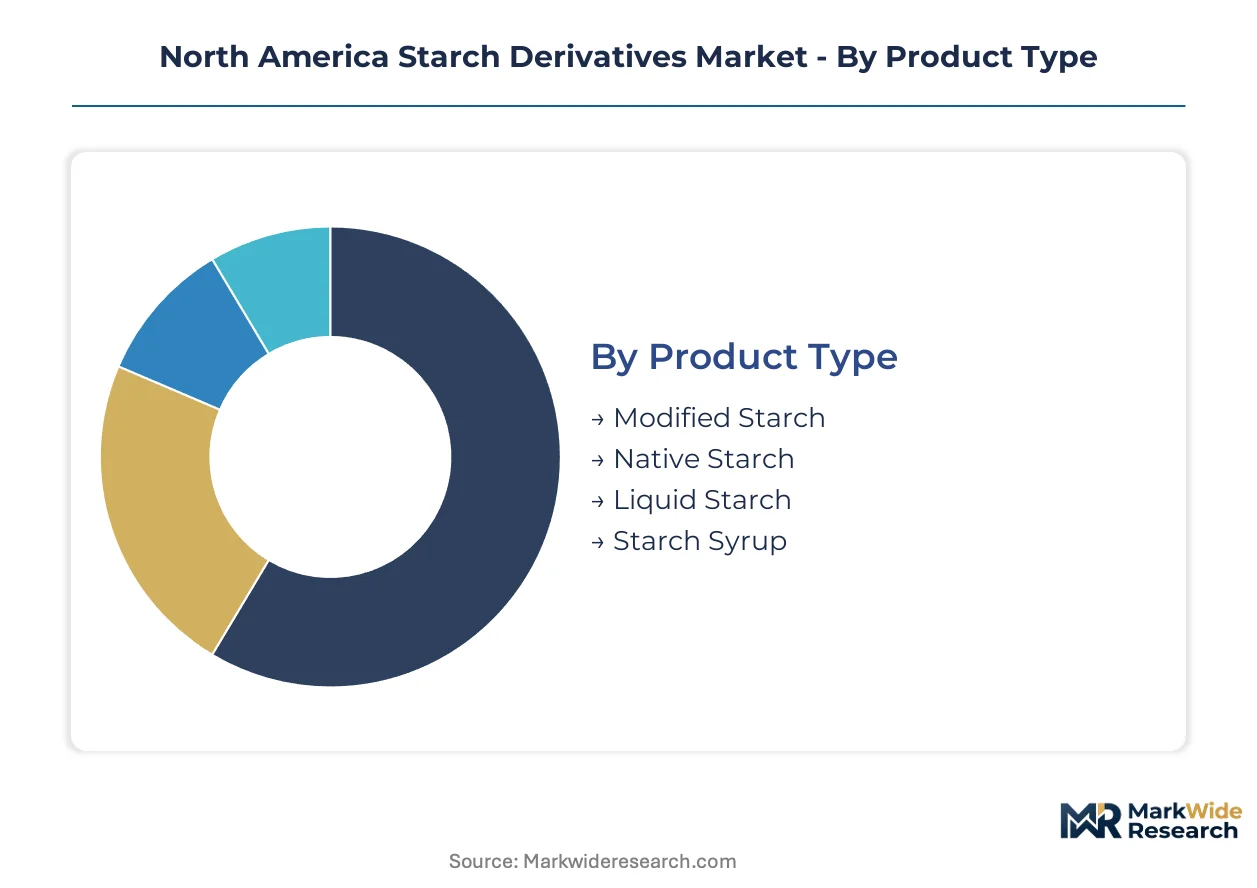
Starch derivative purchasing decisions across North America hinge on functional performance specifications rather than commodity pricing, with formulators prioritizing freeze-thaw stability, viscosity control, and clean-label compliance. Segmentation reveals how supplier technical capabilities align with divergent buyer requirements across food processing, pharmaceutical binding, and industrial sizing applications.
Product Type:
Buyers select product types based on reformulation complexity and end-use performance thresholds, with chemically modified systems commanding premium positioning for demanding applications while native starches penetrate clean-label portfolios.
- Modified Starch:Chemically or enzymatically altered native starches delivering controlled viscosity, film-forming capacity, and freeze-thaw stability. Food manufacturers in the U.S. Midwest rely on these systems for frozen dough applications where thermal cycling resistance remains non-negotiable.
- Native Starch:Unmodified carbohydrate polymers extracted directly from corn, potato, or tapioca sources. Clean-label mandates from major U.S. retailers are accelerating substitution programs in refrigerated pasta and sauce categories.
- Liquid Starch:Pre-hydrated starch dispersions eliminating dry-mix handling steps. Textile sizing operations across Georgia and the Carolinas favor liquid delivery for continuous warp-beam processing.
- Starch Syrup:Hydrolyzed starch solutions ranging from low to high dextrose equivalent values. Confectionery manufacturers in Pennsylvania and Illinois specify these for controlled humectancy and browning reactions.
Modified starch leads on scale; liquid starch leads on momentum.
Application:
Application segmentation tracks how starch functionality maps to processing conditions, with thermal stress, pH extremes, and shelf-life requirements dictating derivative selection.
- Food & Beverage:The dominant consumption channel spanning bakery, dairy, convenience foods, and beverages. FDA dietary fiber labeling updates are redirecting R&D investment toward resistant starch variants in the U.S. West Coast functional food corridor.
- Textiles:Warp sizing, finishing, and printing applications requiring film-forming and adhesive properties. Southeastern U.S. denim and carpet mills are converting from PVA to starch-based sizes to meet wastewater discharge limits.
- Pharmaceuticals:Tablet binders, disintegrants, and capsule fillers. Specialty pregelatinized starches are displacing synthetic binders in generic drug manufacturing facilities across New Jersey and Puerto Rico.
- Cosmetics:Powder absorbency, emulsion stabilization, and rheology modification. Personal care brands in California formulate with modified starches to replace microplastic-based thickeners ahead of state regulatory deadlines.
Food and beverage anchors volume absorption; pharmaceuticals deliver the steepest margin expansion trajectory.
Form:
Physical form selection determines handling economics, hydration kinetics, and dust exposure compliance in processing environments.
- Powder:Free-flowing dried starch with customizable particle size distributions. Large-scale food manufacturers in Illinois and Iowa specify powder for pneumatic conveying systems and automated batching.
- Granules:Agglomerated particles with reduced dusting and improved flow characteristics. Nutraceutical companies in Utah and Colorado prefer granules for direct-compression tableting operations.
- Liquid:Ready-to-use dispersions with defined solids content. Textile mills in North Carolina prioritize liquid form to eliminate pre-cooking steps and reduce energy consumption.
- Flakes:Thin dried sheets requiring extended hydration times. Limited adoption persists in specialty adhesive and papermaking applications across the Great Lakes region.
Powder dominates manufacturing throughput; liquid form gains share fastest in water-stressed processing corridors.
End User:
End user categories reflect divergent procurement sophistication, with technical service intensity scaling from commodity purchasing to collaborative R&D embedding.
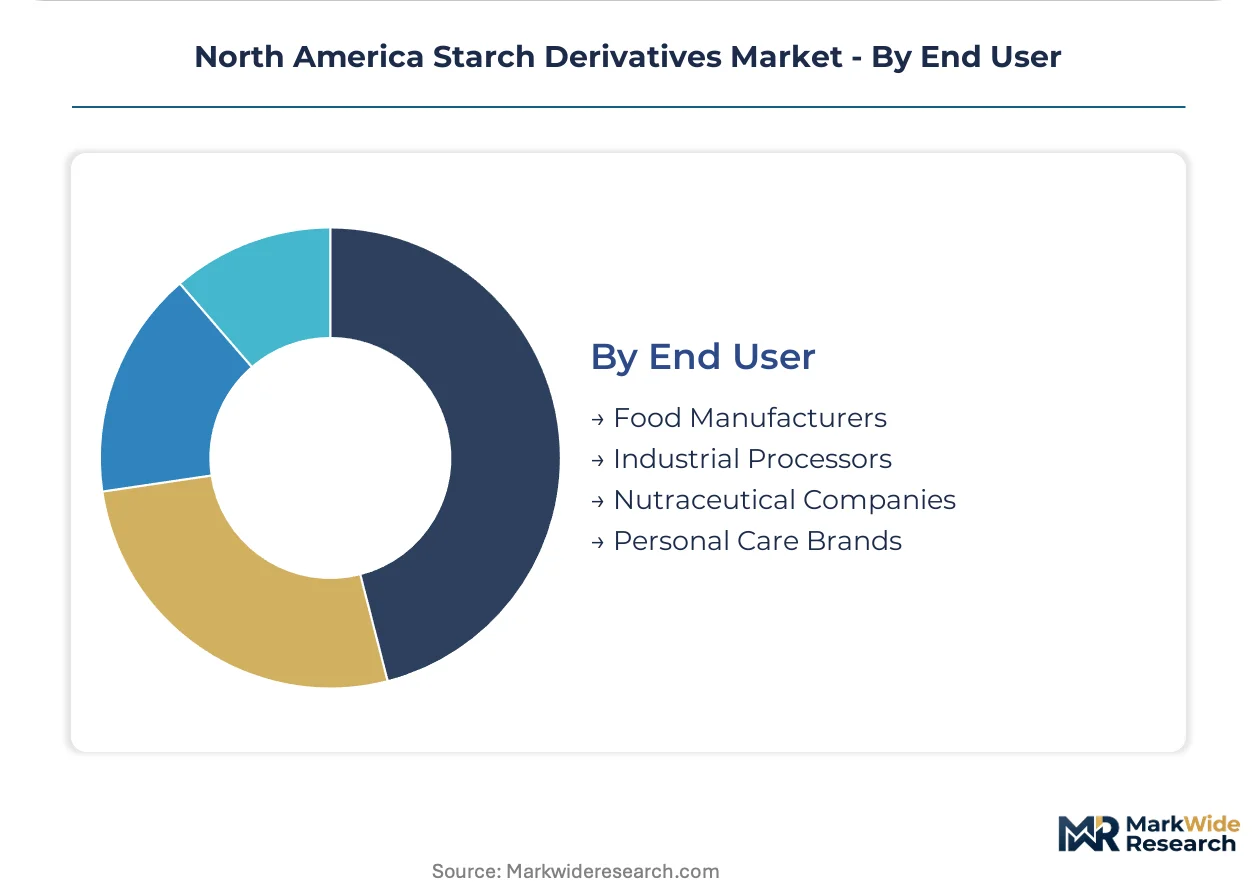
- Food Manufacturers:National bakery, snack, and prepared food companies with centralized R&D functions. Three of the five largest North American food companies now require permanent starch specialist presence at pilot plants.
- Industrial Processors:Textile mills, paper converters, and adhesive compounders. These buyers prioritize freight economics and just-in-time delivery from Midwest corn-processing corridors.
- Nutraceutical Companies:Functional food and dietary supplement producers. West Coast firms face the steepest FDA compliance burden for resistant starch health claim substantiation.
- Personal Care Brands:Cosmetics and hygiene product manufacturers. Clean beauty positioning in California is driving substitution away from petrochemical thickeners toward modified starch systems.
Food manufacturers command the deepest supplier relationships; nutraceutical companies generate the highest technical service revenue per ton.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting starch derivative investment toward jurisdictions with streamlined additive approval pathways and lower wastewater compliance burdens. Production capacity is concentrating where corn-processing infrastructure intersects with permissive environmental permitting.
United States
Frozen dough manufacturers in the U.S. Midwest drive demand for chemically modified starches with freeze-thaw stability. The FDA's evolving guidance on resistant starch dietary fiber classification is reshaping R&D investment priorities. The Decatur, Illinois corn-processing corridor anchors North American derivative output through integrated wet-milling infrastructure.
Canada
Packaged goods manufacturers in Ontario and Quebec are accelerating ingredient substitution programs under clean-label mandates. Health Canada's Food Additive Modernization initiative is compressing approval timelines for novel modified starches. The Great Lakes basin processing corridor faces provincial water-board scrutiny that could elevate capital intensity for capacity expansion.
Mexico
Tortilla and snack producers in Guadalajara and Monterrey represent underpenetrated volume for native starch systems. Mexican regulators are aligning food additive standards with U.S.-Canada frameworks to facilitate cross-border supply chains. The Bajío Region is attracting technical service investment from ingredient suppliers seeking proximity to expanding food manufacturing clusters.
North America Starch Derivatives Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated processors dominating modified starch value pools while regional blenders capture native starch volumes. Three vertically integrated conglomerates control the majority of North American wet-milling capacity, creating supply concentration risk. The competitive terrain separates into three archetypes: corn-origin integrated giants, specialty tapioca/waxy corn sourcing specialists, and regional toll-processing operators. Capacity expansion and backward integration into captive feedstock supply constitute the dominant competitive moves.
Among integrated corn-processors, Archer Daniels Midland Company, Cargill, and Ingredion Incorporated exemplify the scale-driven archetype that defines North American market structure. These entities anchor competitive positioning through control of Midwest wet-milling infrastructure and direct technical service embedding at customer pilot plants. Tate & Lyle and Roquette occupy positions within the specialty derivative tier, representing European-origin players with regional manufacturing footprints.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill |
| Ingredion Incorporated |
| Tate & Lyle |
| Roquette |
| Grain Processing Corporation |
| Primient |
| Agrana Group |
| Beneo |
| Others |
Value Network & Pricing Analysis
Clean-label certification divergence between enzymatically modified and chemically altered starches manifests in both pricing premiums and supply chain sourcing configurations across North American food manufacturing. FDA GRAS notification requirements for novel enzymatic variants create a two-tier procurement landscape where certified clean-label systems command sustained margin advantages while conventional modified starches face commoditization pressure from Midwest corn-processing concentration.
Pricing Analysis
Distributor margin layers absorb 12-18 points between wet-mill gate and end-user formulation facilities across the U.S. Midwest corridor. Three-tier pricing structure across premium, standard, and economy levels tracks functional performance thresholds rather than raw material grades, with freeze-thaw stable variants sustaining premiums despite corn futures volatility. Price differentiation hinges on technical service embedding depth and clean-label certification status. Pricing pressure stems from ethanol policy uncertainty compressing co-product dextrose economics. National bakery chains exhibit lowest price sensitivity due to reformulation switching costs, while regional tortilla manufacturers in Mexico demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Illinois-Iowa wet-milling concentration where three integrated processors control majority North American modified starch capacity. Geographic supply concentration centers on the United States corn belt, with secondary sourcing from Mexican tapioca networks and Canadian prairie wheat starch operations. Raw material dependencies rest on number 2 yellow corn futures, enzyme supply from Danish and Japanese specialty producers, and caustic soda for chemical modification processes. Tariff exposure on Mexican tapioca imports creates supply chain risk for clean-label portfolio diversification. Distribution runs through bulk rail from Decatur and Cedar Rapids to regional blending facilities, with liquid starch delivered via tanker to southeastern textile mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North America starch derivatives function as a stable compounder anchored by irreversible clean-label reformulation mandates across processed food manufacturing. Ingredient substitution cycles create predictable replacement demand even amid corn price volatility.
For Market Incumbents: Hedge margin compression by locking long-term enzyme supply contracts with Novozymes and DuPont Nutrition before clean-label capacity expansion accelerates. Defensive consolidation of regional toll-processing operators in the U.S. Southeast preserves technical service density against emerging Mexican competitors. Capacity addition in water-stressed Great Lakes corridors requires EPA wastewater recovery investment to secure expansion permits.
For New Entrants and Emerging Players: Health Canada's Food Additive Modernization in Ontario and Quebec opens a window for novel modified starch variants with compressed 12-month approval timelines versus 24-month FDA GRAS backlogs. White-space targets include pharmaceutical binder applications in New Jersey-Puerto Rico generic drug manufacturing and native starch penetration of Guadalajara tortilla production. Go-to-market execution should anchor on embedded technical service contracts rather than distributor relationships.
For Investors and Strategic Acquirers: Consolidation pressure builds where three-tier market structure concentrates value capture among integrated wet-mill operators while fragmenting specialty derivative innovation across regional blenders. Long-term viability favors backward-integrated assets with captive corn supply and enzymatic modification capability. Acquisition target archetype: mid-cap enzymatic specialists with Health Canada approval pathways and West Coast nutraceutical customer density. Signal to watch: FDA resistant starch dietary fiber claim finalization triggering R&D capex inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Platform Investment | Clean-label enzymatic systems displace chemical processes in Minneapolis-Chicago food corridor pilot plants. |
| Backward Integration into Waxy Corn Supply | Captive hybrid seed programs reduce input cost volatility for specialty maltodextrin production. |
| EPA Wastewater Recovery Technology Deployment | Clean Water Act compliance unlocks capacity expansion permits in Great Lakes processing corridors. |
| Direct Technical Service Embedding | Permanent starch specialist presence at customer R&D facilities replaces periodic distributor consultation. |
| Health Canada Additive Approval Fast-Track | Accelerated pathways compress commercialization timelines for novel modified starch variants. |
Research Methodology
Bottom-up food manufacturer demand modeling reconciled against top-down wet-milling capacity tracking forms the analytical core of this study. Primary interviews with starch procurement directors at national bakery and snack companies, technical service managers at ingredient suppliers, plant engineers at Midwest wet-milling facilities, and regulatory affairs leads at nutraceutical firms combined with secondary validation from FDA GRAS notification databases, Health Canada food additive registry filings, EPA Clean Water Act permit records, and SEC 10-K disclosures from integrated processors. Triangulation across these sources anchors volume estimates in actual production capacity and confirmed customer substitution programs.
Historical trendline analysis of corn-processing output, modified starch trade flows, and end-use consumption patterns established baseline growth trajectories across the projection horizon. Segmentation modeling incorporated product type functionality tiers, application-specific performance requirements, form factor handling economics, and end-user procurement sophistication levels. CAGRs derived from elasticity-adjusted demand curves responsive to clean-label penetration rates and regulatory approval timeline shifts. Industry-specific forecast inputs included ethanol policy scenario analysis and enzymatic platform adoption curves in frozen prepared food manufacturing.
Revisions become necessary when FDA resistant starch health claim guidance finalizes, EPA regional water-board rulings alter Great Lakes processing economics, or Mexican regulatory alignment with U.S.-Canada frameworks accelerates cross-border supply chain integration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global 2-Methylpropene Market
Bulk Chemicals
Refined Wax Market
Bulk Chemicals
Global Fermentation Chemicals Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Bulk Ingredients Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Global Ethylene Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Global Vanadium Pentoxide Market
Bulk Chemicals
United Kingdom Lime Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Diisopropylbenzene Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Global Basic Chemicals Market