
 Polyphenylene Oxide (PPO) Market | 2026-2036
Polyphenylene Oxide (PPO) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyphenylene Oxide (PPO) Market Analytics
A capital-intensity divergence between integrated resin producers and compound specialists is reorganizing competitive dynamics in the PPO landscape. Asahi Kasei Chemicals Corporation leverages captive phenol-to-PPO integration across its Japanese manufacturing footprint. SABIC sustains cost advantages through feedstock access at its Saudi Arabian petrochemical complexes. Mitsubishi Chemical Corporation specializes in high-purity grades for semiconductor-grade applications, occupying a defensible niche above commodity blends.
Polyphenylene oxide is an amorphous thermoplastic characterized by a glass transition temperature near 210°C and inherent flame resistance without halogenated additives, produced primarily through oxidative coupling polymerization of 2,6-dimethylphenol. The material serves critical functions where dimensional stability under thermal load and dielectric performance are non-negotiable, particularly in electrical connectors and fluid handling systems. PPO blends dominate volume consumption due to processability improvements over neat resin, while copolymer formulations command premium positioning in medical device housings where sterilization resistance is mandatory. The automotive end-use segment leads absolute consumption, though electronics applications for 5G infrastructure components represent the fastest-expanding margin pool.
EPA regulations on persistent organic pollutants constrain legacy additive packages in North American PPO formulations, while REACH restrictions on halogenated flame retardants in Europe redirect R&D toward phosphorus-based alternatives. China's SAMR enforces GB standards for electrical appliance safety that elevate material tracking requirements across the supply chain. Japan's METI circular economy guidelines pressure producers to demonstrate recyclability pathways for engineering thermoplastics. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation fragmentation that erodes economies of scale.
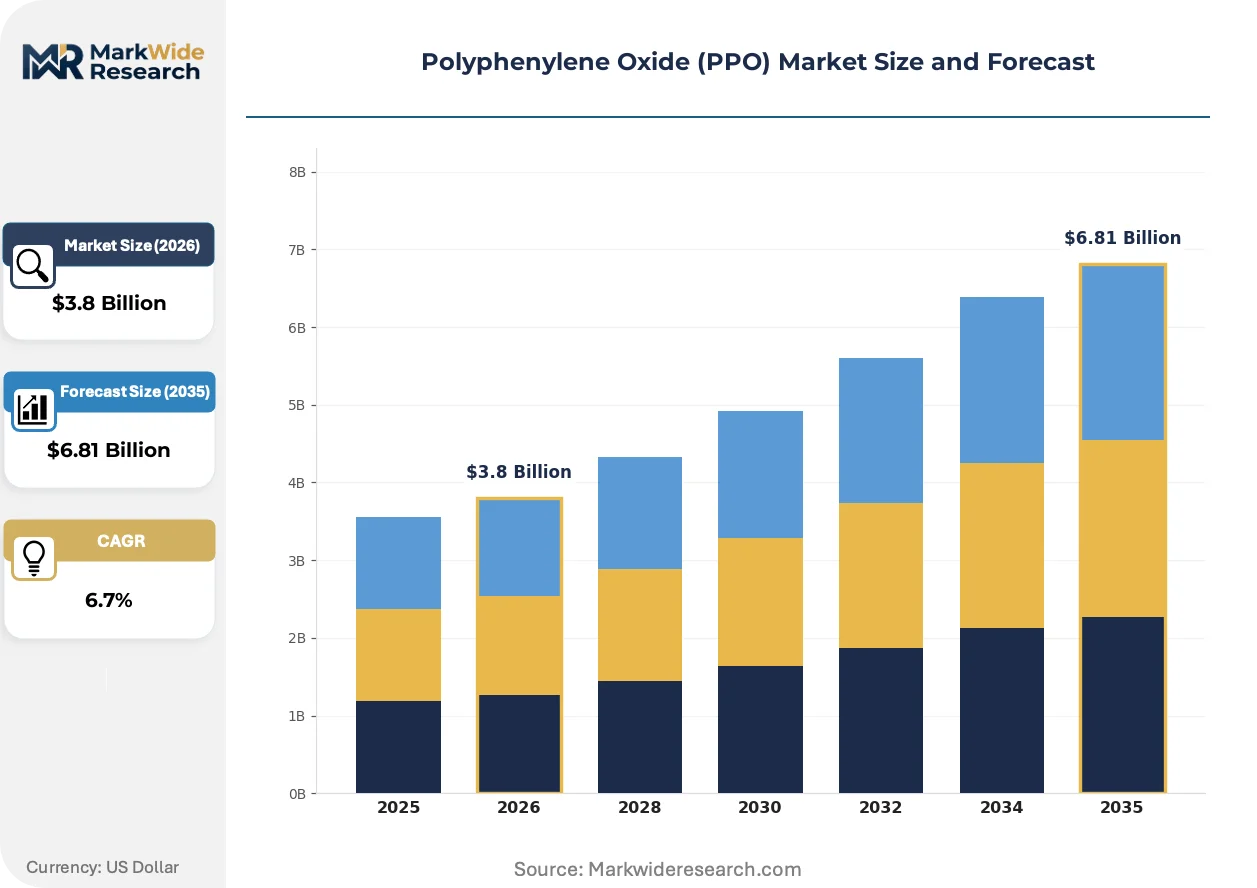
Market Dynamics
Automotive electrification and 5G infrastructure deployment are compressing qualification timelines for high-heat thermoplastics, forcing compounders to accelerate validation cycles for under-hood and base-station applications.
Growth Catalysts
- REACH flame-retardant restrictions:Phosphorus-based alternatives to halogenated additives are unlocking premium positioning for PPO grades in European electrical housings. Compounders with certified formulations capture margin pools unavailable to legacy suppliers.
- China's Yangtze River Delta:Concentrated electronics manufacturing is absorbing specialized PPO blends for connector and relay production. Local compounders benefit from just-in-time feedstock access.
- Oxidative coupling polymerization advances:Process intensification at phenol-to-resin integrated sites is reducing unit conversion costs. Captive producers extend cost advantages over non-integrated competitors.
Market Restraints
- Phenol feedstock volatility:Crude-linked aromatics pricing transmits directly to PPO resin economics, compressing margins for non-integrated compounders during upstream cost spikes.
- Japanese supply concentration:Three integrated producers control majority of high-purity semiconductor-grade capacity, creating bottleneck risk for electronics supply chains.
- Polycarbonate substitution:Lower-cost transparent grades displace PPO in non-critical electrical enclosures where thermal performance requirements relax.
Strategic Opportunities
- India's PLI scheme for electronics:Domestic mobile and component manufacturing incentives are creating virgin demand for flame-retardant engineering thermoplastics.
- Medical device sterilization resistance:Copolymer PPO formulations for autoclave and gamma-irradiation cycles address unmet need in surgical instrument housings.
- Closed-loop recycling pathways:Japan's METI circular economy guidelines reward demonstrated recyclability, opening preferential procurement channels for certified producers.
Industry Challenges
- Multi-jurisdiction formulation fragmentation:Divergent EPA, REACH, and GB standards on additive packages force parallel product lines, eroding scale economies.
- Semiconductor-grade purification capex:Ion-exchange and crystallization infrastructure for electronic-grade resin demands dedicated investment with long payback periods.
- 5G qualification timelines:Dielectric constant and dissipation factor certification for base-station components extends development cycles beyond traditional automotive approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyphenylene Oxide (PPO) Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resin, Copolymer, Blends, Compounds End Use Industry: Automotive, Electronics, Aerospace, Healthcare Form: Granules, Sheets, Films, Powders Application: Insulators, Connectors, Pipes, Housing |
| Companies Covered | Asahi Kasei Chemicals Corporation, Sumitomo Chemical Co., Ltd, SABIC, LyondellBasell Industries, Mitsubishi Chemical Corporation, BASF SE, Celanese Corporation, LG Chem, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyphenylene Oxide (PPO) Market Evolving Landscape
Formulation science and regulatory chemistry are converging to redefine competitive advantage in engineering thermoplastics, with sustainability credentials and electrical performance becoming inseparable selection criteria.
Phosphorus-nitrogen synergist systems are fragmenting legacy halogenated flame-retardant architectures in electrical connector applications. Tier-1 automotive suppliers in Germany and Japan are mandating halogen-free bill-of-materials for new platform introductions. The technology is fragmenting supplier tiers, separating compounders with certified formulations from those dependent on obsolete additive packages.
REACH authorization requirements for persistent organic pollutants are accelerating R&D redirection toward non-halogenated alternatives in European electrical appliance markets. Compounders must reformulate legacy grades or surrender market access. Appliance OEMs in Italy and Poland are consolidating supplier bases around REACH-compliant resin sources.
Consolidated procurement by automotive Tier-1s is compressing compounder margins and transferring inventory risk downstream. Single-source agreements with SABIC and Asahi Kasei are displacing fragmented multi-supplier arrangements. The pattern is most visible in German and Japanese automotive supply chains, where platform standardization favors volume commitments over spot purchasing.
Polyphenylene Oxide (PPO) Market Segmentation
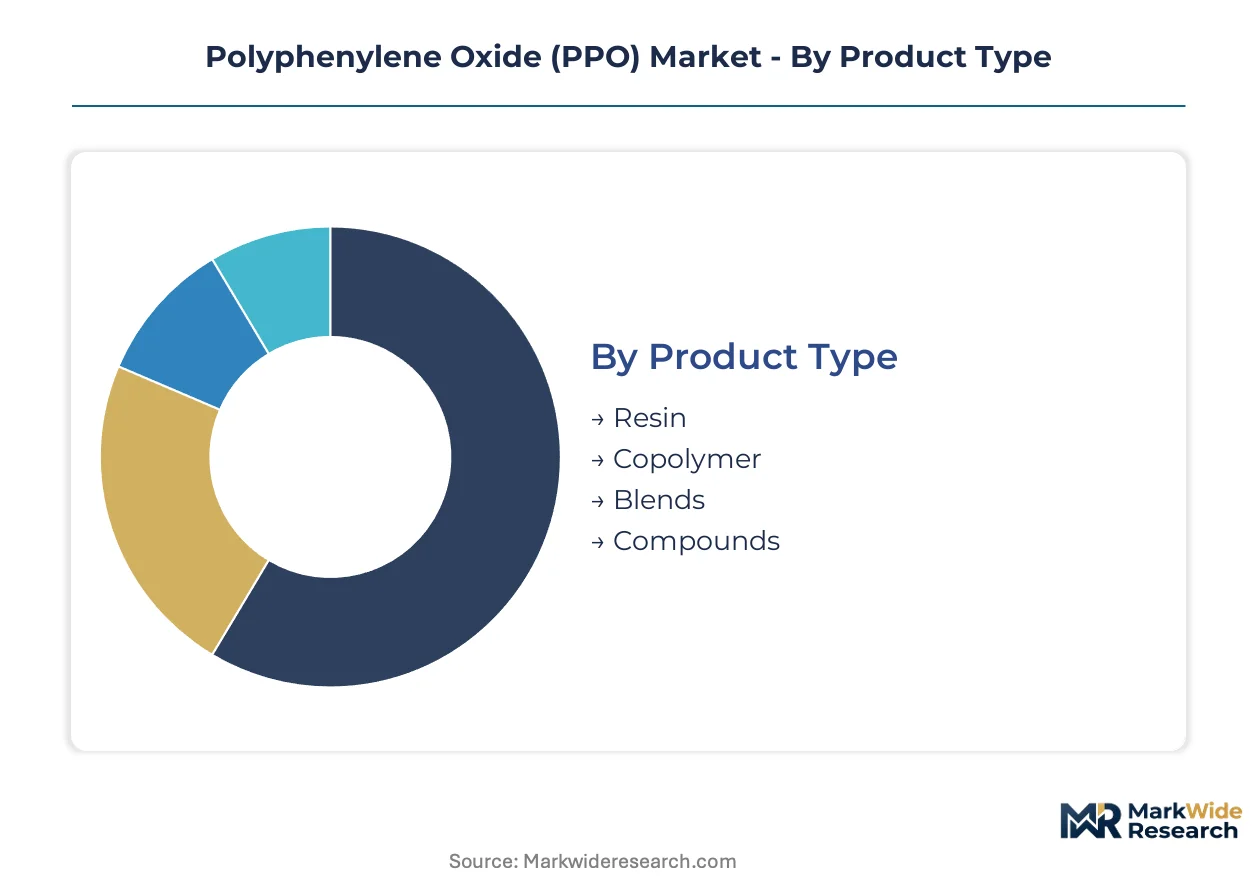
PPO segmentation reveals divergent margin structures across material grades and conversion formats. Automotive electrification and 5G infrastructure are compressing qualification timelines unevenly across product categories, reshaping where compounders capture value.
Product Type:
Margin pools concentrate in high-purity grades where semiconductor and medical device certification creates pricing power, while commodity blends compete on scale and feedstock integration.
- Resin:Neat PPO resin produced through oxidative coupling polymerization delivers the highest thermal performance with glass transition temperatures near 210°C. Demand concentrates in Japan and Germany for semiconductor-grade applications where ion-exchange purification infrastructure limits supply. Japanese integrated producers control majority capacity, creating bottleneck risk for electronics supply chains.
- Copolymer:Modified PPO copolymers incorporate styrenic or other monomer units to enhance processability and chemical resistance. Medical device manufacturers in Germany and Japan specify these grades for autoclave and gamma-irradiation sterilization cycles, commanding premium positioning above commodity blends.
- Blends:PPO-polystyrene and PPO-polyamide alloys dominate volume consumption through improved melt flow characteristics.
- Compounds:Custom-formulated grades with tailored additive packages serve specific electrical and flame-retardant specifications.
Resin holds installed capacity. Copolymer is rotating up the share rankings.
End Use Industry:
Application-driven segmentation shows automotive consuming absolute volume while electronics generates fastest margin expansion through dielectric performance requirements.
- Automotive:Under-hood electrical components, battery housings, and thermal management systems absorb specialized PPO grades. China's Yangtze River Delta manufacturing corridor and German Tier-1 suppliers are accelerating adoption for electric vehicle platforms where flame resistance and dimensional stability under thermal load are non-negotiable.
- Electronics:5G base-station components, high-frequency connectors, and relay housings demand low dielectric constant and dissipation factor certification. Extended qualification timelines beyond traditional automotive approvals compress development cycles for compounders serving this segment.
- Aerospace:Interior components and electrical systems specify PPO for flame-retardant properties without halogenated additives.
- Healthcare:Surgical instrument housings and sterilization-resistant device components utilize copolymer formulations.
Automotive maintains volume leadership. Electronics is climbing the fastest through infrastructure deployment.
Form:
Conversion format determines supply chain configuration, with granules enabling just-in-time compounding and films serving specialized membrane applications.
- Granules:Standard pellet form facilitates extrusion and injection molding across automotive and electronics applications. Compounders in China's Yangtze River Delta benefit from localized feedstock access for connector and relay production.
- Films:Thin-gauge PPO films serve dielectric and separation membrane functions in battery and electronic applications. Processing complexity limits producers with biaxial orientation capability.
- Sheets:Thick-gauge extruded products address structural and electrical insulation requirements.
- Powders:Fine particle grades enable compression molding and coating applications.
Granules dominate shipment volumes. Films is gaining share fastest through battery separator demand.
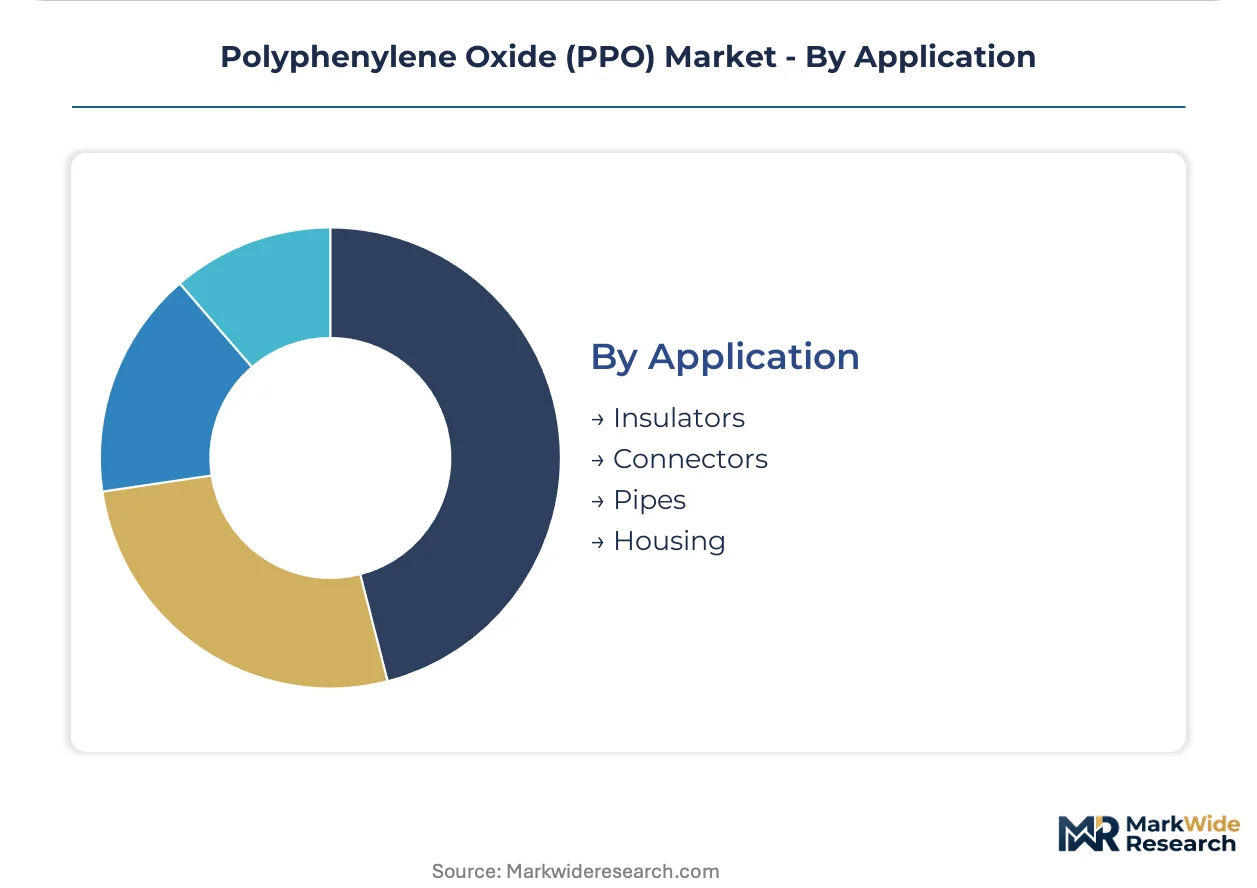
Application:
Functional segmentation separates commodity electrical enclosures from performance-critical components where material selection locks in platform designs.
- Connectors:High-density electrical connectors for automotive and 5G infrastructure require precise dielectric properties and dimensional stability. REACH flame-retardant restrictions in Europe are redirecting formulation toward phosphorus-based alternatives, fragmenting supplier tiers between certified and legacy compounders.
- Housing:Enclosures for electrical appliances, medical devices, and automotive components balance flame resistance with processability. EPA regulations on persistent organic pollutants in North America and GB standards in China force parallel product lines, eroding scale economies for multi-jurisdiction suppliers.
- Insulators:High-voltage electrical insulation leverages PPO's inherent dielectric strength and thermal resistance.
- Pipes:Fluid handling systems utilize dimensional stability and chemical resistance for industrial applications.
Connectors command formulation premiums. Housing is rotating up the share rankings through appliance safety standard tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese producers command pricing power in semiconductor-grade resin while Chinese compounders compete on scale for automotive blends. German automotive electrification and India's electronics manufacturing incentives are reshaping regional demand patterns. Regulatory divergence between EPA, REACH, and GB standards fragments formulation strategies across jurisdictions.
China
Electronics manufacturing in the Yangtze River Delta absorbs specialized PPO blends for connector and relay production. SAMR enforces GB standards for electrical appliance safety that elevate material tracking requirements across supply chains. Local compounders in Jiangsu and Zhejiang provinces benefit from just-in-time feedstock access to serve automotive Tier-1 suppliers.
Japan
Integrated phenol-to-PPO producers dominate high-purity semiconductor-grade capacity through oxidative coupling polymerization infrastructure. METI circular economy guidelines pressure producers to demonstrate recyclability pathways for engineering thermoplastics. Kanto and Kansai industrial corridors concentrate electronics-grade resin purification and medical device copolymer formulation.
Germany
Automotive electrification accelerates qualification timelines for under-hood electrical components and battery thermal management systems. REACH restrictions on halogenated flame retardants redirect R&D toward phosphorus-based alternatives in European electrical housings. Bavaria and Baden-Württemberg host Tier-1 suppliers consolidating procurement around REACH-compliant resin sources.
United States
5G infrastructure deployment drives dielectric performance requirements for base-station components and high-frequency connectors. EPA regulations on persistent organic pollutants constrain legacy additive packages in North American formulations. Texas and Michigan manufacturing corridors absorb specialized compounds for automotive under-hood applications.
India
Domestic mobile and component manufacturing incentives under the PLI scheme create virgin demand for flame-retardant engineering thermoplastics. BIS standards for electrical safety equipment tighten material certification requirements. Maharashtra and Karnataka electronics manufacturing clusters attract compounders seeking proximity to assembly operations.
Polyphenylene Oxide (PPO) Market Competitive Landscape
Concentration sits with integrated petrochemical conglomerates possessing captive phenol feedstock access. Three Japanese producers control majority semiconductor-grade capacity while Saudi and European majors compete on scale for automotive blends. Strategic archetypes separate captive resin producers from compound specialists and regional blenders. Dominant competitive moves include oxidative coupling polymerization process intensification and REACH-compliant formulation certification.
Among integrated resin producers, Asahi Kasei Chemicals Corporation, SABIC, and Mitsubishi Chemical Corporation exemplify divergent positioning strategies. Asahi Kasei represents captive phenol-to-PPO integration across Japanese manufacturing footprints. SABIC anchors cost advantages through feedstock access at Saudi Arabian petrochemical complexes. Mitsubishi Chemical occupies a defensible niche in high-purity grades for semiconductor applications above commodity blend competition.
| Leading Market Players |
|---|
| Asahi Kasei Chemicals Corporation |
| Sumitomo Chemical Co., Ltd |
| SABIC |
| LyondellBasell Industries |
| Mitsubishi Chemical Corporation |
| BASF SE |
| Celanese Corporation |
| LG Chem |
| Solvay |
| Others |
Value Network & Pricing Analysis
REACH flame-retardant authorization requirements gate both supplier qualification and price differentiation simultaneously, separating compounders with certified phosphorus-based formulations from legacy halogenated suppliers locked out of European electrical housing markets. This regulatory sieve concentrates pricing power among certified producers while fragmenting procurement options for multi-jurisdiction OEMs.
Pricing Analysis
Configured-to-order pricing for semiconductor-grade resin commands substantial premiums over standard automotive blend quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by purity grade and certification tier, with ion-exchange purification infrastructure limiting supply of electronic-grade material. Cost compression in commodity blends is intensifying because polycarbonate substitution erodes non-critical electrical enclosure demand. Automotive Tier-1 suppliers exhibit lowest price sensitivity due to platform standardization, while appliance OEMs in emerging manufacturing clusters face acute budget constraints.
Supply Chain Analysis
Phenol feedstock transit through the Strait of Hormuz underwrites cost volatility for non-integrated compounders dependent on aromatics pricing. Production concentrates in Japan, Saudi Arabia, and Germany, with Japanese integrated producers controlling majority high-purity semiconductor-grade capacity. Supply chains draw from 2,6-dimethylphenol monomer, styrenic modifiers, and phosphorus-nitrogen flame-retardant synergists. Single-source vulnerability runs through Japanese electronics-grade purification infrastructure. Distribution runs through direct long-term offtake agreements with automotive Tier-1s and spot purchasing for appliance OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification and 5G infrastructure deployment signal early-cycle expansion, with virgin demand creation outpacing substitution effects in flame-retardant engineering thermoplastics.
For Market Incumbents: Compound backward integration into captive phenol feedstock to defend margin position against aromatics volatility. Prioritize REACH-compliant formulation certification to lock out legacy competitors from European electrical housing procurement. Extend oxidative coupling polymerization process intensification at integrated Japanese and Saudi sites to widen cost advantages over non-integrated compounders. For New Entrants and Emerging Players: Lead with medical device sterilization resistance as the most penetrable white-space target, where copolymer formulation expertise commands premium positioning above commodity blend competition. Target India's PLI-supported electronics manufacturing clusters with localized compounding capacity for connector and relay production. Pursue joint development agreements with surgical instrument OEMs seeking gamma-irradiation certified housings. For Investors and Strategic Acquirers: Japan's METI circular economy guidelines reshape the acquisition landscape by rewarding demonstrated recyclability pathways with preferential procurement channels. Frame long-term viability around engineering thermoplastic consolidation plays with certification moats in semiconductor-grade purification or REACH-compliant additive packages. Watch phosphorus-based flame-retardant patent filings as the signal indicating formulation leadership transitions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstock | Captive aromatics supply insulates SABIC and Asahi Kasei from crude-linked cost spikes. |
| REACH-Compliant Formulation Certification | Phosphorus-based additive packages unlock European electrical housing markets for certified compounders. |
| Medical Device Copolymer Development | Autoclave and gamma-irradiation resistance commands premium positioning in surgical instrument housings. |
| India PLI Manufacturing Footprint | Jiangsu and Zhejiang compounders gain proximity to Maharashtra and Karnataka electronics clusters. |
| Closed-Loop Recycling Pathway Demonstration | METI guidelines reward certified producers with preferential procurement from Japanese OEMs. |
Research Methodology
The analysis maps resin, copolymer, blend, and compound sub-sectors, each validated through technical R&D directors at integrated producers, procurement leads at automotive Tier-1 suppliers, and distribution channel partners across Asian manufacturing corridors. Primary interviews with plant managers and downstream OEM sourcing teams combined with customs/trade data, ACC and Cefic industry reports, and SEC 10-K filings provided demand-side triangulation. Bottom-up capacity modeling and top-down consumption estimates converged through iterative stakeholder validation.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled grade tier, end-use industry, conversion format, and regional production hub segmentation dimensions. CAGRs derived from historical trajectory analysis and adoption curve penetration rates incorporated automotive electrification content-per-vehicle assumptions and 5G base-station deployment timelines as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained phenol feedstock availability, REACH authorization timelines, or semiconductor capital expenditure cycles would require recalibration. Forecasts reflect documented assumptions about regulatory stability and substitution elasticity. Practitioners should keep alternative scenarios live as polycarbonate thermal performance improvements and biobased engineering thermoplastic scale-up evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Polymeric Sand Market
Polymers & Resins
Global Unplasticized Polyvinyl Chloride (UPVC) Windows Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Biopolymer Tubes Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Europe Polyurethane Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Renewable Polyethylene Market