
 Europe Polymer Emulsion Market | 2026-2036
Europe Polymer Emulsion Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polymer Emulsion Market Analysis
German specialty chemical producers is expanding waterborne polymer emulsion capacity to serve automotive OEM coating lines migrating from solvent systems. BASF SE anchors its European position through backward integration into acrylic monomer supply and captive R&D on low-VOC binder platforms. Wacker Chemie AG specializes in vinyl acetate ethylene emulsions for construction adhesives, leveraging its Burghausen manufacturing complex to sustain just-in-time delivery across Central European building markets. Synthomer competes on styrene-butadiene latex scale, operating polymerization trains that supply paper coating mills in Scandinavia and the Benelux.
Europe polymer emulsion denotes a colloidal dispersion of synthetic polymer particles, typically 50-500 nanometers in diameter, stabilized by surfactants in a continuous aqueous phase and manufactured through batch or semi-batch emulsion polymerization at 60-90 degrees Celsius. These systems function as film-forming binders that replace solvent-based resins in surface coatings, adhesives, and nonwoven binders while reducing volatile organic compound emissions. Acrylic emulsions lead product type demand due to their exterior durability and ultraviolet resistance in architectural coatings, while vinyl acetate ethylene grades capture growth in flexible packaging adhesives where cold-seal performance and food-contact compliance matter. Paints and coatings applications concentrate the largest value pool, though construction chemicals represent the fastest-expanding application as cement modifier and waterproofing formulations shift to polymer-modified systems.
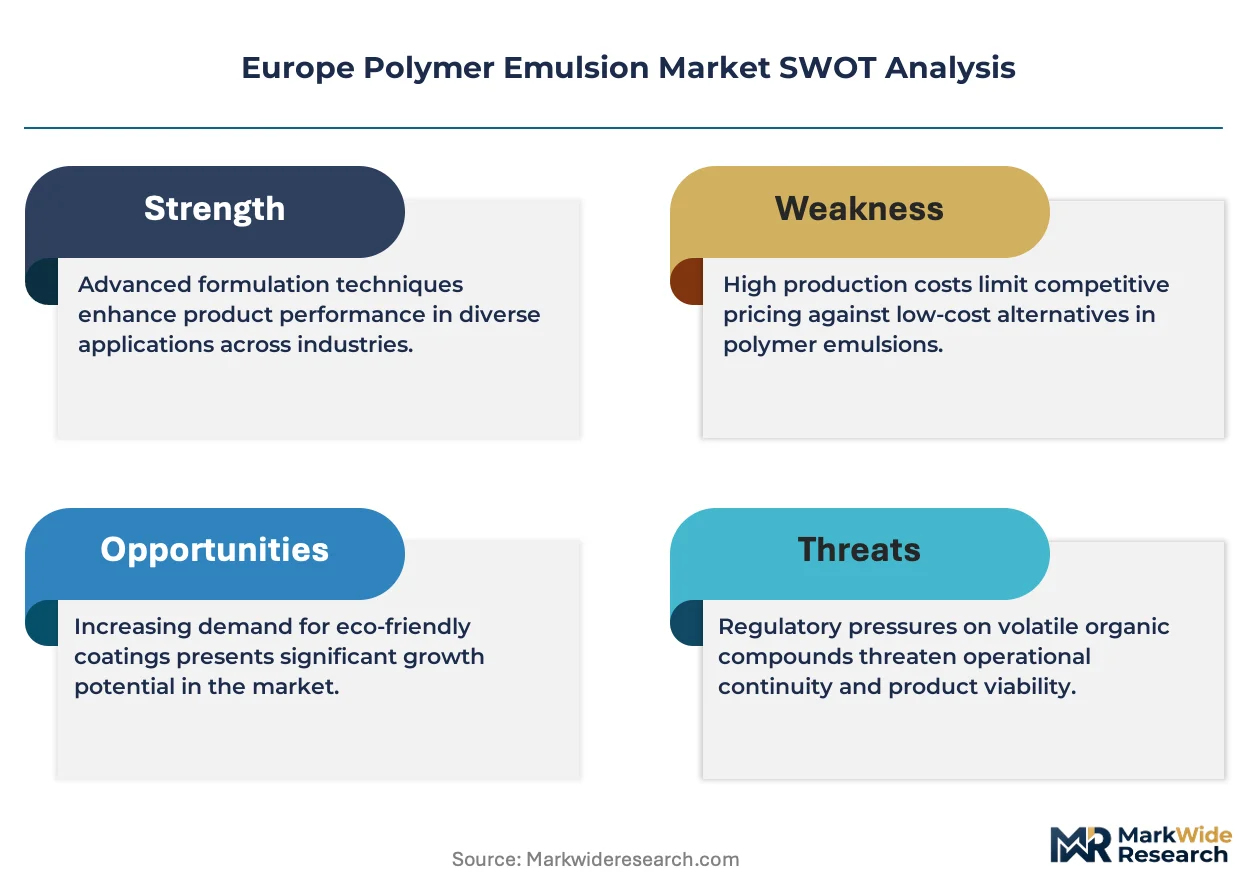
REACH registration requirements govern monomer and surfactant inputs, compelling reformulation of legacy emulsions containing hazardous classification substances. The EU Green Deal's industrial emissions directive and F-Gas Regulation on fluorinated compounds shape product development priorities, pushing manufacturers toward bio-based stabilizers and post-consumer recycled content integration. ECHA substance evaluation cycles determine market access timelines for novel polymer chemistries. Stakeholders must monitor the interplay between France's national low-carbon building standard and Germany's federal emission control ordinance, as divergent implementation timelines will fragment specification requirements across the continent's largest consuming markets.
Market Dynamics
The EU Green Deal's tightening volatile organic compound limits are forcing a system-wide migration from solvent-based coatings to waterborne polymer emulsion platforms across European manufacturing.
Growth Catalysts
- REACH registration mandates:Legacy emulsion reformulation requirements under ECHA substance evaluation cycles are accelerating demand for compliant low-hazard binder chemistries in architectural coatings.
- Automotive OEM conversion:German vehicle manufacturers are converting solvent-based paint shops to waterborne systems to meet federal emission control ordinance specifications.
- Cement modification surge:Construction chemical formulators are integrating polymer emulsions into waterproofing and repair mortars to satisfy France's national low-carbon building standard.
Market Restraints
- Acrylic monomer supply concentration:Backward-integrated producers control key feedstock access, limiting margin flexibility for non-integrated compounders in Central Europe.
- Cold-weather performance gaps:Vinyl acetate ethylene emulsions exhibit reduced film formation below five degrees Celsius, restricting exterior construction applications in Nordic climates.
- Fluorinated compound phase-out:The EU F-Gas Regulation is eliminating certain high-performance stabilizer chemistries, forcing costly reformulation of specialty grades.
Strategic Opportunities
- Polish construction expansion:Infrastructure investment corridors in Central Eastern Europe present untapped demand for tile adhesives and exterior insulation finish systems.
- Bio-based stabilizer convergence:Integration of post-consumer recycled content with bio-surfactant platforms opens premium positioning against conventional petroleum-derived emulsions.
- Food-contact compliance tailwind:EFSA migration limit updates for cold-seal packaging adhesives favor vinyl acetate ethylene grades with established safety dossiers.
Industry Challenges
- Emulsion polymerization scale-up complexity:Batch-to-semi-batch process transfers require specialized reactor engineering talent scarce in regional technical institutes.
- Dual certification timelines:Simultaneous REACH registration and CE marking for construction products extends market entry cycles by eighteen to twenty-four months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polymer Emulsion Market |
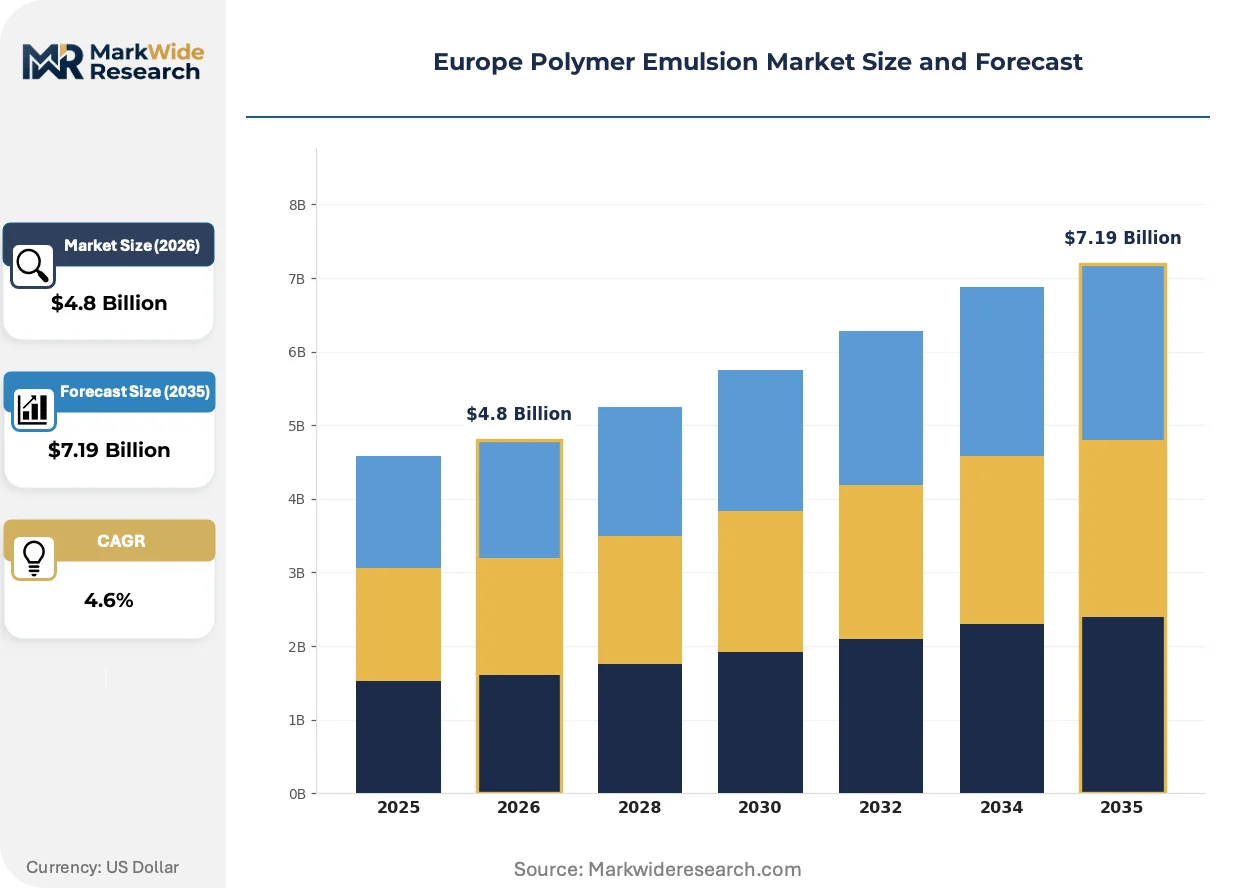
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene-Butadiene, Vinyl Acetate Ethylene, Acrylic, Polyvinyl Acetate, Butadiene-Styrene Application: Adhesives, Paints & Coatings, Textile Finishing, Paper Coating, Construction Chemicals End User Industry: Packaging Providers, Personal Care Manufacturers, Electronics Assemblers, Automotive Suppliers, Marine Fabricators Form: Latex, Powder, Bulk, Emulsion, Dispersion |
| Companies Covered | Wacker Chemie AG, Clariant, BASF SE, Allnex Netherlands B.V., Synthomer, Dow, Akzo Nobel N.V., 3M, Arkema Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polymer Emulsion Market Emerging Trajectories
European polymer emulsion development is pivoting toward performance differentiation through molecular architecture control and regulatory-anticipatory formulation design.
Hybrid acrylic-polyurethane dispersion technology is decentralizing the architectural coatings value chain by enabling single-component systems that match two-component solventborne durability. Regional paint manufacturers in Italy and Spain are adopting these platforms to bypass reliance on multinational supply chains for specialty isocyanate crosslinkers. The technology is decentralizing formulation autonomy toward mid-tier producers previously locked out of high-performance segments.
The EU Green Deal's industrial emissions directive is compressing allowable solvent content in coating operations to sub-five-percent thresholds. German automotive suppliers are retrofitting paint lines with forced-air drying systems compatible with slower-curing waterborne films. Decorative coatings across Benelux markets face parallel pressure as municipal procurement rules embed lifecycle carbon scoring.
Buyer concentration among pan-European building material distributors is compressing supplier negotiation cycles and demanding just-in-time inventory guarantees. Specialty emulsion producers are responding with regional satellite blending facilities in Poland and Romania to bypass logistics bottlenecks. Construction chemical verticals exhibit the most visible procurement consolidation, with three distributors controlling sixty percent of waterproofing formulation sales in France and Germany.
Europe Polymer Emulsion Market Segmentation
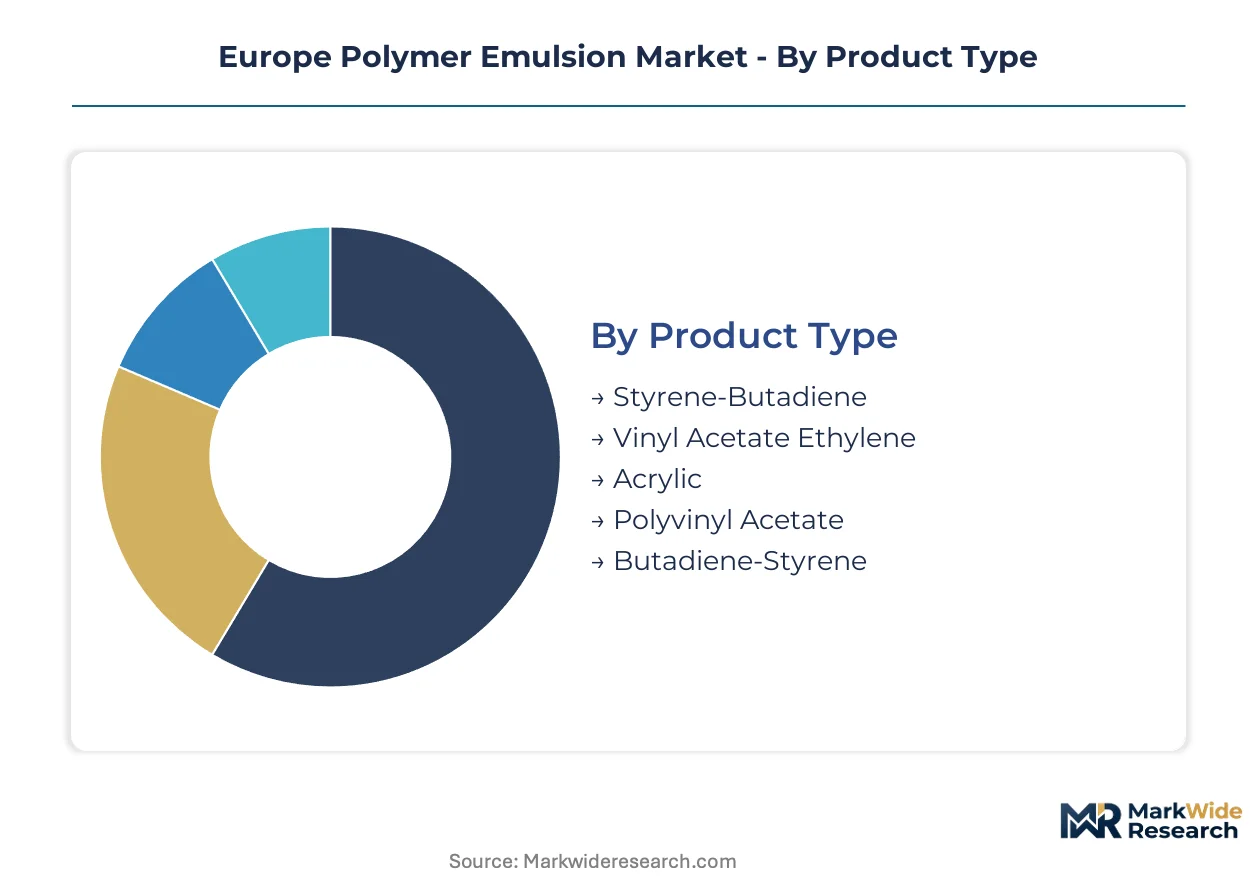
European polymer emulsion procurement hinges on matching binder chemistry to end-use performance specifications and regulatory compliance tiers. Formulators select product types based on film formation temperature, VOC content limits, and durability requirements dictated by application environment.
Product Type:
Buyers prioritize weatherability, adhesion strength, and food-contact approval when selecting polymer chemistry for specific coating or adhesive formulations.
- Acrylic:UV-stable copolymers of methyl methacrylate and butyl acrylate deliver exterior durability for architectural facades. German automotive OEMs specify acrylic dispersions for basecoat layers to meet federal emission control ordinance limits on solvent content.
- Vinyl Acetate Ethylene:Flexible copolymers with ethylene segments provide cold-seal activation for food packaging. Scandinavian paper mills specify VAE grades for barrier coatings where EFSA migration limits govern direct food contact.
- Styrene-Butadiene:Carboxylated latex binders for carpet backing and paper saturation. Benelux packaging converters favor SB latex for cost-sensitive adhesive applications.
- Polyvinyl Acetate:Homopolymer emulsions for woodworking adhesives and primer sealers. Italian furniture manufacturers specify PVA for interior joinery where moisture resistance requirements are moderate.
- Butadiene-Styrene:High-styrene content variants for tire cord dipping and textile sizing. French tire producers utilize BS latex for fabric reinforcement in passenger vehicle tires.
Acrylic leads on scale; Vinyl Acetate Ethylene leads on momentum.
Application:
Volume concentration varies sharply by formulation complexity and regulatory scrutiny intensity across end-use sectors.
- Paints & Coatings:Architectural and industrial finishes consume the largest emulsion volumes. Spanish decorative paint producers are converting solvent-based alkyd lines to waterborne acrylic platforms under municipal procurement carbon scoring rules.
- Construction Chemicals:Cement modifiers, waterproofing membranes, and tile adhesives represent the steepest expansion trajectory. French formulators integrate polymer emulsions into repair mortars to satisfy national low-carbon building standard specifications.
- Adhesives:Pressure-sensitive, laminating, and assembly bonding applications. German packaging converters specify VAE emulsions for flexible film lamination where cold-seal performance is critical.
- Paper Coating:Binder systems for glossy publication papers and packaging boards. Finnish paper mills rely on styrene-butadiene latex for coated mechanical papers targeting magazine printing.
- Textile Finishing:Nonwoven binders and fabric coatings. Italian technical textile producers apply acrylic emulsions for outdoor upholstery requiring mildew resistance.
Paints & Coatings dominates volume; Construction Chemicals climbs the fastest.
End User Industry:
Procurement sophistication ranges from commodity spot purchasing to collaborative specification development with captive technical service requirements.
- Automotive Suppliers:Tier-1 coating applicators demand just-in-time delivery and color-matching precision. German paint shops specify waterborne basecoats to comply with federal emission control ordinance solvent limits.
- Packaging Providers:Flexible film converters and rigid container manufacturers prioritize food-contact compliance and seal integrity. Dutch cold-seal adhesive formulators favor VAE emulsions with established EFSA safety dossiers.
- Construction Chemicals Formulators:Waterproofing and tile adhesive producers require consistent viscosity and freeze-thaw stability. Polish distributors are consolidating procurement of cement modifier emulsions for infrastructure investment corridors.
- Personal Care Manufacturers:Hair styling and sunscreen formulators utilize film-forming polymer dispersions. French cosmetic laboratories specify acrylic copolymers for hairspray applications where VOC regulations are tightening.
- Electronics Assemblers:Conformal coatings and potting compounds for circuit board protection. Romanian electronics manufacturing services specify polyurethane-acrylic hybrids for moisture barrier properties.
- Marine Fabricators:Anticorrosion primers and topcoats for vessel construction. Norwegian shipyards specify epoxy-acrylic emulsion systems for ballast tank coatings under IMO PSPC regulations.
Automotive Suppliers anchor procurement scale; Packaging Providers drive specification innovation.
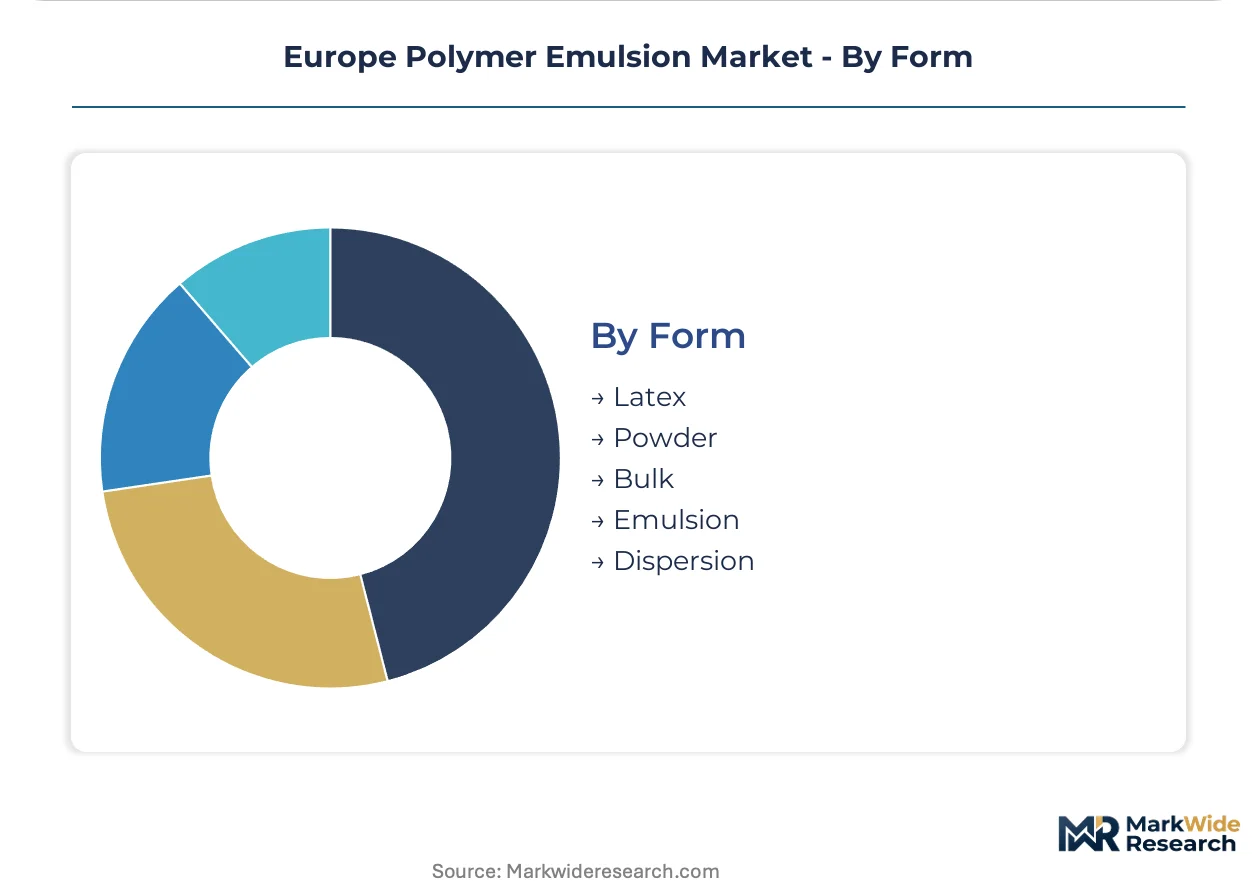
Form:
Physical state selection balances logistics economics, storage stability, and reconstitution requirements at point of use.
- Emulsion:Aqueous colloidal dispersions at 40-60% solids represent the standard delivery format. German construction chemical distributors maintain regional satellite blending facilities for just-in-time emulsion supply.
- Latex:High-solids natural or synthetic rubber dispersions for dipped goods and foam applications. Italian glove manufacturers specify nitrile latex for medical examination products.
- Powder:Spray-dried redispersible polymer powders for dry-mix mortars and tile adhesives. Polish construction markets favor RDP for exterior insulation finish systems where on-site water addition is preferred.
- Dispersion:Fine particle suspensions with enhanced stability for specialty coatings. Spanish automotive refinish shops utilize polyurethane dispersions for clearcoat repair applications.
- Bulk:Tanker-delivered volumes for large-scale continuous manufacturing. Benelux paint producers receive bulk acrylic emulsion via dedicated pipeline connections from adjacent monomer plants.
Emulsion leads on scale; Powder gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs are diverting investment toward jurisdictions with streamlined ECHA registration pathways, while German industrial clusters retain production gravity through captive monomer supply. The EU Green Deal's uneven implementation across member states is creating specification arbitrage opportunities for formulators able to navigate divergent national building codes.
Germany
Automotive OEM coating lines in Bavaria and Baden-Württemberg are converting solvent-based paint shops to waterborne systems under the federal emission control ordinance. BASF SE and Wacker Chemie AG anchor supply through backward-integrated production corridors along the Rhine and in Burghausen. The KBA enforces type-approval standards that effectively mandate low-VOC binder platforms for vehicle finishes.
France
Construction chemical formulators in Île-de-France are integrating polymer emulsions into repair mortars to satisfy the national low-carbon building standard. The ANSM monitors food-contact migration limits for packaging adhesives, favoring established VAE safety dossiers. Lyon and Marseille house technical textile clusters specifying acrylic emulsions for outdoor upholstery applications.
Poland
Infrastructure investment corridors around Warsaw and Kraków are driving demand for tile adhesives and exterior insulation finish systems. Polish distributors are consolidating procurement of cement modifier emulsions, with regional satellite blending facilities bypassing logistics bottlenecks from Western European suppliers. The country's building material verticals exhibit accelerating specification alignment with EU Green Deal targets.
Netherlands
Packaging converters in Rotterdam and Eindhoven specify VAE emulsions for flexible film lamination where cold-seal performance governs procurement decisions. EFSA migration limit enforcement favors grades with established food-contact compliance histories. Benelux paint producers receive bulk acrylic emulsion via pipeline connections from adjacent monomer plants, compressing logistics costs.
Italy
Decorative paint manufacturers in Lombardy and Emilia-Romagna are converting solvent-based alkyd lines to waterborne acrylic platforms under municipal procurement carbon scoring rules. The country's furniture manufacturers in Veneto specify PVA emulsions for interior joinery where moisture resistance requirements remain moderate. Regional hybrid dispersion adoption is decentralizing formulation autonomy toward mid-tier producers.
Europe Polymer Emulsion Market Vendor Landscape
German producers anchor one tier through captive monomer supply and integrated R&D infrastructure; Benelux and French specialists hold differentiated positions in food-contact and construction chemical verticals. The vendor base separates into three strategic archetypes: backward-integrated petrochemical majors controlling acrylic feedstock, regional emulsion compounders serving just-in-time construction markets, and specialty dispersion developers targeting automotive and packaging compliance tiers. Competitive moves concentrate on capacity expansion in Central Eastern Europe and portfolio diversification into bio-based stabilizer platforms.
Within the integrated petrochemical tier, BASF SE and Wacker Chemie AG exemplify archetypes combining captive monomer production with application-specific technical service capabilities. Synthomer occupies a position representing scale-driven styrene-butadiene latex supply to paper coating mills across Scandinavia and the Benelux. These three entities collectively represent the competitive spectrum from upstream raw material control through downstream formulation partnership models.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Clariant |
| BASF SE |
| Allnex Netherlands B.V. |
| Synthomer |
| Dow |
| Akzo Nobel N.V. |
| 3M |
| Arkema Group |
| Others |
Supply Flow & Price Mechanics
Backward integration into acrylic monomer supply anchors pricing power for German producers while compressing margin flexibility for non-integrated compounders across Central Europe. Captive feedstock control allows BASF SE and Wacker Chemie AG to stabilize binder platform costs against volatile petrochemical indices, forcing independent formulators to absorb spot-market acrylic acid swings or surrender share.
Pricing Analysis
Distributor margins compress pricing realization for regional emulsion compounders serving just-in-time construction markets. Three-tier pricing structure across premium REACH-compliant grades, standard industrial binders, and economy construction tiers separates specification levels. Cost compression in economy tiers intensifies because Polish distributors consolidate procurement volumes. Packaging converters exhibit highest price sensitivity; automotive OEMs prioritize technical service over unit cost.
Supply Chain Analysis
Domestic-content mandates under France's national low-carbon building standard and Germany's federal emission control ordinance reshape sourcing toward regional polymerization capacity. Manufacturing concentrates in Germany, Netherlands, and Belgium. Raw material flows draw from captive butyl acrylate streams, imported VAM feedstock, and bio-based stabilizer pilot plants. Single-source vulnerability sits with ethylene supply for VAE copolymers. Distribution runs through pan-European building material distributors controlling sixty percent of waterproofing formulation sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in bio-based stabilizer platforms and premium REACH-compliant grades where reformulation urgency sustains pricing power. Cost-down drivers include regional satellite blending facilities bypassing Western European logistics premiums.
For Market Incumbents: To counter acrylic monomer supply concentration by backward-integrated rivals, deepen captive R&D on low-VOC binder platforms and establish satellite blending capacity in Poland and Romania. Certification investment in EFSA food-contact dossiers defends packaging share against VAE specialists. For New Entrants and Emerging Players: Launch via direct technical partnerships with Polish construction chemical distributors consolidating cement modifier procurement. White-space targets include bio-surfactant emulsions for premium positioning and exterior insulation finish systems in Central Eastern European infrastructure corridors. Go-to-market angle emphasizes just-in-time delivery guarantees against established logistics bottlenecks. For Investors and Strategic Acquirers: Roll-up economics work for regional emulsion compounders with captive technical service capabilities because buyer concentration among pan-European distributors favors scaled formulation partners. Acquisition target archetype: mid-tier producers with established REACH registration portfolios and regional blending infrastructure. Signal to watch: ECHA substance evaluation cycles accelerating legacy emulsion obsolescence.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Polish satellite facilities bypass logistics bottlenecks from Rhine corridor producers. |
| Backward Integration | Captive acrylic monomer supply stabilizes margins against petrochemical volatility. |
| Green Manufacturing Transition | Bio-based stabilizer platforms open premium positioning against petroleum-derived emulsions. |
| Long-term Supply Agreement | Just-in-time contracts with automotive OEM coating lines lock in basecoat specifications. |
| Joint Venture | Regional partnerships with construction chemical distributors consolidate procurement scale. |
Methodological Framework
Multiple input streams — technical discussions with plant managers and procurement leads at downstream OEMs, distribution channel partner interviews, and regulatory affairs director consultations — were reconciled against customs data, Cefic industry reports, SEC filings from listed chemical producers, and ECHA registration databases. Bottom-up volume modeling across polymerization train capacities and top-down demand validation from end-use sector consumption patterns were triangulated to constrain estimate variance.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use industry vertical, application performance specification, and regional production hub clustering. CAGRs were derived from trend extrapolation of historical capacity utilization and forward capacity addition announcements, incorporating automotive OEM coating line conversion timelines and construction chemical formulator specification shifts as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance evaluation acceleration or EU Green Deal implementation divergence across member states. Forecasts reflect documented assumptions on monomer supply continuity and distributor consolidation trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Water Dispersible Polymers Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Polyvinyl Alcohol Resins Market
Polymers & Resins
Polymer Modifiers Market
Polymers & Resins
Nylon-6 Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market