
 Smart Polymers Market | 2026-2036
Smart Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Polymers Market Intelligence
Software-defined formulation services is consolidating around polymer customization platforms that let buyers tune thermal, electrical, or biodegradation properties through digital specification rather than fixed SKUs. BASF SE leverages its global catalyst network to sustain R&D throughput across shape memory and conductive grades. Evonik Industries AG anchors European supply through specialized additive manufacturing feedstock lines. Dow competes on polyethylene backbone integration, extending its petrochemical infrastructure into responsive polymer architectures.
Smart polymers are macromolecular systems engineered with stimuli-responsive functional groups that undergo reversible physical or chemical changes when exposed to triggers such as temperature, pH, electric fields, or light; these materials typically incorporate phase-transition segments like N-isopropylacrylamide or conductive backbones such as polyaniline, manufactured through controlled radical polymerization or electrospinning processes to achieve precise molecular weights and response kinetics for targeted drug release, adaptive surfaces, or self-repairing structures. Shape memory polymers occupy the largest volume position due to established orthopedic fixation and textile deployment pipelines, while conductive polymers capture expanding margin pools in flexible electronics and energy storage interfaces. Biomedical applications lead value generation through implantable device coatings and controlled-release matrices, whereas electronics represents the fastest structural expansion as printed circuit and sensor manufacturers adopt organic semiconducting layers.
FDA device classification rules and EU MDR biocompatibility standards shape product development timelines and clinical trial requirements for healthcare-grade smart polymers, while REACH substance restrictions and EPA chemical management frameworks govern monomer selection and cross-border material certification. Japan's PMDA and METI coordinate domestic approval pathways for responsive polymer medical devices, creating parallel regulatory tracks that multinational suppliers must navigate simultaneously. Stakeholders should monitor how evolving per- and polyfluoroalkyl substance restrictions in major jurisdictions constrain fluorinated smart polymer development and redirect investment toward halogen-free alternatives.
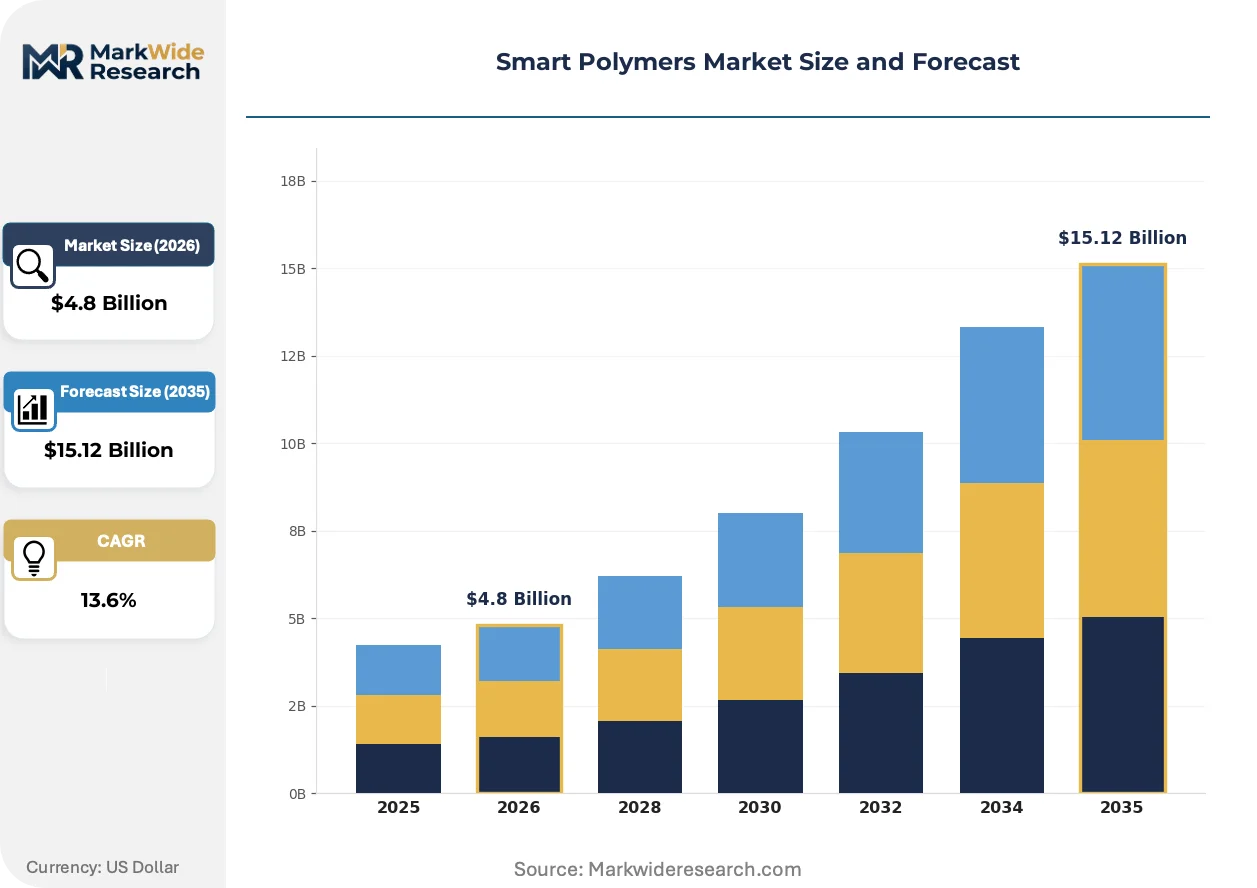
Market Dynamics
Software-defined formulation platforms are compressing development cycles for responsive polymer architectures, enabling buyers to specify thermal, electrical, and biodegradation properties through digital interfaces rather than traditional compound selection.
Growth Catalysts
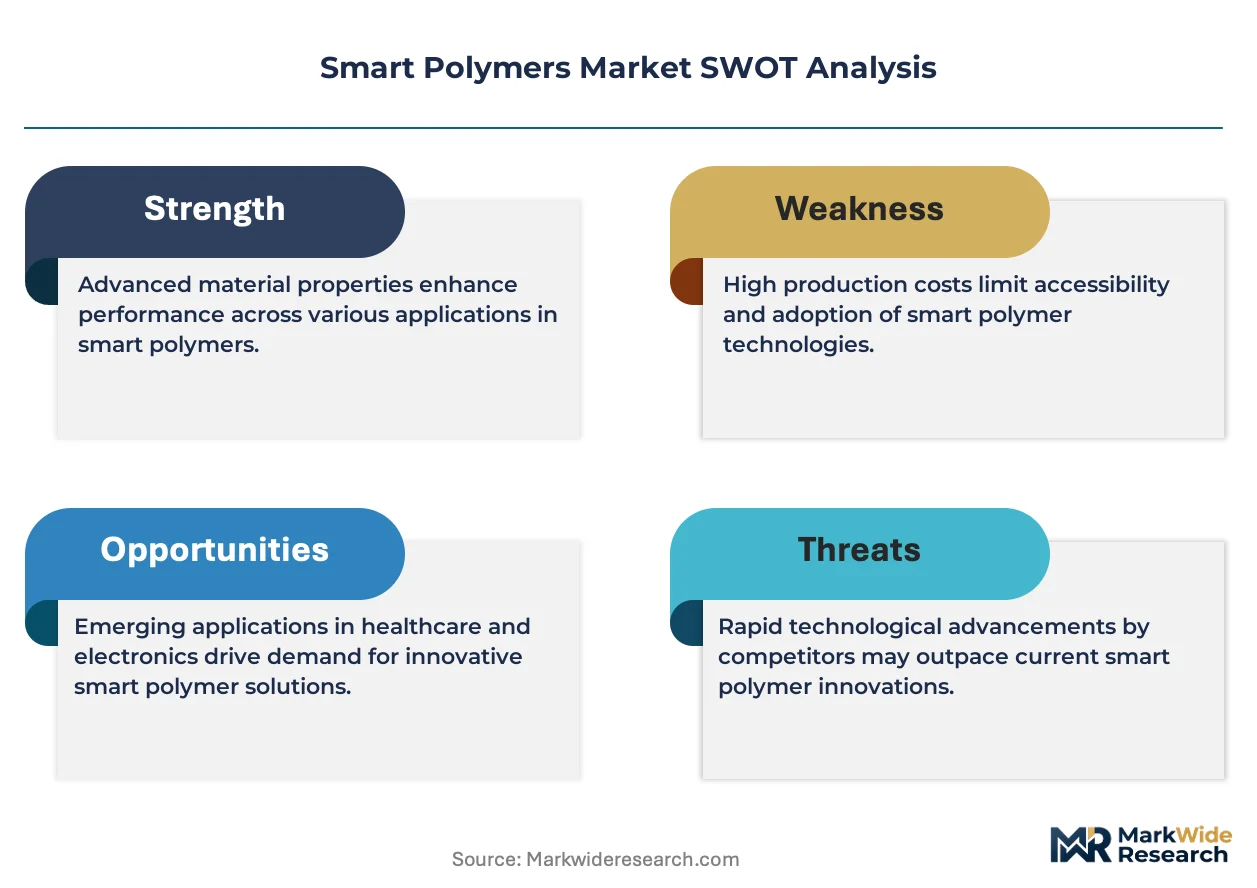
- EU Green Deal compliance mandates:REACH substance restrictions and circular economy targets are redirecting R&D investment toward halogen-free smart polymer alternatives, accelerating certification timelines for sustainable grades.
- Drug delivery system demand:Implantable device coatings and controlled-release matrices in healthcare are pulling volume through FDA and EU MDR biocompatibility pathways.
- Japan's PMDA-METI coordination:Parallel approval tracks for responsive polymer medical devices create dedicated domestic supply chains that multinational suppliers must maintain.
Market Restraints
- Monomer supply concentration:N-isopropylacrylamide and specialized acrylate feedstock production clusters in Germany and the United States, creating geographic vulnerability to energy cost spikes.
- Fluorinated polymer restrictions:Evolving per- and polyfluoroalkyl substance limits under EPA chemical management frameworks and REACH annex revisions are constraining established product lines.
- Conductive backbone cost volatility:Polyaniline and polythiophene synthesis depends on aniline and thiophene derivatives subject to petrochemical feedstock price swings.
Strategic Opportunities
- Flexible electronics penetration:Printed circuit and organic semiconductor manufacturers are adopting conductive polymer layers for sensor interfaces, opening margin pools outside traditional biomedical channels.
- India's PLI scheme alignment:Domestic medical device manufacturing incentives create localized demand for certified smart polymer feedstock with reduced import dependency.
- Electrospinning-digital twin convergence:Process simulation platforms are enabling predictive control over fiber morphology and response kinetics, compressing scale-up timelines for new grades.
Industry Challenges
- Controlled radical polymerization expertise scarcity:Atom transfer radical polymerization and reversible addition-fragmentation chain transfer process engineering requires specialized talent concentrated in academic and national laboratory ecosystems.
- Cross-regional certification synchronization:Simultaneous navigation of FDA device classification, EU MDR biocompatibility standards, and Japan PMDA approval tracks extends commercialization timelines and duplicates testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Polymers Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shape Memory Polymers, Conductive Polymers, Biodegradable Polymers, Self-Healing Polymers Application: Biomedical, Coatings, Textiles, Electronics End User: Healthcare, Automotive, Aerospace, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, wholesalers |
| Companies Covered | Lubrizol Corporation, Huntsman International LLC, BASF SE, SABIC, DuPont, Covestro AG, Dow, Merck KGaA, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Polymers Market Strategic Shifts & Innovations
Digital specification platforms are displacing fixed-SKU procurement models, while regulatory pressure on fluorinated chemistries redirects molecular design toward bio-based and halogen-free alternatives.
4D printing with shape memory polymers is integrating time-dependent geometric transformation into orthopedic fixation and textile deployment workflows. Medical device manufacturers in Germany and the United States are adopting these programmable architectures for patient-specific implants. The technology is integrating adaptive response into previously static structural components, compressing the boundary between manufacturing and therapeutic function.
REACH substance restrictions and the EU F-Gas Regulation are tightening monomer selection criteria for responsive polymer development. ECHA candidate list updates are forcing reformulation of established phase-transition materials ahead of sunset dates. European additive manufacturing feedstock suppliers are accelerating halogen-free certification programs to maintain market access.
Specification-driven procurement is displacing catalog-based purchasing for smart polymer grades. Electronics manufacturers and medical device OEMs are requiring tunable property sets through direct digital interface with formulation platforms. This pattern is most visible in Japan, where METI-backed standardization initiatives enable seamless data exchange between buyer specification systems and supplier production controls.
Smart Polymers Market Segmentation
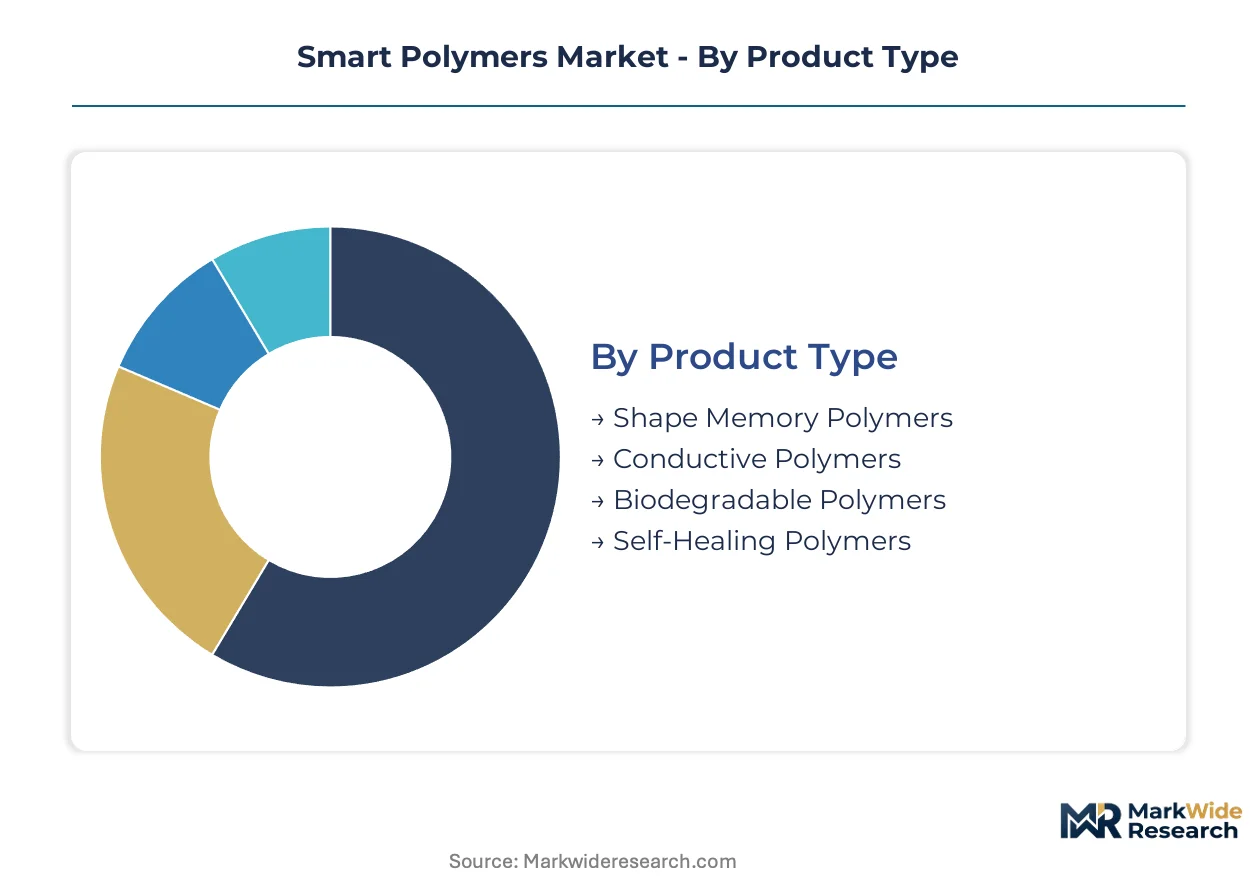
Smart polymers require precise property matching to application triggers, making specification granularity a commercial differentiator. Buyers increasingly reject fixed grades in favor of tunable architectures that align with regulatory pathways and manufacturing integration requirements.
Product Type:
Customization intensity varies sharply across this category, from commodity biodegradable backbones to highly engineered conductive systems requiring batch-level molecular weight control.
- Shape Memory Polymers:These materials incorporate phase-transition segments that enable reversible deformation recovery upon thermal or electrical stimulus. Orthopedic fixation devices in Germany and textile deployment systems in Japan concentrate procurement volume, with FDA device classification and PMDA approval tracks governing commercialization timelines. Most installed capacity flows through Shape Memory Polymers. Expansion is steepest in Conductive Polymers.
- Conductive Polymers:Polyaniline and polythiophene backbones provide organic semiconducting properties for flexible electronics interfaces. Printed circuit manufacturers and energy storage developers drive specification complexity, with petrochemical feedstock volatility constraining margin stability.
- Biodegradable Polymers:Aliphatic polyester and polyanhydride systems engineered for controlled hydrolysis rates in implantable applications.
- Self-Healing Polymers:Microcapsule-based and reversible bond architectures for adaptive surface restoration in coatings and structural composites.
Manufacturing scale tilts toward established phase-transition materials, while conductive grades capture premium positioning in emerging electronics channels.
Application:
Regulatory burden intensity separates this category, with healthcare-facing segments requiring multi-jurisdictional biocompatibility certification against lighter-touch industrial coatings.
- Biomedical:Implantable device coatings and controlled-release matrices dominate value generation, with EU MDR and FDA pathways extending development cycles. Drug delivery system demand in the United States and Germany anchors procurement volume.
- Electronics:Organic semiconductor layers and sensor interfaces represent the fastest structural expansion, with printed circuit manufacturers adopting conductive polymer architectures for flexible form factors.
- Coatings:Adaptive surface treatments for corrosion resistance and self-cleaning functionality in industrial equipment.
- Textiles:Temperature-responsive fibers and shape-memory woven structures for performance apparel and medical compression garments.
Biomedical applications command the highest certification investment per kilogram, while electronics offers the steepest volume growth trajectory outside traditional healthcare channels.
End User:
Procurement sophistication divides this category, with regulated medical device manufacturers demanding full supply chain documentation against automotive and consumer goods buyers prioritizing cost-positioned standard grades.
- Healthcare:Medical device OEMs and pharmaceutical formulators require REACH-compliant and FDA-cleared material certifications, with specialized additive manufacturing feedstock lines anchoring European supply.
- Automotive:Interior climate-responsive components and lightweight structural elements with self-repairing surface properties.
- Aerospace:Morphing structures and adaptive insulation systems subject to FAA and EASA airworthiness validation.
- Consumer Goods:Packaging with intelligent barrier properties and wearable electronics integration.
Healthcare procurement concentrates in Germany, the United States, and Japan, while automotive demand is diversifying across multiple manufacturing clusters.
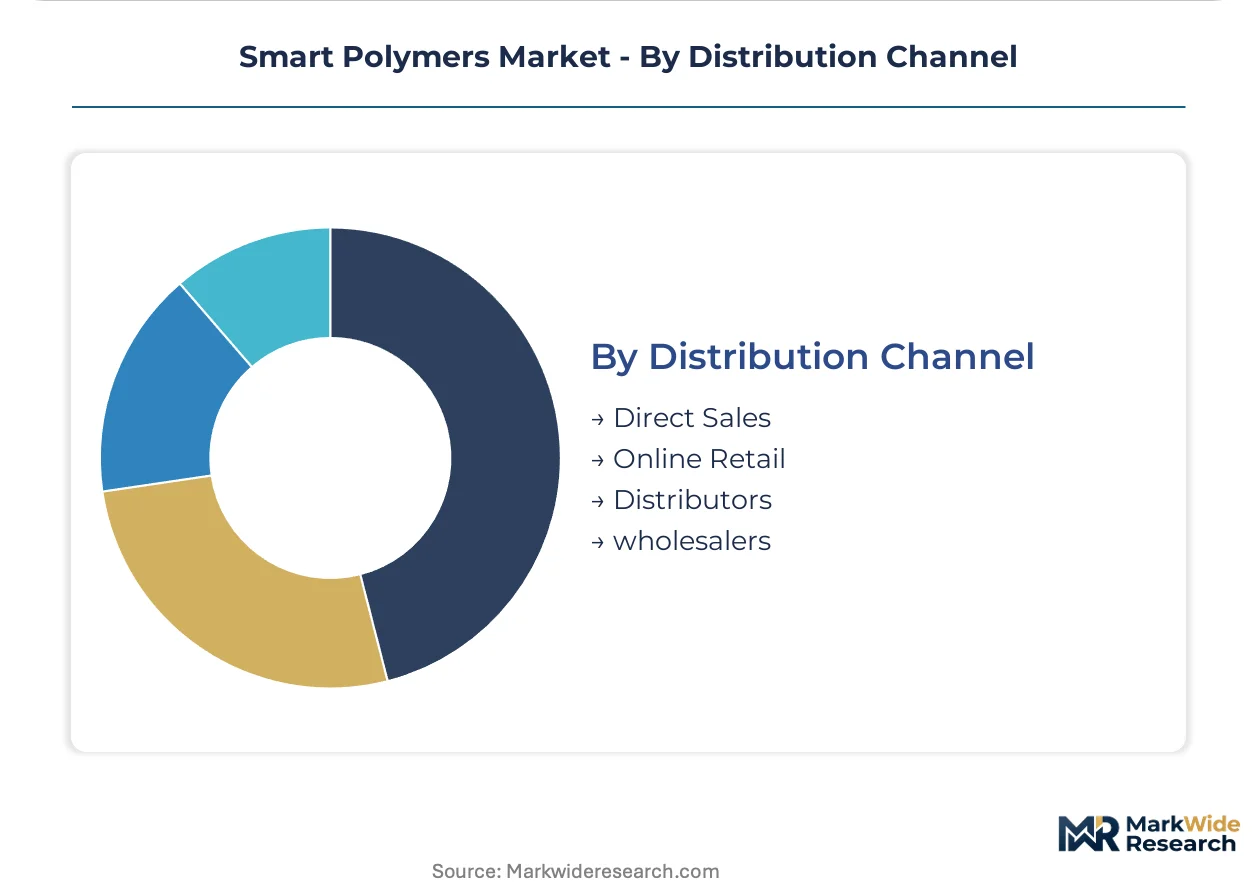
Distribution Channel:
Relationship intensity varies from specification-heavy direct partnerships to transactional digital procurement, with channel selection correlating to application technical complexity.
- Direct Sales:Formulation platforms engage healthcare and electronics manufacturers through digital specification interfaces, enabling property tuning without fixed-SKU constraints. BASF SE and Evonik Industries AG maintain dedicated technical service teams for responsive polymer accounts.
- Distributors:Regional specialty chemical distributors stock certified grades for mid-volume buyers requiring faster fulfillment than direct manufacturing schedules permit.
- Online Retail:Standardized biodegradable and self-healing polymer grades for research institutions and small-scale prototyping operations.
- Wholesalers:Bulk commodity biodegradable backbones for industrial coating and textile processing applications.
Direct sales capture the highest-margin specification-driven transactions, while distributor networks extend geographic reach for certified healthcare grades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting smart polymer manufacturing toward jurisdictions with streamlined chemical certification pathways. Producers are relocating formulation capacity to exploit gaps between EU REACH compliance costs and faster-track Asian medical device approval systems.
United States
FDA device classification rules for implantable coatings drive healthcare-grade polymer demand in Massachusetts and California clusters. EPA chemical management frameworks constrain fluorinated monomer selection, pushing reformulation toward halogen-free alternatives. Boston's medical device corridor anchors domestic R&D for controlled-release matrices.
Germany
EU Green Deal mandates and REACH substance restrictions accelerate sustainable grade certification timelines. ECHA candidate list updates force phase-transition material reformulation ahead of sunset dates. The Rhine-Ruhr industrial belt concentrates additive manufacturing feedstock production for European medical device supply chains.
Japan
PMDA-METI coordination creates parallel approval tracks for responsive polymer medical devices that multinational suppliers must maintain. Domestic standardization initiatives enable seamless data exchange between buyer specification systems and supplier production controls. The Kansai region hosts specialized shape memory polymer textile deployment manufacturing.
China
NMPA medical device regulations govern import substitution for implantable polymer coatings in domestic healthcare systems. MIIT industrial policy supports conductive polymer development for flexible electronics manufacturing. The Yangtze River Delta cluster integrates electrospinning capacity with printed circuit board production.
India
PLI scheme incentives for domestic medical device manufacturing create localized demand for certified smart polymer feedstock. CDSCO regulatory pathways for implantable materials are compressing versus legacy import-dependent approval timelines. Gujarat's specialty chemical corridor attracts formulation platform investments serving South Asian healthcare OEMs.
Smart Polymers Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical conglomerates commanding volume positions in commodity biodegradable backbones while specialized additive suppliers capture premium positioning in conductive and shape memory grades. The market exhibits moderate consolidation at the top tier, where global catalyst networks sustain R&D throughput across responsive polymer architectures. Three archetypes dominate: diversified chemical majors leveraging backward integration into monomer supply, specialized polymer houses focusing on medical-grade certification pathways, and regional compounders serving mid-volume industrial coating applications. Capacity expansion and portfolio diversification toward halogen-free alternatives represent the dominant competitive moves.
Within the diversified chemical major tier, BASF SE and Dow exemplify scale-driven positioning through captive polyethylene backbone integration and global formulation platform reach. Evonik Industries AG occupies a specialist position anchored in European additive manufacturing feedstock certification. These three entities represent distinct strategic postures: BASF SE leverages catalyst network density, Dow extends petrochemical infrastructure into responsive architectures, and Evonik Industries AG concentrates on medical-grade supply chain documentation.
| Leading Market Players |
|---|
| Lubrizol Corporation |
| Huntsman International LLC |
| BASF SE |
| SABIC |
| DuPont |
| Covestro AG |
| Dow |
| Merck KGaA |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
Digital specification demands from medical device OEMs in Germany and Japan are forcing formulation platforms to compress batch customization cycles, which concentrates margin pressure on mid-tier compounders lacking software-defined production controls.
Pricing Analysis
Distributor markups on certified healthcare grades range from 15-25% above direct-to-OEM contract pricing for comparable volume tiers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared implantable coatings from industrial textile grades and research-scale biodegradable backbones. Cost compression in conductive polymer feedstocks is intensifying because aniline derivative volatility feeds through from petrochemical indices. Electronics manufacturers exhibit highest price sensitivity due to thin margins in printed circuit assembly, while orthopedic device OEMs absorb premium positioning for PMDA-tracked shape memory formulations.
Supply Chain Analysis
Freight costs for temperature-sensitive N-isopropylacrylamide monomer shipments from Germany to Asian manufacturing clusters add 8-12% to landed input costs versus regional sourcing. Supply concentrates in Germany, the United States, and Japan for specialized acrylate feedstocks and controlled radical polymerization catalyst systems. Raw material sourcing draws from aniline derivatives, thiophene-based intermediates, and aliphatic polyester precursors tethered to petrochemical value chains. Single-source vulnerability in atom transfer radical polymerization catalyst supply creates concentration risk for medical-grade batch certification. Distribution runs through direct technical service partnerships for specification-driven healthcare accounts, with regional specialty distributors filling mid-volume electronics and textile channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart polymer manufacturing exhibits geographic arbitrage potential between EU REACH compliance costs and streamlined Asian medical device approval pathways, with formulation platform investments in India capturing 30-40% regulatory cost differentials versus European certification timelines.
For Market Incumbents: Deepen backward integration into N-isopropylacrylamide monomer supply to defend against energy cost spikes in German production clusters. Expand halogen-free certification capacity ahead of ECHA candidate list sunset dates to capture reformulation demand from fluorinated polymer displacement. Prioritize software-defined formulation platform deployment to neutralize emerging digital-native compounders targeting specification-driven procurement channels. For New Entrants and Emerging Players: Enter via India's PLI-backed medical device manufacturing corridor, where localized smart polymer feedstock demand outpaces domestic supply certification capacity. Target conductive polymer grades for flexible electronics in the Yangtze River Delta, where printed circuit board integration creates pull-through without FDA/MDR pathway barriers. Pursue electrospinning-digital twin convergence as a technical differentiation angle to compress scale-up timelines against established additive manufacturing feedstock suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized polymer houses holding medical-grade certification pathways across FDA, EU MDR, and Japan PMDA tracks simultaneously. Long-term viability over the analysis window favors acquisition targets with captive catalyst networks and software-defined formulation interfaces rather than commodity biodegradable backbone producers. Monitor ECHA candidate list expansion velocity as an inflection signal for halogen-free alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Certification Program | ECHA candidate list updates force phase-transition material reformulation ahead of regulatory sunset dates. |
| Software-Defined Formulation Platform | Digital specification interfaces displace fixed-SKU procurement for medical device OEMs in Japan and Germany. |
| Backward Integration into Monomer Supply | Captive N-isopropylacrylamide production insulates margin stability from German energy cost volatility. |
| Regional Manufacturing Footprint Expansion | India PLI scheme alignment captures localized demand from domestic medical device manufacturing incentives. |
| Electrospinning-Digital Twin Convergence | Predictive fiber morphology control compresses scale-up timelines for new responsive polymer grades. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer plant managers, medical device procurement leads at German and Japanese OEMs, distribution channel partners in specialty chemicals, and technical R&D directors at additive manufacturing feedstock suppliers. Secondary validation drew from ECHA substance restriction filings, FDA device classification databases, SEC 10-K chemical segment disclosures, and customs trade data for N-isopropylacrylamide and conductive monomer flows. Bottom-up segment sizing triangulated against top-down chemical industry value chain estimates to constrain forecast variance.
Historical reference periods anchored volume and value projections across the modeling period, with CAGRs derived from regression-weighted growth rate convergence across product type, application, and end-user dimensions. Segmentation modeling incorporated grade tier differentiation, regulatory pathway clustering, and regional production hub concentration as structural variables. Forecast inputs included electrospinning capacity expansion announcements, PMDA-METI coordination timeline disclosures, and EU Green Deal implementation velocity indicators.
Inputs from ECHA regulatory filings and FDA 510(k) device databases were available through the study window; gaps in real-time monomer inventory positioning data introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions about REACH substance restriction enforcement consistency and PLI scheme incentive continuity. Stakeholders should weight assumptions against their own operating context and regulatory exposure profiles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
Global Bio Based Polyurethane Market
Polymers & Resins
Foamed Plastics Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Optically Clear Resin Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Global Polyethyleneimine Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Global Polyolefin Powders Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market