
 Silicone Resins Market | 2026-2036
Silicone Resins Market Size, Share, and Industry Trends Forecast 2026-2036
Silicone Resins Market Outlook
The price-performance gap between premium and commodity silicone resins is hardening as automotive OEMs demand certified thermal stability above 250°C while construction buyers prioritize cost per liter. Wacker Chemie AG leverages its integrated siloxane feedstock position to sustain margin advantage in high-purity grades. Dow Inc. competes through geographic breadth in coatings applications. Shin-Etsu Chemical Co., Ltd. anchors its position in Asian electronics supply chains with proprietary methyl-phenyl resin chemistry.
Silicone resins are cross-linked organosilicon polymers formed from hydrolysis and condensation of chlorosilanes or alkoxysilanes, yielding Si-O-Si backbones with organic substituents that provide thermal resistance, weatherability, and dielectric stability. Liquid silicone resins dominate coatings formulation due to spray-applied processing efficiency, while solid grades command premium positioning in aerospace composites where outgassing specifications constrain supplier qualification. The adhesives segment is expanding fastest as electric vehicle battery module bonding shifts toward thermally conductive silicone systems.
EPA oversight of volatile organic compound limits in industrial coatings directly constrains solvent-borne silicone resin formulations, while REACH registration requirements in Europe enforce full toxicological dossiers for monomer precursors. The EU Green Deal carbon border adjustments will incrementally raise compliance costs for imported resin systems. Stakeholders must monitor evolving thermal management specifications from automotive OEMs and pre-qualify alternative catalyst systems before regulatory phase-outs disrupt existing supply relationships.
Market Dynamics
Automotive electrification is compressing thermal management specification cycles, forcing resin suppliers to pre-certify materials for battery module bonding and power electronics encapsulation before OEM platform locks occur.
Growth Catalysts
- REACH Registration Mandates:Full toxicological dossiers for chlorosilane precursors under ECHA requirements are filtering out non-compliant suppliers and consolidating qualified vendor pools for European coatings formulators.
- Electric Vehicle Battery Bonding:Thermally conductive silicone adhesive systems are displacing mechanical fasteners in EV battery pack assembly, creating specification pull from automotive Tier-1 suppliers.
- China Dual Carbon Goals:MEE enforcement of industrial emissions standards is accelerating domestic substitution of solvent-borne coatings with high-solids silicone resin formulations in steel infrastructure protection.
Market Restraints
- Methyl Chlorosilane Feedstock Concentration:Chinese producers control roughly two-thirds of global siloxane monomer capacity, exposing downstream resin manufacturers to supply disruption risks during environmental compliance shutdowns.
- EPA VOC Limits:Stricter industrial coatings emissions rules are forcing reformulation of solvent-borne silicone systems, raising R&D costs and extending qualification timelines for US architectural coatings suppliers.
- Ceramic Coating Substitution:Plasma-sprayed aluminum oxide and yttria-stabilized zirconia are capturing share in aerospace turbine applications above 400°C where silicone resins degrade.
Strategic Opportunities
- India PLI Scheme for Advanced Chemistry Cell Manufacturing:Domestic battery production incentives are creating first-mover openings for thermally conductive silicone resin suppliers to qualify with emerging cell manufacturers in Gujarat and Tamil Nadu.
- EU Green Deal Carbon Border Adjustments:Import tariffs on carbon-intensive materials will incrementally raise landed costs for non-EU resin systems, favoring local production or low-carbon process investments.
- Hybrid Epoxy-Silicone Convergence:Modified systems combining epoxy toughness with silicone thermal stability are opening specification windows in electric motor potting applications previously served by single-chemistry solutions.
Industry Challenges
- Organosilicon Synthesis Expertise Gap:Qualified process engineers capable of controlling hydrolysis-condensation kinetics for high-purity methyl-phenyl resins are concentrated at legacy producers, constraining new entrant scale-up.
- Automotive OEM Qualification Timelines:Thermal stability certification above 250°C requires 18-24 month validation cycles with battery manufacturers, locking working capital in pre-revenue development phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicone Resins Market |
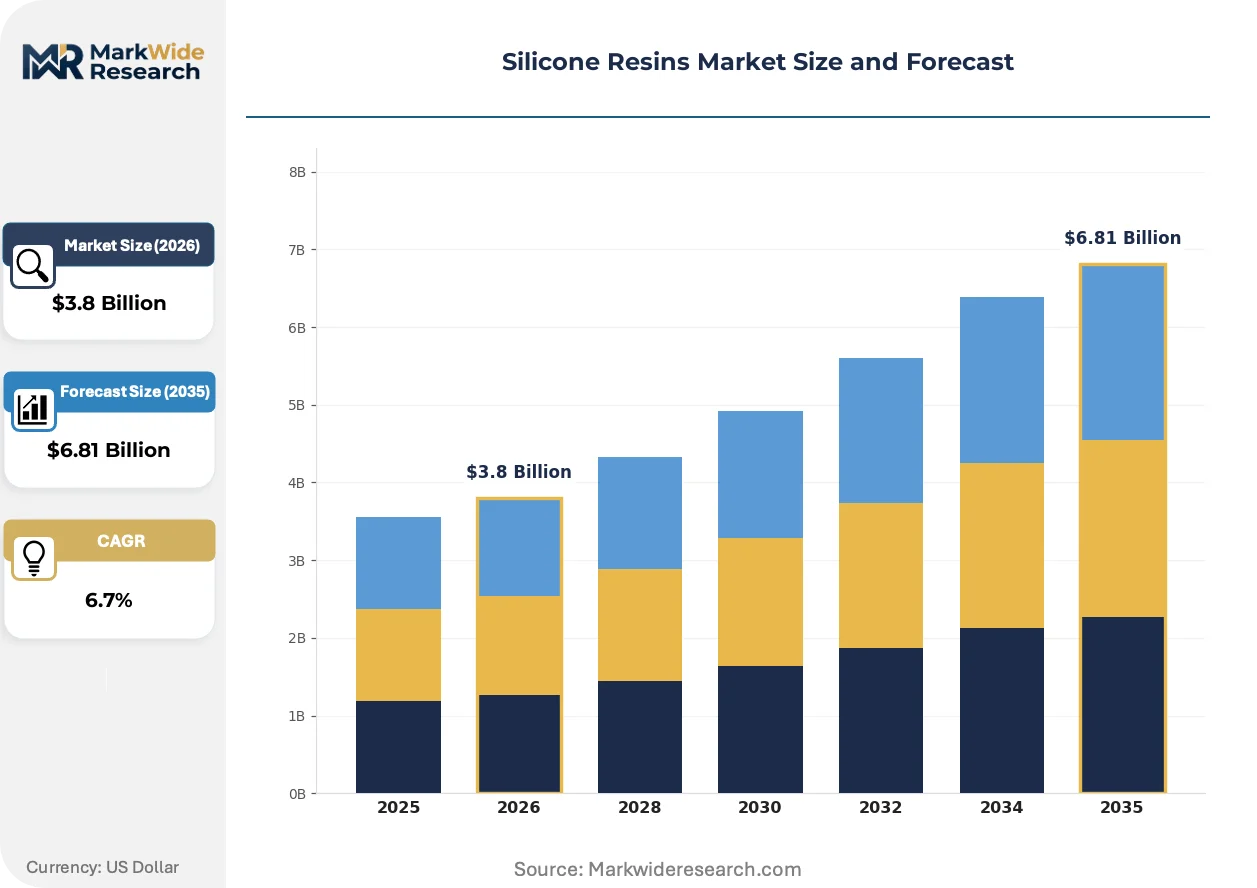
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Semi-solid, Powder Application: Coatings, Adhesives, Sealants, Electronics End User: Construction, Automotive, Aerospace, Consumer Goods Form: Aerosol, Cartridge, Bulk, Dispersion |
| Companies Covered | Evonik Industries AG, Wacker Chemie AG, Shin-Etsu Chemical Co., Ltd., Dow Inc., Momentive Performance Materials, Elkem ASA, Kaneka Corporation, KCC Corporation, Gelest Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicone Resins Market Strategic Shifts
Formulation chemistry is pivoting toward water-borne and high-solids systems as regulatory pressure on solvent emissions intensifies, while thermal conductivity enhancement through filler loading is becoming the primary performance battleground in EV applications.
Water-reducible silicone resins with self-crosslinking acrylic hybridization are absorbing share in industrial maintenance coatings as applicators face EPA VOC enforcement in US Gulf Coast petrochemical facilities. PPG Industries and Sherwin-Williams specification teams are accelerating qualification of these systems for tank farm and pipeline protection, compressing the viable window for traditional solvent-borne technologies in corrosion-resistant segments.
REACH authorization requirements for cyclic siloxanes (D4, D5, D6) under ECHA Annex XIV are forcing reformulation of personal care and electronics-grade resins toward linear oligomer alternatives. German cosmetics and automotive electronics suppliers are absorbing compliance costs through supply chain audits and alternative catalyst investments, with downstream effects rippling through Asian export-oriented resin compounders.
Specification consolidation around thermal interface materials is concentrating procurement authority at automotive OEM battery engineering centers, displacing historical distributor-led purchasing for commodity resin grades. BMW and Volkswagen cell integration teams in Munich and Wolfsburg now mandate direct supplier relationships for thermally conductive adhesives, compressing margins for regional coatings distributors across Central European supply chains.
Silicone Resins Market Segmentation
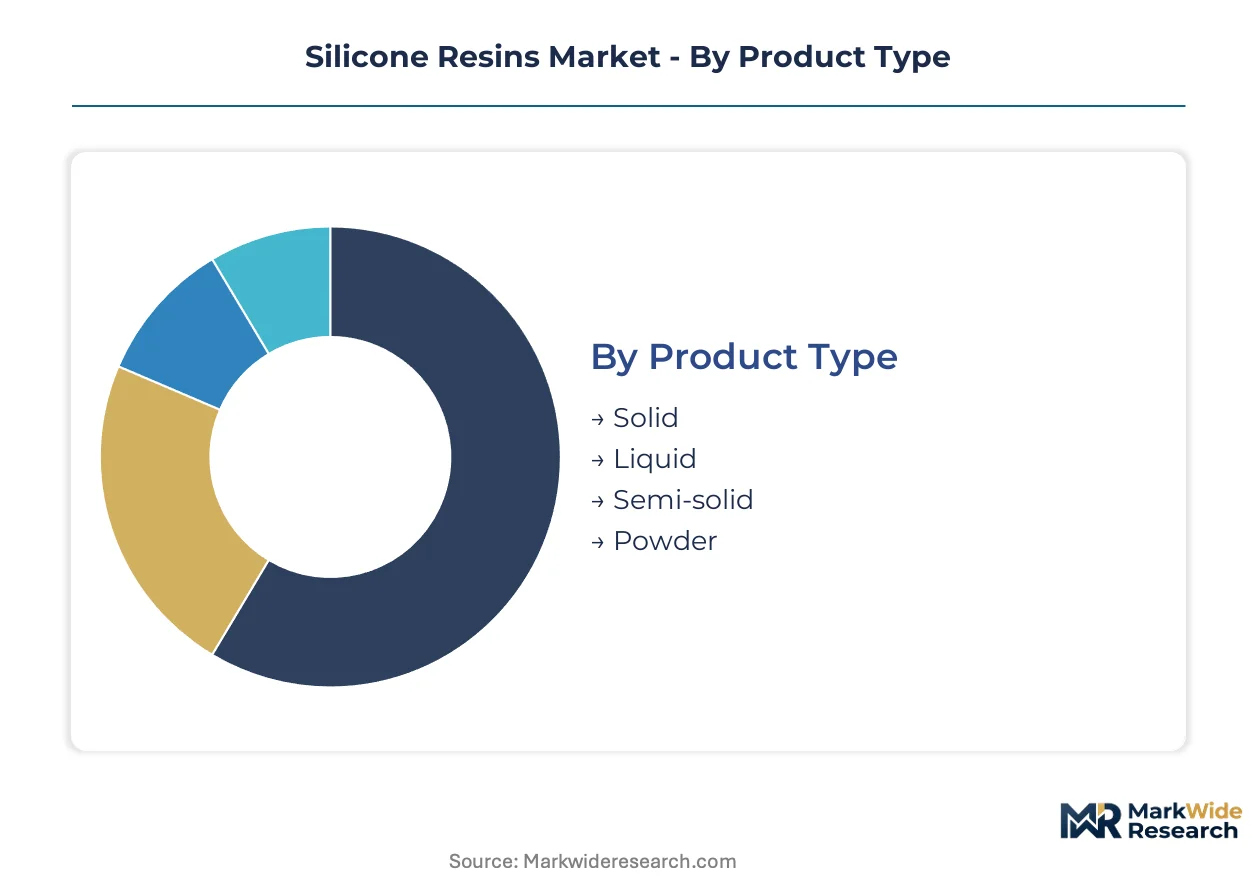
Segmentation in silicone resins reflects divergent capital requirements across product forms and end-use specifications. Automotive electrification and construction coatings are compressing specification cycles, forcing suppliers to align capacity investments with the most demanding certification tiers.
Product Type:
Capital intensity peaks in solid and liquid grades where hydrolysis-condensation reactor systems and purification trains demand the heaviest upfront investment.
- Solid:Cross-linked methyl-phenyl polymers with rigid Si-O-Si networks deliver thermal stability above 300°C. Aerospace composite outgassing specifications in Germany and the United States concentrate procurement at qualified suppliers with captive siloxane feedstock.
- Liquid:Low-viscosity hydroxyl-terminated resins enable spray-applied coatings processing. Demand clusters in Chinese steel infrastructure protection as MEE enforcement accelerates high-solids formulation adoption.
- Semi-solid:Thixotropic pastes for gap-filling applications in electronics potting.
- Powder:Micronized grades for powder coating integration in architectural metal finishing.
Most installed capacity flows through Liquid. Expansion is steepest in Solid.
Application:
Application selection dictates formulation complexity and regulatory exposure, with coatings carrying the broadest geographic compliance burden.
- Coatings:Weather-resistant films for industrial maintenance and architectural metal protection. EPA VOC limits in US Gulf Coast petrochemical facilities and REACH authorization for cyclic siloxanes in Europe are forcing water-borne reformulation investments.
- Adhesives:Thermally conductive systems for EV battery module bonding displace mechanical fasteners. BMW and Volkswagen engineering centers in Munich and Wolfsburg now mandate direct supplier qualification, compressing distributor margins.
- Sealants:Elastomeric joint fillers for construction and transportation infrastructure.
- Electronics:Dielectric encapsulants for power semiconductors and LED packages.
Coatings absorbs the largest share of production volume. Adhesives is gaining share fastest.
End User:
End-user concentration determines pricing power and contract structure, with automotive OEMs extracting the most stringent qualification terms.
- Construction:Architectural coatings and structural sealants where cost-per-liter sensitivity dominates procurement in commercial building markets.
- Automotive:Battery bonding, power electronics encapsulation, and underhood coatings requiring 250°C+ thermal stability certification. OEM platform locks in Germany and China freeze supplier selection 18-24 months ahead of production.
- Aerospace:Outgassing-compliant composites and turbine coatings above 400°C where ceramic alternatives are capturing share.
- Consumer Goods:Personal care and electronics-grade resins facing REACH D4/D5/D6 phase-outs.
Construction commands the widest volume base. Automotive shows the steepest specification escalation.
Form:
Form selection reflects application-scale economics and distribution channel configuration.
- Aerosol:Pre-packaged spray systems for maintenance and touch-up coatings in field applications.
- Cartridge:Two-component dispensing for adhesives and sealants in automotive assembly.
- Bulk:Tanker and drum supply for high-volume coatings formulators with in-house compounding.
- Dispersion:Water-borne emulsions for low-VOC construction coatings meeting EPA and MEE requirements.
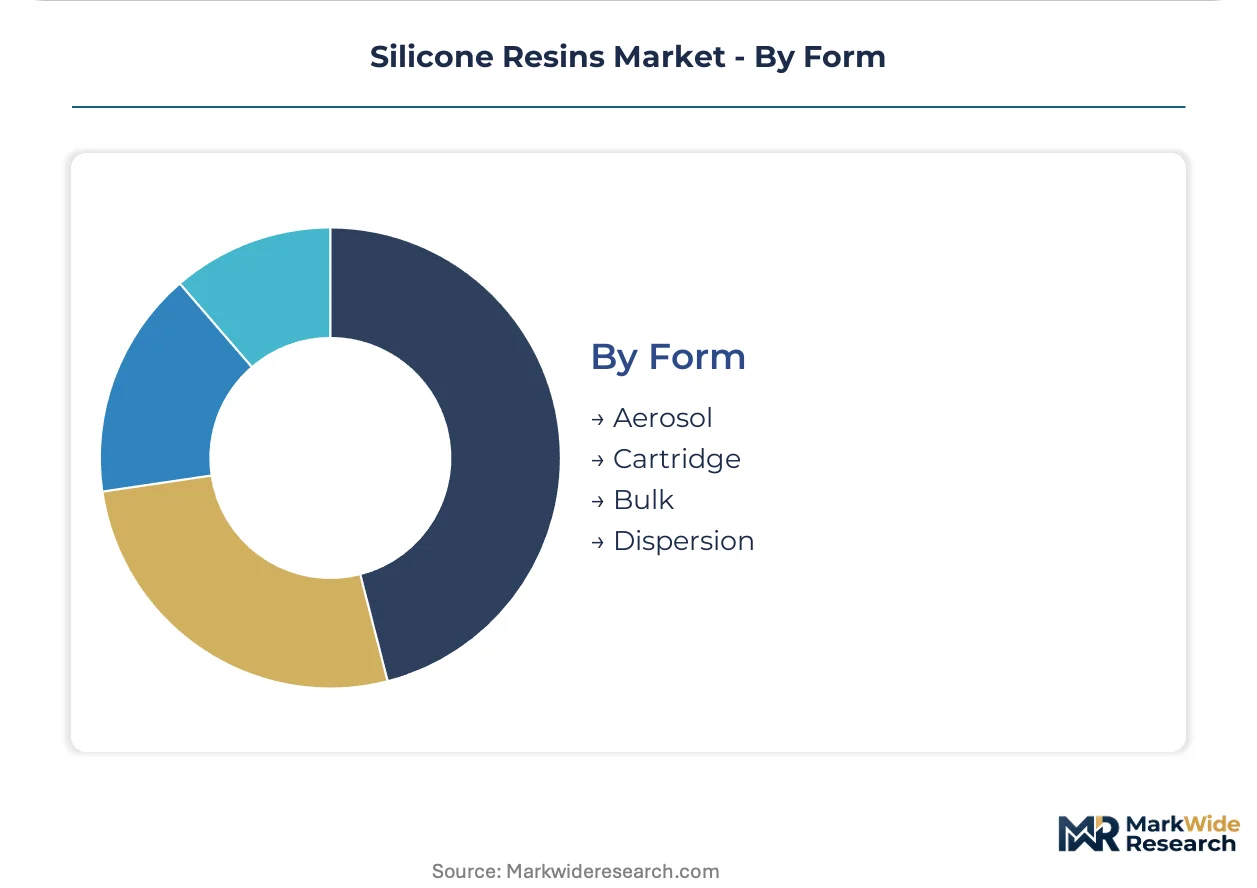
Bulk form dominates resin transfer economics. Dispersion is climbing fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German process engineers and Chinese siloxane technicians anchor the global talent base for methyl-phenyl resin synthesis. Their concentration at legacy production sites shapes where high-purity grades achieve commercial scale.
China
Domestic battery assembly and steel infrastructure protection drive silicone resin consumption. MEE enforcement of industrial emissions standards accelerates high-solids formulation adoption. The Yangtze River Delta clusters concentrate capacity expansion for water-borne coatings serving petrochemical tank farms.
Germany
Automotive OEM thermal management specifications and aerospace outgassing compliance dominate demand. ECHA REACH authorization requirements for cyclic siloxanes force reformulation toward linear oligomer alternatives. Munich and Wolfsburg engineering centers now mandate direct supplier qualification for battery bonding adhesives.
United States
EPA VOC limits in Gulf Coast industrial coatings and electric vehicle battery production shape formulation requirements. Stricter emissions rules compress qualification timelines for architectural coatings suppliers. Detroit-area automotive engineering centers lock supplier selection months ahead of EV platform launches.
India
Domestic advanced chemistry cell manufacturing incentives under the PLI scheme create first-mover openings for thermally conductive resin suppliers. BIS certification requirements for industrial chemicals filter import competition. Gujarat and Tamil Nadu emerging cell manufacturers qualify adhesive systems for module bonding.
Japan
Electronics-grade resin demand for power semiconductor encapsulation and LED packaging sustains premium positioning. METI guidance on chemical substance management influences regional formulation standards. The Osaka-Kobe industrial corridor concentrates methyl-phenyl resin production for Asian electronics supply chains.
Silicone Resins Market Competitive Environment
Top-tier vendors anchor integrated siloxane-to-resin production, while mid-scale compounders compete on formulation flexibility and regional service. German and Japanese specialists concentrate high-purity methyl-phenyl capacity for aerospace and electronics specifications. Three archetypes dominate: integrated feedstock operators with captive siloxane supply, regional formulators serving construction coatings, and specialty houses focused on thermal interface materials. Capacity expansion in Asian battery supply chains and pre-qualification investments for automotive OEM platforms represent the dominant competitive vectors.
Among integrated German chemical producers, Wacker Chemie AG and Evonik Industries AG occupy positions shaped by backward control over siloxane monomer supply. Dow Inc. exemplifies the geographic breadth archetype with coatings application focus across multiple industrial markets. Shin-Etsu Chemical Co., Ltd. anchors the Asian electronics specialist tier through proprietary resin chemistry and regional supply chain integration. These three represent distinct strategic postures rather than interchangeable competitors.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Wacker Chemie AG |
| Shin-Etsu Chemical Co., Ltd. |
| Dow Inc. |
| Momentive Performance Materials |
| Elkem ASA |
| Kaneka Corporation |
| KCC Corporation |
| Gelest Inc. |
| Others |
Value Chain & Pricing Dynamics
Process engineers skilled in hydrolysis-condensation kinetics cluster in Germany's chemical corridor and Japan's Osaka-Kobe industrial zone, creating labor-cost differentials that widen spreads between aerospace-grade methyl-phenyl resins and commodity construction coatings. This workforce concentration anchors premium pricing for outgassing-compliant solid grades while Asian mass-production facilities compress margins on liquid formulations for steel protection.
Pricing Analysis
Bundled technical service and certification support commands premiums in automotive battery bonding, while unbundled bulk resin supply dominates construction coatings procurement. Three-tier pricing structure separates aerospace-qualified solid grades from industrial maintenance liquids and economy powder coatings for architectural metal finishing. Price differentiation hinges on thermal stability certification above 250°C and captive siloxane feedstock integration. Cost compression in commodity liquids intensifies because Chinese MEE enforcement accelerates high-solids reformulation investments. Construction buyers exhibit highest price sensitivity per liter, while automotive OEMs prioritize qualification security over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle automotive Tier-1 demand for thermally conductive adhesives, while bulk drum distribution serves construction coatings formulators. Geographic supply concentrates in China, Germany, and Japan, with Chinese producers commanding roughly two-thirds of global siloxane monomer capacity. Downstream resin manufacturing draws from chlorosilane precursors, methyl-phenyl monomer feedstocks, and specialized catalyst systems. Single-source vulnerability runs through Yangtze River Delta environmental compliance shutdowns that disrupt siloxane availability. Distribution runs through qualified distributor networks for electronics-grade resins and direct mill relationships for high-volume coatings buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicone resins market functions as a regulatory compounder where ECHA REACH authorization requirements for cyclic siloxanes force systematic reformulation investments across European supply chains. This regulatory milestone sustains demand pull for compliant linear oligomer alternatives and pre-qualified catalyst systems.
For Market Incumbents: Cement backward integration into captive siloxane feedstock to defend margin position against Chinese environmental compliance disruptions. Expand high-purity methyl-phenyl capacity in Germany or Japan to capture aerospace outgassing specification premiums. Pre-qualify alternative catalyst systems before D4/D5/D6 phase-outs disrupt existing supply relationships with cosmetics and electronics customers.
For New Entrants and Emerging Players: Begin with water-borne dispersion formulations for Indian steel infrastructure protection under MEE-aligned domestic substitution trends. Target Gujarat and Tamil Nadu advanced chemistry cell manufacturers qualifying adhesive systems for battery module bonding. Pursue direct qualification with automotive OEM engineering centers rather than distributor channel penetration.
For Investors and Strategic Acquirers: Specialty chemical conglomerates seeking thermal management material exposure are the most active acquirer in this space. The five-to-ten year viability window favors targets with automotive OEM pre-qualification investments and low-carbon process patents. Acquisition focus should center on mid-scale compounders with proprietary methyl-phenyl chemistry and regional supply chain integration. Monitor EPA VOC enforcement intensity in US Gulf Coast petrochemical facilities as inflection indicator for water-borne formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Siloxane Feedstock | Captive methyl chlorosilane supply insulates margin from Chinese environmental shutdown volatility. |
| Automotive OEM Pre-Qualification Investment | Eighteen-to-twenty-four month validation cycles with BMW and Volkswagen lock supplier selection ahead of platform launches. |
| Water-Borne Formulation Transition | EPA VOC limits in US Gulf Coast facilities and MEE enforcement in China accelerate high-solids adoption. |
| Hybrid Epoxy-Silicone R&D Program | Modified systems open electric motor potting applications previously served by single-chemistry solutions. |
| India PLI Scheme Alignment | Domestic battery production incentives in Gujarat and Tamil Nadu create first-mover qualification openings. |
Study Parameters
Multiple input streams — technical director interviews at resin compounders, procurement lead discussions at automotive Tier-1 suppliers, and regulatory affairs consultations with ECHA-registered entities — were reconciled against customs trade data, SEC chemical segment disclosures, and ACC industry reports. Primary fieldwork with plant managers at siloxane production facilities and distribution channel partners in coatings supply chains informed capacity and flow estimates. Bottom-up product-grade volume builds were cross-checked against top-down end-use consumption models.
Historical shipment patterns were cross-referenced against panel input from silicone resin technical directors to establish baseline trajectories across the analysis window. Segmentation dimensions modeled include product form, application category, end-user industry, and regional production hub. CAGRs were derived from elasticity-adjusted demand projections incorporating electric vehicle thermal management specification cycles and construction coatings regulatory compliance timelines. Forecast inputs included automotive OEM platform lock schedules and REACH authorization phase-out calendars.
Caveats apply where EPA VOC rulemaking acceleration or ECHA substance restriction expansions could materially shift the outlook for solvent-borne formulation demand. Forecasts reflect documented assumptions regarding siloxane feedstock availability and automotive qualification timeline stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global UV Curable Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Resins Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Silane-Modified Polymers Market
Polymers & Resins
Global Amino Resin Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Homopolymer Resins Market
Polymers & Resins
Middle East LLDPE Market
Polymers & Resins
Polyester Polyol Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Global Polyol Market