
 Redispersible Polymer Powder Market | 2026-2036
Redispersible Polymer Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Redispersible Polymer Powder Market Intelligence
Multi-source procurement among construction material formulators is shifting toward captive supply agreements with specialized polymer producers. Wacker Chemie AG leverages its integrated VAE emulsion-to-powder chain to secure feedstock reliability across EMEA construction markets. BASF SE anchors its position through R&D intensity in styrene acrylic copolymers for high-performance tile adhesives. Dow Inc. competes on geographic dominance in North American dry-mix distribution channels.
Redispersible polymer powders consist of spray-dried polymer dispersions, typically 40-80 micron particle size, that re-emulsify upon contact with water to restore original film-forming properties in cementitious matrices. Vinyl acetate ethylene dominates volume due to cost-performance balance in standard-grade tile adhesives, while pure acrylic commands premium positioning in exterior insulation finish systems where hydrophobicity and UV resistance justify higher formulation spend. Styrene butadiene retains structural share in repair mortars and joint fillers where elastomeric crack-bridging performance remains specified. Deployment through dry-mix systems concentrates margin pools with building material suppliers seeking shelf-stable, just-in-time blending at job sites.
EPA construction material VOC limits, REACH substance restrictions, and China's GB standards for interior building materials collectively shape product registration pathways and reformulation cycles. ECHA evaluations of residual monomer content directly influence polymerization process investments and quality certification costs. Stakeholders must monitor evolving green building code harmonization between EU EPD requirements and emerging state-level low-carbon procurement mandates in the United States.
Market Dynamics
REACH substance restrictions and China's GB standards for interior building materials are compressing reformulation cycles, forcing polymer producers to accelerate residual monomer reduction investments while construction formulators scramble to certify compliant dry-mix systems ahead of tightening VOC thresholds.
Growth Catalysts
- EU Green Deal compliance mandates:Lower-emission building material requirements across European member states are accelerating specification of redispersible polymer powders in certified tile adhesives and self-leveling compounds.
- China infrastructure buildout:Specialty contractors and state-backed development firms in Chinese provinces are driving procurement volume for high-performance dry-mix mortar applications.
- Vinyl acetate ethylene cost-performance balance:This polymer chemistry dominates standard-grade formulations where film-forming properties must restore reliably in cementitious matrices at competitive formulation economics.
Market Restraints
- Ethylene feedstock volatility:Crude oil price swings transmit directly to VAE emulsion production costs, compressing margin stability for integrated polymer-to-powder producers.
- ECHA residual monomer evaluations:Evolving substance restriction protocols in Europe are extending quality certification timelines and raising polymerization process investment thresholds.
- Acrylic substitution pressure:Pure acrylic dispersions command specification in exterior insulation finish systems where UV resistance and hydrophobicity justify premium formulation spend over VAE alternatives.
Strategic Opportunities
- Underpenetrated Indian dry-mix sector:BIS standards harmonization with European EPD frameworks creates first-mover positioning for polymer powder suppliers targeting emerging commercial construction clusters.
- Styrene acrylic copolymer R&D intensity:High-performance tile adhesive segments reward formulation innovation that bridges VAE cost structures with acrylic durability specifications.
- Job-site just-in-time blending:Shelf-stable powder logistics are compressing traditional ready-mix concrete distribution channels in North American residential construction markets.
Industry Challenges
- Polymerization process retooling:Residual monomer reduction targets require capital-intensive reactor modifications and extended validation cycles before ECHA registration approval.
- Green building code harmonization friction:Misalignment between EU EPD requirements and emerging state-level low-carbon procurement mandates in the United States complicates cross-border product certification strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Redispersible Polymer Powder Market |
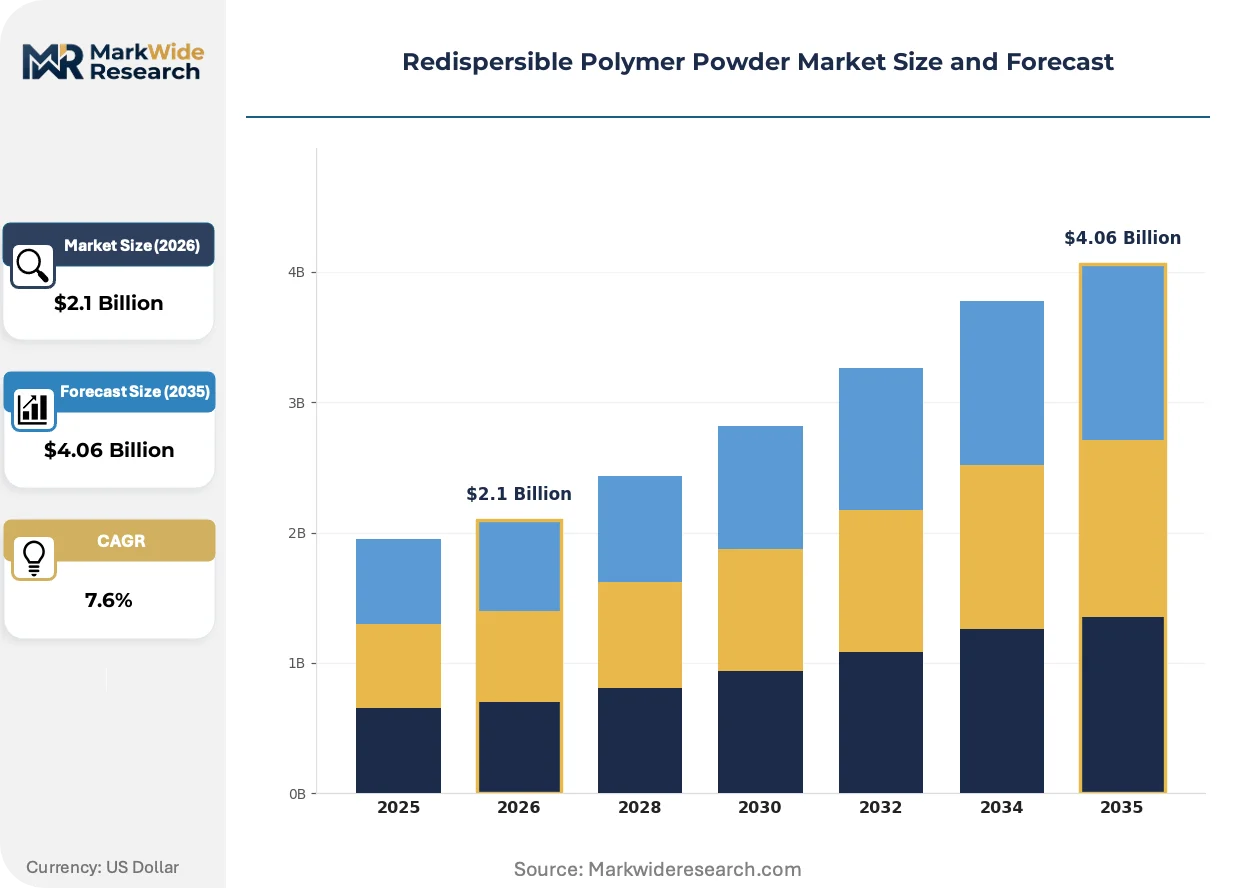
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.06 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vinyl Acetate Ethylene, Styrene Butadiene, Pure Acrylic, Styrene Acrylic, EVA, Ethylene Vinyl Acetate Application: Tile Adhesives, Self-leveling Compounds, Repair Mortars, Insulation Systems, Joint Fillers, Tile Grouts End User Industry: Construction Companies, Building Material Suppliers, Specialty Contractors, Infrastructure Development Firms Deployment Type: Dry Mix, Wet Mix, Pre-blended, Custom Formulations |
| Companies Covered | Celanese Corporation, Ashland Global Holdings Inc., Wacker Chemie AG, Dairen Chemical Corporation, Evonik Industries AG, BASF SE, Synthomer plc, Organik Kimya A.S., Dow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Redispersible Polymer Powder Market Strategic Shifts & Innovations
Formulation chemistry advances and procurement model compression are redistributing competitive advantage across the value chain, with integrated producers capturing margin pools that previously accrued to independent dry-mix blenders.
Hybrid styrene acrylic copolymers are expanding into high-performance tile adhesive segments where contractors demand hydrophobicity approaching pure acrylic grades at VAE-adjacent price points. Regional formulators in Germany and Italy are accelerating adoption to secure specification on commercial facade projects. This chemistry bridge is expanding into mid-tier specification territory previously dominated by commodity VAE powders.
REACH substance restriction protocols are mandating residual monomer thresholds that force polymerization process investments exceeding €50 million for integrated producers. The industrial consequence is accelerated consolidation among European VAE emulsion manufacturers unable to fund retooling. Exterior insulation finish system suppliers face compressed registration timelines as ECHA evaluations target residual vinyl acetate content.
Building material distributors are unbundling after-sales technical service from powder procurement contracts, shifting specification influence toward specialty contractors with in-house formulation expertise. This behavior change concentrates volume with large dry-mix blenders capable of self-directed product selection. The United States exhibits the most visible channel compression, where national distribution networks are displacing regional independents in major metropolitan construction markets.
Redispersible Polymer Powder Market Segmentation
Redispersible polymer powders serve distinct performance tiers across construction chemistry, with formulation specifications varying sharply by load-bearing requirements, weather exposure, and certification grade. Procurement patterns diverge between commodity volume applications and engineered systems demanding precise rheology control.
Product Type:
Customization intensity spans from standardized VAE grades to specialty acrylic copolymers requiring tailored monomer ratios and residual monomer management.
- Vinyl Acetate Ethylene:Spray-dried copolymer dispersion with 40-80 micron particle size re-emulsifies reliably in cementitious matrices. Demand concentrates with Chinese infrastructure development firms specifying cost-optimized dry-mix mortars for high-volume residential and commercial tiling. Ethylene feedstock volatility transmits directly to margin stability for integrated producers.
- Styrene Acrylic:Hybrid copolymer bridges hydrophobicity performance approaching pure acrylic grades at VAE-adjacent economics. German and Italian formulators accelerate adoption for commercial facade projects requiring mid-tier specification. R&D intensity rewards suppliers capable of tuning glass transition temperatures for regional climate exposure.
- Styrene Butadiene:Elastomeric crack-bridging properties retain specification in repair mortars and joint fillers where structural movement tolerance is mandatory.
- Pure Acrylic:UV resistance and hydrophobicity command premium formulation spend in exterior insulation finish systems facing severe weather exposure.
- EVA:Ethylene-vinyl acetate chemistry serves niche applications requiring specific adhesion profiles to non-cementitious substrates.
- Ethylene Vinyl Acetate:Distinct from standard VAE through modified vinyl acetate content ratios targeting specialized bonding characteristics.
Most installed capacity flows through Vinyl Acetate Ethylene. Expansion is steepest in Styrene Acrylic.
Application:
Volume concentration versus margin capture splits this category, with high-throughput tiling applications diverging from technical specialty systems.
- Tile Adhesives:Largest consumption segment by tonnage, spanning standard-grade interior applications through high-performance exterior facade systems. Chinese specialty contractors and European commercial developers drive procurement of certified formulations meeting REACH VOC thresholds and GB interior material standards.
- Self-leveling Compounds:Flowable underlayment systems demand precise particle size distribution and re-emulsification kinetics. North American residential construction markets exhibit accelerating shelf-stable powder logistics adoption, compressing traditional ready-mix concrete distribution.
- Repair Mortars:Structural rehabilitation applications specify Styrene Butadiene chemistry for elastomeric performance under cyclic loading.
- Insulation Systems:Exterior insulation finish systems represent premium formulation territory where pure acrylic hydrophobicity justifies higher spend.
- Joint Fillers:Movement accommodation requirements sustain demand for elastomeric polymer grades in commercial flooring and facade applications.
- Tile Grouts:Aesthetic and durability specifications drive chemistry selection toward stain-resistant acrylic variants in high-end residential markets.
Tile Adhesives absorb the majority of polymer powder volume. Self-leveling Compounds are climbing the fastest as job-site logistics reshape distribution economics.
End User Industry:
Specification authority and procurement scale determine segment boundaries, with fragmented contractor bases contrasting concentrated material supplier networks.
- Construction Companies:Volume purchasers across residential and commercial sectors, increasingly consolidating procurement through national distribution networks displacing regional independents. Technical service unbundling shifts specification influence toward in-house formulation expertise.
- Building Material Suppliers:Dry-mix blenders capture margin pools through captive supply agreements with specialized polymer producers. Large national blenders concentrate volume as distributors compress channel structure.
- Specialty Contractors:Niche specification authority in high-performance systems drives demand for custom formulation capabilities and direct technical support relationships.
- Infrastructure Development Firms:State-backed Chinese development entities drive procurement scale for standardized dry-mix mortar applications across provincial buildout programs.
Building Material Suppliers command the deepest polymer powder procurement relationships. Specialty Contractors are gaining share fastest as technical specification authority centralizes.
Deployment Type:
Supply chain configuration and just-in-time logistics requirements segment this category between shelf-stable powder systems and liquid-dependent alternatives.
- Dry Mix:Shelf-stable powder logistics enable job-site blending with controlled water addition, eliminating liquid emulsion transport costs and spoilage risk. North American metropolitan construction markets exhibit visible channel compression favoring national distribution networks.
- Pre-blended:Factory-optimized formulations reduce field variation risk for specification-critical applications requiring consistent performance certification.
- Wet Mix:Liquid emulsion systems retain position in applications where immediate film formation or specific rheology modification is required.
- Custom Formulations:Project-specific chemistry tuning serves high-performance segments where standard grades fail certification or performance thresholds.
Dry Mix deployment dominates installed blending capacity. Custom Formulations are expanding most quickly as green building code harmonization creates regional certification fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as compliance cost differentials between jurisdictions widen. Producers migrate capacity toward regions with streamlined substance registration pathways while maintaining sales presence in high-threshold markets through reformulated product lines.
China
Provincial infrastructure buildouts in Sichuan-Chongqing and Yangtze River Delta clusters drive procurement volume for standardized dry-mix mortars. GB standards for interior building materials mandate VOC thresholds that compress reformulation cycles for both domestic and imported polymer grades. State-backed development firms in Chengdu and Wuhan concentrate demand for cost-optimized VAE powders in high-volume residential tiling.
Germany
Commercial facade specification in Munich and Frankfurt construction corridors rewards styrene acrylic copolymer adoption for mid-tier hydrophobicity performance. REACH substance restrictions and ECHA residual monomer evaluations extend quality certification timelines, favoring integrated producers with captive emulsion-to-powder capabilities. North Rhine-Westphalia chemical clusters anchor polymerization capacity serving EMEA construction markets.
United States
Metropolitan construction markets in Texas and Florida exhibit accelerating shelf-stable powder logistics adoption, compressing traditional ready-mix concrete distribution channels. EPA construction material VOC limits vary by state, creating fragmented registration requirements that complicate national product rollouts. National distribution networks in Dallas and Miami displace regional independents through technical service unbundling.
India
BIS standards harmonization with European EPD frameworks creates first-mover positioning opportunities for suppliers targeting emerging commercial construction clusters in Maharashtra and Gujarat. Specialty contractors in Mumbai and Ahmedabad drive specification of certified tile adhesives as green building codes gain traction. Infrastructure development in Delhi-NCR concentrates demand for high-performance dry-mix systems.
Italy
Regional formulators in Lombardy and Veneto accelerate styrene acrylic adoption for commercial facade projects requiring hydrophobicity approaching pure acrylic grades. EU Green Deal compliance mandates tighten specification criteria for certified self-leveling compounds in Milan and Turin construction corridors. Northern industrial clusters maintain formulation expertise that influences polymer powder procurement decisions across Mediterranean markets.
Redispersible Polymer Powder Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialty copolymer niches and geographic white spaces. The vendor base stratifies across integrated chemical conglomerates with captive VAE emulsion supply, independent powder specialists reliant on third-party dispersion feedstock, and regional formulators building backward integration into polymerization. Three archetypes dominate: integrated emulsion-to-powder operators, technology licensors seeking royalty streams, and distribution-focused blenders capturing margin through logistics optimization. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure feedstock reliability and regional registration expertise.
Among integrated chemical producers, Celanese Corporation, Wacker Chemie AG, and BASF SE exemplify the emulsion-to-powder archetype with captive supply chain control. These entities occupy positions where polymerization investments and quality certification capabilities create defensive moats against feedstock volatility and regulatory tightening. Their geographic footprints reflect decades of regional market development rather than recent expansion initiatives.
| Leading Market Players |
|---|
| Celanese Corporation |
| Ashland Global Holdings Inc. |
| Wacker Chemie AG |
| Dairen Chemical Corporation |
| Evonik Industries AG |
| BASF SE |
| Synthomer plc |
| Organik Kimya A.S. |
| Dow Inc. |
| Others |
Cost & Logistics Intelligence
Spray-drying technology migration toward continuous processing lines simultaneously compresses unit production costs and concentrates capacity among integrated VAE emulsion-to-powder operators with capital reserves for reactor retooling. This capital-intensity threshold is eliminating batch-oriented independents while securing feedstock reliability premiums for Wacker Chemie AG and BASF SE across EMEA construction markets.
Pricing Analysis
Distributor margin compression runs through North American dry-mix channels where national networks displace regional independents. Three-tier pricing structure across premium pure acrylic, standard styrene acrylic, and economy VAE grades reflects certification grade and volume scale differentiation. Pricing pressure stems from ethylene feedstock volatility transmitting directly to integrated producers' margin stability. Chinese infrastructure development firms exhibit highest price sensitivity in standardized dry-mix mortar procurement, while European commercial facade contractors accept premium formulation spend for REACH-compliant hydrophobicity performance.
Supply Chain Analysis
Dual-sourcing qualification requirements among German and Italian formulators mandate redundant VAE emulsion suppliers for commercial facade projects. Geographic supply concentrates in Germany, China, and the United States, with North Rhine-Westphalia chemical clusters anchoring EMEA polymerization capacity. Raw material dependencies rest on ethylene monomer, vinyl acetate feedstock, and spray-drying energy inputs. Single-source vulnerability persists for specialty styrene acrylic copolymers requiring tuned glass transition temperatures. Distribution runs through building material suppliers consolidating procurement through captive supply agreements with integrated polymer producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The redispersible polymer powder market compounds steadily as green building code harmonization mandates recurring reformulation cycles across construction chemistry. Infrastructure development in China and India sustains volume foundations while European regulatory tightening secures premium pricing tiers.
For Market Incumbents: Anticipate ECHA residual monomer evaluation extensions by accelerating polymerization process investments ahead of substance restriction protocols. Secure backward integration into VAE emulsion supply to defend margin position against ethylene feedstock volatility. Channel control through technical service bundling with large dry-mix blenders counters distributor unbundling trends in North American metropolitan markets. For New Entrants and Emerging Players: Begin with BIS standards harmonization opportunities in Maharashtra and Gujarat commercial construction clusters where first-mover positioning remains available. Target underpenetrated Indian dry-mix sectors through direct technical support relationships with specialty contractors gaining specification authority. Pursue job-site just-in-time blending logistics as the go-to-market angle compressing traditional ready-mix concrete distribution channels. For Investors and Strategic Acquirers: Valuations sit cheapest among independent powder specialists reliant on third-party dispersion feedstock facing REACH compliance cost escalation. Long-term viability over a multi-year horizon favors integrated emulsion-to-powder operators with captive supply chain control and EMEA registration expertise. Watch ECHA residual vinyl acetate content evaluations as the inflection signal accelerating consolidation among European VAE manufacturers unable to fund retooling.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VAE Emulsion Supply | Celanse Corporation and Wacker Chemie AG secure feedstock reliability against ethylene price volatility. |
| Green Manufacturing Transition | Residual monomer reduction investments exceed quality certification thresholds mandated by REACH protocols. |
| Long-term Supply Agreement | Captive contracts with Chinese infrastructure development firms lock volume for provincial buildout programs. |
| Joint Venture | Regional formulators in Lombardy and Veneto partner for styrene acrylic R&D serving Mediterranean facade markets. |
| Capacity Expansion | Spray-drying line additions in North Rhine-Westphalia serve accelerating German commercial construction specification. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary field engagement with secondary validation. Plant managers at integrated polymer producers, procurement leads at German and Italian dry-mix blenders, distribution channel partners in North American metropolitan markets, and technical R&D directors specializing in styrene acrylic copolymer formulation provided operational perspective. Secondary sources included customs and trade data tracking VAE emulsion cross-border flows, Cefic chemical industry reports, SEC 10-K filings from listed chemical conglomerates, and ECHA substance restriction documentation. Bottom-up volume modeling and top-down market sizing triangulated across these inputs.
Segment-weighting approaches distributed value and volume across product type tiers, application categories, end-user industry concentration, and deployment configuration. Polymer chemistry grade, construction application specification, procurement channel structure, and regional regulatory cluster density formed the core segmentation dimensions. CAGRs derived from regression analysis of historical demand patterns and forward projection of infrastructure investment cycles. Ethylene feedstock cost trajectories and green building code adoption curves served as industry-specific forecast inputs across the analysis window.
Several conditions sit outside the modeled scope, including geopolitical disruption to ethylene supply chains and abrupt shifts in Chinese infrastructure stimulus intensity. Forecasts reflect documented assumptions about REACH substance restriction timelines and BIS standards harmonization progress. Deviation in ECHA residual monomer evaluation stringency or EPA construction material VOC limit adoption rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ethylene Tetrafluoroethylene (ETFE) Market
Polymers & Resins
Polycaprolactone Polyols Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
US Acrylic Solid Surface Market
Polymers & Resins
Global Polycaprolactone Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
South America Polyamide Market
Polymers & Resins
UV Stabilized Thermoplastic Elastomer for Automotive Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
United Kingdom Engineering Plastics Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Non-Ionic Polyacrylamide Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market