
 Saudi Arabia Sodium Thiosulphate Market | 2026-2036
Saudi Arabia Sodium Thiosulphate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Sodium Thiosulphate Market Analytics
Water treatment utilities are reorganizing procurement priorities toward higher-purity sodium thiosulphate for municipal dechlorination, pulling volume from legacy photography applications. SABIC anchors domestic supply through its petrochemical integration and captive sulphur derivatives. Fouz Chemical Company specializes in technical-grade distribution to industrial clusters across the Eastern Province. AquaChemie Middle East competes on bulk liquid logistics and just-in-time delivery to Red Sea coastal facilities.
Sodium thiosulphate (Na₂S₂O₃·5H₂O) is a colourless crystalline inorganic salt manufactured through sulphur-alkali reaction, typically assaying at minimum 99% purity for industrial grades and higher for pharmaceutical applications. The compound functions primarily as a reducing agent, chlorine scavenger, and silver halide solvent across process industries. Crystalline and liquid product types dominate volume throughput owing to handling efficiency in large-scale water treatment and mining applications. Chemical synthesis and pharmaceutical applications command margin premiums due to stringent SASO and SFDA certification requirements. Powdered and granular forms occupy niche positions in food processing and specialized agricultural formulations where controlled dissolution rates matter.
SFDA pharmaceutical standards, SASO industrial chemical specifications, and Royal Commission environmental directives for Jubail and Yanbu collectively shape product purity thresholds and market access conditions. The national chemicals regulator enforces GMP-aligned manufacturing protocols for pharmaceutical-grade material while SASO technical regulations govern industrial-grade import and labelling. Stakeholders must monitor evolving desalination expansion timelines and associated dechlorination chemical demand across new SWCC facilities.
Market Dynamics
SWCC desalination expansion is restructuring chemical procurement volumes across the Kingdom's water utilities, pulling sodium thiosulphate demand toward bulk liquid formats and away from crystalline legacy supply.
Growth Catalysts
- SFDA pharmaceutical mandates:Purity thresholds for injectable-grade material are tightening, creating certified supply premiums for domestic manufacturers aligned with GMP protocols.
- Jubail-Yanbu industrial corridor:Petrochemical integration generates captive sulphur feedstock, lowering input costs for regional sodium thiosulphate synthesis.
- Dechlorination intensity:Reverse osmosis pretreatment standards at new coastal facilities require higher dosing precision, favoring technical-grade liquid solutions over solid alternatives.
Market Restraints
- Sulphur price volatility:Refinery output fluctuations in the Gulf region transmit directly to thiosulphate production economics, compressing margin stability for non-integrated producers.
- Single-source concentration:Eastern Province production clusters dominate domestic supply, exposing buyers to localized disruption risk from logistics bottlenecks or feedstock interruptions.
- Hypochlorite alternative threat:UV-based dechlorination systems are gaining technical validation at smaller treatment plants, threatening volume displacement in sub-municipal segments.
Strategic Opportunities
- Red Sea coastal logistics:Yanbu and Jeddah port infrastructure supports just-in-time liquid delivery models for desalination operators currently underserved by crystalline supply chains.
- Pharmaceutical certification premiums:SFDA GMP alignment opens margin expansion for producers willing to absorb compliance timeline costs that commodity traders avoid.
- Mining leaching applications:Gold extraction cyanide detoxification protocols are expanding in the Arabian Shield, creating new technical-grade demand outside water treatment.
Industry Challenges
- Analytical chemistry skill scarcity:Assay verification for pharmaceutical-grade batches requires specialized chromatography expertise concentrated in Riyadh and Dammam laboratories.
- SASO certification timelines:Industrial chemical import permits face processing delays that conflict with just-in-time delivery commitments to Red Sea utilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Sodium Thiosulphate Market |
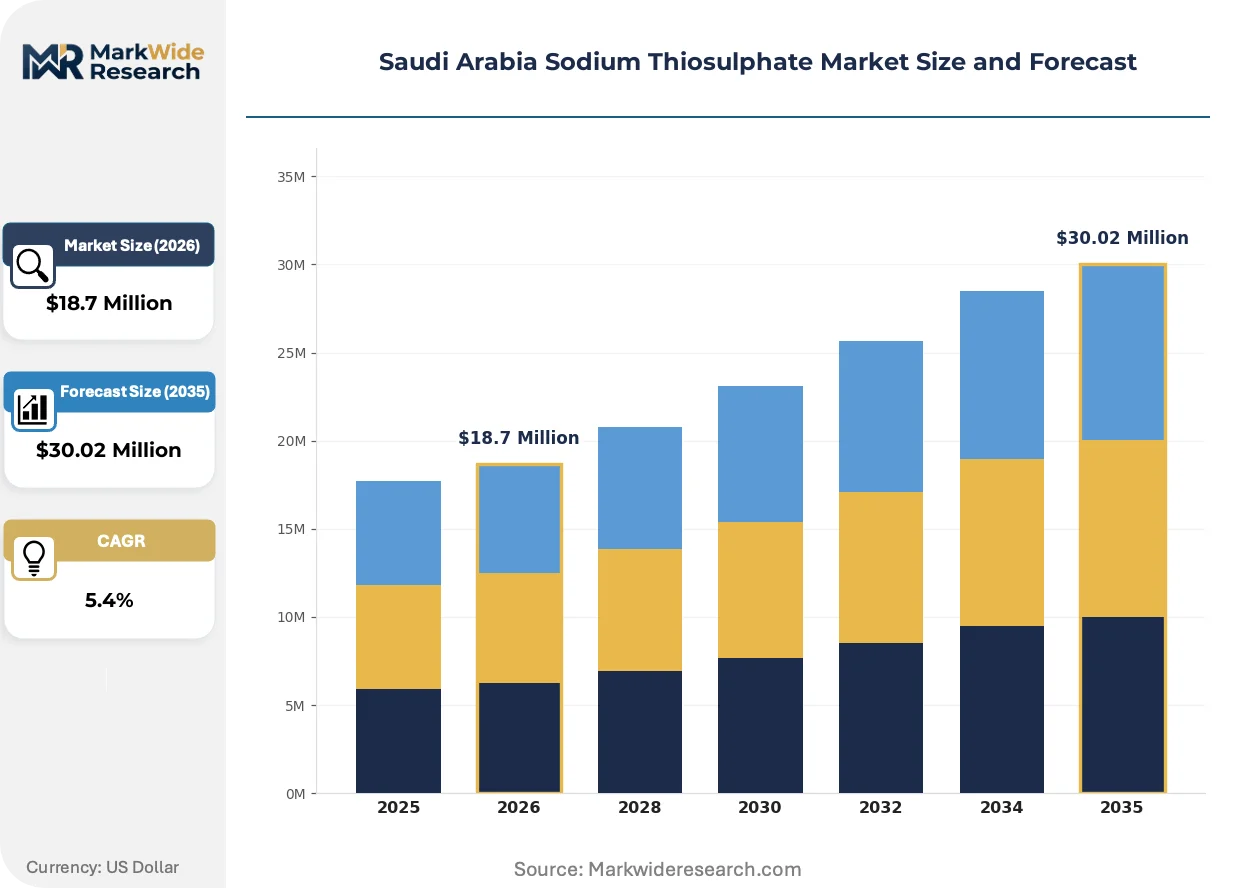
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $30.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline, Liquid, Powdered, Granular Application: Water Treatment, Pharmaceuticals, Photography, Chemical Synthesis End User: Agriculture, Mining, Textile, Food Processing Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | Saudi Basic Industries Corporation (SABIC), Fouz Chemical Company, Saudi (Overseas) Marketing & Trading Company (SOMATCO), AquaChemie Middle East, Chemsol, Al-Jubail Chemical Industries Company (JANA), National Chemical Company (NCC), Arabian Chemical Company Ltd. (ACC), Saudi Industrial Chemical Company (SICCO), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Sodium Thiosulphate Market Evolving Landscape
Process intensification and regulatory digitization are compressing traditional supply chain timelines. Technical-grade specifications are fragmenting into application-specific tiers.
Membrane-based crystallization systems are miniaturizing production footprints for mid-scale sodium thiosulphate synthesis. Water treatment contractors in Dammam and Jubail are piloting containerized units that bypass bulk import dependencies. This distributed manufacturing architecture is miniaturizing the minimum efficient scale for regional supply, enabling proximity sourcing to coastal desalination clusters.
SASO technical regulations for industrial chemical labelling are mandating QR-code traceability and Arabic safety data sheets. Importers must reconfigure packaging workflows to comply with digital disclosure requirements. Pharmaceutical-grade material faces parallel SFDA serialization mandates, with Riyadh-based distributors absorbing compliance system investments.
Long-term contracting is displacing spot purchasing among Eastern Province utilities. SWCC facilities are consolidating annual volumes with single-source liquid suppliers, compressing trader margins. This procurement consolidation is most advanced at Jubail industrial city installations, where Royal Commission environmental directives favor supply security over price flexibility.
Saudi Arabia Sodium Thiosulphate Market Segmentation
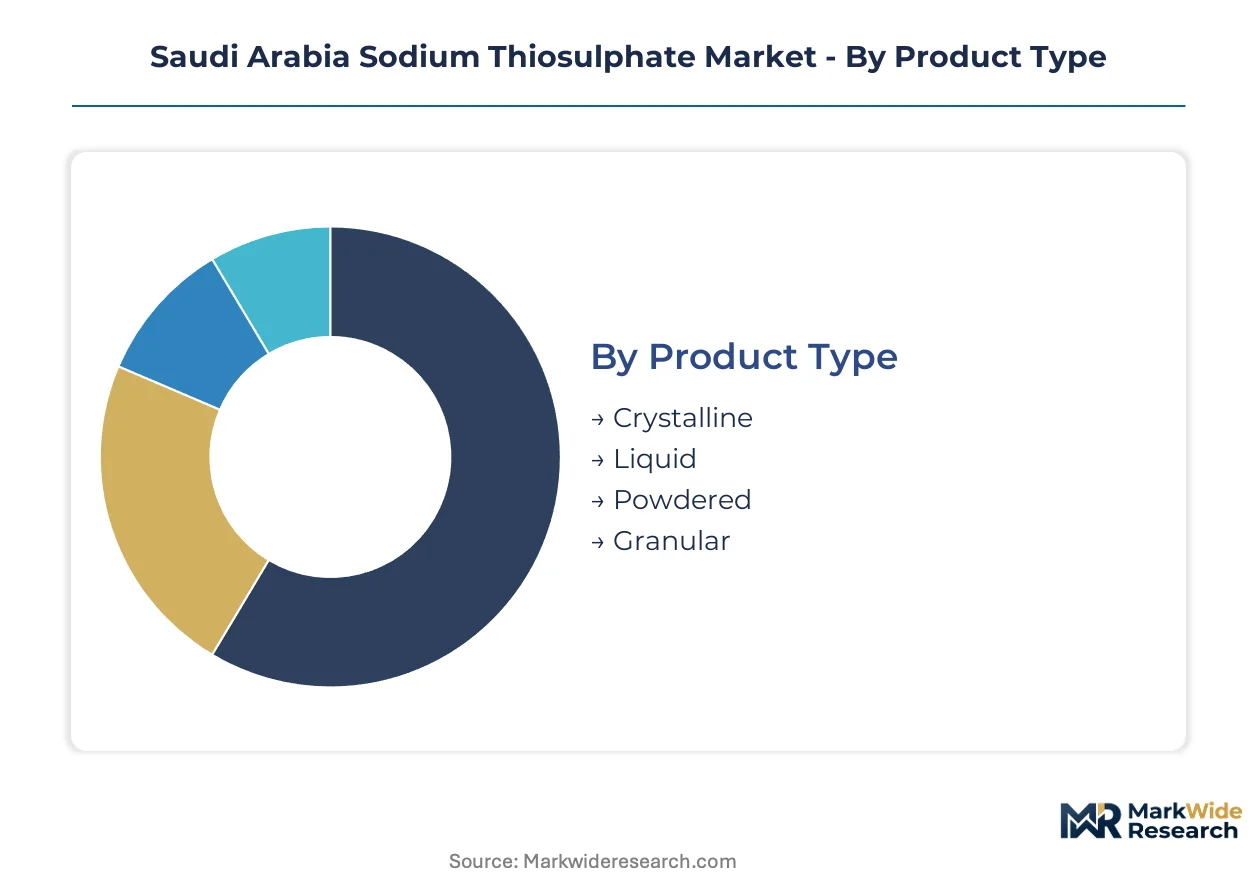
Product format, application purity, and channel logistics define competitive positioning in Saudi Arabia's sodium thiosulphate supply architecture. SFDA and SASO regulatory tiers fragment what appears chemically uniform into distinct margin pools.
Product Type:
Regulatory differentiation separates pharmaceutical-grade crystalline from industrial liquid formats, with SASO technical specifications governing labelling and SFDA mandates controlling injectable-grade certification.
- Crystalline:Pentahydrate salt (Na₂S₂O₃·5H₂O) assaying at 99% minimum purity serves pharmaceutical synthesis and analytical reagent markets. Eastern Province water utilities in Jubail and Dammam are shifting procurement toward liquid alternatives, compressing crystalline volume in municipal dechlorination.
- Liquid:Aqueous solutions at 30-50% concentration dominate bulk water treatment logistics. SWCC desalination facilities along the Red Sea coast favor tanker delivery over solid handling, pulling demand toward Yanbu and Jeddah port infrastructure.
- Powdered:Milled crystalline form with rapid dissolution kinetics targets food processing and agricultural formulations. Controlled-release applications in the Arabian Shield mining corridor use this format for cyanide detoxification protocols.
- Granular:Sized crystals for slow-release industrial processes occupy niche positions in textile bleaching neutralization. SASO import permits for this grade face fewer purity constraints than pharmaceutical categories.
Liquid handles the majority of throughput; powdered is expanding most quickly on share.
Application:
End-use concentration varies sharply across the Kingdom's industrial corridor, with water treatment procurement dwarfing specialty chemical offtake.
- Water Treatment:Dechlorination of SWCC desalination output and municipal distribution systems consumes bulk volumes. Royal Commission environmental directives for Jubail and Yanbu mandate residual chlorine neutralization before discharge.
- Pharmaceuticals:Injectable-grade material requires GMP-aligned manufacturing and SFDA batch certification. Riyadh-based distributors absorb chromatography assay costs that commodity traders avoid.
- Photography:Silver halide fixing applications have contracted as digital imaging displaced film processing. Remaining demand concentrates in specialized industrial radiography and archival restoration.
- Chemical Synthesis:Reducing agent applications in sulphur dye manufacture and analytical chemistry represent stable technical-grade offtake. SABIC petrochemical integration supplies captive feedstock to this segment.
Water treatment commands volume leadership; pharmaceuticals claims the steepest expansion trajectory on certification premiums.
End User:
Customer-type economics split between bulk commodity procurement and specification-driven specialty purchasing.
- Agriculture:Fungicide formulations and soil dechlorination in greenhouse operations near Riyadh and Qassim. Powdered and granular formats dominate this price-sensitive segment.
- Mining:Gold extraction cyanide detoxification in the Arabian Shield generates technical-grade demand outside water treatment. Containerized production pilots in Dammam target this application specifically.
- Textile:Bleaching neutralization and dye reduction in Jeddah industrial zones. Granular product with controlled dissolution rates matches batch process timing requirements.
- Food Processing:Antioxidant applications and chlorine removal in packaged goods manufacturing. SFDA food additive standards govern purity thresholds tighter than industrial grades.
Mining is gaining share fastest on leaching expansion; agriculture retains the widest format dispersion.
Distribution Channel:
Channel structure reflects the tension between bulk logistics efficiency and regulatory traceability requirements.
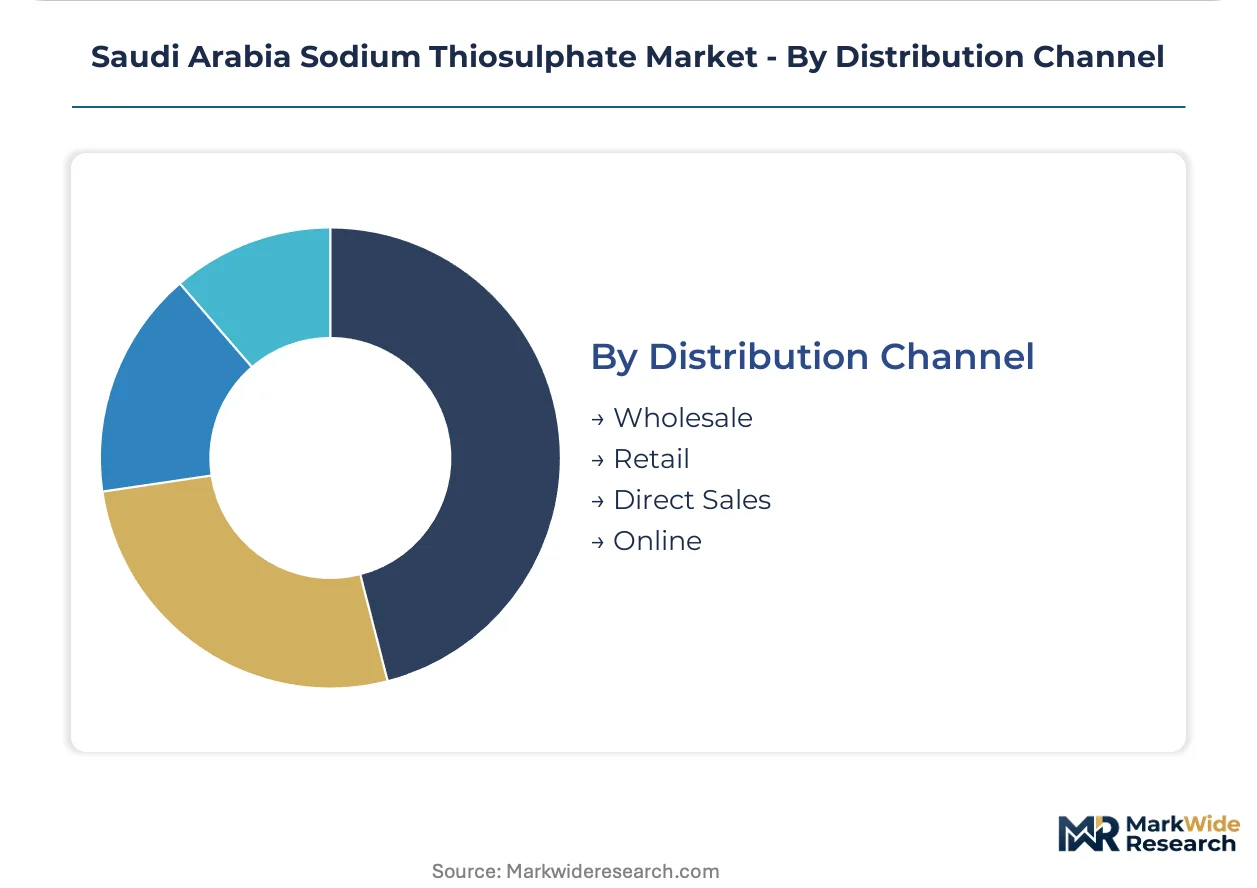
- Wholesale:Tanker and bulk bag distribution to Eastern Province industrial clusters. SABIC and integrated petrochemical players dominate this channel through captive supply.
- Retail:Packaged quantities for laboratory and small-scale agricultural users. SASO QR-code traceability mandates are reconfiguring packaging workflows for this channel.
- Direct Sales:Long-term contracting between SWCC facilities and single-source liquid suppliers. Royal Commission directives favor supply security over price flexibility at Jubail installations.
- Online:Digital procurement platforms for standardized technical-grade material. Arabic safety data sheet requirements complicate cross-border e-commerce fulfillment.
Direct sales captures the largest contract value; online is climbing the fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia exports sodium thiosulphate to Gulf Cooperation Council water utilities and Red Sea desalination projects. Trade flows concentrate through Yanbu and Jubail port infrastructure serving Egyptian and Jordanian buyers. Eastern Province production clusters supply technical-grade material to Arabian Shield mining operations.
Eastern Province
Jubail and Dammam industrial cities anchor domestic sodium thiosulphate manufacturing through petrochemical integration. Royal Commission environmental directives mandate residual chlorine neutralization at coastal desalination facilities. SABIC's captive sulphur derivatives feed regional thiosulphate synthesis, lowering input costs for integrated producers.
Riyadh
Central Region pharmaceutical distributors absorb SFDA batch certification costs for injectable-grade material. Chromatography assay verification requires specialized expertise concentrated in Riyadh and Dammam laboratories. National Chemical Company maintains technical-grade distribution networks serving Qassim agricultural greenhouse operations.
Western Region
Jeddah port infrastructure supports liquid sodium thiosulphate tanker delivery to Red Sea SWCC facilities. AquaChemie Middle East competes on bulk logistics and just-in-time supply to coastal utilities. SASO import permit processing delays conflict with procurement timelines at smaller treatment plants.
NEOM Northwest
Planned gigaproject desalination capacity will expand dechlorination chemical demand beyond existing supply chains. Containerized production pilots in Dammam target proximity sourcing to this underserved geography. Mining leaching applications in the adjacent Arabian Shield generate technical-grade offtake outside water treatment.
Saudi Arabia Sodium Thiosulphate Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and logistics capabilities. The Saudi market exhibits moderate concentration around petrochemical-integrated producers and regional distributors. Three archetypes dominate: captive sulphur-derivative manufacturers, technical-grade distributors to industrial clusters, and bulk liquid logistics operators. Competitive moves center on long-term contracting consolidation with SWCC facilities and pharmaceutical-grade certification investments.
Among petrochemical-integrated manufacturers, Saudi Basic Industries Corporation anchors the captive supply archetype through sulphur derivative control. Fouz Chemical Company and AquaChemie Middle East represent the distribution-logistics tier, with the former specializing in Eastern Province industrial clusters and the latter competing on Red Sea coastal delivery. These three exemplify how regulatory alignment and geographic positioning separate margin pools in a market where SFDA certification and SASO compliance create distinct competitive vectors.
| Leading Market Players |
|---|
| Saudi Basic Industries Corporation (SABIC) |
| Fouz Chemical Company |
| Saudi (Overseas) Marketing & Trading Company (SOMATCO) |
| AquaChemie Middle East |
| Chemsol |
| Al-Jubail Chemical Industries Company (JANA) |
| National Chemical Company (NCC) |
| Arabian Chemical Company Ltd. (ACC) |
| Saudi Industrial Chemical Company (SICCO) |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day crystalline inventory cycles at Eastern Province utilities compress pricing power for non-integrated distributors while amplifying margin capture for SABIC's captive sulphur-derivative operations. This lead-time band ties procurement flexibility directly to petrochemical integration depth across the Kingdom's industrial corridor.
Pricing Analysis
Current-generation liquid solution formats command 15-20% premia over legacy crystalline grades, with next-generation pharmaceutical-grade material widening this gap further under SFDA GMP mandates. Contract-based long-term offtake dominates SWCC procurement, compressing spot-market liquidity. Price differentiation rests on certification tier and volume scale, with pharmaceutical-grade buyers least sensitive and agricultural greenhouse operators most price-elastic. Cost compression in technical-grade crystalline supply intensifies as Jubail petrochemical integration deepens.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock security for Saudi producers while exposing non-integrated importers to bunker fuel volatility and customs clearance friction. Supply concentrates in Saudi Arabia, India, and China for crystalline material, with Germany and Switzerland anchoring pharmaceutical-grade import flows. Sulphur alkali, sodium carbonate, and sulphur dioxide constitute core inputs. Single-source vulnerability concentrates in Eastern Province production clusters. Distribution runs through tanker delivery to coastal utilities and bulk bag networks to inland industrial zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chromatography assay expertise scarcity in Riyadh and Dammam laboratories constrains pharmaceutical-grade batch certification velocity, creating bottlenecks that favor early compliance investors over commodity traders.
For Market Incumbents: Fortify long-term contracting positions with SWCC facilities before procurement consolidation hardens at Jubail and Yanbu installations. Absorb SFDA GMP certification timeline costs that traders cannot shoulder, locking in pharmaceutical-grade margin pools. Expand captive sulphur-derivative integration to defend against sulphur price volatility transmitted from Gulf refinery output fluctuations. For New Entrants and Emerging Players: Just-in-time liquid delivery gaps at Red Sea coastal facilities offer white-space entry points against crystalline-legacy supply chains. Target NEOM Northwest desalination capacity with containerized production pilots bypassing Eastern Province logistics chokepoints. Lead with Arabic safety data sheet compliance and SASO QR-code traceability as differentiated service capabilities. For Investors and Strategic Acquirers: Carve-out targets emerge from petrochemical majors seeking to monetize non-core sulphur-derivative operations. Long-term viability hinges on regulatory alignment depth rather than commodity scale. Watch SWCC desalination expansion timelines as the primary inflection signal for dechlorination chemical demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulphur Derivatives | SABIC's captive feedstock control lowers input costs below non-integrated competitors. |
| SFDA GMP Certification Investment | Chromatography assay capabilities open pharmaceutical-grade margin pools unavailable to commodity traders. |
| Containerized Production Deployment | Membrane crystallization pilots enable proximity sourcing to NEOM and Red Sea coastal utilities. |
| Long-term Supply Agreement with SWCC | Royal Commission directives favor supply security over price flexibility at Jubail installations. |
| Red Sea Logistics Infrastructure Expansion | Yanbu and Jeddah port capacity supports just-in-time liquid delivery models. |
Research Methodology
The analysis maps crystalline, liquid, powdered, and granular product tiers, each validated through water treatment procurement managers, pharmaceutical QA directors, petrochemical plant managers, and mining operations engineers. Primary fieldwork combined with SASO regulatory filings, SFDA certification databases, customs trade records, and SEC disclosures from listed chemical producers enabled bottom-up volume estimation and top-down market sizing triangulation.
Consistency checks against SWCC desalination expansion timelines and SABIC sulphur derivative output disclosures validated projection outputs across the analysis window. The forecasting framework modeled grade tier, end-use industry, packaging format, and regional production hub as core segmentation dimensions. CAGRs derived from installed capacity trajectories, regulatory mandate implementation schedules, and petrochemical integration economics.
Material uncertainties — sulphur price volatility, SASO certification processing delays, UV dechlorination substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions on regulatory timeline adherence and desalination capacity commissioning. Practitioners should keep alternative scenarios live as SFDA pharmaceutical mandate evolution and NEOM project sequencing clarify.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sorbic Acid Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Sodium Silicate Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Trimellitic Anhydride Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Ethylbenzene Market
Bulk Chemicals
Titanium Dioxide Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Dicyclopentadiene (DCPD) Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Sodium Sulphate Market
Bulk Chemicals
Bulk Chemical Packaging Market