
 Insulin Storage Devices Market | 2026-2036
Insulin Storage Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Insulin Storage Devices Market Intelligence
Subscription-based temperature monitoring software is repositioning how insulin storage devices create recurring revenue beyond hardware sales. Arkray Inc. leverages its diagnostic heritage to anchor credibility in precision cooling systems. ReadyCare LLC specializes in direct-to-consumer portable refrigeration for travel-intensive patients. DISIONCARE competes through pharmacy channel partnerships that extend its geographic footprint.
Insulin storage devices are engineered thermal management systems maintaining biologic potency between two and eight degrees Celsius through insulation, thermoelectric cooling, or compressor-based refrigeration. Active cooling technology dominates premium segments where battery-powered portability protects insulin during extended travel, while passive cooling occupies economy tiers relying on gel packs for shorter durations. Home care end users represent the fastest-growing demand pool as self-administration of insulin expands beyond clinical settings. Distribution through online retail channels captures margin pools by eliminating specialty store markups and enabling direct patient education.
FDA 21 CFR Part 211 guidelines and EMA Good Distribution Practice standards mandate documented temperature control across insulin handling, forcing manufacturers to integrate data-logging capabilities. ISO 13485 quality management systems govern design controls for medical device classification in major markets. Stakeholders must monitor evolving reimbursement codes for connected storage devices as payors weigh prevention of spoilage against upfront hardware costs.
Market Dynamics
Portable cooling systems are compressing the addressable market for stationary insulin storage as patients prioritize mobility over home-based refrigeration units. This shift forces manufacturers to reallocate R&D budgets toward battery efficiency and miniaturization while maintaining FDA and EMA thermal compliance.
Growth Catalysts
- Self-administration expansion:Home care settings now dominate insulin delivery as diabetes management moves beyond clinical supervision, creating sustained pull for patient-operated storage solutions.
- EMA Good Distribution Practice:Cold-chain documentation mandates across Europe force pharmacies and distributors to upgrade temperature-controlled infrastructure, expanding the installed base of compliant devices.
- Thermoelectric cooling modules:Solid-state refrigeration technology eliminates compressor maintenance and vibration, enabling lighter portable designs that meet airline cabin baggage restrictions.
Market Restraints
- Lithium-ion battery supply concentration:Cell production clusters in China and South Korea expose portable device manufacturers to raw material price volatility and export control risks.
- Reimbursement code gaps:Medicare and private payors in the United States classify most storage devices as durable medical equipment with limited coverage, forcing patients toward out-of-pocket purchases.
- Passive cooling substitutes:Gel-pack wallets and evaporative cooling pouches satisfy short-duration travel needs at price points below active refrigeration, capping premium segment expansion.
Strategic Opportunities
- India pharmacy modernization:CDSCO cold-chain guidelines and expanding diabetes prevalence create whitespace for mid-priced active cooling devices distributed through organized retail pharmacy chains.
- Subscription telemetry services:Continuous temperature monitoring software bundled with hardware generates recurring revenue while satisfying FDA 21 CFR Part 211 documentation requirements.
- Connected device integration:Bluetooth-enabled storage units that sync with glucose monitors and insulin pumps are capturing patient preference in Germany and Japan where digital health reimbursement is expanding.
Industry Challenges
- ISO 13485 certification timelines:Medical device quality management system audits extend product launch schedules by 12-18 months, compressing first-mover advantage windows.
- Multi-jurisdiction registration:Separate FDA 510(k), CE marking under MDR, and PMDA approvals fragment regulatory resources and delay geographic expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulin Storage Devices Market |
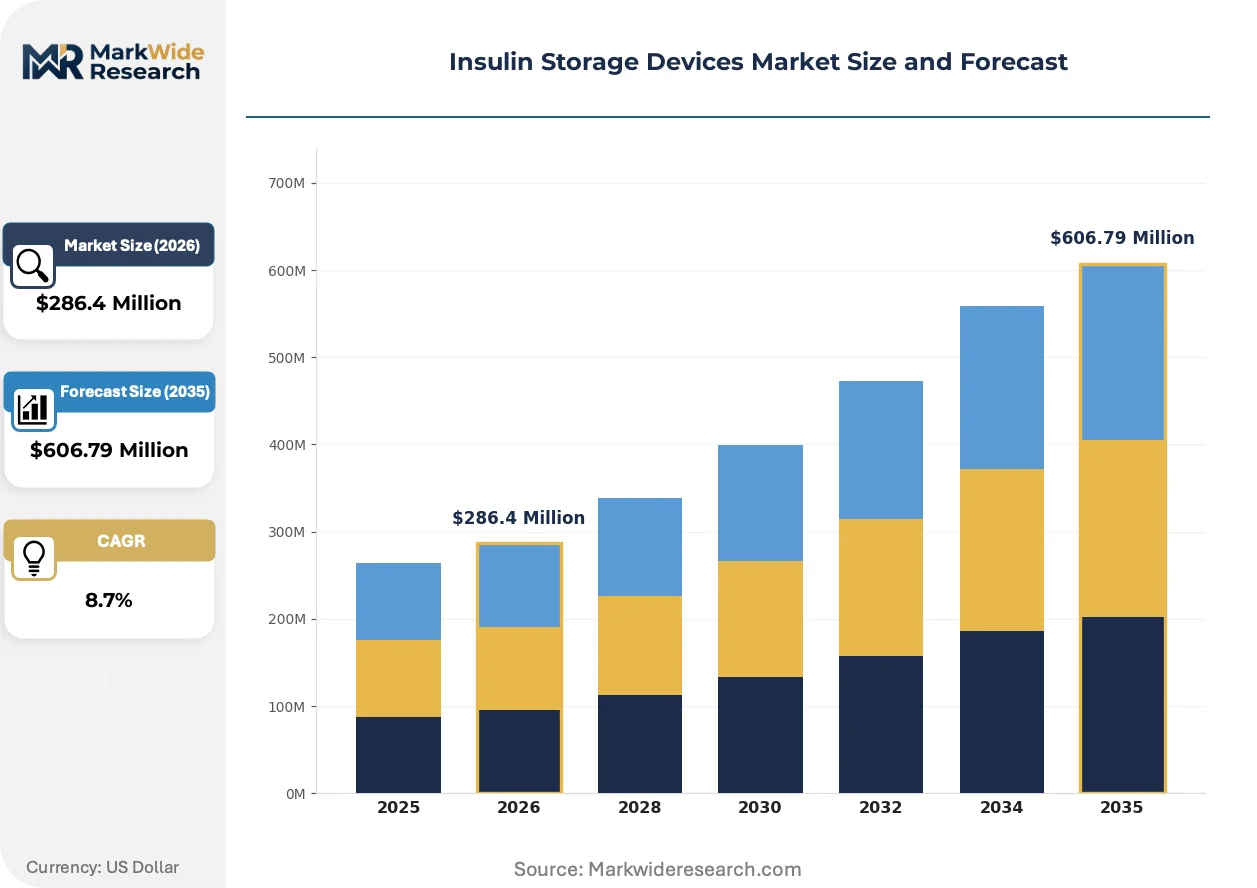
| Market Size in 2026 | $286.4 Million |
| Market Size in 2035 | $606.79 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Pens, Insulin Pumps, Coolers, Portable Refrigerators Technology: Thermal Insulation, Active Cooling, Passive Cooling, Refrigeration End User: Hospitals, Clinics, Home Care, Pharmacies Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Arkray Inc., Tawa Outdoor, ReadyCare LLC, Zhengzhou Defrigus Electric Device Co. Ltd., Zhengzhou Olive Electronic Technology Co. Ltd., DISIONCARE, Cooluli, COOL Sarl-FR, Medicool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulin Storage Devices Market Strategic Shifts & Innovations
Solid-state thermoelectric cooling is overtaking compressor-based systems as the dominant portable refrigeration architecture. This transition accelerates as battery chemistry improvements resolve prior energy density constraints.
Thermoelectric modules utilizing bismuth telluride semiconductors deliver precise temperature control without mechanical vibration that risks insulin denaturation. Frequent travelers and outdoor workers in the United States and Germany are adopting these devices faster than homebound patient segments. Solid-state architecture is overtaking compressor designs in units under five liters, collapsing the premium pricing tier that previously separated portable from stationary categories.
REACH restrictions on fluorinated refrigerants are forcing redesigns of compressor-based units sold in European Union markets. Manufacturers must substitute hydrofluorocarbon coolants with hydrocarbon or carbon dioxide alternatives, increasing unit cost and reducing energy efficiency. The F-Gas Regulation phase-down most impacts mid-capacity storage devices targeting pharmacy and clinic installations, pushing vendors toward thermoelectric alternatives or absorption cooling for larger units.
Direct-to-consumer online channels are displacing durable medical equipment suppliers as the primary patient acquisition path. Specialty diabetes retailers and Amazon Marketplace capture margin pools previously retained by clinical distributors, while enabling manufacturers to gather real-world usage data. This channel rotation is most visible in Japan and the United States where patient digital literacy and reimbursement self-management are highest among OECD markets.
Insulin Storage Devices Market Segmentation
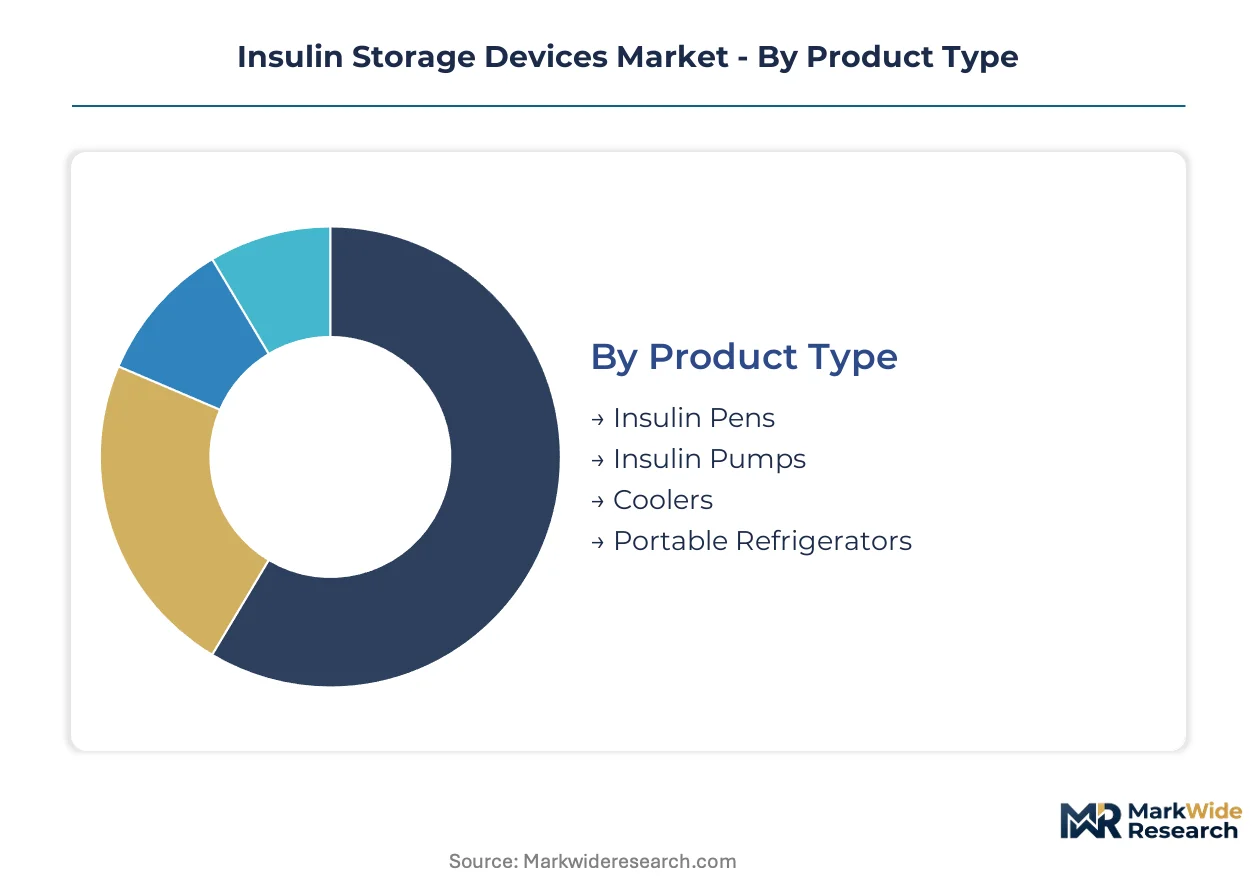
Segmentation in insulin storage devices separates commodity passive solutions from precision active cooling systems. Technology and end-use splits determine pricing architecture, regulatory burden, and channel economics.
Product Type:
Volume concentrates in portable formats while premium pricing attaches to integrated delivery systems.
- Insulin Pens:Disposable and reusable injection devices incorporating cartridge storage chambers. Demand clusters in Germany and Japan where pen-based therapy dominates outpatient diabetes management. FDA 510(k) clearance requirements for pen-integrated cooling add regulatory cost.
- Insulin Pumps:Continuous subcutaneous infusion systems with onboard insulin reservoirs requiring temperature-stable housing. Home care adoption in the United States drives replacement cycles as patients upgrade to Bluetooth-connected models.
- Coolers:Insulated carrying cases for vial and pen transport. Gel-pack dependent designs serve price-sensitive travel segments across pharmacy retail channels.
- Portable Refrigerators:Battery-powered thermoelectric or compressor units maintaining 2-8°C during extended travel. Airline cabin baggage compliance and TSA screening protocols shape form factor constraints.
Mature deployment sits with Coolers. Newer deployment is concentrated in Portable Refrigerators.
Technology:
Cost tier stratification runs from disposable gel systems to solid-state electronics with data-logging capabilities.
- Thermal Insulation:Vacuum-panel or high-R-value foam barriers extending passive temperature stability. Hospital bulk storage applications in Japan leverage this for energy efficiency in centralized pharmacy operations.
- Active Cooling:Thermoelectric Peltier modules or micro-compressors powered by lithium-ion cells. Germany's EMA cold-chain documentation requirements accelerate adoption of data-logging active systems in outpatient settings.
- Passive Cooling:Phase-change materials and evaporative media requiring no electrical input. Short-duration travel in the United States sustains demand despite temperature excursion risks.
- Refrigeration:Compressor-based mechanical cooling for stationary high-capacity installations. Clinic and pharmacy infrastructure in India faces CDSCO cold-chain upgrade pressures favoring this category.
Passive Cooling dominates unit volume. Active Cooling is gaining share fastest.
End User:
Application context determines device specification, from clinical-grade documentation to consumer portability.
- Hospitals:Centralized pharmacy storage with networked temperature monitoring and alarm systems. JIS standards compliance in Japanese tertiary facilities mandates redundant cooling backup.
- Clinics:Point-of-care inventory for same-day patient administration. EMA Good Distribution Practice audits across European outpatient clinics drive replacement of non-compliant legacy units.
- Home Care:Patient-operated storage for daily insulin self-administration. Medicare reimbursement gaps in the United States force out-of-pocket purchase decisions toward lower-cost passive alternatives.
- Pharmacies:Dispensing counter storage and patient counseling on transport protocols. Organized retail chains in India expand cold-chain capacity under CDSCO distribution guidelines.
Hospital procurement is stabilizing. Home Care shows the steepest expansion trajectory.
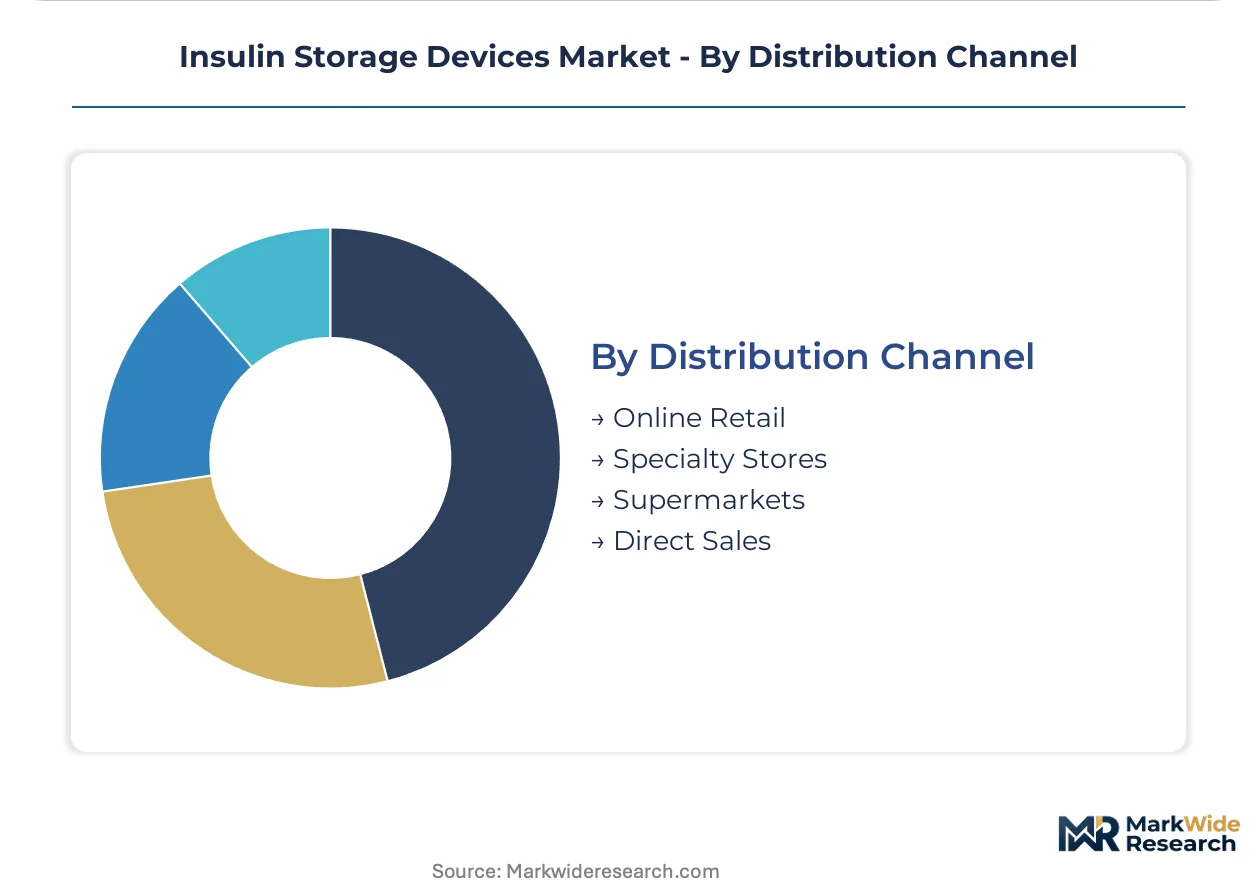
Distribution Channel:
Margin capture shifts from clinical distributors to direct-to-consumer platforms as patient self-management expands.
- Online Retail:Amazon Marketplace and diabetes specialty e-commerce capturing price comparison behavior. Patient education content and review systems reduce specialty store dependency.
- Specialty Stores:Durable medical equipment suppliers with fitting services and insurance billing support. United States Medicare documentation requirements sustain this channel for reimbursed purchases.
- Supermarkets:Mass retail placement of basic coolers and gel packs. Convenience positioning targets impulse travel purchases in Japan's urban pharmacy-integrated retail.
- Direct Sales:Manufacturer-owned channels for subscription telemetry services and premium portable units. Arkray Inc. and DISIONCARE deploy field teams for clinic and pharmacy account management.
Specialty Stores retain the highest average selling prices. Online Retail is capturing volume growth fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors North American insulin storage innovation through its concentration of diabetes device R&D clusters and proximity to FDA regulatory infrastructure.
United States
Home care self-administration and Medicare reimbursement gaps drive patient out-of-pocket spending on portable cooling solutions. FDA 21 CFR Part 211 mandates temperature documentation across distribution chains. The Boston-Cambridge corridor hosts connected device startups integrating Bluetooth telemetry with glucose monitoring ecosystems.
Germany
Pen-based therapy dominance and EMA Good Distribution Practice audits accelerate pharmacy upgrades to data-logging active cooling systems. REACH and F-Gas Regulation restrictions force refrigerant redesigns in compressor-based units. The Rhine-Ruhr industrial belt concentrates thermoelectric module assembly operations serving outpatient clinic networks.
Japan
Aging demographics and digital health reimbursement expansion pull Bluetooth-enabled storage units into patient preference. PMDA medical device approvals and JIS standards compliance govern tertiary hospital procurement. The Kanto region around Tokyo houses precision cooling manufacturers supplying centralized pharmacy operations.
India
Organized retail pharmacy chains expand cold-chain capacity under CDSCO distribution guidelines. Diabetes prevalence growth and pharmacy modernization create whitespace for mid-priced active cooling devices. Mumbai and Delhi-NCR serve as distribution hubs for domestic manufacturers targeting tier-1 city hospital networks.
United Kingdom
NHS procurement frameworks prioritize cost-effective passive cooling for short-duration patient transport. MHRA post-Brexit regulatory alignment with MDR extends CE marking transition timelines. The Oxford-Cambridge arc hosts diagnostic heritage companies diversifying into precision temperature management systems.
Insulin Storage Devices Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a fragmented vendor base where no single entity commands dominant share. The market stratifies into three tiers: diagnostic heritage conglomerates leveraging clinical credibility, direct-to-consumer specialists capturing travel-intensive patient segments, and contract manufacturers supplying private-label pharmacy channels. Consolidation pressure intensifies as M&A activity concentrates connected device capabilities and geographic expansion through distributor acquisitions accelerates.
Within the diagnostic heritage tier, Arkray Inc. exemplifies clinical credibility anchoring. Among direct-to-consumer specialists, ReadyCare LLC and Cooluli occupy positions targeting travel-intensive patient demand. Contract manufacturing concentration appears in Zhengzhou-based entities including Zhengzhou Defrigus Electric Device Co. Ltd. and Zhengzhou Olive Electronic Technology Co. Ltd., representing cost-optimized production archetypes serving pharmacy channel private-label programs.
| Leading Market Players |
|---|
| Arkray Inc. |
| Tawa Outdoor |
| ReadyCare LLC |
| Zhengzhou Defrigus Electric Device Co. Ltd. |
| Zhengzhou Olive Electronic Technology Co. Ltd. |
| DISIONCARE |
| Cooluli |
| COOL Sarl-FR |
| Medicool |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists in Zhengzhou and Shenzhen anchor tier-two production, combining legacy thermoelectric manufacturing with tight working-capital discipline that buffers pricing volatility while constraining R&D reinvestment. Their ownership structure locks in long-term supplier relationships with bismuth telluride refiners, creating procurement rigidity that premium brands exploit through backward integration into semiconductor cooling modules.
Pricing Analysis
Outcome-based pricing anchored to insulin spoilage prevention commands 40-60% premiums over commodity cooling tiers across German and Japanese outpatient markets. Three-tier pricing structure across premium, standard, and economy levels separates Bluetooth-enabled data-logging units from basic thermoelectric designs and gel-pack passive alternatives. Cost compression in economy tiers is intensifying because Chinese contract manufacturers are absorbing lithium-ion cell price volatility to maintain pharmacy channel share. Home care patients in the United States exhibit highest price sensitivity due to Medicare reimbursement gaps, while hospital procurement committees in Japan demonstrate lowest sensitivity given JIS-mandated redundancy requirements.
Supply Chain Analysis
Freight cost escalation on lithium-ion cells shipped from South Korean and Japanese battery plants is compressing margins for portable device assemblers in China's Pearl River Delta. Bismuth telluride semiconductors, vacuum insulation panels, and precision temperature sensors draw from concentrated East Asian supply bases. Single-source vulnerability in rare-earth-doped semiconductor substrates exposes manufacturers to export licensing delays from Chinese customs authorities. Distribution runs through organized retail pharmacy chains in India and direct-to-consumer platforms in the United States, with specialty durable medical equipment suppliers retaining clinical channel control for reimbursed purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around connected-device capabilities as ISO 13485 certification timelines and multi-jurisdiction registration costs force sub-scale players toward exit or acquisition.
For Market Incumbents: Cement defensible positioning through captive production of thermoelectric modules in the Rhine-Ruhr corridor, insulating margin structure from raw material volatility while accelerating CE marking under MDR for integrated delivery systems. Acquire distressed telemetry software assets to bundle subscription revenue with hardware sales, countering direct-to-consumer entrants eroding pharmacy channel premiums. For New Entrants and Emerging Players: Amazon Marketplace and diabetes specialty e-commerce offer lowest-friction patient acquisition paths for travel-focused portable refrigerators targeting United States self-pay segments. White-space concentrates in mid-priced active cooling devices for India's organized retail pharmacy chains, where CDSCO cold-chain upgrades outpace domestic manufacturing capacity. Partner with airline cabin baggage compliance consultants to accelerate TSA-friendly form factor development. For Investors and Strategic Acquirers: Distressed-cycle entries favor diagnostic heritage conglomerates with dormant cooling divisions in Japan and Germany, where PMDA and EMA regulatory infrastructure can be reactivated for connected device launches. Long-term viability hinges on software companion revenue attaching to hardware installed base. Watch for inflection when Medicare issues dedicated reimbursement codes for temperature-documented storage, unlocking United States home care volume.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance separates premium active cooling systems from non-compliant legacy clinic inventory across German outpatient networks. |
| Software Companion Development | Bluetooth-enabled temperature telemetry satisfies FDA 21 CFR Part 211 documentation mandates while generating recurring subscription revenue. |
| Hospital System Partnership | JIS-compliant redundant cooling backup contracts anchor long-term procurement relationships with Japanese tertiary facility pharmacy operations. |
| Reimbursement Strategy | Medicare durable medical equipment code advocacy determines United States home care patient out-of-pocket exposure and volume elasticity. |
| Backward Integration | In-house bismuth telluride module production insulates margin structure from Chinese rare-earth export licensing volatility. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving diabetes device product managers, hospital biomedical engineers, pharmacy procurement leads, and GPO contracts managers. FDA 510(k) databases, EMA Good Distribution Practice audit reports, PMDA medical device registration filings, and CDSCO cold-chain guidance documents supplied validation benchmarks. Bottom-up unit shipment estimates by technology tier and top-down market value reconciliation triangulated final outputs.
Granularity-level modeling tracked portable versus stationary form factors, thermoelectric versus compressor versus passive cooling architectures, and home care versus hospital versus pharmacy end-use segments across the projection horizon. CAGRs derived from patient population growth, self-administration penetration curves, and regulatory compliance upgrade cycles. Forecast inputs incorporated airline cabin baggage restriction evolution, lithium-ion energy density improvement trajectories, and digital health reimbursement expansion patterns.
The model holds under stable regulatory enforcement of FDA and EMA cold-chain documentation; deviation in Medicare reimbursement policy or REACH refrigerant phase-down acceleration would shift volume trajectories between active and passive cooling tiers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Blood Collection Devices Market
Medical Devices
Internal Trauma Fixation Device Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market
Medical Devices
Coronary Angiography Devices Market
Medical Devices
Drug Delivery Systems Market
Medical Devices
Surgical Mesh Market
Medical Devices
Asia-Pacific Respiratory Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Arteriosclerosis Detector Market
Medical Devices
Interlaminar Device Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Cannula Market
Medical Devices
Erectile Dysfunction Shockwave Generators Market
Medical Devices
Surgical Integration Systems Market