
 Implantable Neurostimulators Market | 2026-2036
Implantable Neurostimulators Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Neurostimulators Market Intelligence
Closed-loop neurostimulation architectures with embedded biosensors and adaptive algorithms is fragmenting traditional open-loop device paradigms across the industry. Medtronic leverages its integrated manufacturing infrastructure to sustain dominance in deep brain stimulation systems for movement disorders. Abbott anchors its competitive stance through rechargeable battery platforms that extend device longevity and reduce surgical replacement cycles.
Implantable neurostimulators are active electronic medical devices that deliver precisely modulated electrical impulses to targeted neural structures via lead electrodes, typically incorporating pulse generators with lithium-ion or inductive charging systems to treat refractory neurological conditions. Spinal cord stimulators occupy the largest revenue pool within pain management applications, while vagus nerve stimulators for epilepsy represent the fastest-expanding segment driven by pediatric indication expansions. Wireless and rechargeable technologies are concentrating margin pools as manufacturers differentiate through reduced surgical burden and improved patient compliance metrics.
FDA premarket approval pathways and the EU Medical Device Regulation (MDR) impose stringent clinical evidence requirements that shape product development timelines and market access strategies for active implantable devices. ISO 14708 standards for active implantable medical devices establish baseline electrical safety and electromagnetic compatibility thresholds that manufacturers must satisfy across jurisdictions. Stakeholders must monitor evolving reimbursement coding decisions by CMS and national health technology assessment bodies, as these determinations will dictate commercial viability faster than regulatory clearance alone.
Market Dynamics
Closed-loop neurostimulation architectures with embedded biosensors and adaptive algorithms are fragmenting traditional open-loop device paradigms across the industry. This technological shift is compressing product development cycles while elevating clinical evidence requirements for regulatory clearance.
Growth Catalysts
- FDA-EMA Harmonization:Streamlined premarket approval pathways for active implantable medical devices are reducing redundant clinical trials and accelerating cross-border commercialization timelines.
- Chronic Pain Epidemiology:Hospital settings are expanding spinal cord stimulator programs as opioid-sparing alternatives gain institutional priority in post-surgical and neuropathic pain protocols.
- Pediatric Epilepsy Indications:Vagus nerve stimulator label expansions for drug-resistant seizure disorders are opening addressable patient populations previously excluded from neuromodulation therapy.
Market Restraints
- Lithium-Ion Supply Concentration:Pulse generator battery sourcing depends on concentrated Asian refining capacity, exposing manufacturers to raw material volatility and geopolitical disruption risks.
- EU MDR Compliance Burden:The Medical Device Regulation's enhanced clinical evidence requirements for Class III active implantables are extending certification timelines and inflating regulatory affairs overhead.
- Non-Invasive Neurostimulation:Transcutaneous electrical nerve stimulation devices and non-invasive vagus nerve stimulation systems present substitution threats for mild-to-moderate indications.
Strategic Opportunities
- Japan Reimbursement Expansion:METI and PMDA are broadening national health insurance coverage for deep brain stimulation in movement disorders, creating accessible volume pools for manufacturers.
- Wireless Power Transfer Convergence:Inductive charging platforms combined with miniaturized lead electrodes are enabling fully implantable systems without transcutaneous ports.
- Germany's Digital Health Act:DiGA fast-track pathways for software-integrated neurostimulation systems are accelerating market access for algorithm-augmented devices.
Industry Challenges
- Electromagnetic Compatibility Certification:ISO 14708-3 testing for active implantable devices requires specialized anechoic chamber infrastructure and extended validation protocols that compress development bandwidth.
- Biocompatibility Polymer Sourcing:Lead insulation materials meeting ISO 10993 standards face qualified supplier scarcity, forcing dual-sourcing investments and inventory carrying costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Neurostimulators Market |
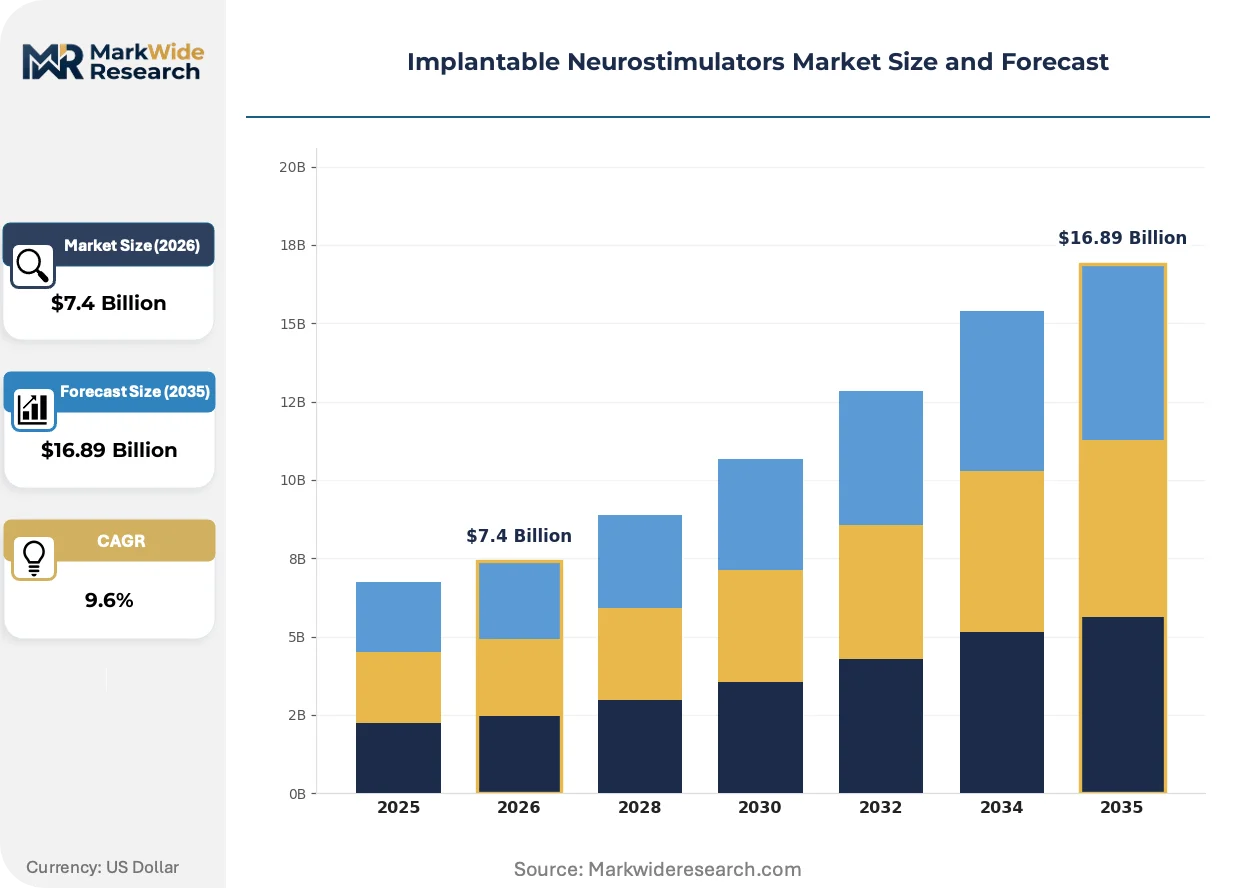
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $16.89 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Deep Brain Stimulators, Spinal Cord Stimulators, Vagus Nerve Stimulators, Sacral Nerve Stimulators End User: Hospitals, Rehabilitation Centers, Homecare Settings, Outpatient Clinics Technology: Non-Invasive, Minimally Invasive, Wireless, Rechargeable Application: Pain Management, Movement Disorders, Epilepsy, Depression |
| Companies Covered | Medtronic, Abbott, Boston Scientific Corporation, LivaNova PLC, Nevro Corp, NeuroPace, Inc., Inspire Medical Systems, Inc., Aleva Neurotherapeutics, Synapse Biomedical Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Neurostimulators Market Strategic Shifts & Innovations
Neurostimulator architectures are converging toward intelligent, adaptive systems that respond to real-time physiological feedback rather than delivering fixed stimulation protocols. This evolution is compressing the gap between diagnostic sensing and therapeutic intervention.
Biosensor-embedded lead arrays with local field potential recording capability are digitizing the therapeutic loop in movement disorder applications. Deep brain stimulation systems in academic medical centers are adopting these platforms to correlate neural biomarkers with motor symptom fluctuations. The technology is digitizing how clinicians optimize stimulation parameters, shifting from empirical programming to data-driven personalization.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic long-term safety registries for active implantables. Manufacturers must now maintain active implantable device identification systems traceable across the supply chain and clinical use. Spinal cord stimulator portfolios face the steepest compliance burden given their installed base scale and diverse lead configurations.
Hospital procurement committees are consolidating neurostimulator vendor relationships to standardize programming interfaces and reduce clinical training overhead. Integrated delivery networks are replacing fragmented physician preference item purchasing with single-source contracts spanning multiple neuromodulation modalities. This concentration is most visible in United States health systems where CMS bundled payment models incentivize device standardization.
Implantable Neurostimulators Market Segmentation
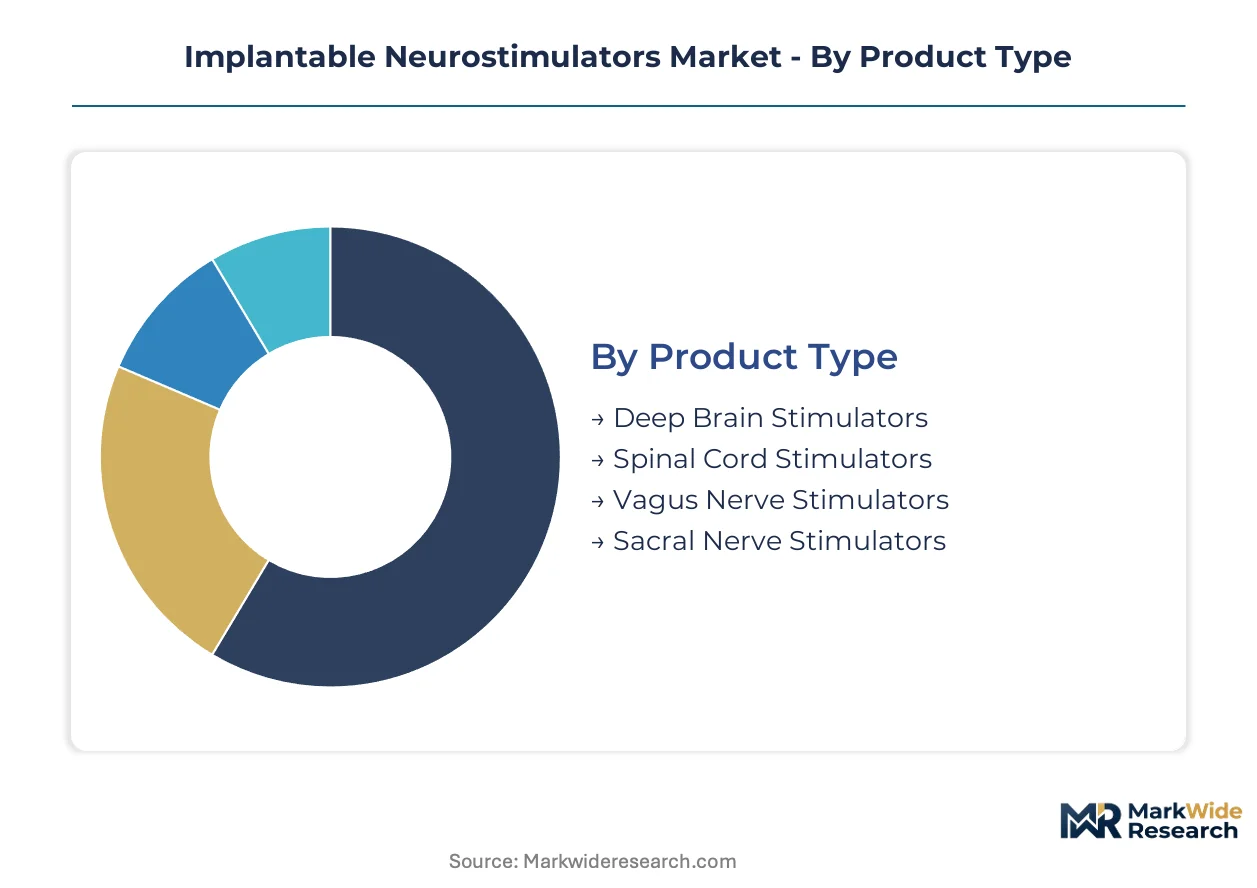
Implantable neurostimulators serve distinct clinical workflows that reshape how manufacturers configure pulse generator specifications and lead electrode arrays. Segmentation reveals where technology investments concentrate and which patient populations unlock commercial viability.
Product Type:
Use cases span movement disorders, chronic pain, epilepsy, and pelvic dysfunction—each demanding specialized anatomical targeting and stimulation protocols.
- Spinal Cord Stimulators:Lead arrays with 8-16 contact configurations deliver epidural electrical pulses to dorsal column fibers for neuropathic and ischemic pain syndromes. Hospital pain management departments in the United States and Germany are expanding SCS programs as opioid-sparing protocols gain institutional priority.
- Deep Brain Stimulators:Quadripolar leads with sub-millimeter precision target basal ganglia structures for Parkinson's disease and essential tremor. Japan's METI reimbursement expansion for movement disorders is accelerating volume uptake in academic medical centers.
- Vagus Nerve Stimulators:Bipolar helical electrodes wrap around the left cervical vagus nerve for drug-resistant epilepsy.
- Sacral Nerve Stimulators:Tined lead placement at S3 foramina addresses refractory overactive bladder and fecal incontinence.
The dominant share belongs to spinal cord stimulators, while vagus nerve stimulators are closing the gap fastest.
End User:
Care delivery settings determine device complexity, programming infrastructure, and reimbursement pathway design.
- Hospitals:Tertiary centers with dedicated neuromodulation suites manage complex lead implantation and parameter optimization for movement disorders. CMS bundled payment models in the United States are consolidating vendor relationships around standardized programming interfaces.
- Outpatient Clinics:Ambulatory surgical centers perform spinal cord stimulator trials and permanent implants under local anesthesia. Germany's Digital Health Act DiGA pathways enable software-integrated follow-up outside hospital walls.
- Rehabilitation Centers:Post-acute facilities manage stimulation parameter titration and patient training.
- Homecare Settings:Remote programming platforms and patient controllers enable chronic disease management outside clinical facilities.
Hospital systems capture the largest procedure volume, though outpatient clinics are expanding their share through minimally invasive protocols.
Technology:
Power delivery and surgical invasiveness define competitive differentiation and patient compliance economics.
- Rechargeable:Lithium-ion pulse generators with inductive charging coils extend device longevity beyond 15 years. Abbott's platform strategy centers on rechargeable architectures that reduce surgical replacement burden.
- Wireless:Fully implantable systems eliminate transcutaneous ports through resonant inductive power transfer. Japan's PMDA fast-track reviews favor wireless platforms that minimize infection risk.
- Minimally Invasive:Percutaneous lead placement via Touhy needles reduces operative time and recovery.
- Non-Invasive:Transcutaneous alternatives compete for mild-to-moderate indications outside implantable markets.
Rechargeable systems hold the installed base advantage, yet wireless platforms are climbing the fastest as miniaturization converges with power efficiency gains.
Application:
Indication-specific regulatory pathways and reimbursement coding determine commercial access and development investment priority.
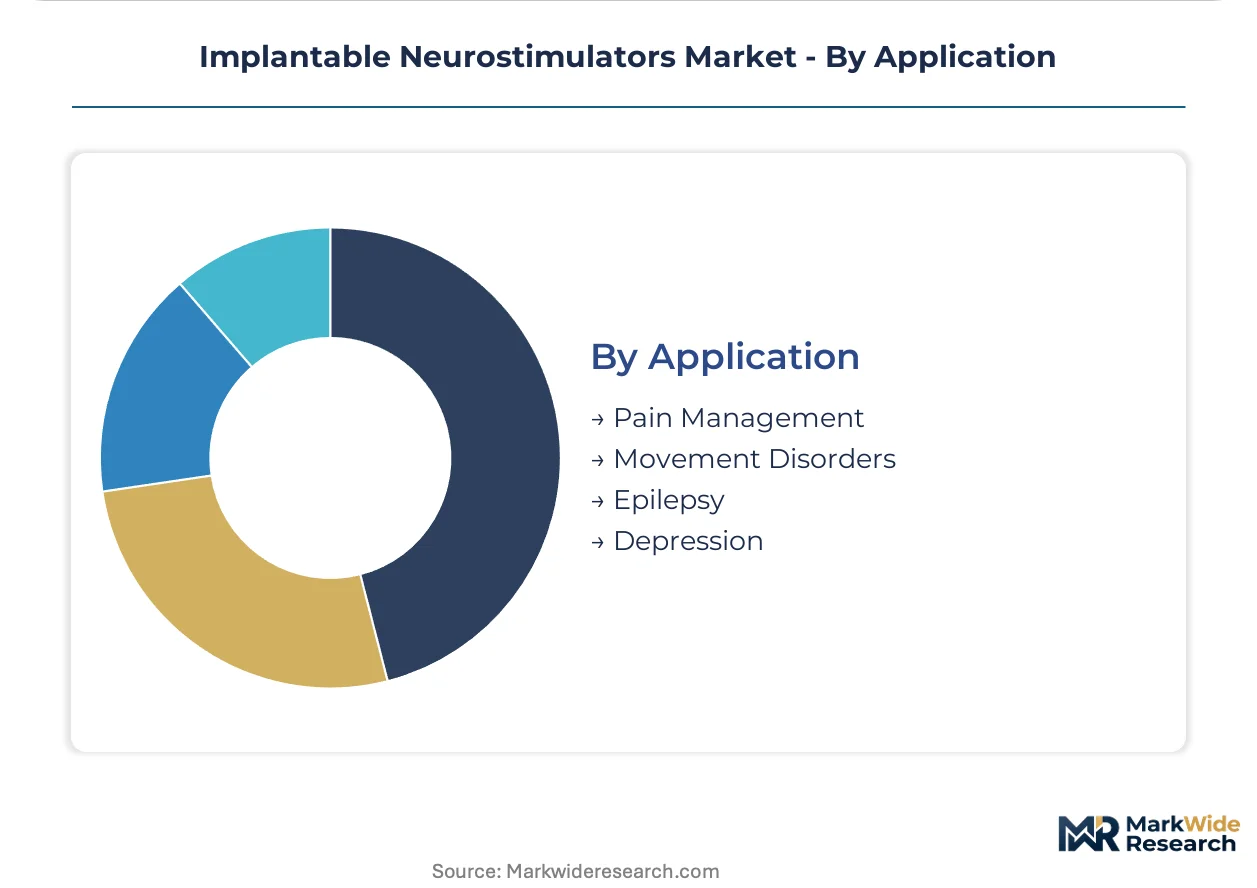
- Pain Management:Failed back surgery syndrome and complex regional pain syndrome drive spinal cord stimulator utilization. FDA premarket approval pathways for novel pain indications require rigorous randomized controlled trials.
- Epilepsy:Drug-resistant seizure disorders in pediatric and adult populations expand vagus nerve stimulator addressable markets. EMA pediatric investigation plans mandate systematic age-stratified efficacy data.
- Movement Disorders:Parkinson's disease, essential tremor, and dystonia anchor deep brain stimulator demand.
- Depression:Treatment-resistant major depressive disorder represents an emerging indication with evolving evidence standards.
Pain management commands the deepest revenue pool, while epilepsy applications are gaining share fastest through pediatric label expansions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing corridors for implantable neurostimulators flow from Switzerland and Ireland toward hospital systems in Germany, Japan, and the United States. These trade routes concentrate high-value pulse generator production near European regulatory hubs while serving Asia-Pacific demand centers.
United States
FDA premarket approval pathways for active implantable medical devices anchor North American regulatory stringency. CMS bundled payment models incentivize hospital consolidation around standardized neuromodulation vendors. The Minneapolis medical device cluster sustains deep brain stimulation manufacturing alongside spinal cord stimulator R&D facilities.
Germany
Hospital pain management departments expand spinal cord stimulator programs as opioid-sparing protocols gain institutional priority. The EU Medical Device Regulation's Class III active implantable requirements shape certification timelines for manufacturers serving German markets. The Baden-Württemberg precision engineering corridor concentrates lead electrode manufacturing and pulse generator assembly operations.
Japan
METI reimbursement expansion for movement disorders accelerates deep brain stimulator volume uptake in academic medical centers. PMDA fast-track reviews favor wireless neurostimulation platforms that minimize surgical infection risk. The Tokyo-Osaka medical technology corridor hosts regional headquarters for multinational neuromodulation manufacturers.
Switzerland
Swissmedic regulatory alignment with EMA standards streamlines cross-border commercialization for active implantable devices. The country's precision manufacturing heritage supports miniaturized pulse generator production and biosensor-embedded lead arrays. The Basel-Zurich medtech cluster concentrates European headquarters functions for global neurostimulation manufacturers.
Ireland
IDA Ireland investment incentives attract European manufacturing operations for implantable medical devices serving EMA-regulated markets. The country's regulatory affairs infrastructure supports MDR compliance documentation for Class III active implantables. The Galway medical technology hub hosts contract manufacturing for pulse generator subassemblies and lead insulation systems.
Implantable Neurostimulators Market Key Industry Players
On the supply side, the industry is consolidating around integrated manufacturers with captive battery technology and proprietary lead electrode platforms. Three strategic archetypes dominate: diversified medical technology conglomerates with neuromodulation divisions, pure-play neurostimulation specialists with rechargeable platforms, and emerging wireless system developers. Competitive moves center on M&A for biosensor capabilities and strategic partnerships for algorithm-augmented closed-loop systems.
Within the diversified conglomerate tier, Medtronic and Abbott exemplify scale-driven positioning through integrated manufacturing infrastructure and multi-modality neuromodulation portfolios. Boston Scientific Corporation occupies a position between diversified scale and specialist focus with its rechargeable spinal cord stimulator platforms. These three entities anchor the competitive structure through distinct technology vectors rather than overlapping market coverage.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| Boston Scientific Corporation |
| LivaNova PLC |
| Nevro Corp |
| NeuroPace, Inc. |
| Inspire Medical Systems, Inc. |
| Aleva Neurotherapeutics |
| Synapse Biomedical Inc. |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery cell production concentrates in South Korea and Japan, anchoring margin pools in pulse generator manufacturing while downstream pricing power fragments across hospital procurement committees and integrated delivery networks.
Pricing Analysis
Next-generation wireless neurostimulation platforms command premium positioning over rechargeable current-generation systems and legacy primary-cell devices. Three-tier pricing structure across closed-loop adaptive, standard rechargeable, and economy non-rechargeable levels separates clinical outcomes from basic pain management. Price differentiation hinges on FDA breakthrough device designation and ISO 14708-3 electromagnetic compatibility certification tier. Cost compression in standard rechargeable tiers is intensifying because hospital GPO contracts consolidate volume around single-source vendors. Academic medical centers show lowest price sensitivity for closed-loop systems with embedded biosensors, while ambulatory surgical centers prioritize per-procedure economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days characterize supplier-financing arrangements as manufacturers manage working capital through supply-chain finance facilities. Pulse generator assembly draws from Switzerland, Ireland, and Malaysia for miniaturized electronics and lead insulation polymers. Raw material dependencies center on lithium-ion cathode materials, platinum-iridium electrode alloys, and biocompatible silicone elastomers. Single-source vulnerability in qualified polymer suppliers meeting ISO 10993 standards forces dual-sourcing investments. Distribution runs through regional distribution centers serving hospital systems and specialized neuromodulation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remote programming platforms and algorithm-augmented parameter optimization services expand recurring revenue faster than hardware replacement cycles, transforming device economics toward subscription-like attach rates.
For Market Incumbents: Harden closed-loop algorithm IP through strategic biosensor acquisitions and deepen backward integration into lithium-ion cell manufacturing to offset Asian supply concentration. Non-invasive vagus nerve stimulation substitutes threaten mild epilepsy indications, demanding defensive indication expansion into treatment-resistant depression. Lock in hospital system sole-source contracts before CMS bundled payment models consolidate vendor relationships further. For New Entrants and Emerging Players: Establish a beachhead in wireless power transfer platforms where miniaturization gaps favor nimble engineering teams over legacy manufacturing infrastructure. Japan's METI reimbursement expansion for movement disorders offers the most penetrable geography for novel deep brain stimulation entrants lacking installed base scale. Lead with PMDA fast-track regulatory strategy and academic medical center investigator-initiated trials. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed rechargeable platform specialists facing technology obsolescence from wireless convergence. Five-to-ten year viability hinges on algorithm-augmented closed-loop capabilities rather than hardware scale alone. Watch FDA breakthrough device designation velocity for epilepsy and depression indications as inflection signal for platform valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | Premarket approval pathways for closed-loop systems accelerate commercialization timelines for adaptive algorithms. |
| CE Marking Pathway | EU MDR Class III active implantable compliance underpins market access across German and Swiss hospital systems. |
| Hospital System Partnership | Integrated delivery network sole-source contracts consolidate procurement around standardized programming interfaces. |
| Software Companion Development | DiGA-eligible remote monitoring platforms capture recurring revenue outside traditional device replacement cycles. |
| Reimbursement Strategy | CMS coding decisions and METI national health insurance expansion dictate commercial viability faster than regulatory clearance. |
Research Approach
Cross-validation between primary interviews with neuromodulation division executives and secondary validation through FDA 510(k) and PMA filings anchors the qualitative findings. Clinicians, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided frontline perspective on procurement consolidation and programming interface standardization. Secondary sources include CMS Medicare reimbursement databases, EMA MDR certification records, ISO 14708 compliance documentation, and hospital procurement system data. Bottom-up installed base modeling triangulates against top-down neuromodulation procedure volume estimates.
Calibration against historical CAGR realization rates across medical device categories shapes the analytical framework over the projection horizon. Segmentation dimensions span product type, end-user setting, technology platform, and application indication, with regional regulatory cluster as the industry-specific overlay. CAGRs derive from logistic diffusion curves fitted to adoption data and adjusted for reimbursement policy inflections. Forecast inputs incorporate lithium-ion battery cost trajectories and EU MDR compliance timeline assumptions.
Sensitivities concentrate around FDA approval pathway delays, EU MDR notified body capacity constraints, and lithium supply chain disruption scenarios. Forecasts reflect documented assumptions on reimbursement expansion velocity and closed-loop clinical evidence generation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Deaver Retractor Market
Medical Devices
Sphincterotomes Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Global Cataract Surgery Devices Market
Medical Devices
Annuloplasty System Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Global Continuous Peripheral Nerve Block Catheter Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Global Microcatheter Market
Medical Devices
Urinary Flow Meters Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Sterile Filtration Module Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
India Enteral Feeding Devices Market