
 Cervical Traction Devices for Home Use Market | 2026-2036
Cervical Traction Devices for Home Use Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Traction Devices for Home Use Market Insights
The manufacturing scale gap between established orthopedic equipment producers and emerging direct-to-consumer brands is unwinding traditional competitive moats. Saunders leverages vertical integration across foam molding and mechanical assembly to sustain margin control. ComforTrac anchors its position through specialized traction angle engineering, while DR-HO competes via infomercial-driven channel dominance in North American retail.
Cervical traction devices for home use apply controlled tensile force to the cervical spine through mechanical, pneumatic, or electric systems, typically delivering 10-20 pounds of distraction force at adjustable angles between 15 and 30 degrees to relieve nerve root compression and restore disc spacing. These devices serve patients seeking non-surgical intervention for herniated discs, degenerative joint disease, and radiculopathy outside clinical settings. Electric traction systems command premium positioning due to programmable force curves and patient compliance tracking features, while manual traction maintains volume leadership through lower price points and minimal maintenance requirements. Pneumatic traction represents the fastest-expanding category as inflatable collar designs improve portability and reduce setup complexity for elderly users.
FDA 510(k) clearance requirements govern device safety and electromagnetic compatibility for electric traction units sold in the United States, while ISO 13485 quality management certification shapes supplier qualification for brands targeting European distribution through CE-marked medical device pathways. The Federal Trade Commission monitors direct-to-consumer health claims, constraining marketing language around pain relief efficacy and treatment duration. Stakeholders must weigh reimbursement code stability against the accelerating shift toward cash-pay home health equipment before committing capital to regional expansion or technology platform bets.
Market Dynamics
Direct-to-consumer channel expansion is compressing traditional medical equipment distribution hierarchies, forcing established orthopedic manufacturers to rebuild go-to-market infrastructure around patient self-selection and cash-pay transactions rather than clinical procurement relationships.
Growth Catalysts
- Aging Demographics:Population cohorts over 65 in the United States and Germany are managing chronic cervical spine conditions outside institutional settings, expanding the addressable patient base for home therapeutic interventions.
- FDA 510(k) Pathway Efficiency:Streamlined predicate device clearance for pneumatic traction systems accelerates product iteration cycles and reduces regulatory capital requirements for device innovators.
- Pneumatic Collar Miniaturization:Advances in thermoplastic elastomer bladder fabrication enable portable inflation systems that elderly patients deploy without caregiver assistance.
Market Restraints
- Reimbursement Code Instability:CMS HCPCS coding revisions for home traction equipment create revenue recognition uncertainty for durable medical equipment suppliers dependent on insurance adjudication.
- Polymer Feedstock Volatility:Medical-grade silicone and TPU resin prices fluctuate with petrochemical supply chain disruptions, compressing gross margins on inflatable collar devices.
- Clinical Efficacy Skepticism:Peer-reviewed meta-analyses questioning sustained pain relief outcomes from mechanical traction limit physician referral enthusiasm for home-based alternatives.
Strategic Opportunities
- Remote Patient Monitoring Integration:Bluetooth-enabled force sensors paired with traction devices capture compliance data for value-based care contracts with Medicare Advantage plans.
- Physical Therapy Channel Partnerships:Outpatient rehabilitation clinics in Texas and Florida are establishing rental-to-purchase programs that reduce patient acquisition costs.
- ISO 13485 Certification Arbitrage:European contract manufacturers with existing quality management systems can serve as accelerated CE-marking pathways for brands entering EU distribution.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Device firms compete for specialists capable of integrating mechanical traction systems with embedded sensor arrays and mobile application interfaces.
- Electromagnetic Compatibility Testing Backlogs:FDA-mandated EMC validation for electric traction units faces laboratory capacity constraints, extending time-to-market timelines.
- Cross-Border Regulatory Divergence:Harmonizing ISO 13485 documentation with Health Canada CMDCAS requirements demands dedicated quality assurance infrastructure for North American market coverage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Traction Devices for Home Use Market |
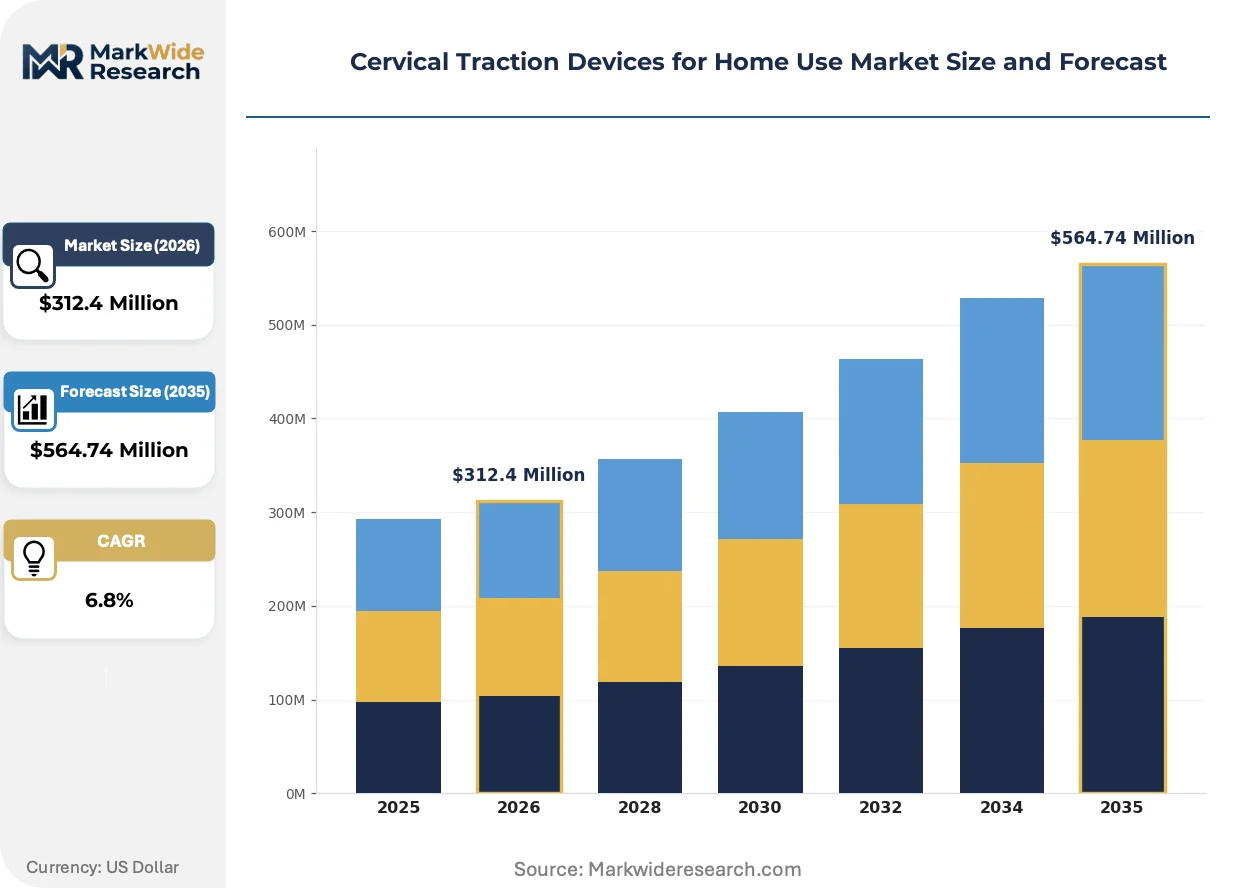
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Traction, Electric Traction, Inversion Devices, Pneumatic Traction End User: Patients, Physiotherapists, Chiropractors, Home Care Providers Distribution Channel: Online Retail, Medical Supply Stores, Pharmacies, Direct Sales Price Tier: Budget, Mid-range, Premium, Luxury |
| Companies Covered | Saunders, Pronex, Neckpro, ComforTrac, Posture Pump, DR-HO, TruLife, Everyway4all, DMI, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Traction Devices for Home Use Market Trends and Innovations
Sensor-enabled traction systems are rewriting competitive requirements, as patient compliance tracking and force curve optimization become baseline expectations rather than premium differentiators in home therapeutic devices.
Programmable electric traction is fragmenting the traditional mechanical device market by enabling personalized treatment protocols. Patients with radiculopathy are selecting units with mobile app connectivity at three times the rate of manual alternatives. This capability compression is eroding price premiums historically commanded by pneumatic systems with simpler mechanical architectures.
The FDA's evolving cybersecurity guidance for connected medical devices is reshaping electric traction system architecture. Manufacturers must now embed encryption protocols and vulnerability management processes into product development cycles. Premium electric traction lines targeting the United States market are absorbing these compliance costs through subscription-based software update models rather than hardware price increases.
Physical therapy clinics are unbundling device provision from supervised treatment, creating direct-to-patient rental channels that bypass durable medical equipment distributors. This disintermediation concentrates in Sun Belt states where out-of-pocket healthcare spending rates exceed national averages. Equipment financiers are responding with specialized lease products calibrated to 90-day treatment protocols rather than traditional 36-month medical equipment depreciation schedules.
Cervical Traction Devices for Home Use Market Segmentation
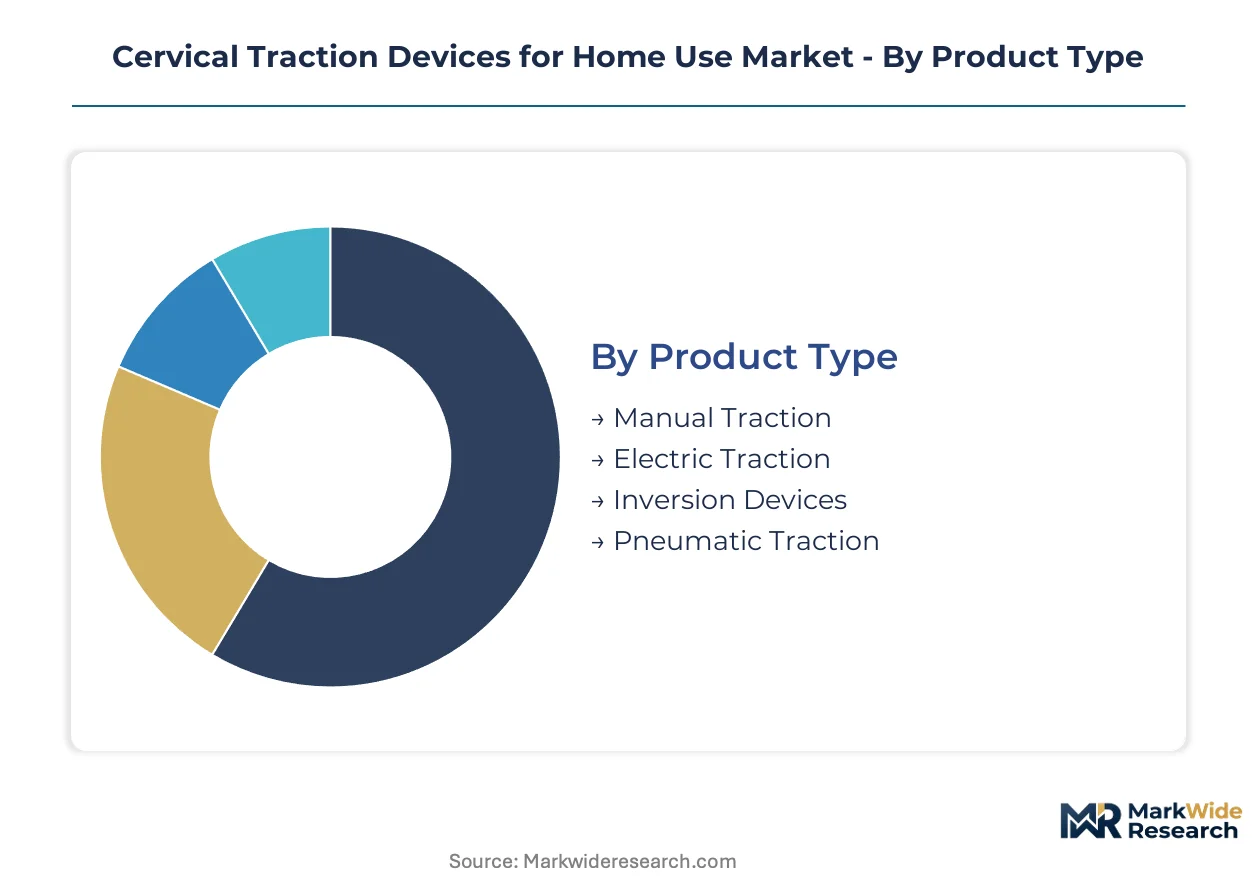
Cervical traction devices for home use fragment across four distinct axes, each carrying unique regulatory and commercial implications. Product type determines FDA 510(k) pathway complexity and electromagnetic compatibility testing burdens. Distribution channel selection shapes margin capture and patient acquisition economics for device manufacturers.
Product Type:
FDA Class II clearance requirements and ISO 13485 quality management certification create divergent compliance cost structures across mechanical, pneumatic, and electric traction architectures.
- Manual Traction:Spring-loaded or pulley-based mechanical systems delivering 10-20 pounds of distraction force through patient-controlled tension adjustment. Volume concentrates among budget-conscious elderly patients in Germany and the United States managing chronic degenerative joint disease without electrical infrastructure requirements. Minimal regulatory burden sustains margin flexibility for established orthopedic equipment producers.
- Electric Traction:Programmable motor-driven units with force curve optimization and Bluetooth-enabled compliance tracking. Demand clusters among Medicare Advantage enrollees in Florida and Texas seeking remote patient monitoring integration for value-based care contracts. FDA electromagnetic compatibility validation and cybersecurity guidance compliance absorb significant development capital.
- Inversion Devices:Gravity-assisted traction tables utilizing inverted body positioning to decompress cervical vertebrae through patient body weight.
- Pneumatic Traction:Inflatable collar designs with thermoplastic elastomer bladders enabling portable deployment. Elderly users in Japan and South Korea favor these systems for caregiver-independent setup.
Established volume favors manual traction; emerging adoption favors pneumatic traction.
End User:
Procurement authority and reimbursement eligibility diverge sharply between clinical professionals and direct patient purchasers, reshaping go-to-market infrastructure requirements.
- Patients:Direct purchasers navigating cash-pay transactions or limited durable medical equipment coverage for home therapeutic interventions. Concentration is highest among aging populations in the United States managing herniated disc conditions outside institutional settings. Price sensitivity and self-selection capability drive preference for simplified setup protocols.
- Physiotherapists:Outpatient rehabilitation clinics in Texas and Florida establishing rental-to-purchase programs that reduce patient acquisition costs. These stakeholders prioritize force measurement accuracy and treatment duration tracking for insurance documentation.
- Chiropractors:Manual therapy practitioners recommending home traction as adjunctive care for radiculopathy patients.
- Home Care Providers:Agencies coordinating therapeutic device provision for mobility-limited patients.
Direct patient purchases dominate transaction volume; physiotherapist channel partnerships are climbing the fastest.
Distribution Channel:
Channel selection determines regulatory exposure to FTC health claim monitoring and state-level durable medical equipment licensure requirements.
- Online Retail:Amazon and specialized medical equipment marketplaces capturing self-directed patient searches. FTC scrutiny of pain relief efficacy claims constrains marketing language and necessitates legal review of product descriptions. California and New York consumers show highest per-capita spending on electric traction systems through this channel.
- Medical Supply Stores:Brick-and-mortar durable medical equipment dealers with established Medicare billing relationships. Inventory carrying costs and showroom space limitations favor pneumatic collar systems with compact footprints.
- Pharmacies:Retail health chains with licensed pharmacist consultation services.
- Direct Sales:Infomercial-driven and manufacturer-owned channels bypassing distributor margins.
Online retail commands volume leadership; direct sales channels show steepest expansion trajectory.
Price Tier:
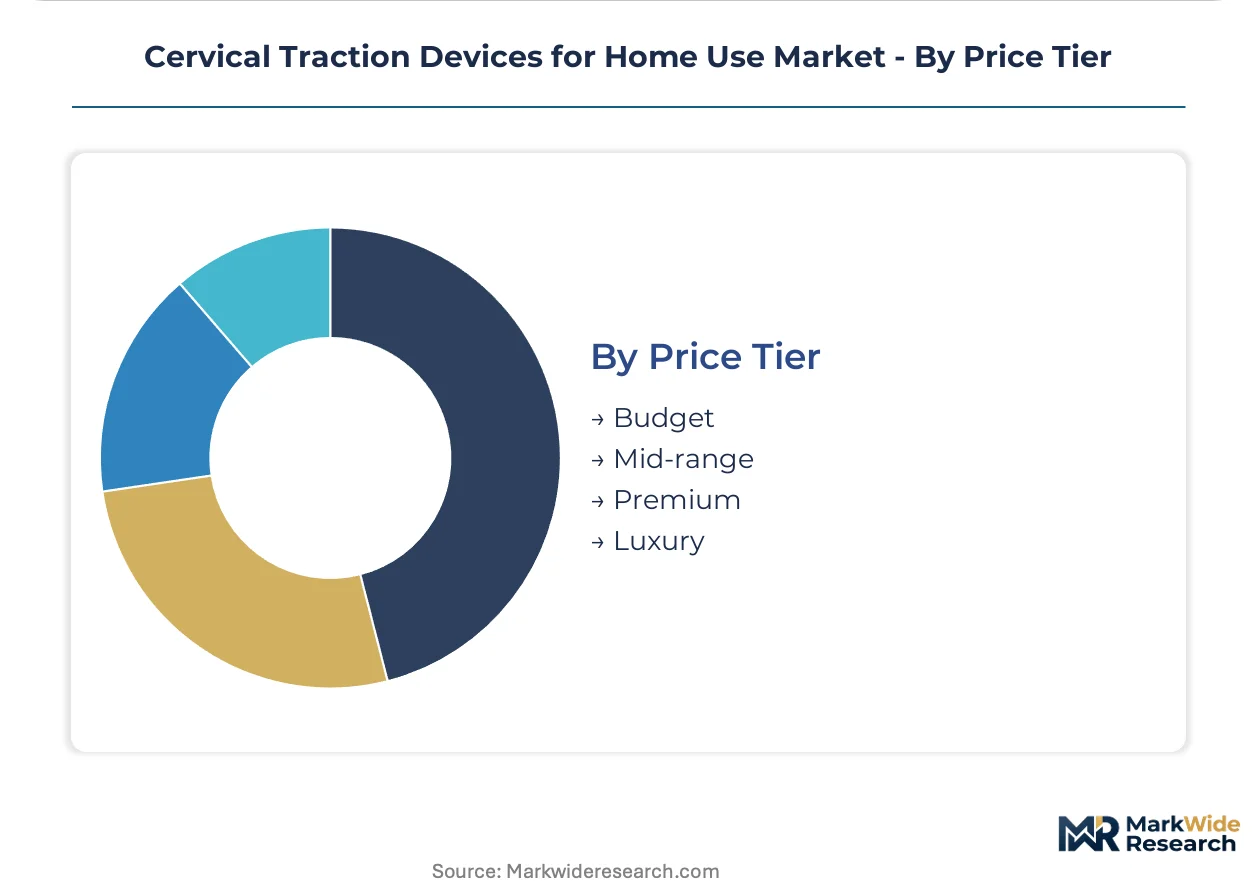
Cost stratification aligns with certification grade, sensor integration depth, and warranty duration rather than raw material differentiation alone.
- Budget:Manual traction systems priced below $100 with minimal feature sets and 90-day warranty terms. Demand concentrates in Medicaid-eligible populations and cash-constrained rural markets across the United States.
- Mid-range:Pneumatic collars and basic electric units with programmable force settings. Medicare Advantage plans in Arizona and Nevada increasingly cover this tier through supplemental benefit allocations.
- Premium:Bluetooth-enabled electric systems with mobile application connectivity and cloud-based compliance reporting.
- Luxury:Custom-fitted devices with concierge setup services and extended warranty protection.
Mid-range tier captures volume concentration; premium tier is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for cervical traction devices varies sharply by geography. Cash-pay patients in the United States absorb premium electric traction pricing with minimal resistance, while elderly buyers in Germany and Japan gravitate toward budget mechanical systems where insurance reimbursement gaps persist.
United States
Medicare Advantage enrollees in Florida and Texas are driving electric traction adoption through value-based care contracts that reward remote patient monitoring compliance. FDA 510(k) clearance requirements govern device safety and electromagnetic compatibility for electric units, while the FTC monitors direct-to-consumer health claims. The Sun Belt corridor from Phoenix to Miami concentrates rental-to-purchase program experimentation by outpatient rehabilitation clinics.
Germany
Aging populations in Bavaria and North Rhine-Westphalia manage chronic cervical spine conditions through manual traction systems priced below €100. ISO 13485 quality management certification shapes supplier qualification for CE-marked distribution pathways. Medical supply stores in Hamburg and Munich favor pneumatic collar systems with compact footprints due to showroom space constraints.
Japan
Elderly users in Tokyo and Osaka favor portable pneumatic traction collars that deploy without caregiver assistance. The country's national pharmaceutical regulator, PMDA, oversees medical device safety standards. Thermoplastic elastomer bladder fabrication advances cluster in the Nagoya industrial corridor, enabling miniaturized inflation systems.
South Korea
Seoul's aging demographic is expanding the patient base for home-based therapeutic interventions outside institutional settings. MFDS medical device regulations govern safety testing and electromagnetic compatibility requirements. Daegu-Gyeongbuk manufacturing hubs are absorbing contract production for inflatable collar designs targeting export markets.
Canada
Health Canada CMDCAS requirements demand dedicated quality assurance infrastructure for North American market coverage, extending time-to-market timelines for electric traction innovators. Ontario's outpatient rehabilitation clinics are establishing rental-to-purchase programs that reduce patient acquisition costs. Vancouver and Toronto concentrate direct-to-consumer channel experimentation for cash-pay home health equipment.
Cervical Traction Devices for Home Use Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in cervical traction device manufacturing. Established orthopedic equipment producers maintain margin control through backward integration across foam molding and mechanical assembly, while emerging direct-to-consumer brands compete via infomercial-driven channel dominance and specialized traction angle engineering. Three archetypes define the competitive terrain: vertically integrated legacy manufacturers, digitally native direct-to-consumer entrants, and contract-manufacturing-dependent specialists. Dominant competitive moves include strategic partnerships with outpatient rehabilitation clinics and portfolio diversification into Bluetooth-enabled compliance tracking systems.
Among North American-based market participants, Saunders and ComforTrac exemplify differentiated positioning archetypes, while DR-HO occupies a position within the direct-to-consumer channel dominance tier. Saunders represents the vertically integrated legacy manufacturer model with captive supply of foam molding and mechanical assembly capabilities. ComforTrac anchors the specialized engineering segment through traction angle optimization expertise. DR-HO exemplifies infomercial-driven retail penetration strategies in North American markets. These three companies collectively illustrate how competitive moats are unwinding as manufacturing scale gaps between established producers and emerging brands compress traditional hierarchies.
| Leading Market Players |
|---|
| Saunders |
| Pronex |
| Neckpro |
| ComforTrac |
| Posture Pump |
| DR-HO |
| TruLife |
| Everyway4all |
| DMI |
| Others |
Pricing and Supply Chain Analysis
Scale economies in thermoplastic elastomer bladder fabrication anchor cost structures across pneumatic traction systems, concentrating margin leverage with manufacturers operating captive molding capacity in Nagoya and Daegu-Gyeongbuk while compressing price floors for contract-dependent competitors sourcing components through third-party distributors.
Pricing Analysis
After-sales revenue from replacement bladders, extended service contracts, and mobile app subscriptions drives lifetime value capture in electric traction systems. Three-tier pricing structure across premium Bluetooth-enabled units, standard programmable electric models, and economy manual devices stratifies by certification grade and sensor integration depth. Cost compression in mid-range pneumatic collars is intensifying because medical-grade silicone feedstock prices fluctuate with petrochemical supply disruptions. Medicaid-eligible populations in rural United States markets exhibit highest price sensitivity, while Medicare Advantage enrollees in Florida absorb premium pricing with minimal resistance.
Supply Chain Analysis
Inventory lead times for FDA electromagnetic compatibility testing components extend time-to-market timelines by six to eight months for electric traction innovators. Manufacturing concentrates in China, South Korea, and Germany, with thermoplastic elastomer bladders sourcing from Nagoya industrial clusters and final assembly gravitating toward Daegu-Gyeongbuk export hubs. Supply chain risk centers on single-source vulnerability for medical-grade TPU resin from petrochemical suppliers in East Asia. Distribution runs through direct-to-consumer online channels, medical supply stores with Medicare billing relationships, and outpatient rehabilitation clinic rental-to-purchase programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a defensive-moat story anchored in regulatory entrenchment, where FDA 510(k) clearance requirements and ISO 13485 certification barriers protect incumbent positions against fast-follower replication.
For Market Incumbents: Fortify margin control through backward integration into foam molding and mechanical assembly, mirroring Saunders' captive supply model. Deepen channel entrenchment by embedding Bluetooth-enabled compliance tracking into rental-to-purchase programs with Texas and Florida outpatient rehabilitation clinics. Emerging direct-to-consumer brands with infomercial-driven retail penetration pose the primary displacement threat. For New Entrants and Emerging Players: FDA 510(k) predicate device clearance offers the fastest pathway to market entry for pneumatic traction systems with simplified mechanical architectures. Target elderly users in Japan and South Korea seeking caregiver-independent portable collar deployment, where ISO 13485-certified European contract manufacturers enable accelerated CE-marking pathways. Pursue white-space capture through physical therapy channel partnerships in Sun Belt states with above-average out-of-pocket healthcare spending. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated legacy manufacturers with captive molding capacity and established Medicare billing relationships over digitally native entrants dependent on cash-pay transactions. Long-term viability across the projection horizon rests on reimbursement code stability and remote patient monitoring integration capabilities. Watch CMS HCPCS coding revisions for home traction equipment as the primary inflection signal for revenue recognition uncertainty.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Streamlined predicate device approval accelerates pneumatic traction product iteration cycles. |
| CE Marking Pathway | ISO 13485-certified European contract manufacturers enable accelerated EU distribution entry. |
| Hospital System Partnership | Outpatient rehabilitation clinic rental-to-purchase programs reduce patient acquisition costs. |
| Software Companion Development | Bluetooth-enabled mobile applications capture compliance data for Medicare Advantage contracts. |
| Reimbursement Strategy | HCPCS code stability determines durable medical equipment supplier revenue recognition certainty. |
Research Methodology
Operator-level perspectives from biomedical engineers, durable medical equipment procurement managers, outpatient rehabilitation clinic directors, and Medicare Advantage plan contract specialists anchored the qualitative base. Primary interviews combined with secondary validation from FDA 510(k) filings, ISO 13485 certification databases, CMS HCPCS coding records, and GPO contract repositories. Bottom-up demand modeling across product type, end user, distribution channel, and price tier dimensions triangulated against top-down market sizing.
Sensitivity analysis tested forecast robustness across polymer feedstock price volatility scenarios and reimbursement code revision probabilities. Segmentation dimensions modeled include traction system architecture, procurement authority, channel structure, and certification grade. CAGRs derived from patient population growth trajectories, technology adoption curves, and pricing elasticity parameters. Industry-specific inputs encompassed electromagnetic compatibility testing backlog durations and thermoplastic elastomer bladder miniaturization trends.
Underlying assumptions cover aging demographic projections, regulatory pathway efficiency, and channel migration patterns, with deviation risk concentrated in CMS coding revisions and petrochemical supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Surgical Visualization Products Market
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Peritoneal Dialysis Solutions Market
Medical Devices
Global Brain Implants Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Global Embolic Protection Device Market
Medical Devices
Global Extremities Market
Medical Devices
Infrared Heating Pad Market
Medical Devices
External Pacemakers Market
Medical Devices
Lactation Massager Market
Medical Devices
Germany Minimally Invasive Surgery Devices Market
Medical Devices
Light Therapy Market
Medical Devices
Medical Bionic Implants and Exoskeletons Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Non-Surgical Skin Tightening Devices Market
Medical Devices
Brazil Medical Devices Market