
 Inhaled Nitric Oxide (NO) Delivery Systems Market | 2026-2036
Inhaled Nitric Oxide (NO) Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Inhaled Nitric Oxide (NO) Delivery Systems Market Intelligence
A shortage of certified respiratory therapists and neonatal perfusionists is unwinding capacity expansion at major medical centers. Linde plc leverages its industrial gas logistics network to sustain cylinder-to-bedside supply chains across North America and Europe. Mallinckrodt Pharmaceuticals anchors its position through hospital formulary contracts and specialized pharmacy distribution for inhaled NO. Beyond Air, Inc. differentiates by developing on-demand generation systems that eliminate cylinder dependency.
Inhaled nitric oxide delivery systems are precision medical devices that generate, meter, and administer NO gas at therapeutic concentrations typically between 5 and 20 parts per million, blending it with ventilator gas streams to achieve selective pulmonary vasodilation without systemic hypotension. These systems incorporate chemiluminescence or electrochemical sensors for real-time NO and nitrogen dioxide monitoring to prevent toxic oxidation byproduct exposure. Portable systems are gaining fastest among product types as hospitals seek to extend therapy beyond traditional ICU footprints into emergency transport and step-down units. Neonatal intensive care units remain the deepest end-user margin pool due to the established clinical standard of care for persistent pulmonary hypertension of the newborn, though adult critical care represents the largest volume expansion opportunity as post-cardiac surgery protocols broaden.
FDA 510(k) clearance requirements and EU MDR technical documentation standards shape device design cycles, testing burdens, and market access timelines for manufacturers seeking dual-territory commercialization. The EPA's ambient air quality standards for nitrogen oxides indirectly influence hospital ventilation engineering specifications where inhaled NO systems operate. Stakeholders must monitor evolving pulsed-dose delivery protocols and reimbursement coding decisions that will determine whether portable systems achieve standard-of-care status outside tertiary academic centers.
Market Dynamics
Portable on-demand nitric oxide generation is compressing the traditional cylinder-dependent supply model, forcing incumbent logistics networks to defend bedrock hospital contracts against capital-light technology entrants.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance timelines for predicate devices are accelerating second-generation portable system introductions into US neonatal intensive care units.
- Adult cardiac surgery protocol expansion:Post-operative pulmonary hypertension management guidelines are broadening reimbursable indications beyond neonatal populations.
- German hospital infrastructure specialization:Concentrated investment in respiratory critical care centers across Bavaria and North Rhine-Westphalia is deepening regional demand density.
Market Restraints
- Industrial gas supply concentration:Cylinder production and refill networks cluster among three North American and European industrial gas majors, creating single-source vulnerability at smaller hospitals.
- EU MDR technical documentation burden:Extended conformity assessment timelines for electrochemical sensor subsystems are delaying product line extensions by 12-18 months.
- Electrochemical sensor drift:Calibration degradation in high-humidity environments limits deployment confidence outside controlled ICU settings.
Strategic Opportunities
- Japan's aging surgical population:METI-targeted critical care infrastructure investments are opening procurement windows for integrated NO-ventilator systems in tertiary centers.
- Emergency medical transport:Helicopter and ground ambulance services represent unserved demand for battery-powered miniaturized delivery platforms.
- ISO 18562 biocompatibility harmonization:Converging international testing standards are reducing duplicate certification costs for dual-territory manufacturers.
Industry Challenges
- Neonatal perfusionist certification scarcity:Specialized training program throughput limits are capping ICU bed expansion at academic medical centers despite installed base demand.
- Legacy ventilator integration complexity:Proprietary gas blending protocols from dominant mechanical ventilation OEMs force costly adapter development for NO system connectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inhaled Nitric Oxide (NO) Delivery Systems Market |
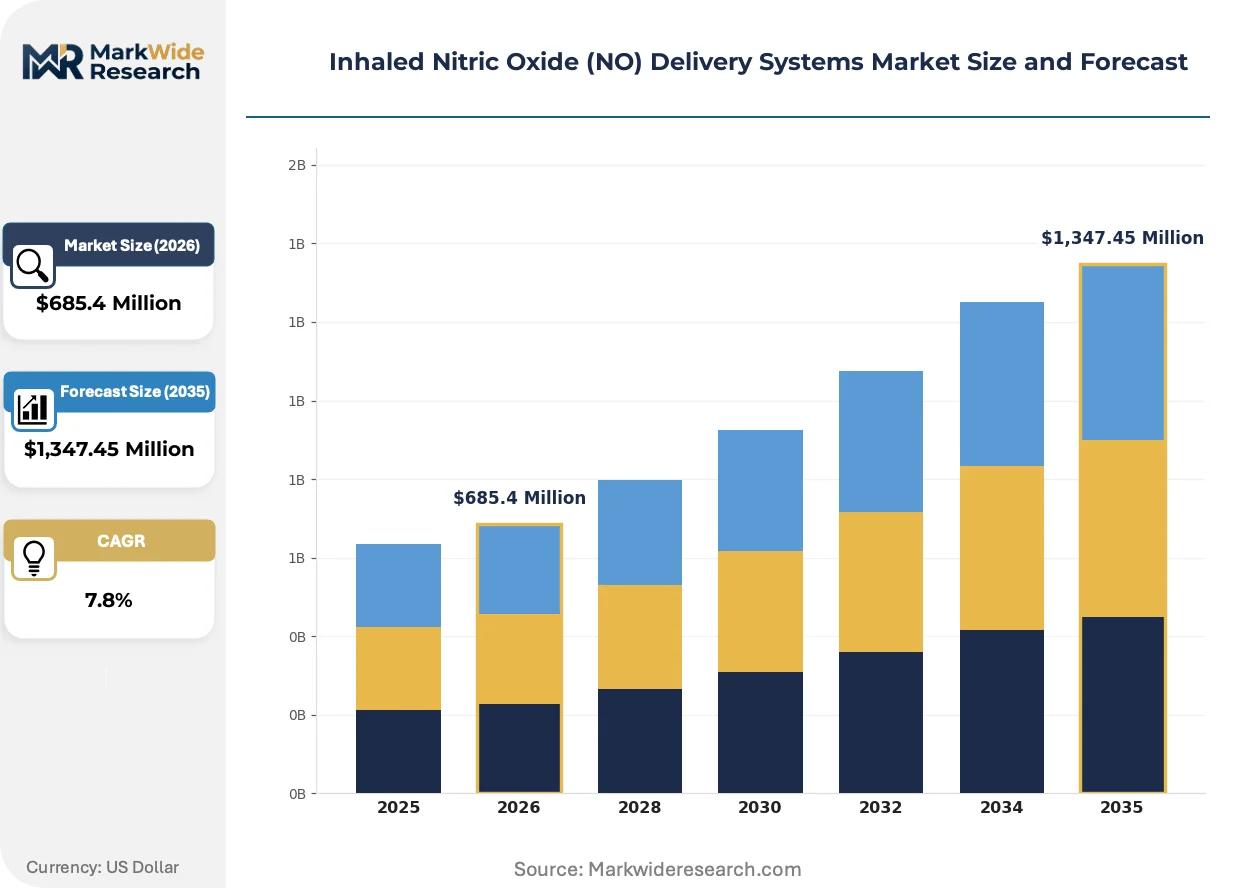
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,347.45 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Systems, Bedside Monitors, Integrated Ventilator Systems, Multigas Analyzers Application: Respiratory Distress Syndrome, Pulmonary Hypertension, Cardiac Surgery, Organ Transplantation End User: Neonatal Intensive Care Units, Adult Critical Care, Ambulatory Clinics, Surgical Centers Delivery Technology: Continuous Flow, Pulsed Dose, Demand Valve, Electronic Control Systems |
| Companies Covered | Linde plc, International Biomedical, Mallinckrodt Pharmaceuticals, SLE Ltd., Air Liquide Healthcare, VERO Biotech, Beyond Air, Inc., Bellerophon Therapeutics, Getinge AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inhaled Nitric Oxide (NO) Delivery Systems Market Strategic Shifts & Innovations
Electrochemical generation architectures are displacing compressed gas logistics, while regulatory convergence and buyer procurement centralization are compressing vendor margins and accelerating consolidation pressures.
Plasma-based on-demand nitric oxide synthesis is miniaturizing delivery systems from cart-mounted units to wearable formats. Pediatric transport teams at US children's hospitals are piloting these systems for inter-facility transfers. The technology is miniaturizing capital requirements and enabling ambulatory therapy extension beyond traditional ICU footprints.
EU MDR Annex I general safety and performance requirements are tightening post-market surveillance obligations for gas delivery precision devices. Manufacturers must now maintain clinical follow-up registries for sensor accuracy degradation. German notified bodies are enforcing stricter interpretation of these standards, delaying market access for non-EU applicants.
Hospital procurement consortia are consolidating NO delivery system purchasing through centralized formulary committees. Group purchasing organizations are displacing individual hospital pharmacy negotiations across US health systems. This concentration is most visible in the Northeast and Midwest, where integrated delivery networks command 60-plus percent of regional acute care capacity.
Inhaled Nitric Oxide (NO) Delivery Systems Market Segmentation
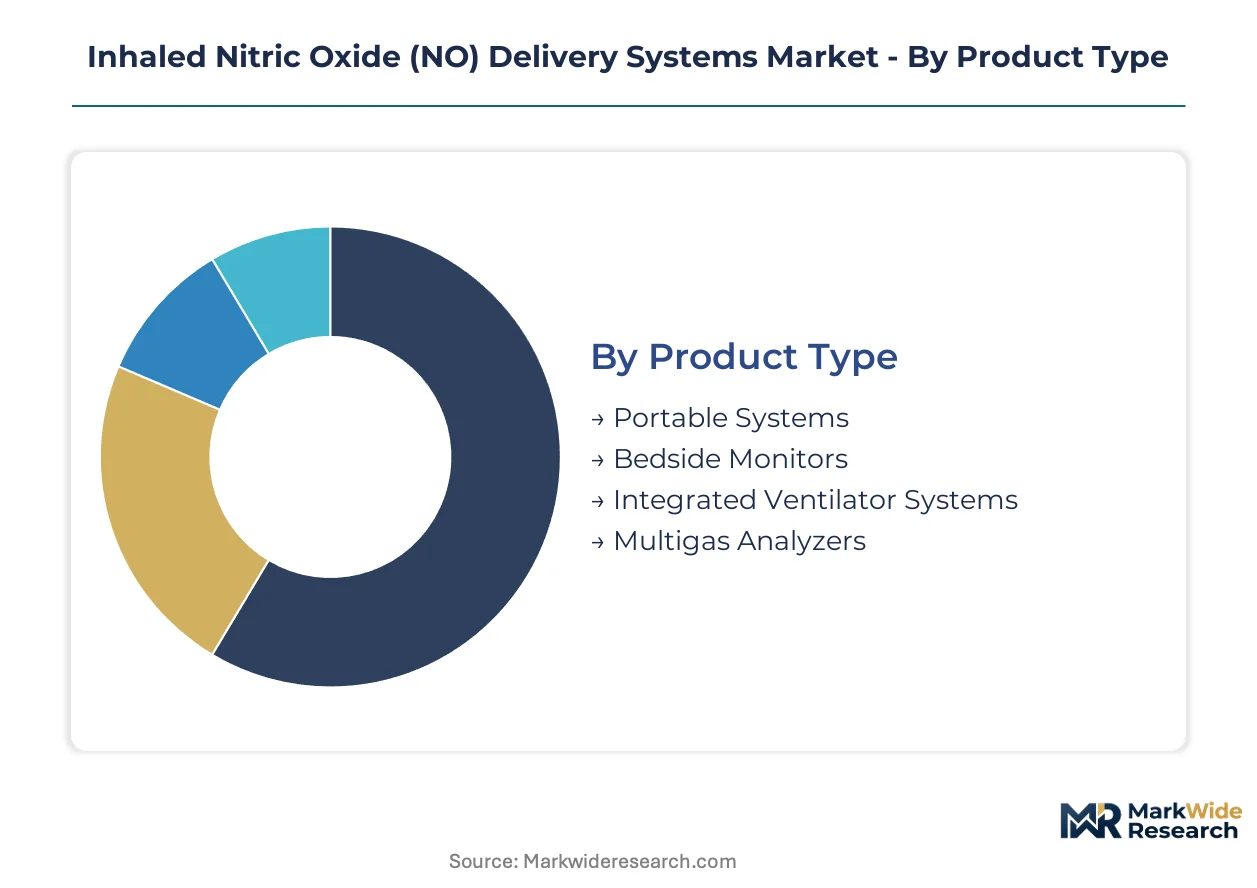
Segmentation in inhaled nitric oxide delivery systems reveals how technology architecture, clinical setting, and patient acuity reshape procurement priorities. Each dimension carries distinct margin profiles, regulatory burdens, and integration requirements that determine vendor competitive positioning.
Product Type:
Margin pools concentrate in systems that reduce cylinder dependency and extend therapy beyond fixed infrastructure.
- Portable Systems:Battery-powered units weigh under 15 kilograms and integrate electrochemical generation cells. Pediatric transport teams at US children's hospitals are piloting these for inter-facility helicopter transfers. Demand is climbing fastest where cylinder logistics face weather or traffic disruption.
- Integrated Ventilator Systems:Direct gas-blending modules attach to dominant mechanical ventilation platforms. German tertiary centers in Bavaria favor these for seamless workflow integration, though proprietary connector protocols force costly adapter development.
- Bedside Monitors:Standalone chemiluminescence analyzers verify NO and nitrogen dioxide concentrations at the point of care.
- Multigas Analyzers:Laboratory-grade instruments support research protocols and regulatory compliance testing.
The dominant share belongs to Integrated Ventilator Systems, while Portable Systems are gaining share fastest.
Application:
Volume scales with procedure complexity and reimbursement coding maturity across patient populations.
- Pulmonary Hypertension:Neonatal persistent pulmonary hypertension of the newborn represents the deepest reimbursed indication with established clinical protocols. US NICUs command premium pricing for FDA-cleared systems in this category.
- Cardiac Surgery:Post-operative right ventricular failure protocols are broadening adult patient eligibility. Japanese tertiary centers under METI infrastructure grants are expanding installed base fastest.
- Respiratory Distress Syndrome:Premature infant ventilation support drives consistent baseline demand.
- Organ Transplantation:Reperfusion injury prevention during lung transplant remains investigational with limited payer coverage.
Pulmonary Hypertension retains the largest revenue footprint, though Cardiac Surgery is expanding most quickly.
End User:
Customer concentration and purchasing power determine contract structure and service bundling requirements.
- Neonatal Intensive Care Units:Specialized perfusionist staffing and established therapeutic protocols sustain premium pricing. Academic medical centers in the US Northeast and Midwest anchor demand through group purchasing organization consolidation.
- Adult Critical Care:Broader patient volumes and expanding cardiac surgery indications drive absolute unit demand. German hospital infrastructure specialization in North Rhine-Westphalia deepens regional density.
- Ambulatory Clinics:Limited reimbursement for outpatient pulmonary hypertension limits penetration.
- Surgical Centers:Freestanding cardiac facilities lack critical care backup for NO therapy complications.
Neonatal Intensive Care Units command the highest margin per bed, while Adult Critical Care is climbing the fastest in absolute unit deployment.
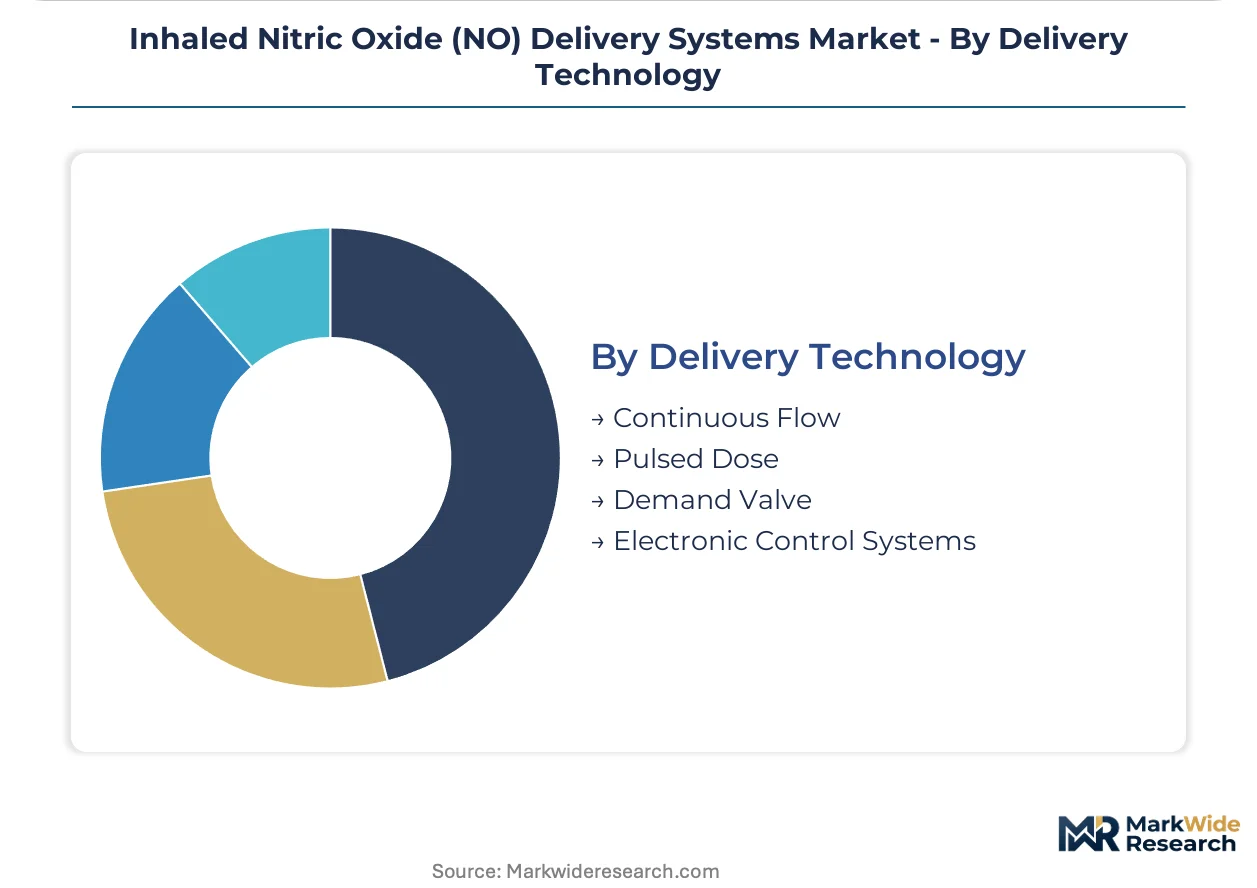
Delivery Technology:
Precision requirements and sensor reliability shape technology adoption confidence outside controlled environments.
- Electronic Control Systems:Closed-loop feedback algorithms adjust flow rates based on real-time gas analysis. EU MDR technical documentation burdens are delaying product line extensions for these subsystems by 12-18 months.
- Pulsed Dose:Synchronized delivery with patient inspiration conserves gas consumption. Pulsed-dose protocols are under evaluation for standard-of-care designation outside tertiary academic centers.
- Continuous Flow:Simple blending of NO with ventilator gas streams dominates legacy installations.
- Demand Valve:Patient-triggered delivery reduces waste but requires reliable breath detection.
Electronic Control Systems hold the dominant installed position, while Pulsed Dose is gaining share fastest through gas conservation economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Neonatal intensive care protocols diverge sharply across major markets, with the United States emphasizing portable transport systems while German hospital networks prioritize integrated ventilator modules. Japanese tertiary centers under METI infrastructure grants represent the fastest adult cardiac surgery expansion. Regulatory pathway efficiency and cylinder logistics reliability shape procurement priorities in each geography.
United States
FDA 510(k) clearance streamlining accelerates second-generation portable system introductions into neonatal intensive care units. Group purchasing organizations consolidate procurement across Northeast and Midwest integrated delivery networks commanding sixty-plus percent of regional acute care capacity. Children's hospitals in Boston and Philadelphia pilot helicopter transport systems for inter-facility transfers.
Germany
Hospital infrastructure specialization in Bavaria and North Rhine-Westphalia deepens regional demand density for precision gas delivery devices. EU MDR technical documentation standards enforced by German notified bodies delay market access for non-EU applicants through extended conformity assessments. Tertiary centers in Munich favor seamless ventilator integration despite proprietary connector costs.
Japan
METI-targeted critical care infrastructure investments open procurement windows for integrated NO-ventilator systems in Tokyo and Osaka tertiary centers. Post-operative pulmonary hypertension management protocols broaden adult patient eligibility fastest among developed markets. Aging surgical populations in Kanto and Kansai regions drive absolute volume expansion.
United Kingdom
NHS England specialized respiratory critical care center designation concentrates demand in London and Manchester academic medical centers. MHRA alignment with EU MDR post-Brexit maintains stringent electrochemical sensor documentation requirements. Scottish neonatal networks face cylinder logistics vulnerability from remote geography.
Canada
Health Canada device licensing prioritizes chemiluminescence sensor accuracy for nitrogen dioxide monitoring in Ontario and Quebec NICUs. Provincial health authority bulk purchasing centralizes procurement decisions in Toronto and Montreal. Western province transport medicine programs evaluate battery-powered miniaturized platforms for rural access.
Inhaled Nitric Oxide (NO) Delivery Systems Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with industrial gas majors leveraging cylinder logistics networks against technology entrants compressing capital requirements through on-demand generation. The structure concentrates around three strategic archetypes: industrial gas distributors defending hospital formulary contracts, pharmaceutical specialists anchoring therapeutic distribution, and miniaturization technology developers eliminating cylinder dependency. Competitive moves center on backward integration into sensor manufacturing and strategic partnerships with dominant mechanical ventilation OEMs.
Among industrial gas and pharmaceutical anchors, Linde plc, Mallinckrodt Pharmaceuticals, and Beyond Air, Inc. exemplify the tier divergence. Linde plc represents the logistics-integrated archetype through its North American and European cylinder-to-bedside supply chain position. Mallinckrodt Pharmaceuticals occupies the therapeutic distribution specialist tier with hospital formulary contract concentration. Beyond Air, Inc. anchors the capital-light technology entrant segment through on-demand generation system development that eliminates cylinder dependency entirely.
| Leading Market Players |
|---|
| Linde plc |
| International Biomedical |
| Mallinckrodt Pharmaceuticals |
| SLE Ltd. |
| Air Liquide Healthcare |
| VERO Biotech |
| Beyond Air, Inc. |
| Bellerophon Therapeutics |
| Getinge AB |
| Others |
Cost & Logistics Intelligence
Sixty-to-ninety-day cylinder refill cycles in North American NICUs concentrate procurement leverage with industrial gas majors, translating logistics reliability into pricing power that sustains premium bed-day rates for cylinder-dependent systems.
Pricing Analysis
Long-term offtake contracts dominate hospital formulary agreements, with three-year minimum commitments locking in volume discounts against spot cylinder purchases. Pricing stratifies across FDA-cleared premium systems, CE-marked standard configurations, and economy-grade transport units lacking integrated monitoring. Cost compression in the portable segment intensifies as on-demand generation eliminates recurring gas purchase obligations. Adult critical care units exhibit highest price sensitivity due to uncertain reimbursement coding, while neonatal intensive care units absorb premiums for established therapeutic protocols.
Supply Chain Analysis
Germany and the United States anchor electrochemical sensor fabrication, while Japan specializes in miniaturized gas generation cell components. Production draws from high-purity aluminum cylinder stock, platinum-group catalyst substrates, and medical-grade polymer tubing. Single-source vulnerability concentrates in European notified body certification capacity, where German assessors control access timelines for EU MDR compliance. Distribution runs through hospital group purchasing organizations in the US Northeast and Midwest, with direct-to-facility logistics networks serving German Bavarian tertiary centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
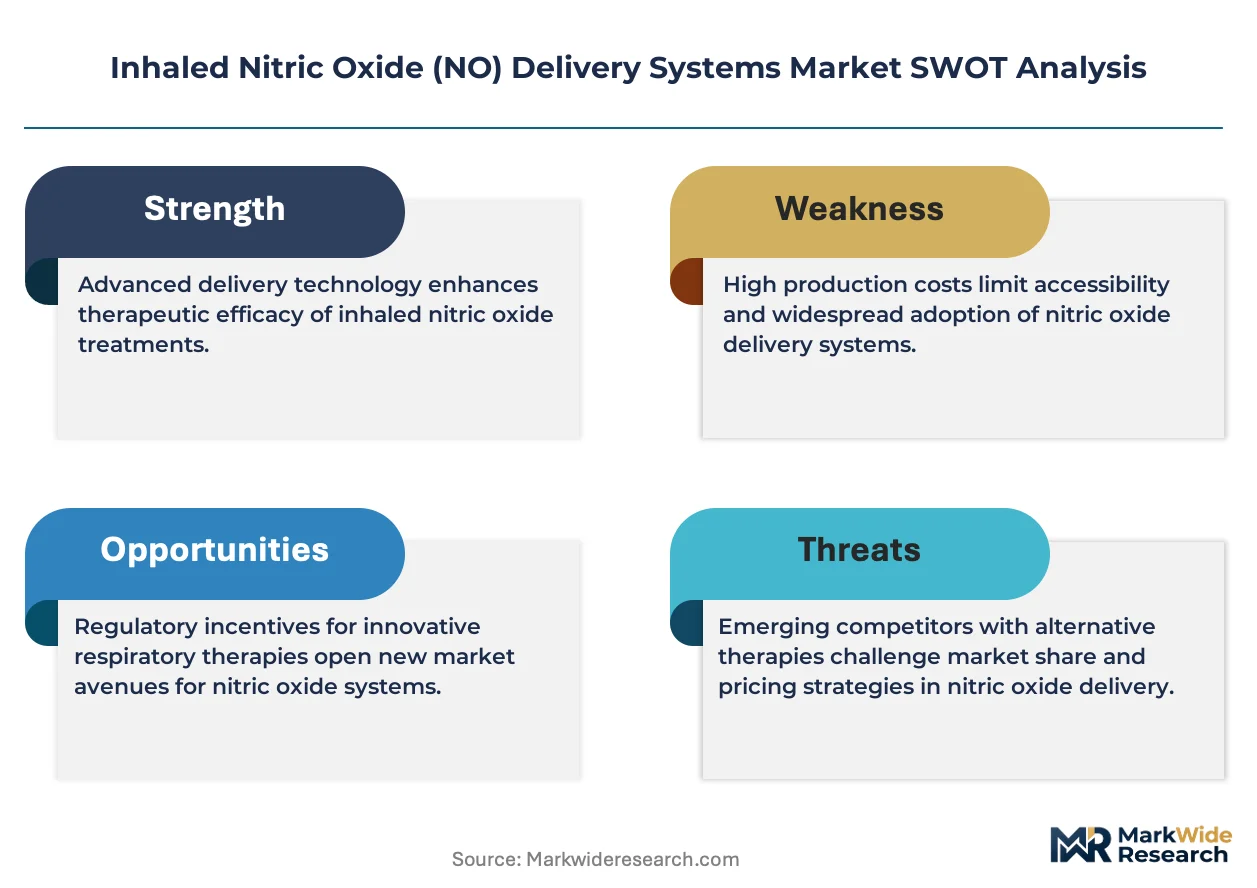
This market functions as a regulatory-entrenchment defensive moat, where FDA 510(k) predicate device pathways and EU MDR technical documentation burdens create switching costs that cement incumbent positions against technology substitution.
For Market Incumbents: Compound formulary contract density through backward integration into electrochemical sensor manufacturing, eliminating third-party subsystem vulnerability. Extend service bundling into predictive calibration maintenance to offset portable generation erosion in transport applications. Prioritize certification investment in Japanese METI infrastructure grant windows before competitor predicate devices accumulate.
For New Entrants and Emerging Players: Lead with emergency medical transport as the most penetrable white-space segment, where battery-powered miniaturization bypasses established cylinder logistics entirely. Target helicopter and ground ambulance services lacking critical care backup infrastructure. Deploy direct clinical outcome demonstration to overcome GPO procurement centralization barriers in academic medical centers.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because electrochemical generation technology commoditization will compress hardware margins toward service and consumable recurring revenue models. Acquisition targets center on portable system developers with ISO 18562 biocompatibility pre-certification and existing pilot deployments at US children's hospitals. Monitor pulsed-dose protocol reimbursement coding decisions as the inflection signal for ambulatory therapy expansion beyond tertiary footprints.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates conformity assessment timelines through German notified body pre-submission engagement. |
| On-Demand Generation Platform Launch | Eliminates cylinder logistics dependency while capturing portable transport segment growth. |
| Hospital System Partnership | Secures formulary positioning against GPO procurement consolidation in US integrated delivery networks. |
| Reimbursement Strategy Development | Positions pulsed-dose protocols for standard-of-care designation in adult cardiac surgery indications. |
| Software Companion Development | Enables remote calibration monitoring and predictive maintenance service revenue attachment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) device filings, EU MDR technical documentation databases, and hospital procurement contract registries. Conversations with neonatal perfusionists, biomedical engineering directors, GPO contracts managers, and industrial gas supply chain operators inform demand-side validation. Bottom-up installed base enumeration triangulates against top-down therapeutic procedure volume estimates across neonatal and adult critical care settings.
Segmentation dimensions modeled include product architecture, delivery technology, patient population, end-user facility type, and regional regulatory pathway cluster. CAGRs derive from weighted average of historical pricing trajectory, procedure volume elasticity, and technology substitution curves across the projection horizon. Forecast inputs incorporate cylinder logistics cost structures, electrochemical sensor replacement cycles, and reimbursement coding evolution in US and German markets.
The analysis sits within stated boundaries; outcomes outside sustained FDA 510(k) pathway efficiency or EU MDR notified body capacity expansion would require recalibration. Forecasts reflect assumptions of stable therapeutic protocol endorsement and continued cylinder supply network reliability. Recalibration cycles align with material shifts in pulsed-dose reimbursement decisions and portable generation battery chemistry advances.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Photorejuvenation Devices Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Global Orthopedic Surgical Robots Market
Medical Devices
Europe 3D Printing in Healthcare Market
Medical Devices
Nasogastric Tube Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Medical Face Shield Market
Medical Devices
Saudi Arabia Ophthalmic Devices Market
Medical Devices
Advanced Infusion Systems Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
MRI Motion Tracking Systems Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Vaginal Pessary Market