
 Human Platelet Lysate Market | 2026-2036
Human Platelet Lysate Market Size, Share, and Industry Trends Forecast 2026-2036
Human Platelet Lysate Market Intelligence
Fetal bovine serum is expanding its displacement by human platelet lysate across stem cell manufacturing workflows as researchers prioritize xeno-free culture conditions. Merck KGaA leverages its life science distribution network to supply standardized platelet lysate formulations across European and North American research markets. STEMCELL Technologies Inc. anchors its competitive position through specialized protocols that integrate platelet lysate into induced pluripotent stem cell workflows. Lonza dominates contract manufacturing services where platelet lysate serves as a critical input for cell therapy production at scale.
Human platelet lysate constitutes a cell culture supplement derived from pooled human platelet concentrates through freeze-thaw cycling, containing growth factors including PDGF, TGF-beta, and VEGF at concentrations that typically exceed serum-derived alternatives. Its primary commercial purpose centers on supporting ex vivo expansion of mesenchymal stem cells and other primary cell types for therapeutic and research applications. Liquid formulations lead current procurement volumes due to their immediate usability in standard laboratory workflows, while freeze-dried products capture growing interest from facilities prioritizing cold chain simplification and extended shelf stability. Regenerative medicine applications command the most concentrated investment in product development, with tissue engineering representing an adjacent segment where platelet lysate's angiogenic properties drive experimental adoption.
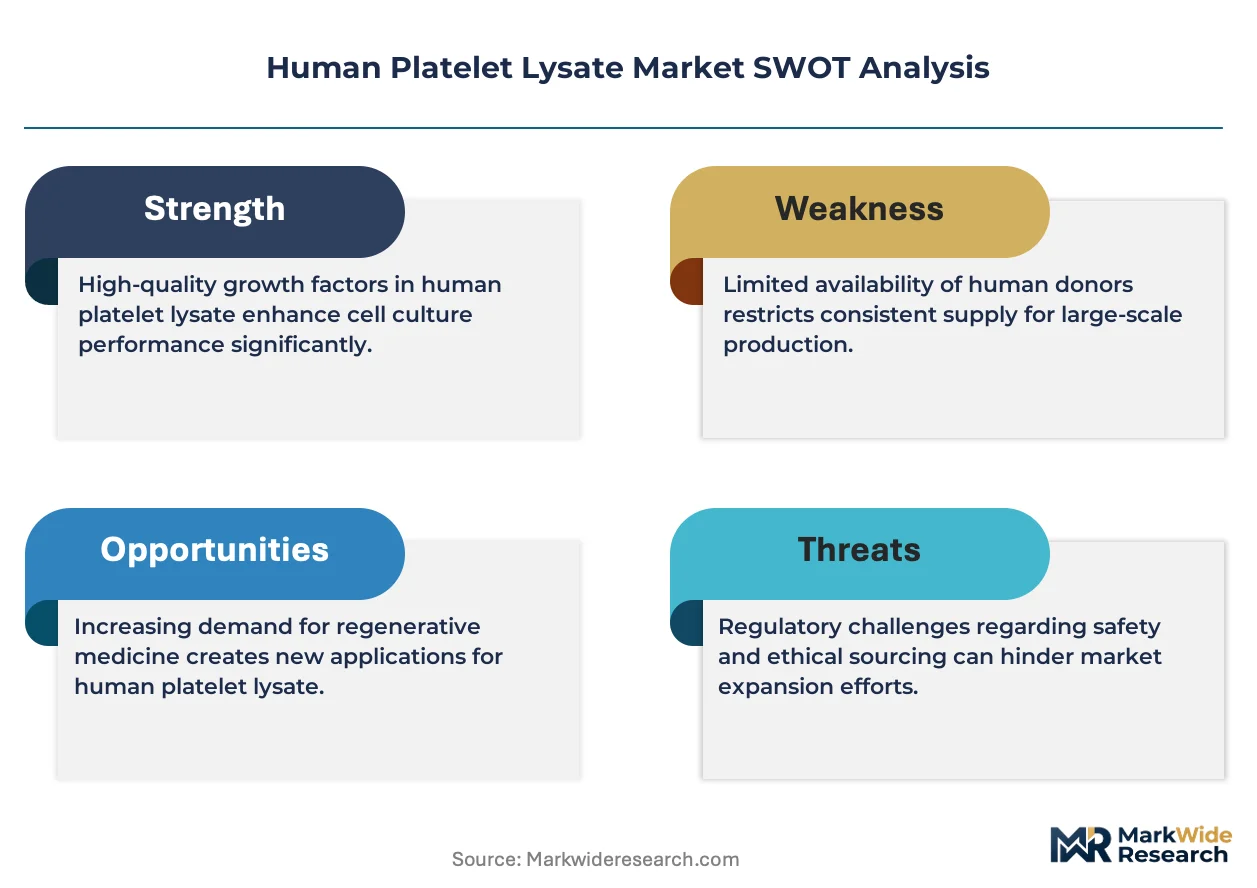
The FDA regulates human platelet lysate as a human-derived material subject to donor screening and Good Tissue Practice requirements, while the EMA's Advanced Therapy Medicinal Products framework shapes commercialization pathways in European markets. ISO 13485 certification and compliance with USP <1043> ancillary materials guidelines increasingly determine supplier qualification for biopharmaceutical procurement. Stakeholders must monitor evolving donor traceability requirements and regional divergence in xeno-free labeling standards as these factors will reshape supplier selection criteria and manufacturing location decisions.
Market Dynamics
The FDA's evolving guidance on human-derived cell culture supplements is compressing supplier qualification timelines while simultaneously accelerating capital deployment into GMP-compliant manufacturing infrastructure across North America and Europe.
Growth Catalysts
- EMA Advanced Therapy Medicinal Products framework:The European regulatory pathway provides commercial clarity for platelet lysate manufacturers seeking to serve cell therapy developers in Germany, France, and the Netherlands.
- Xeno-free stem cell manufacturing:Academic medical centers in the United States are systematically replacing fetal bovine serum with human platelet lysate to eliminate immunogenicity risks in clinical-grade cell products.
- Induced pluripotent stem cell workflows:Biopharmaceutical companies require standardized platelet lysate formulations to support scalable expansion protocols for autologous and allogeneic therapeutic candidates.
Market Restraints
- Donor material variability:Pooled human platelet concentrates exhibit batch-to-batch growth factor concentration fluctuations that complicate process validation for commercial cell therapy manufacturing.
- Supply concentration in blood banking networks:North American and Western European hospital-based blood collection systems control access to starting material, creating dependency on regional healthcare infrastructure.
- Freeze-drying capital intensity:Conversion from liquid to lyophilized product formats demands specialized lyophilization equipment and validated aseptic processing lines that smaller suppliers cannot finance.
Strategic Opportunities
- Japan's regenerative medicine commercialization framework:PMDA's accelerated approval pathways for cell therapies create demand for qualified ancillary materials from suppliers willing to establish local distribution partnerships.
- Automated closed-system bioreactors:Integration of platelet lysate feeding strategies with single-use perfusion platforms enables continuous cell expansion at commercial scale.
- Direct-to-clinic distribution:Specialized distributors are building cold chain logistics capabilities that bypass traditional research product wholesalers and shorten delivery timelines to point-of-care cell processing facilities.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for medical device-grade ancillary materials typically requires eighteen to twenty-four months of documented process validation before supplier qualification.
- Donor traceability system integration:Blood establishment computer systems must interface with manufacturer ERP platforms to maintain chain of identity documentation across multiple freeze-thaw processing steps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Human Platelet Lysate Market |
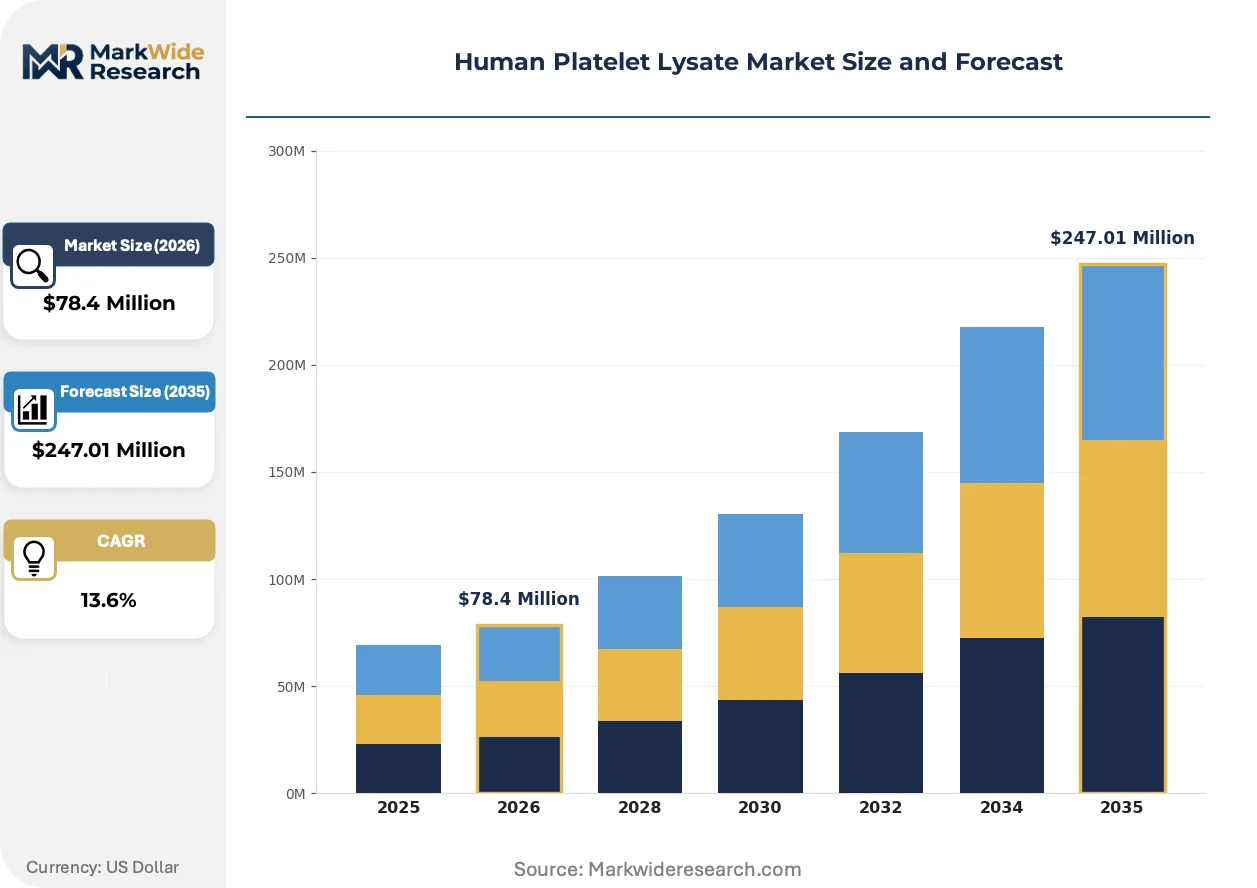
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $247.01 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Freeze-Dried, Liquid, Powder, Concentrate Application: Cell Culture, Tissue Engineering, Regenerative Medicine, Cosmetic Treatments End User: Biopharmaceutical Companies, Research Institutes, Contract Research Organizations, Diagnostic Labs Formulation: Sterile, Non-Sterile, Isoosmotic, Buffered |
| Companies Covered | Merck KGaA, Compass Biomedical Inc., STEMCELL Technologies Inc., Macopharma SA, Lonza, Terumo BCT, Mill Creek Life Sciences LLC, Cook Regentec, Sartorius AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Human Platelet Lysate Market Strategic Shifts & Innovations
Manufacturing technology and regulatory classification frameworks are actively restructuring how human platelet lysate is produced, qualified, and procured across therapeutic and research applications.
Single-use closed-system bioreactor technology is decentralizing cell expansion workflows that previously required centralized cleanroom facilities. Contract development and manufacturing organizations are adopting perfusion-based platforms that integrate platelet lysate feeding at 50-liter to 200-liter scales. This equipment shift is compressing the minimum efficient scale for commercial cell therapy production and enabling distributed manufacturing networks closer to patient treatment centers.
The FDA's Good Tissue Practice requirements and USP <1043> ancillary materials guidelines are tightening documentation standards for human-derived supplements. Manufacturers must now maintain donor eligibility records, infectious disease testing results, and processing facility environmental monitoring data across extended retention periods. Cell therapy sponsors in the United States are responding by consolidating supplier bases to entities with established regulatory affairs capabilities and prior FDA interaction histories.
Biopharmaceutical procurement teams are implementing risk-based supplier qualification programs that prioritize vendors with dual-sourced plasma collection networks and redundant manufacturing sites. This behavioral shift displaces single-source relationships that dominated early-stage clinical material supply. The pattern is most visible among mid-cap cell therapy developers in the United States and Germany who cannot tolerate batch failure risks during pivotal trials.
Human Platelet Lysate Market Segmentation
Procurement decisions in the human platelet lysate market pivot on formulation stability, regulatory compliance tier, and integration complexity with existing cell culture workflows. Buyers weigh cold chain requirements against shelf-life extension, while GMP certification status increasingly gates supplier qualification for commercial cell therapy manufacturing.
Product Type:
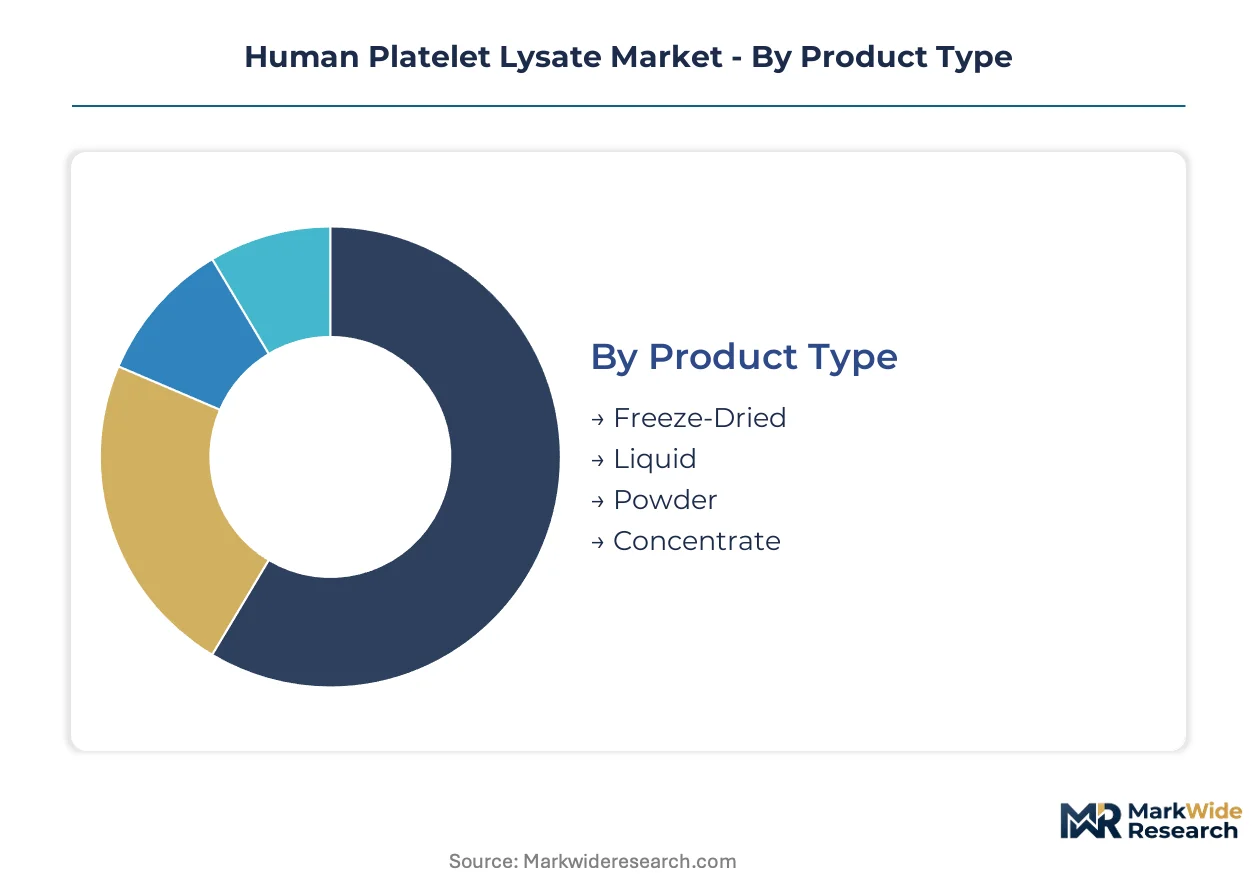
Cost tier and storage infrastructure drive product type selection, with facilities balancing immediate usability against capital investment in lyophilization-compatible processing.
- Liquid:Ready-to-use aqueous formulations dominate current procurement volumes in academic medical centers and early-stage research operations. United States biopharmaceutical companies favor liquid platelet lysate for rapid protocol implementation without reconstitution steps, though batch-to-batch variability complicates process validation.
- Freeze-Dried:Lyophilized products eliminate frozen storage requirements and extend shelf stability from months to years. German cell therapy developers are accelerating adoption of freeze-dried formats to support distributed manufacturing networks closer to patient treatment sites.
- Concentrate:High-protein formulations enable dose customization through dilution protocols. Contract manufacturing organizations leverage concentrates to optimize growth factor dosing across diverse cell line requirements.
- Powder:Spray-dried alternatives offer intermediate stability between liquid and lyophilized formats. Japanese regenerative medicine clinics evaluate powder formulations for point-of-care cell processing applications.
Liquid leads on scale; freeze-dried leads on momentum.
Application:
Application selection correlates directly with regulatory pathway maturity and reimbursement infrastructure in target markets.
- Cell Culture:Mesenchymal stem cell expansion constitutes the dominant consumption segment, with xeno-free protocols displacing fetal bovine serum in GMP-compliant manufacturing. United States academic medical centers systematically convert to human platelet lysate for clinical-grade cell product qualification.
- Regenerative Medicine:Autologous and allogeneic therapeutic candidates require standardized ancillary materials with documented donor traceability. EMA's Advanced Therapy Medicinal Products framework shapes commercialization pathways for platelet lysate suppliers serving European cell therapy developers.
- Tissue Engineering:Angiogenic properties drive experimental adoption in vascularized construct development. Netherlands research consortia integrate platelet lysate into perfusion bioreactor protocols for organoid maturation.
- Cosmetic Treatments:Topical and injectable applications leverage growth factor content for aesthetic procedures. South Korean dermatology clinics source cosmetic-grade formulations outside pharmaceutical regulatory pathways.
Cell culture commands volume concentration; regenerative medicine climbs the fastest.
End User:
Customer type determines specification rigor, with commercial manufacturers demanding ISO 13485-certified suppliers while research operations prioritize formulation flexibility.
- Biopharmaceutical Companies:Commercial cell therapy sponsors require GMP-compliant production with validated aseptic processing and redundant manufacturing sites. FDA interaction histories and prior 483 observation responses weigh heavily in supplier qualification decisions.
- Contract Research Organizations:CROs serving mid-cap cell therapy developers consolidate supplier bases to entities with established regulatory affairs capabilities and dual-sourced plasma collection networks.
- Research Institutes:Academic laboratories prioritize cost efficiency and immediate availability over documentation depth. United States National Institutes of Health-funded centers drive standardization through shared procurement consortiums.
- Diagnostic Labs:Cell-based assay developers utilize platelet lysate for primary cell maintenance in quality control applications. Diagnostic procurement emphasizes lot-to-lot consistency for reproducible test performance.
Biopharmaceutical companies anchor procurement value; contract research organizations expand most quickly.
Formulation:
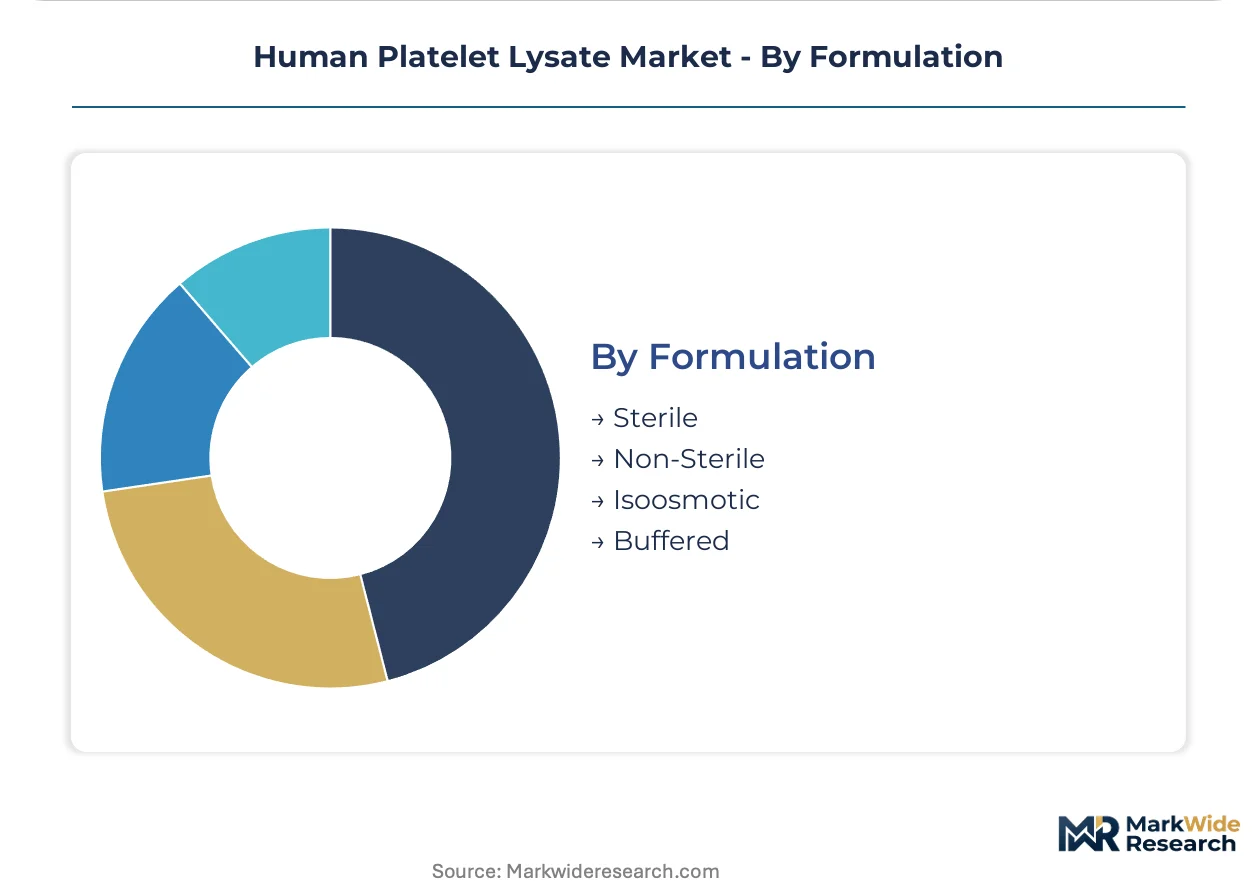
Formulation attributes directly determine qualification tier for specific therapeutic applications, with sterile processing adding cost premiums that research buyers often decline.
- Sterile:Aseptically processed formulations meet USP <1043> ancillary materials guidelines for direct contact with therapeutic cell products. Sterile processing requires validated cleanroom operations that constrain supplier participation.
- Buffered:pH-stabilized formulations reduce adaptation requirements when substituting for serum in established protocols. Buffered products command price premiums in cell therapy manufacturing where pH drift compromises cell viability.
- Isoosmotic:Osmolality-matched formulations minimize osmotic shock during media exchange sequences. Isoosmotic specifications attract buyers transitioning sensitive primary cell types from serum-containing media.
- Non-Sterile:Research-grade formulations bypass terminal sterilization to preserve heat-labile growth factor activity. Non-sterile products serve discovery-stage applications where subsequent filtration or antibiotic supplementation addresses contamination risk.
Sterile formulations dominate commercial value; buffered alternatives gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's regenerative medicine corridor anchors procurement volumes for clinical-grade human platelet lysate formulations. Academic medical centers in Massachusetts and neighboring states drive standardization efforts for xeno-free cell culture protocols. The FDA's Good Tissue Practice requirements shape supplier qualification timelines across North American manufacturing networks.
United States
Academic medical centers in Massachusetts and California systematically displace fetal bovine serum with human platelet lysate in stem cell workflows. The FDA's evolving guidance on human-derived cell culture supplements accelerates capital deployment into GMP-compliant manufacturing infrastructure. Greater Boston's cell therapy cluster concentrates contract manufacturing demand for standardized ancillary materials.
Germany
Cell therapy developers in Baden-Württemberg and North Rhine-Westphalia prioritize lyophilized platelet lysate formats for distributed manufacturing networks. The EMA's Advanced Therapy Medicinal Products framework provides commercial clarity for suppliers serving German biopharmaceutical sponsors. Heidelberg and Cologne anchor procurement consortiums for clinical-grade mesenchymal stem cell expansion materials.
Japan
PMDA's accelerated approval pathways for regenerative therapies create demand for qualified ancillary materials from suppliers establishing local distribution partnerships. Tokyo and Osaka medical centers drive adoption of platelet lysate in induced pluripotent stem cell workflows. The country's regenerative medicine commercialization framework compresses supplier qualification timelines for GMP-compliant production.
Netherlands
Research consortia in Leiden and Utrecht integrate platelet lysate into perfusion bioreactor protocols for organoid maturation and tissue engineering applications. Dutch cell therapy developers leverage the EMA's centralized marketing authorization procedures to streamline pan-European supply chains. The country's blood banking infrastructure supports regional access to pooled platelet concentrates for manufacturing feedstock.
United Kingdom
London and Cambridge biotech clusters procure platelet lysate for autologous and allogeneic therapeutic candidate development under post-Brexit regulatory divergence pressures. The Medicines and Healthcare products Regulatory Agency's alignment with EMA standards maintains supplier qualification continuity for European market access. UK academic medical centers participate in NIH-funded standardization initiatives for xeno-free cell culture protocols.
Human Platelet Lysate Market Key Industry Players
Global majors compete with regional champions across distribution network depth and regulatory affairs capabilities. The supplier base organizes into three tiers: diversified life science conglomerates with established GMP infrastructure, specialized cell culture reagent houses with protocol integration expertise, and regional blood product processors with captive platelet supply access. Competitive positioning hinges on ISO 13485 certification timelines, donor traceability system integration, and freeze-drying capacity deployment.
Within the diversified conglomerate tier, Merck KGaA and Lonza occupy positions leveraging life science distribution networks and contract manufacturing services respectively. STEMCELL Technologies Inc. exemplifies the specialized reagent house archetype through protocol integration capabilities. Regional blood product processors including Macopharma SA and Terumo BCT anchor positions through captive access to hospital-based platelet collection networks. Sartorius AG represents the bioprocessing equipment-and-consumables hybrid model.
| Leading Market Players |
|---|
| Merck KGaA |
| Compass Biomedical Inc. |
| STEMCELL Technologies Inc. |
| Macopharma SA |
| Lonza |
| Terumo BCT |
| Mill Creek Life Sciences LLC |
| Cook Regentec |
| Sartorius AG |
| Others |
Cost & Logistics Intelligence
Family-owned blood product processors in France and privately-held specialty reagent houses in Canada anchor supply-side discipline through captive platelet collection networks and conservative capacity expansion timelines. Their financing structures resist price-cutting to chase volume, sustaining margin stability across GMP-certified and research-grade tiers even as biopharmaceutical procurement teams consolidate supplier bases.
Pricing Analysis
Input-cost pass-through from pooled human platelet concentrates and lyophilization energy expenses sustains elevated pricing for clinical-grade formulations. Three-tier pricing structure across GMP-certified, ISO-compliant, and research-grade levels separates biopharmaceutical sponsors from academic laboratories on price sensitivity. Cost compression in research-grade tiers is intensifying because NIH-funded centers pool procurement through shared consortiums. Academic medical centers exhibit highest price sensitivity; commercial cell therapy sponsors prioritize regulatory documentation over unit cost.
Supply Chain Analysis
Human platelet lysate supply rests on hospital-based blood banking infrastructure concentrated in the United States, Germany, and Japan. Manufacturing feedstock draws from pooled apheresis collections, specialized freeze-thaw processing equipment, and validated aseptic filling lines. Single-source vulnerability runs through regional blood establishment networks where pandemic-era collection disruptions revealed concentration risk. Distribution runs through specialized cold chain logistics providers serving point-of-care cell processing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The human platelet lysate market functions as a stable compounder anchored by irreversible displacement of fetal bovine serum in clinical-grade stem cell manufacturing workflows.
For Market Incumbents: Hedge donor material variability through backward integration into blood establishment partnerships or dual-sourced collection networks spanning multiple hospital systems. Freeze-drying capacity expansion in Germany and Massachusetts defends position against regional champions capturing distributed manufacturing demand. ISO 13485 certification maintenance constitutes the priority lever as FDA inspection frequency intensifies for ancillary materials suppliers. For New Entrants and Emerging Players: Enter via cosmetic-grade formulations in South Korea and point-of-care reconstitution products for Japanese regenerative medicine clinics where regulatory pathways remain less encumbered. Spray-dried powder formats targeting dermatology applications outside pharmaceutical compliance frameworks represent the most penetrable segment. Direct-to-clinic distribution partnerships bypass entrenched research product wholesalers. For Investors and Strategic Acquirers: Valuations sit cheapest among regional blood product processors with captive platelet supply but underdeveloped lyophilization capabilities. Five-to-ten year viability hinges on GMP infrastructure deployment pace and EMA Advanced Therapy Medicinal Products framework alignment. Watch FDA donor traceability guidance expansion as the signal indicating qualification cost escalation and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Lyophilization Capacity Expansion | German manufacturers deploy freeze-drying lines to serve distributed cell therapy production networks. |
| Dual-Sourced Collection Network | Suppliers anchor donor material security through blood establishment partnerships across multiple hospital systems. |
| ISO 13485 Certification Investment | Quality management system implementation gates supplier qualification for commercial cell therapy manufacturing. |
| Direct-to-Clinic Distribution Partnership | Cold chain logistics capabilities bypass traditional wholesalers and shorten delivery timelines to treatment centers. |
| Regulatory Affairs Capability Buildout | Prior FDA interaction histories accelerate supplier qualification timelines for biopharmaceutical sponsors. |
Research Approach
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with cell therapy manufacturing executives, blood bank operations directors, regulatory affairs specialists, and hospital procurement managers. Secondary validation drew from FDA Good Tissue Practice guidance documents, EMA Advanced Therapy Medicinal Products framework publications, USP ancillary materials standards, and blood establishment computer system vendor disclosures. Bottom-up demand modeling triangulated against top-down market sizing across formulation types and end-user segments.
Rate-of-change decomposition structured the analytical framework, isolating volume expansion from price trajectory and mix shift effects across the projection horizon. Segmentation dimensions modeled include product format, regulatory compliance tier, application area, and end-user category. CAGRs were derived from fitted growth curves anchored to disclosed capacity expansion timelines and blood collection volume trends. Industry-specific forecast inputs incorporated cell therapy clinical pipeline progression rates and GMP facility commissioning schedules.
Inputs from blood establishment annual reports and regulatory guidance documents were available through the study window; gaps in real-time donor collection volume data introduce uncertainty bands around near-term supply capacity assumptions. Forecasts reflect documented assumptions regarding EMA framework implementation pace and FDA inspection prioritization for ancillary materials. Pandemic-era collection disruption patterns and emerging xeno-free labeling standard divergence warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Automated Blood Analyzer Market
Laboratory Equipment
Laboratory Furnaces Market
Laboratory Equipment
UK Pipette Tips Market
Laboratory Equipment
Portable Hemoglobin Analyzer Market
Laboratory Equipment
Centrifuge Tubes Market
Laboratory Equipment
Global Hematocrit Test Devices Market
Laboratory Equipment
Test Tube Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Asia-Pacific Laboratory Hoods and Enclosure Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Laboratory Data Loggers Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Global Laboratory Plasticware Market
Laboratory Equipment
Microplate Washer Market