
 Self-Expanding Stents Market | 2026-2036
Self-Expanding Stents Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Expanding Stents Market Analytics
The gap between premium nitinol platforms and commodity stainless steel alternatives is repositioning procurement patterns across vascular centers. Boston Scientific leverages its interventional portfolio breadth to sustain catheter-lab loyalty in high-volume territories. Medtronic anchors its position through captive manufacturing of shape-memory alloys, while Abbott Laboratories differentiates via drug-eluting coating technologies that command preferential formulary placement.
Self-expanding stents are tubular mesh devices fabricated predominantly from nickel-titanium alloys that deploy via thermal shape-memory activation without balloon dilation, restoring patency in tortuous or calcified vessels where balloon-expandable alternatives risk fracture. Nitinol stents dominate revenue pools due to their superelastic recovery and kink resistance in femoropopliteal applications, whereas polymer stents occupy emerging niches in bioabsorbable pediatric and neurovascular trials where long-term implant permanence poses complications. Percutaneous delivery mode leads procedure volume given its alignment with same-day discharge protocols, though laparoscopic deployment sustains margin concentration in biliary and colonic stricture cases requiring direct visualization.
FDA premarket approval pathways and CE marking under the EU MDR impose escalating biocompatibility and fatigue-testing documentation burdens that favor well-capitalized submitters with dedicated regulatory affairs infrastructure. The EPA monitors nickel ion leaching thresholds through environmental exposure assessments, while ISO 25539 sets dimensional and mechanical performance benchmarks that manufacturers must validate across intended anatomical indications. Stakeholders must weigh sustained R&D commitments against reimbursement compression as health technology assessment bodies tighten evidence requirements for premium-tier positioning.
Market Dynamics
Shape-memory alloy manufacturing concentration in Germany and Japan is tightening supply security for nitinol-based platforms while FDA fatigue-testing documentation burdens extend submission timelines for mid-tier competitors lacking dedicated regulatory infrastructure.
Growth Catalysts
- EU MDR biocompatibility mandates:Stricter CE marking requirements for nickel ion leaching documentation are filtering out marginal suppliers and consolidating procurement toward validated manufacturers with ISO 25539 compliance infrastructure.
- Femoropopliteal procedure volume:Aging demographics in the United States and Japan are expanding eligible patient pools for peripheral artery disease intervention in catheter-lab settings.
- Superelastic nitinol recovery:Thermal activation deployment without balloon dilation is displacing stainless steel alternatives in tortuous vessel anatomies where kink resistance determines clinical outcomes.
Market Restraints
- Nickel price volatility:Raw material input swings for nickel-titanium alloys compress margin stability for stent fabricators without captive smelter arrangements or long-term offtake contracts.
- Regulatory friction from EPA thresholds:Environmental exposure assessments for nickel ion leaching impose additional validation layers that extend time-to-revenue for novel platform submissions.
- Balloon-expandable substitution:Cobalt-chromium alternatives retain cost advantage in straight-segment coronary applications where calcification is minimal and fracture risk is reduced.
Strategic Opportunities
- Bioabsorbable polymer niches:Pediatric and neurovascular trials are opening for temporary scaffold applications where long-term implant permanence poses thrombotic complications.
- Same-day discharge protocols:Percutaneous delivery mode expansion in United States ambulatory surgical centers is creating channel preference for low-profile delivery systems.
- Laparoscopic visualization integration:Direct-deployment platforms for biliary and colonic stricture cases command premium positioning in interventional gastroenterology suites.
Industry Challenges
- Metallurgical talent scarcity:Specialized shape-memory alloy processing expertise concentrates in legacy aerospace and dental supply chains, constraining workforce scaling for medical device fabrication.
- Health technology assessment compression:Evidence requirements for premium-tier reimbursement are tightening across German and Japanese health technology evaluation bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Expanding Stents Market |
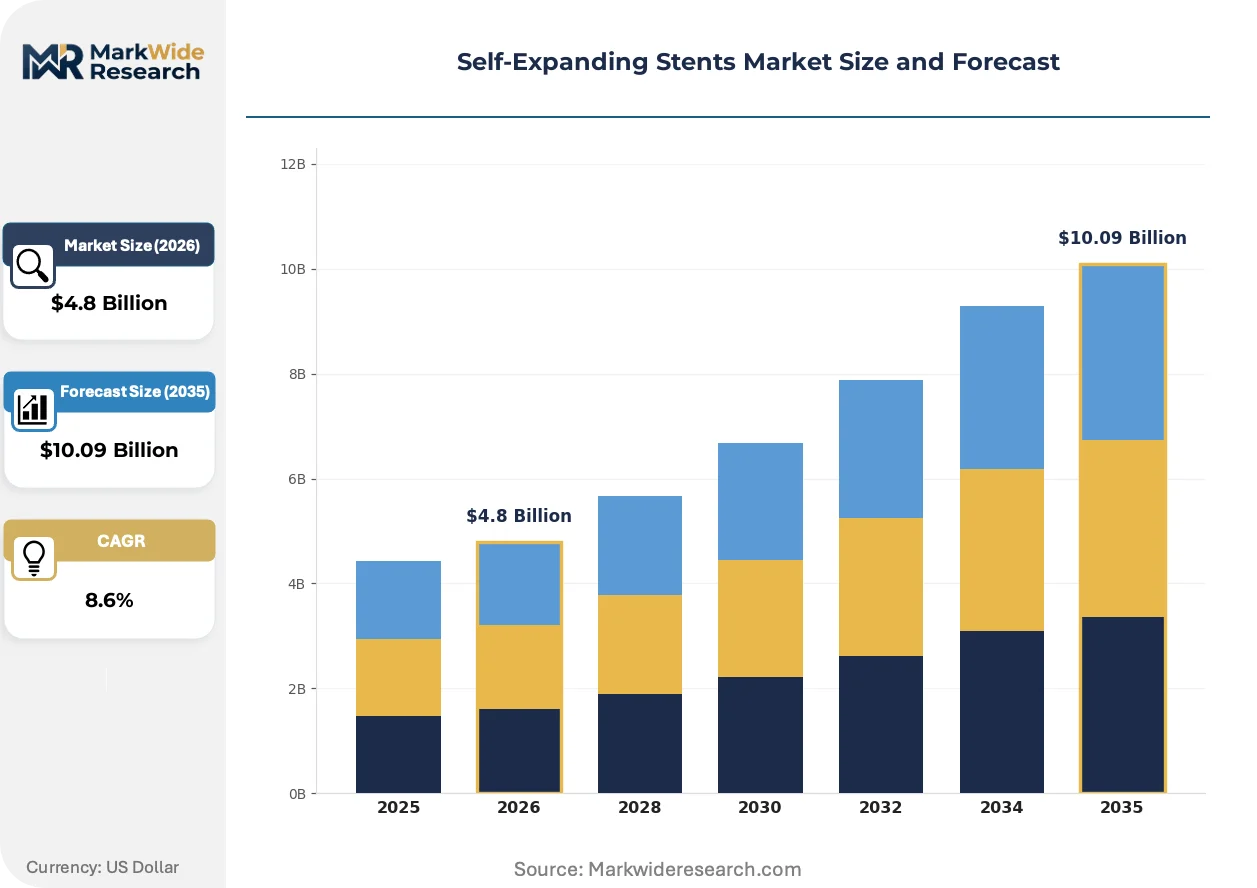
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitinol Stents, Polymer Stents, Stainless Steel Stents, Hybrid Stents End User: Hospitals, Speciality Clinics, Ambulatory Surgical Centers, Research Institutions Delivery Mode: Percutaneous, Endoscopic, Open Surgery, Laparoscopic Material: Metallic, Biodegradable Polymers, Coated Materials, Composite Materials |
| Companies Covered | Boston Scientific, Medtronic, Abbott Laboratories, Cook Medical, B. Braun Melsungen, Terumo Corporation, Biotronik, BD, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Expanding Stents Market Evolving Landscape
Modular platform architectures are fragmenting the traditional integrated-stent supply model while regulatory documentation automation and procurement centralization reshape competitive access.
Drug-eluting coating systems are modularizing around polymer-matrix combinations that permit indication-specific release kinetics without redesigning underlying nitinol scaffolds. Interventional cardiologists in high-volume United States hospital systems are adopting these configurable platforms at accelerated pace. The technology is modularizing R&D spend away from alloy metallurgy toward surface chemistry differentiation.
EU MDR post-market surveillance requirements are mandating extended clinical follow-up datasets for Class III implantable devices. Manufacturers must now maintain active implant registries across multiple member states. German notified bodies are experiencing backlog concentration that delays CE certificate renewal for legacy stent platforms.
Catheter-lab procurement consolidation through group purchasing organizations is compressing vendor panels to three preferred suppliers per metropolitan region. United States health system mergers are accelerating this concentration in Midwest and Southeast territories. Smaller manufacturers now face exclusion risk without demonstrated supply continuity or volume rebate compliance.
Self-Expanding Stents Market Segmentation
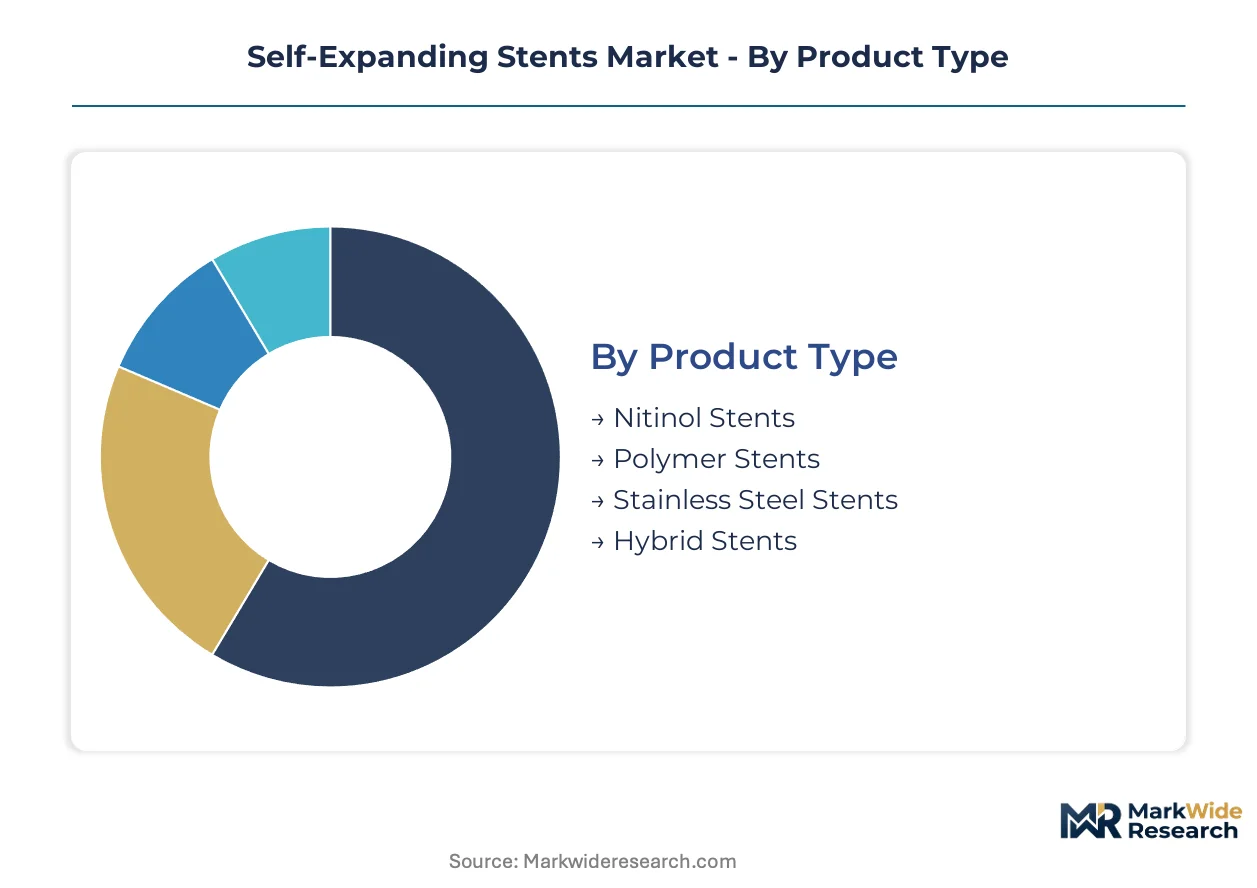
Self-expanding stent procurement varies sharply by clinical setting and anatomical indication, with material selection and deployment method determining reimbursement tiers and supply chain requirements. Manufacturers must align platform specifications against the regulatory and operational constraints of each channel.
Product Type:
Customization intensity spans from commodity stainless steel to precision-engineered nitinol systems, with fabrication complexity dictating margin profiles and vendor qualification barriers.
- Nitinol Stents:Nickel-titanium alloys exploit superelastic recovery and thermal shape-memory activation for deployment in tortuous femoropoliteal anatomies without balloon dilation. United States catheter-labs and German vascular centers concentrate procurement of these platforms where kink resistance determines patency outcomes.
- Polymer Stents:Bioabsorbable scaffolds degrade through hydrolysis after temporary structural support, eliminating long-term thrombotic risks in pediatric and neurovascular applications where permanent implants complicate future interventions. Japanese research consortia and United States academic medical centers drive clinical trial enrollment for these emerging platforms.
- Stainless Steel Stents:Balloon-expandable alternatives retain cost positioning in straight-segment coronary procedures where calcification is minimal.
- Hybrid Stents:Composite architectures combine metallic scaffolding with polymer sleeves for indication-specific drug delivery.
Leading the category by volume: Nitinol Stents. Growing fastest: Polymer Stents.
End User:
Channel economics separate high-throughput hospital systems from specialized outpatient settings, with reimbursement codes and capital equipment requirements filtering vendor access.
- Hospitals:Integrated delivery networks in the United States and Germany anchor procurement volume through catheter-lab consolidation and preferential formulary placement for FDA- and CE-marked platforms. Same-day discharge protocols and bundled payment structures favor low-profile delivery systems that minimize overnight stays.
- Speciality Clinics:Peripheral vascular and interventional radiology practices in Japan concentrate elective femoropoliteal procedures outside acute-care settings, with PMDA reimbursement pathways supporting office-based lab investments.
- Ambulatory Surgical Centers:United States outpatient facilities expanding percutaneous delivery capacity face GPO panel restrictions that limit supplier diversity.
- Research Institutions:Academic medical centers in Germany and Japan host bioabsorbable polymer trials requiring extended follow-up infrastructure.
Hospitals dominate procurement volume. Ambulatory Surgical Centers are climbing the fastest as United States site-of-service shifts accelerate.
Delivery Mode:
Minimally invasive techniques displace open surgical approaches across anatomical indications, with visualization technology integration determining platform selection.
- Percutaneous:Transcatheter deployment through femoral or radial access aligns with same-day discharge protocols in United States hospital systems and German outpatient vascular centers. Low-profile delivery sheaths reduce access-site complications and support ambulatory migration.
- Laparoscopic:Direct visualization deployment sustains premium positioning in biliary and colonic stricture interventions where endoscopic navigation fails. Japanese interventional gastroenterology suites and United States tertiary referral centers concentrate this higher-margin segment.
- Endoscopic:Natural orifice transluminal approaches reduce procedural trauma in select esophageal and colonic applications.
- Open Surgery:Direct surgical placement retains niche indication in complex redo operations and combined revascularization procedures.
Percutaneous delivery commands volume leadership. Laparoscopic deployment shows steepest expansion trajectory in interventional gastroenterology.
Material:
Supply security and biocompatibility documentation requirements stratify manufacturing capabilities and regulatory submission burdens.
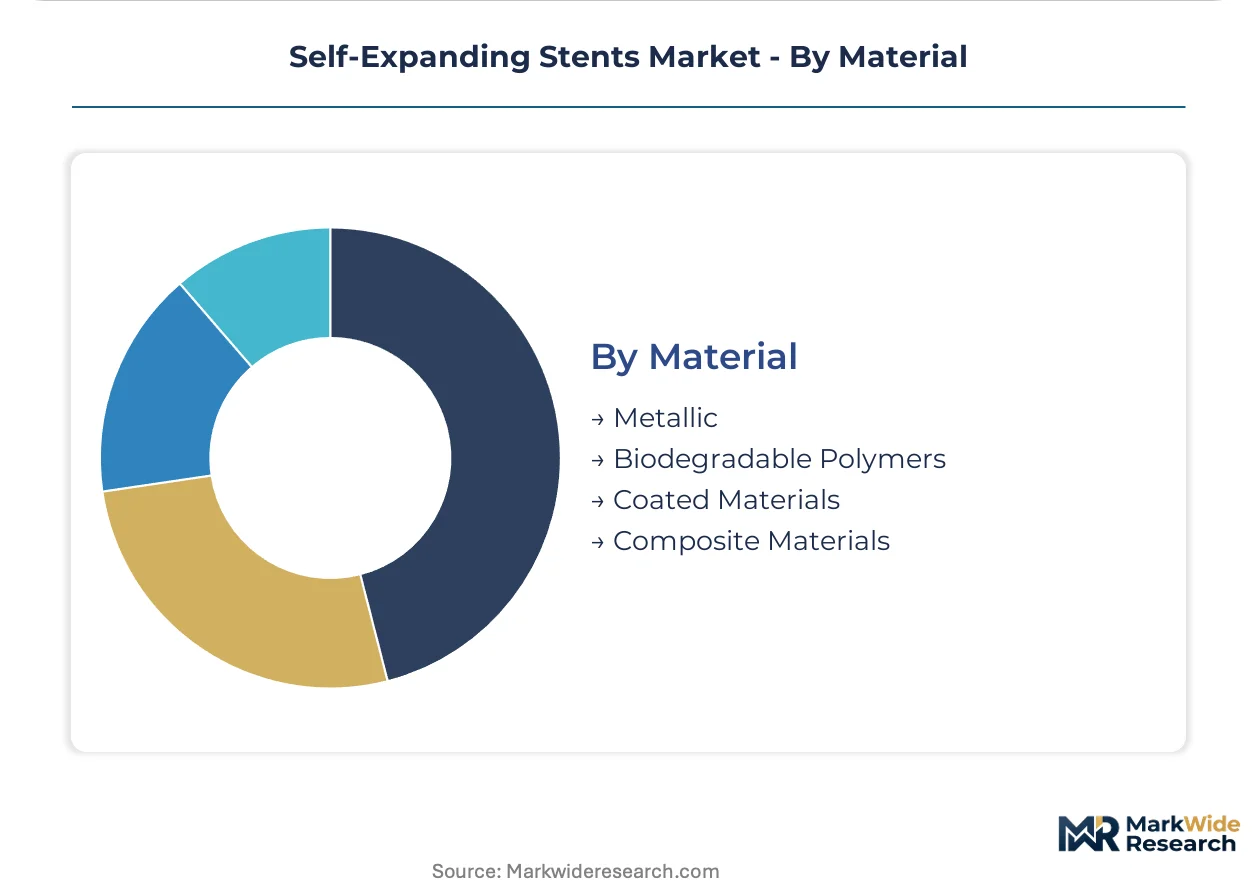
- Metallic:Nitinol and cobalt-chromium alloys dominate commercial revenue through established fatigue-testing protocols and ISO 25539 dimensional validation. German and Japanese shape-memory alloy fabricators concentrate upstream supply for medical-grade nickel-titanium.
- Biodegradable Polymers:Polylactic acid and polycaprolactone scaffolds degrade through controlled hydrolysis, attracting pediatric and neurovascular trial sponsorship where permanent implants pose lifetime management challenges.
- Coated Materials:Drug-eluting polymer matrices applied to metallic substrates enable indication-specific release kinetics without scaffold redesign.
- Composite Materials:Layered architectures combining structural metals with bioactive coatings address multi-functional performance requirements.
Metallic materials lead by installed base volume. Biodegradable Polymers are gaining share fastest as temporary scaffold applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Minneapolis anchors North American catheter-lab procurement concentration through integrated delivery network consolidation and bundled payment structures that favor low-profile nitinol delivery systems.
United States
FDA premarket approval pathways and aging demographics expand eligible patient pools for peripheral artery disease intervention. The EPA monitors nickel ion leaching thresholds through environmental exposure assessments. Minneapolis and Boston corridor health systems concentrate catheter-lab consolidation through group purchasing organization panel restrictions.
Germany
EU MDR biocompatibility mandates and CE marking fatigue-testing documentation filter marginal suppliers from procurement channels. German notified bodies experience backlog concentration that delays certificate renewal for legacy platforms. The Baden-Württemberg and North Rhine-Westphalia industrial corridors concentrate shape-memory alloy manufacturing for medical-grade nickel-titanium supply security.
Japan
PMDA reimbursement pathways support office-based lab investments in peripheral vascular and interventional radiology practices. METI standards coordination aligns with ISO 25539 dimensional and mechanical performance benchmarks. The Kanto and Kansai metropolitan clusters drive clinical trial enrollment for bioabsorbable polymer scaffolds in pediatric and neurovascular applications.
Switzerland
Swissmedic regulatory frameworks impose stringent biocompatibility documentation for Class III implantable devices. The country's precision manufacturing heritage supports specialized shape-memory alloy processing expertise concentration. The Zurich-Geneva corridor hosts research consortia exploring temporary scaffold applications where permanent implants complicate future interventions.
Self-Expanding Stents Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation infrastructure and captive metallurgical supply. The vendor base stratifies into three tiers: multinational interventional portfolios with dedicated regulatory affairs divisions, mid-cap specialists with regional CE marking concentration, and emerging fabricators dependent on toll manufacturing arrangements. Dominant competitive moves include backward integration into nickel-titanium smelter arrangements and strategic partnerships with German and Japanese shape-memory alloy processors.
Among United States-based multinationals, Boston Scientific and Medtronic occupy positions within the premium-tier regulatory infrastructure cluster, while Abbott Laboratories exemplifies surface-chemistry differentiation through drug-eluting coating system modularization. These three entities represent the consolidated procurement channel preferred supplier archetype that group purchasing organizations favor in Midwest and Southeast health system mergers.
| Leading Market Players |
|---|
| Boston Scientific |
| Medtronic |
| Abbott Laboratories |
| Cook Medical |
| B. Braun Melsungen |
| Terumo Corporation |
| Biotronik |
| BD |
| Merit Medical Systems |
| Others |
Value Network & Pricing Analysis
Captive smelter arrangements for nickel-titanium alloys anchor supply security and pricing power for nitinol stent fabricators facing raw material volatility. Backward integration into shape-memory alloy manufacturing insulates premium-tier vendors from commodity spot-market swings while compressing margin exposure for competitors dependent on toll processing.
Pricing Analysis
Throughput-based pricing in catheter-lab settings ties vendor contracts to procedure volume commitments and patency outcome guarantees. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated nitinol platforms with drug-eluting coatings from bare-metal alternatives and commodity stainless steel substitutes. Cost compression in the standard tier intensifies because group purchasing organizations consolidate vendor panels to three preferred suppliers per metropolitan region. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement ceilings, while integrated delivery networks in high-volume territories prioritize supply continuity over unit cost.
Supply Chain Analysis
Freight costs for medical-grade nickel-titanium feedstock concentrate procurement leverage around German and Japanese metallurgical centers with established ISO 25539 validation infrastructure. Upstream supply draws from Baden-Württemberg shape-memory alloy processors and Kanto region precision forgers, with cobalt-chromium alternatives sourced from Swiss and US specialty metals distributors. Single-source vulnerability concentrates in nitinol smelter capacity, where legacy aerospace and dental supply chains constrain workforce scaling for medical device fabrication. Distribution runs through catheter-lab consignment models and GPO-administered volume rebate programs that tie inventory positioning to procedure forecasting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over nickel-titanium smelter capacity determines margin defense against raw material volatility and regulatory submission timelines.
For Market Incumbents: Hedge nickel price exposure through long-term offtake contracts with German and Japanese alloy processors while accelerating drug-eluting coating modularization to shift R&D spend away from metallurgy. Balloon-expandable cobalt-chromium substitution in coronary applications threatens peripheral nitinol volumes. Captive manufacturing of shape-memory alloys remains the critical defensive lever. For New Entrants and Emerging Players: Office-based interventional radiology practices in Japan represent an underserved buyer archetype with PMDA reimbursement support and lower regulatory documentation barriers than US FDA pathways. Bioabsorbable polymer stents for pediatric neurovascular applications offer the most penetrable white space, with academic medical center trial sponsorship as the viable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to multinational interventional portfolios seeking nitinol supply security and CE marking infrastructure. Long-term viability over a five-to-ten-year window hinges on demonstrated ISO 25539 compliance and active implant registry maintenance. German notified body backlog resolution serves as the critical inflection signal for legacy platform renewal timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Titanium Smelting | Captive alloy supply insulates margins from commodity volatility and secures FDA submission timelines. |
| Drug-Eluting Coating Modularization | Surface chemistry differentiation shifts R&D spend from metallurgy toward indication-specific release kinetics. |
| CE Marking Pathway Acceleration | EU MDR compliance infrastructure filters marginal competitors from consolidated procurement channels. |
| Hospital System Partnership | Catheter-lab consignment models embed inventory positioning within high-volume integrated delivery networks. |
| Reimbursement Strategy | PMDA office-based lab pathways in Japan and CMS bundled payments in the United States determine site-of-service economics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving interventional cardiologists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers specializing in vascular device evaluation. FDA premarket approval databases, CE marking notifications under EU MDR, PMDA reimbursement schedules, and ISO 25539 certification registries supplied validation benchmarks. Bottom-up procedure volume modeling and top-down market sizing triangulated demand estimates across catheter-lab, ambulatory surgical center, and specialty clinic channels.
Segment-level granularity modeled material type, delivery mode, end-user setting, and anatomical indication across the projection horizon. Nitinol stent fatigue-testing documentation requirements, polymer scaffold hydrolysis rates, and reimbursement code bundling structures informed volume and value outputs. CAGRs derived from patient demographic projections, procedure migration patterns toward outpatient settings, and health technology assessment body evidence requirements for premium-tier positioning.
Revisions become necessary when EPA nickel ion leaching thresholds tighten, German notified body backlog extends CE certificate renewal timelines, or health system merger activity accelerates GPO panel consolidation beyond modeled rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Artery Compression Devices Market
Cardiovascular Devices
Point-Of-Care Cholesterol Monitoring Device Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Intracardiac Echocardiography (ICE) and Intravascular Ultrasound (IVUS) Market
Cardiovascular Devices
Cardiac Ablation Catheter Market
Cardiovascular Devices
Global Sclerotherapy Market
Cardiovascular Devices
Ambulatory Cardiac Monitoring Devices Market
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Heart Beat Irregularity Detection Device Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Smart Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Cardiac Catheters Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
Infusion Catheters Market
Cardiovascular Devices
Continuous Blood Pressure Monitoring Devices Market
Cardiovascular Devices
Integrated Cardiology Devices Market