
 Atrial Fibrillation Devices Market | 2026-2036
Atrial Fibrillation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Atrial Fibrillation Devices Market Analysis
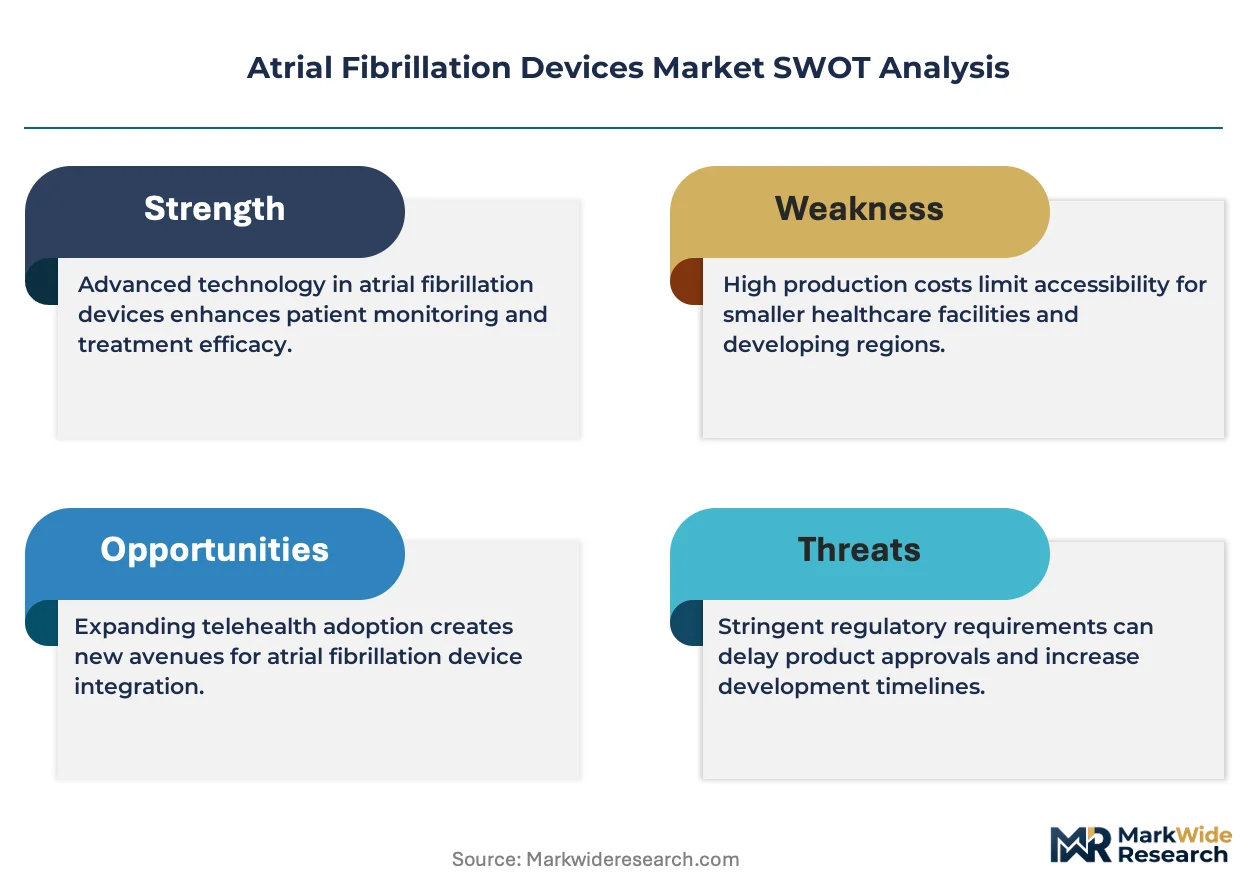
Hospital procurement committees are unwinding their historical preference for open surgical ablation as cardiac centers gain share in device selection authority. Abbott leverages its integrated mapping and ablation portfolio to sustain technology leadership across electrophysiology labs. Medtronic anchors its position through deep manufacturing scale in implantable cardiac monitors and cryoballoon systems. Boston Scientific Corporation differentiates via specialized catheter engineering that occupies the premium射频 segment.
Atrial fibrillation devices encompass catheters, implantable devices, monitoring systems, and surgical instruments designed to restore normal cardiac rhythm through ablation, electrical cardioversion, or continuous arrhythmia surveillance, typically operating at frequencies between 450 and 550 kHz for radiofrequency applications and requiring precise temperature monitoring to prevent esophageal injury during posterior wall ablation. Implantable devices such as leadless left atrial appendage occluders and subcutaneous implantable cardiac monitors serve commercial purposes by reducing stroke risk and enabling long-term ambulatory monitoring without transvenous leads. Catheters and implantable devices capture the dominant margin pools, while magnetic navigation technology grows fastest as physicians seek reduced fluoroscopy exposure and improved catheter stability in complex anatomies.
FDA premarket notification and PMA pathways, CE marking under the EU MDR, and ISO 14155 clinical investigation standards collectively shape product development timelines and market access conditions for manufacturers seeking multi-regional commercialization. The EU MDR's heightened clinical evidence requirements are forcing extended post-market surveillance commitments that favor well-capitalized firms with established notified body relationships. Stakeholders must monitor evolving CMS national coverage determinations for novel ablation modalities and the trajectory of real-world evidence requirements under FDA's CDRH digital health pre-certification framework.
Market Dynamics
Cardiac centers are consolidating device selection authority from hospital procurement committees, redirecting purchasing decisions toward integrated electrophysiology platforms that combine mapping, navigation, and ablation capabilities. This shift compresses vendor margins on standalone catheter sales while rewarding full-stack portfolios with multi-year service contracts.
Growth Catalysts
- Catheter-based ablation as first-line therapy:Cardiac centers in the United States are expanding electrophysiology lab capacity to treat paroxysmal atrial fibrillation before antiarrhythmic drug failure, accelerating device utilization rates.
- Medicare reimbursement alignment:CMS national coverage determinations for pulmonary vein isolation procedures reduce prior authorization friction for advanced mapping systems in hospital outpatient departments.
- Magnetic navigation adoption:Physicians in specialized electrophysiology networks are deploying robotic catheter systems to reduce fluoroscopy exposure during complex anatomical ablations.
Market Restraints
- EU MDR clinical evidence requirements:Extended post-market surveillance commitments under the EU Medical Device Regulation favor well-capitalized firms with established notified body relationships, raising barriers for mid-tier manufacturers.
- Esophageal injury risk:Posterior wall ablation procedures require precise temperature monitoring at 450-550 kHz frequencies, limiting procedural throughput and creating liability exposure.
- Specialized electrophysiologist shortage:Training pipeline constraints for complex ablation procedures restrict expansion of high-volume catheter lab programs outside major metropolitan clusters.
Strategic Opportunities
- Leadless left atrial appendage occlusion:Ambulatory surgical centers represent an underpenetrated channel for stroke-risk reduction devices that eliminate transvenous lead complications.
- Real-world evidence frameworks:FDA's CDRH digital health pre-certification pathway creates regulatory tailwinds for continuous arrhythmia surveillance platforms that leverage automated rhythm analysis.
- Cryoballoon system expansion:Single-shot pulmonary vein isolation technology is displacing point-by-point radiofrequency ablation in community hospital settings seeking standardized procedural outcomes.
Industry Challenges
- Electrophysiology fellowship capacity:The three-year training requirement for complex ablation competency creates a bottleneck in physician supply that constrains procedural volume growth.
- Notified body queue congestion:EU MDR transition timelines are extending CE marking cycles for novel catheter designs, compressing commercialization windows before patent expiration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atrial Fibrillation Devices Market |
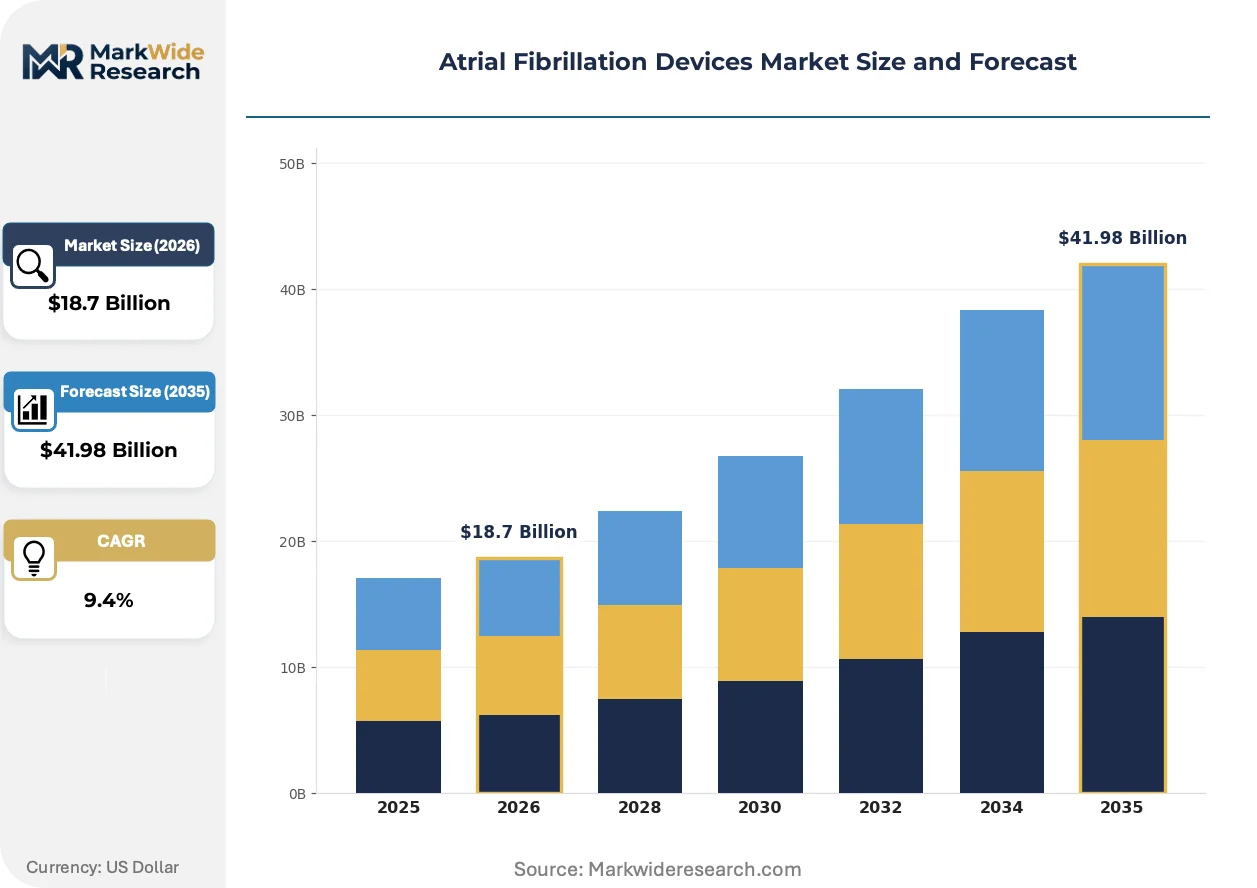
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Implantable Devices, Monitoring Systems, Surgical Instruments Technology: Radiofrequency, Cryoablation, Laser, Magnetic Navigation End User: Hospitals, Clinics, Cardiac Centers, Home Care Delivery Mode: Invasive, Minimally Invasive, Non-Invasive, Telemetry |
| Companies Covered | Abbott, Boston Scientific Corporation, Johnson & Johnson, Medtronic, Stryker Corporation, AtriCure, Biotronik, MicroPort Scientific Corporation, Acutus Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atrial Fibrillation Devices Market Emerging Trajectories
Device architecture is converging around integrated platforms that unify diagnostic mapping with therapeutic delivery, collapsing the traditional separation between lab equipment and disposable catheters. This integration is reshaping vendor competitive dynamics and procurement evaluation criteria.
Subcutaneous implantable cardiac monitor form factors are miniaturizing below 4cc volumes while extending battery longevity beyond three years. Cardiac electrophysiologists are implanting these devices in cryptogenic stroke patients at accelerating rates. This miniaturization is enabling same-day discharge protocols and expanding addressable indications beyond traditional arrhythmia surveillance.
CE marking under the EU MDR is tightening clinical evidence requirements for novel ablation technologies, mandating extended follow-up data that extends development timelines. Manufacturers are responding by front-loading post-market surveillance commitments into pivotal trial designs. Cryoballoon and laser balloon systems face the steepest compliance burden due to their thermal energy delivery mechanisms.
Hospital value analysis committees are unbundling capital equipment purchases from disposable catheter contracts, forcing vendors to compete on per-procedure economics rather than upfront system placement. Electrophysiology lab directors are gaining procurement influence at the expense of centralized materials management. This shift is most visible in United States integrated delivery networks where catheter utilization data drives vendor selection.
Atrial Fibrillation Devices Market Segmentation
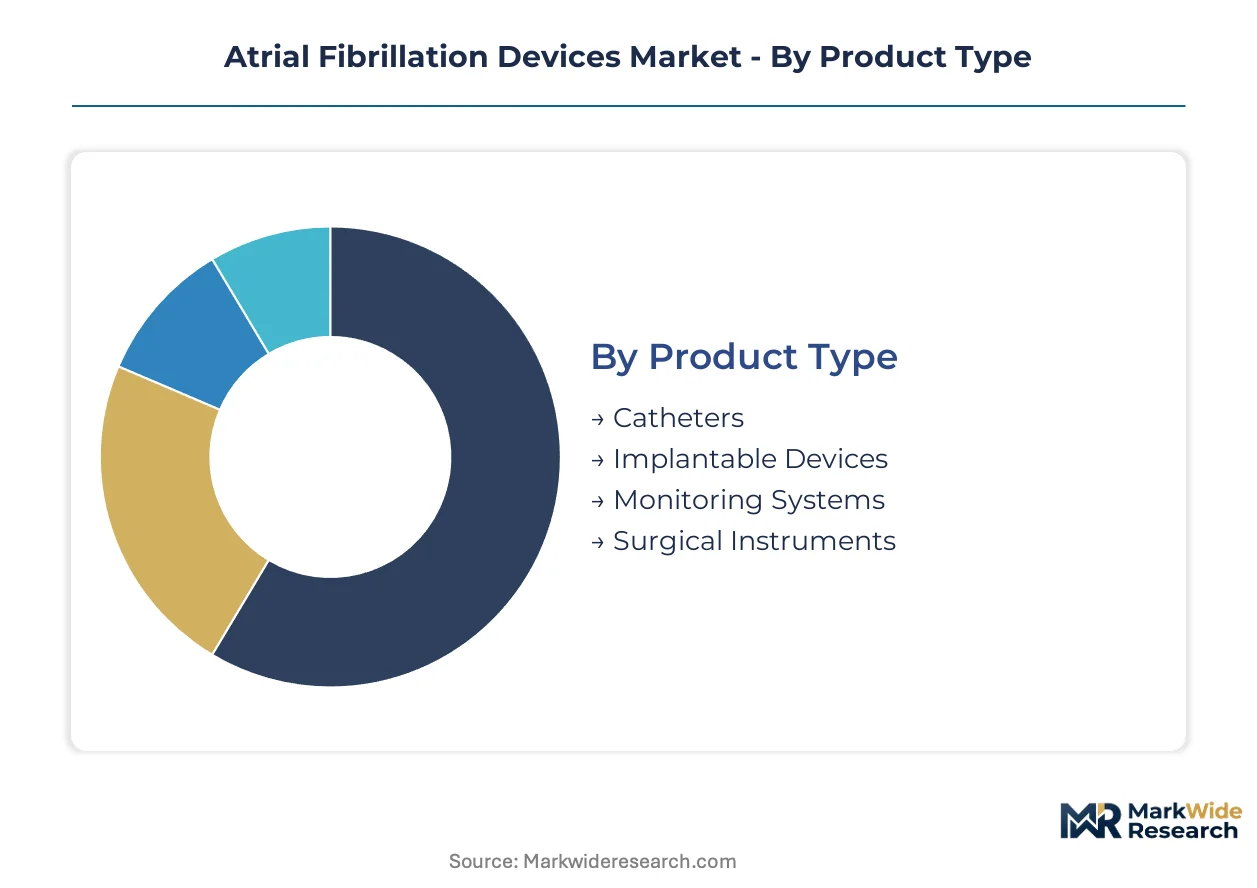
Atrial fibrillation device segmentation reveals how margin pools concentrate in catheter-based platforms and implantable technologies, while procurement authority shifts toward integrated electrophysiology systems that bundle diagnostics with therapeutic delivery.
Product Type:
Margin concentration flows toward catheter platforms and implantable devices where proprietary technology creates pricing power and recurring revenue streams.
- Catheters:Radiofrequency and cryoballoon designs operate at 450-550 kHz frequencies with integrated temperature sensing to prevent esophageal injury during posterior wall ablation. Demand concentrates in United States cardiac centers expanding electrophysiology lab capacity for first-line paroxysmal atrial fibrillation treatment.
- Implantable Devices:Leadless left atrial appendage occluders and subcutaneous cardiac monitors eliminate transvenous lead complications while enabling same-day discharge protocols. Medicare reimbursement alignment for stroke-risk reduction procedures accelerates implantation rates in hospital outpatient departments.
- Monitoring Systems:Continuous arrhythmia surveillance platforms leverage automated rhythm analysis under FDA digital health pre-certification pathways.
- Surgical Instruments:Open surgical ablation tools face contracting demand as catheter-based approaches gain first-line therapy designation.
The dominant share belongs to Catheters, while Implantable Devices is closing the gap fastest.
Technology:
Cost tier stratification separates premium magnetic navigation systems from standardized cryoballoon platforms, with reimbursement codes determining adoption velocity.
- Radiofrequency:Point-by-point ablation at controlled thermal delivery requires precise impedance monitoring and force-sensing catheter contact. United States electrophysiology networks favor this modality for complex anatomical cases requiring lesion customization.
- Cryoablation:Single-shot pulmonary vein isolation using nitrous oxide or refrigerant-based balloon systems standardizes procedural duration for community hospital settings. CE marking under EU MDR imposes extended clinical evidence requirements on thermal energy delivery mechanisms.
- Laser:Balloon-based optical energy delivery enables circumferential ablation with reduced thermal spread to adjacent structures.
- Magnetic Navigation:Robotic catheter steering reduces fluoroscopy exposure and improves stability in complex anatomies, commanding premium pricing in specialized lab networks.
Cryoablation captures the dominant procedural volume, while Magnetic Navigation is climbing the fastest as radiation safety protocols tighten.
End User:
Customer type determines purchasing authority, with cardiac centers displacing hospital procurement committees in device selection decisions.
- Hospitals:Integrated delivery networks negotiate multi-year service contracts for full-stack electrophysiology platforms combining mapping, navigation, and ablation capabilities.
- Clinics:Ambulatory surgical centers represent underpenetrated channels for leadless left atrial appendage occlusion procedures.
- Cardiac Centers:Specialized electrophysiology labs drive adoption of advanced mapping systems through direct physician influence over capital equipment decisions.
- Home Care:Remote patient monitoring platforms extend arrhythmia surveillance beyond traditional clinical settings.
Cardiac Centers command the dominant share of high-value procedures, while Ambulatory surgical channels are expanding most quickly.
Delivery Mode:
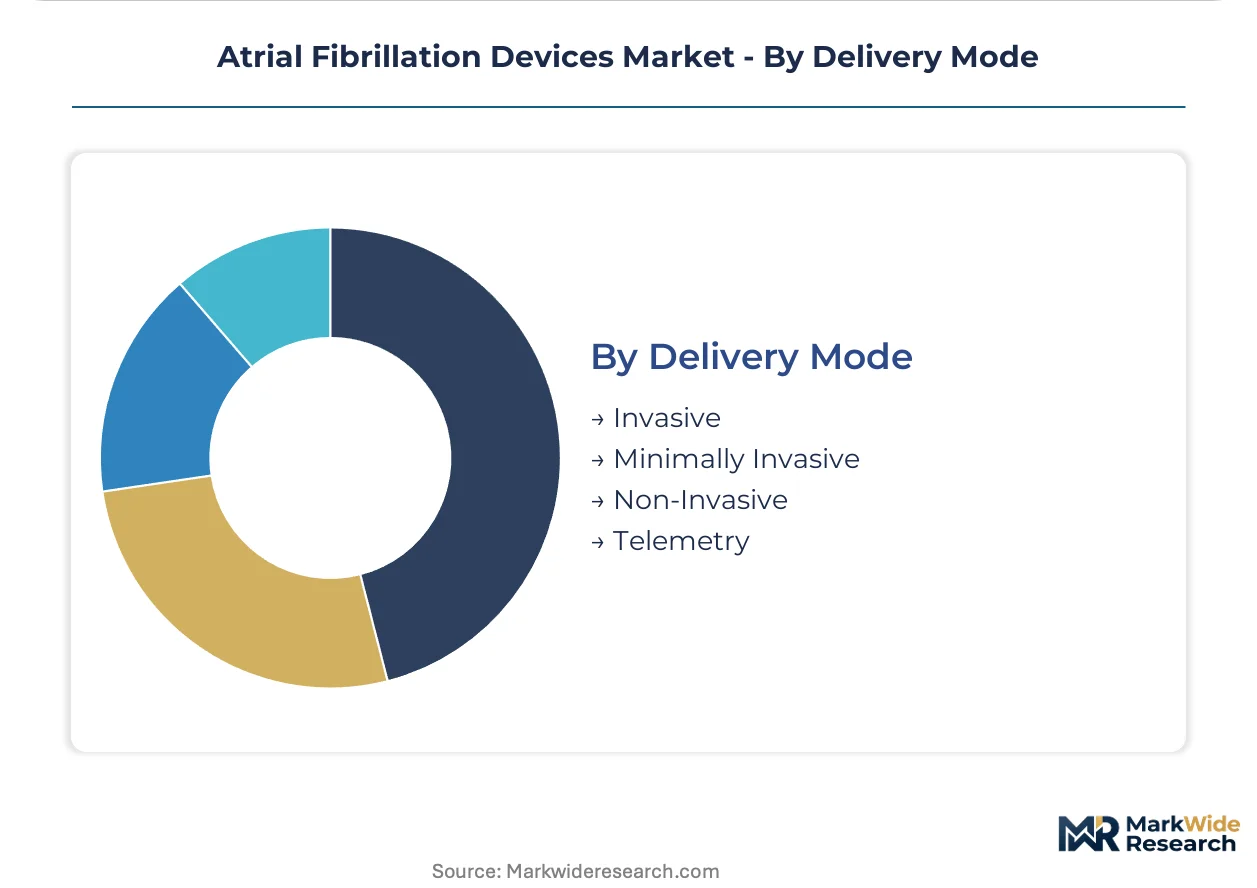
Volume concentration favors minimally invasive approaches that reduce recovery duration and enable same-day discharge protocols.
- Invasive:Surgical ablation via thoracotomy or sternotomy retains indication for concomitant cardiac procedures but contracts as standalone therapy.
- Minimally Invasive:Transcatheter approaches via femoral venous access dominate paroxysmal atrial fibrillation treatment with reduced complication profiles.
- Non-Invasive:External electrical cardioversion maintains role in acute rhythm restoration but offers no durable arrhythmia suppression.
- Telemetry:Continuous wireless monitoring enables long-term ambulatory surveillance without patient mobility constraints.
Minimally Invasive delivery holds the dominant procedural share, while Telemetry is gaining share fastest as remote monitoring reimbursement codes expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cleveland Clinic electrophysiology network anchors North American demand through its catheter lab density and physician training pipeline. United States Medicare reimbursement pathways for pulmonary vein isolation procedures accelerate device utilization across integrated delivery networks.
United States
Specialized electrophysiology labs in the Cleveland Clinic and Mayo Clinic networks drive adoption of advanced mapping systems through direct physician influence over capital equipment decisions. FDA premarket approval pathways for novel ablation technologies mandate rigorous clinical evidence standards that favor established manufacturers with deep regulatory expertise. The Boston-Cambridge corridor concentrates medical device R&D activity where catheter engineering innovation intersects with venture capital funding.
Germany
Cardiac centers in Munich and Heidelberg are expanding cryoballoon ablation programs as first-line therapy for paroxysmal atrial fibrillation patients. CE marking under the EU Medical Device Regulation imposes extended post-market surveillance commitments that compress commercialization timelines for mid-tier manufacturers. The Baden-Württemberg medical technology cluster hosts precision catheter manufacturing operations serving European hospital networks.
Japan
Metropolitan Tokyo and Osaka cardiac institutes are deploying magnetic navigation systems to reduce fluoroscopy exposure during complex anatomical ablations. PMDA regulatory reviews for implantable cardiac monitors emphasize long-term safety data that extends product registration cycles. The Kansai region's aging demographic profile drives demand for stroke-risk reduction devices in hospital outpatient departments.
Switzerland
Swissmedic oversight of leadless left atrial appendage occluders maintains stringent clinical evidence requirements that align with EU MDR standards. The Basel-Zurich medical device corridor concentrates European headquarters operations for multinational electrophysiology manufacturers. Geneva university hospitals are piloting same-day discharge protocols for subcutaneous cardiac monitor implantation.
United Kingdom
NHS England specialized commissioning frameworks for atrial fibrillation ablation are redirecting procedural volume toward cardiac centers with demonstrated outcome metrics. MHRA post-Brexit regulatory pathways for novel catheter designs create parallel review processes alongside retained EU MDR obligations. The Oxford-Cambridge-London golden triangle hosts translational research programs linking academic electrophysiology to commercial device development.
Atrial Fibrillation Devices Market Vendor Landscape
Listed leaders compete with private specialists across integrated platform portfolios versus standalone catheter offerings. The vendor base stratifies into three tiers: multinational conglomerates with full-stack electrophysiology systems, mid-cap device specialists with focused ablation technologies, and emerging players seeking regulatory clearance for novel energy delivery mechanisms. Dominant competitive moves include strategic partnerships between catheter manufacturers and robotic navigation platforms, plus backward integration into proprietary mapping software.
Within the integrated platform tier, Abbott and Medtronic exemplify archetypes of technology leadership through combined diagnostic-therapeutic portfolios. Boston Scientific Corporation occupies a position among premium catheter engineering specialists. Johnson & Johnson's electrophysiology presence represents the diversified healthcare conglomerate model. These three entities anchor the competitive structure through distinct strategic positioning rather than overlapping capability claims.
| Leading Market Players |
|---|
| Abbott |
| Boston Scientific Corporation |
| Johnson & Johnson |
| Medtronic |
| Stryker Corporation |
| AtriCure |
| Biotronik |
| MicroPort Scientific Corporation |
| Acutus Medical |
| Others |
Supply Flow & Price Mechanics
CE marking under the EU MDR gates both supplier qualification and price differentiation simultaneously, as extended clinical evidence requirements for thermal energy delivery mechanisms create tiered compliance costs that manufacturers pass through to cardiac centers and hospital procurement committees.
Pricing Analysis
Volume-discount tiering structures dominate catheter and cryoballoon procurement, with three-tier pricing separating magnetic navigation systems from standard radiofrequency platforms and economy cryoballoon configurations. Price differentiation rests on FDA PMA certification level and procedural volume commitments, with specialized electrophysiology labs commanding steepest discounts through multi-year service contracts. Cost compression in mid-tier radiofrequency segments is intensifying because hospital value analysis committees now unbundle capital equipment from disposable purchases. Community hospital settings exhibit highest price sensitivity, while academic medical centers prioritize outcome metrics over per-procedure economics.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific trade lanes into European notified body jurisdictions are extending CE marking cycles, compressing commercialization windows for novel catheter designs before patent expiration. Manufacturing concentrates in Germany, Switzerland, and the United States, with precision catheter engineering anchored in the Boston-Cambridge corridor and Baden-Württemberg medical technology cluster. Raw material dependencies include nitinol for catheter shafts, platinum-iridium for electrode tips, and specialized polymers for balloon membranes. Single-source vulnerability in notified body relationships creates supply chain risk. Distribution runs through integrated delivery networks negotiating direct contracts with cardiac centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atrial fibrillation devices market functions as a service-attach opportunity where multi-year electrophysiology lab service contracts expand faster than standalone hardware sales, as cardiac centers prioritize integrated platform uptime and procedural workflow optimization over capital equipment ownership.
For Market Incumbents: Consolidate technology leadership through backward integration into proprietary mapping software and robotic navigation platforms, neutralizing emerging entrants with novel energy delivery mechanisms. Deepen manufacturing scale in implantable cardiac monitors to defend against mid-tier specialists gaining CE marking under EU MDR. Prioritize certification investment in extended post-market surveillance commitments that smaller competitors cannot fund.
For New Entrants and Emerging Players: Lead with leadless left atrial appendage occlusion devices in ambulatory surgical centers, the most penetrable channel where Medicare reimbursement alignment accelerates implantation rates outside integrated delivery network control. Target cryptogenic stroke surveillance through miniaturized subcutaneous cardiac monitors below 4cc volumes. Pursue FDA digital health pre-certification pathway for automated rhythm analysis platforms as primary go-to-market angle.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across magnetic navigation and robotic catheter systems, favoring well-capitalized firms with established notified body relationships over venture-backed device specialists. Long-term viability over the coming decade hinges on recurring revenue from service contracts rather than transactional catheter sales. Acquisition target archetype: mid-cap ablation technology specialists with EU MDR compliance infrastructure already built. Signal to watch: CMS national coverage determination expansions for novel ablation modalities.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR extended post-market surveillance commitments compress commercialization timelines for thermal energy delivery mechanisms. |
| Hospital System Partnership | Multi-year service contracts with integrated delivery networks lock in catheter utilization data and procurement influence. |
| Software Companion Development | Automated rhythm analysis platforms under FDA digital health pre-certification create recurring revenue beyond hardware sales. |
| Reimbursement Strategy | CMS national coverage determinations for pulmonary vein isolation reduce prior authorization friction in hospital outpatient departments. |
| FDA Submission | PMA pathway rigor for novel ablation technologies favors established manufacturers with deep regulatory expertise and clinical evidence infrastructure. |
Methodological Framework
The analysis maps catheter platforms, implantable devices, monitoring systems, and surgical instruments, each validated through electrophysiology lab directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) and PMA filings, EUDAMED device registrations, CMS Medicare claims data, and hospital procurement databases. Bottom-up catheter utilization modeling triangulates against top-down electrophysiology lab capacity expansion estimates.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation dimensions spanning product type, energy delivery technology, end-user facility tier, and procedural approach. CAGRs were derived from modeled adoption curves for magnetic navigation systems and cryoballoon displacement patterns. Industry-specific forecast inputs include electrophysiology fellowship training pipeline constraints and EU MDR notified body queue congestion metrics.
Forecasts assume regulatory continuity in FDA PMA pathways and EU MDR post-market surveillance regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include accelerated CMS coverage determinations for competing stroke-risk reduction therapies and breakthrough device designation withdrawals. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Self-Destructing Syringe Market
Medical Devices
Hybrid Grafts Market
Medical Devices
Global Nasal Spray Market
Medical Devices
Prescription Lens Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Jet Nebulizers Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Uterine Fibroid Embolization Devices Market
Medical Devices
Portable OT Light Market
Medical Devices
Prefilled Syringes Market
Medical Devices
Global Chemotherapy Devices Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Epistaxis Devices Market