
 Inversion Table Market | 2026-2036
Inversion Table Market Size, Share, and Industry Trends Forecast 2026-2036
Inversion Table Market Analytics
Asset-light leasing models for premium home fitness equipment is reconfiguring competitive dynamics in the inversion table space, lowering entry barriers for new participants. Teeter leverages its decades-long brand heritage and specialized engineering to sustain premium positioning across North American channels. Innova competes aggressively on value-engineered steel-frame designs that anchor its presence in mass retail and e-commerce. YOLEO extends its reach through foldable product lines optimized for apartment-dwelling home users in Asian markets.
An inversion table is a pivoting apparatus that secures a user by the ankles and rotates the body to inverted or partially inverted angles, typically employing steel or aluminum framing with padded backboards and adjustable tether systems to control rotation depth. Its primary commercial purpose centers on spinal decompression therapy, core strengthening, and circulatory improvement for both clinical rehabilitation protocols and unsupervised home wellness routines. Manual inversion tables still occupy the largest installed base due to lower price points and mechanical simplicity, though automatic motorized variants capture disproportionate margin pools among rehabilitation centers seeking programmable angle precision. Steel construction dominates unit economics across all channels, while aluminum frames represent the fastest-growing material subset among portable and foldable designs targeting space-constrained urban consumers.
The FDA regulates inversion tables marketed with therapeutic claims as Class I medical devices, requiring adherence to quality system regulations that shape product liability exposure and labeling requirements for US-bound manufacturers. The EU MDR and CE marking obligations impose additional clinical documentation burdens on exporters, while ISO 20957-1 safety standards for stationary training equipment establish baseline structural load testing protocols recognized across multiple jurisdictions. Stakeholders must monitor evolving home-use certification requirements and reimbursement code developments for spinal traction therapies that could either expand clinical channel access or restrict direct-to-consumer positioning.
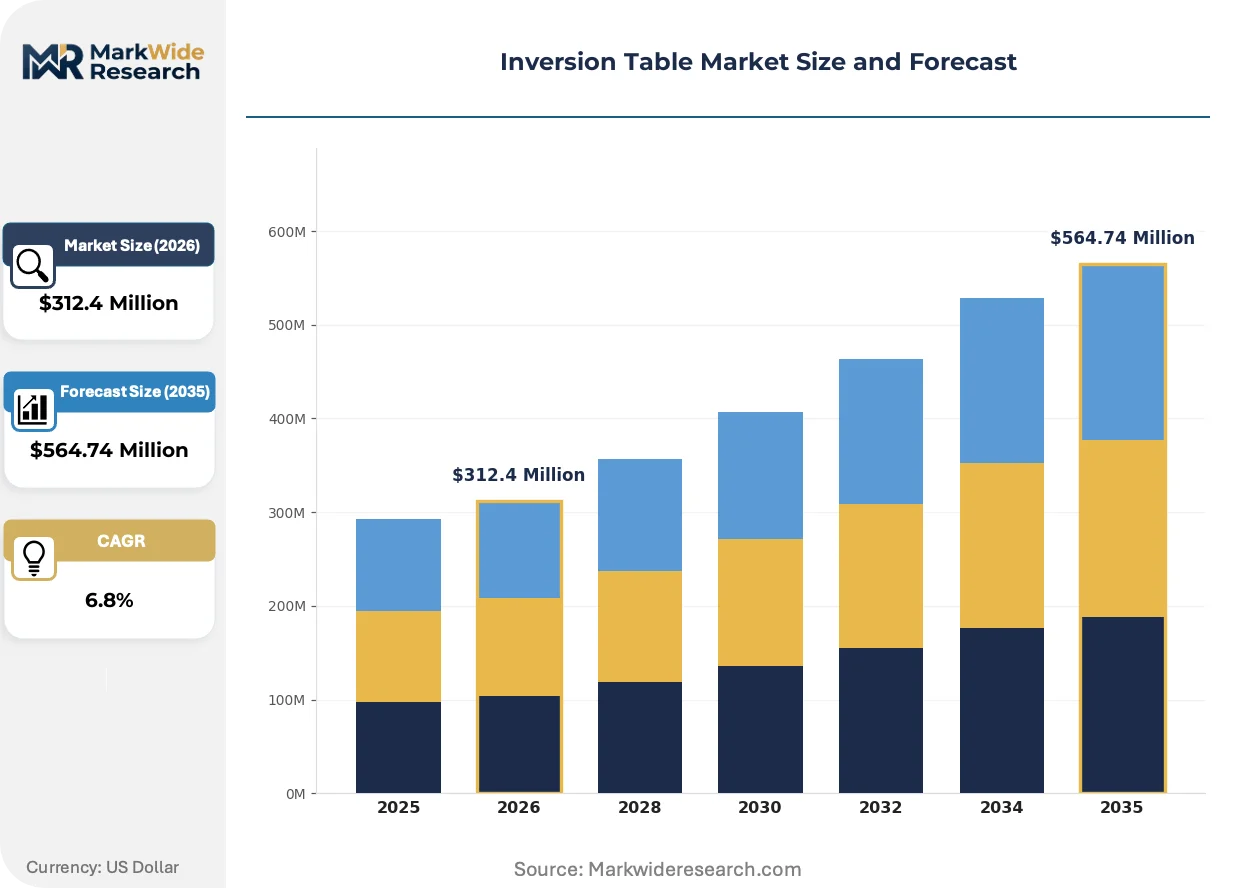
Market Dynamics
Post-pandemic preventive health habits have permanently shifted consumer spending toward home-based spinal decompression equipment, compressing traditional clinical channel volumes while expanding direct-to-consumer addressable demand. This behavioral pivot is forcing manufacturers to reconfigure certification strategies and distribution architectures simultaneously.
Growth Catalysts
- Aging demographics in the United States:The 65-plus population segment drives sustained replacement cycles for therapeutic home fitness equipment. Medicare Advantage supplemental benefit expansions for wellness devices accelerate household penetration.
- EU MDR reclassification protocols:Tighter clinical documentation requirements for Class I therapeutic devices create compliance moats for established manufacturers. European market access barriers filter out low-quality imports.
- Steel-frame value engineering:Automated tube bending and robotic welding reduce per-unit manufacturing costs for mass-market SKUs. Asian contract manufacturers achieve 15-20% cost advantages on standardized frame geometries.
Market Restraints
- Aluminum input cost volatility:LME aluminum price swings above 20% annually compress margins on portable foldable designs. Premium positioning becomes unsustainable during commodity spikes.
- Clinical reimbursement code uncertainty:CPT code modifications for spinal traction therapies threaten direct-to-consumer positioning. Manufacturers face channel conflict if clinical codes restrict retail availability.
- Substitution from suspension trainers:Low-cost bodyweight decompression systems capture price-sensitive segments. Core strengthening alternatives reduce addressable market for mechanical inversion.
Strategic Opportunities
- Apartment-dwelling urban clusters in Japan:Space-constrained Tokyo and Osaka households demand ultra-compact foldable designs. JIS standard compliance opens premium positioning above generic imports.
- Subscription-lease channel innovation:Asset-light rental models for premium motorized units reduce consumer capital barriers. Monthly fee structures align with fitness app subscription expectations.
- ISO 20957-1 certification convergence:Harmonized safety testing protocols reduce multi-jurisdiction compliance costs. Single-test certification enables rapid geographic expansion.
Industry Challenges
- Biomechanical engineering talent scarcity:Specialized expertise in spinal load dynamics and angle-precision motor control concentrates in orthopedic device hubs. Recruitment competes with medical imaging and surgical robotics sectors.
- CE marking timeline compression:EU MDR technical documentation requirements extend certification cycles to 12-18 months. Notified body capacity constraints delay European market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inversion Table Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Automatic, Deluxe, Foldable Material: Steel, Aluminum, Wood, Fabric Feature: Adjustable Angle, Safety Lock, Padded Surface, Portable End User: Gym Owners, Home Users, Health Clinics, Rehabilitation Centers |
| Companies Covered | Health Mark, Chinesport, Teeter, Health Gear, Fysiomed, Innova, Ironman, YOLEO, Body Flex Sport Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inversion Table Market Evolving Landscape
Digital angle-precision controls and connected wellness platforms are transforming inversion tables from passive mechanical devices into programmable therapeutic systems. This convergence demands new competencies in sensor integration and software validation.
Motorized automatic inversion is migrating from rehabilitation centers into affluent home segments. Physical therapy clinics in Germany and the United States adopted programmable angle precision first. Home fitness enthusiasts with chronic back conditions now demand equivalent clinical-grade control at 40-60% lower price points, compressing the premium tier definition.
The EU Medical Device Regulation reclassification tightens clinical evidence requirements for therapeutic claims. Manufacturers must submit biocompatibility testing and risk management files to notified bodies. Exporters targeting European markets are consolidating technical documentation functions and extending quality system investments to capture post-MDR market share.
Direct-to-consumer subscription bundling with telehealth platforms is displacing traditional retail channel dominance. Chronic pain management apps in North American markets now integrate hardware recommendations into treatment protocols. This channel shift concentrates marketing spend on digital acquisition rather than mass retail slotting fees, favoring brands with strong content and influencer ecosystems.
Inversion Table Market Segmentation
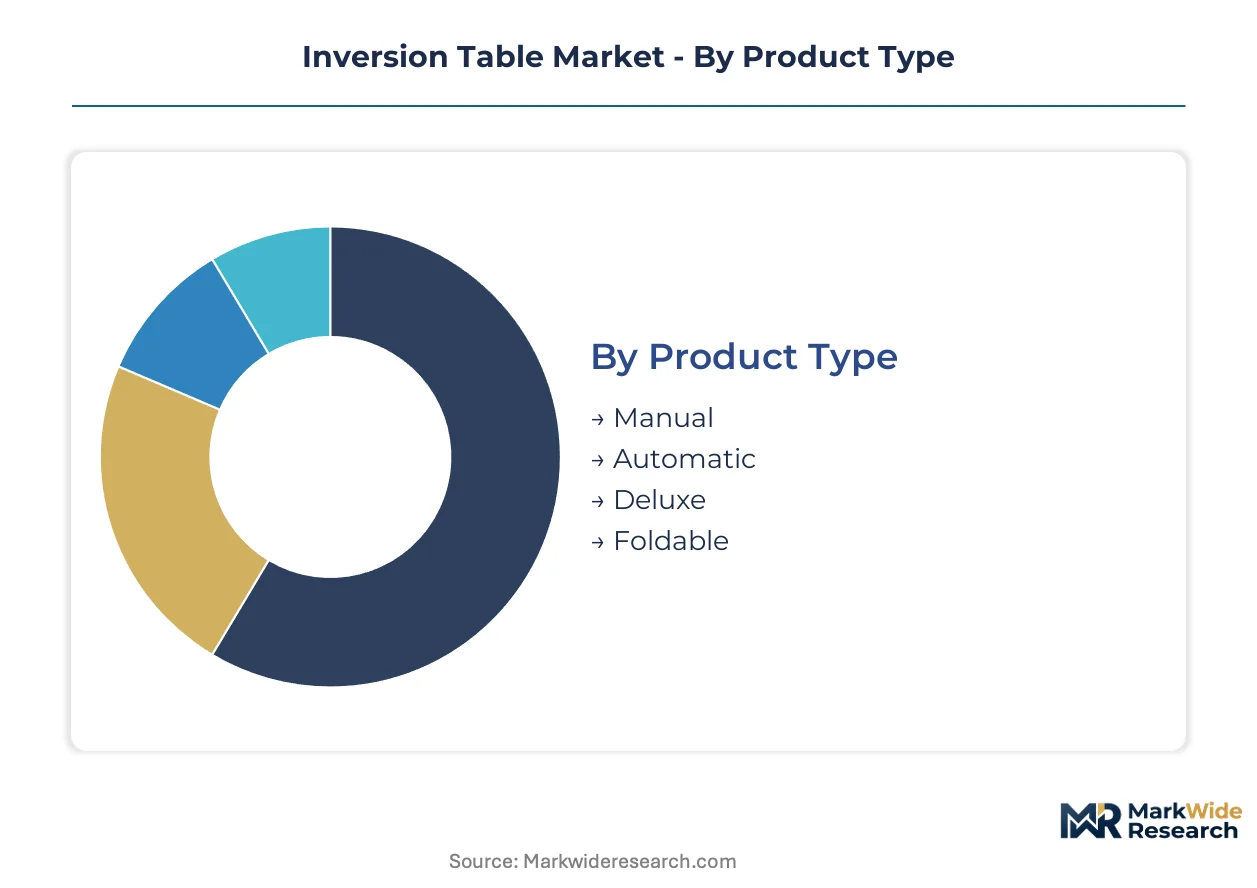
Inversion table manufacturers must navigate divergent engineering priorities across user environments, from space-constrained apartments to clinical rehabilitation protocols. Segmentation reveals where margin pools concentrate and which material or feature investments yield differentiation.
Product Type:
Mature mechanical designs anchor volume economics while emerging motorized variants capture premium positioning in therapeutic settings.
- Manual:Pivot-based mechanical rotation systems employ steel tethers and ankle-locking clamps without electrical components. Home fitness enthusiasts in the United States drive replacement cycles for these entry-level units, though price compression from Asian contract manufacturers squeezes branded margins.
- Automatic:Motorized angle-precision systems with programmable rotation speeds and remote controls command clinical-grade positioning. Rehabilitation centers in Germany and the United States adopted these first, with affluent home users now demanding equivalent functionality at reduced price points.
- Deluxe:Premium configurations integrate heat therapy, massage nodes, and extended padding for extended inversion sessions.
- Foldable:Collapsible frame geometries with quick-release hinges target apartment-dwelling urban consumers in Japan and South Korea.
Manual units retain volume leadership; automatic systems hold the steepest expansion curve.
Material:
Cost tier differentiation separates commodity steel construction from lightweight aluminum alternatives targeting portability premiums.
- Steel:High-tensile carbon or stainless steel tubing dominates frame construction across all channels, with automated tube bending and robotic welding reducing per-unit manufacturing costs. Asian contract manufacturers achieve cost advantages on standardized geometries that anchor mass-market SKUs.
- Aluminum:Aircraft-grade aluminum extrusions reduce frame weight by 40-50% for portable and foldable designs. Space-constrained urban consumers in Tokyo and Osaka pay premiums for these variants, though LME aluminum price volatility above 20% annually compresses margins during commodity spikes.
- Wood:Aesthetic hardwood finishes serve boutique wellness studios and design-conscious home segments in Scandinavian markets.
- Fabric:Reinforced nylon or canvas backboard materials reduce weight in ultra-portable travel-oriented models.
Steel construction commands absolute volume; aluminum frames are expanding most quickly among portable design categories.
Feature:
Application-specific functionality separates clinical-grade precision controls from convenience-oriented consumer features.
- Adjustable Angle:Tether strap or motorized systems enabling 15-degree to full 90-degree inversion control. Physical therapy protocols in the United States and Germany require precise angle documentation for reimbursement eligibility, driving specification requirements.
- Safety Lock:Mechanical or electromagnetic locking mechanisms securing the rotation arm during entry and exit. FDA quality system regulations mandate fail-safe designs for therapeutic claims, shaping engineering investments for US-bound manufacturers.
- Padded Surface:Memory foam or gel-infused backboards extending session comfort for chronic pain users.
- Portable:Quick-disassembly frames and carrying cases targeting traveling professionals and temporary rehabilitation setups.
Adjustable angle mechanisms retain specification dominance; safety lock integration climbs fastest as regulatory scrutiny intensifies.
End User:
Customer type determines channel architecture, with direct-to-consumer positioning diverging sharply from clinical procurement protocols.
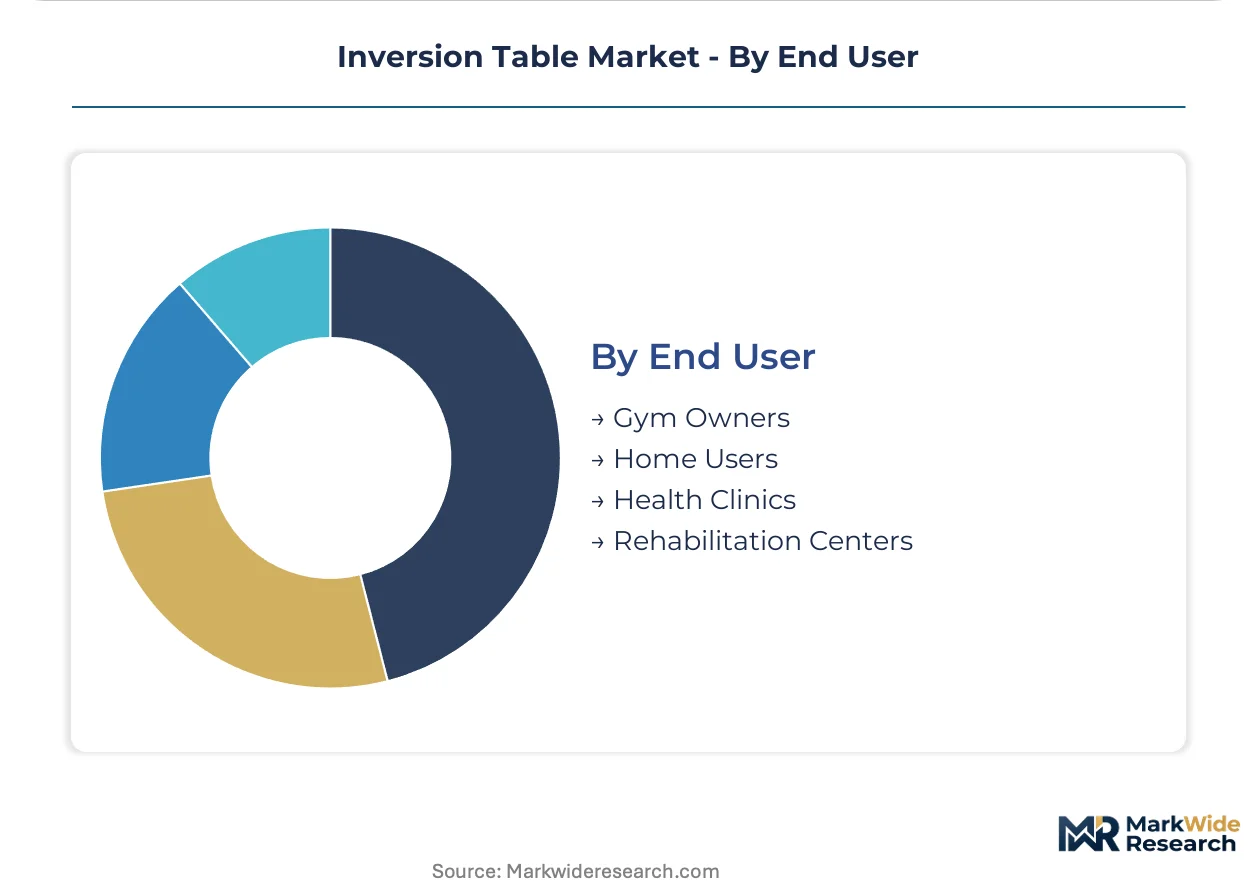
- Home Users:Individual consumers purchasing through e-commerce or mass retail for unsupervised spinal decompression routines. Post-pandemic preventive health habits in the United States have compressed traditional clinical channel volumes while expanding this addressable demand.
- Rehabilitation Centers:Outpatient physical therapy clinics requiring programmable angle precision and durable daily-use construction. Medicare Advantage supplemental benefit expansions for wellness devices accelerate equipment refresh cycles in US markets.
- Gym Owners:Commercial fitness facilities incorporating inversion stations into recovery zones or premium membership tiers.
- Health Clinics:Chiropractic and pain management practices utilizing inversion as adjunct therapy to spinal adjustment protocols.
Home users retain volume leadership; rehabilitation centers hold the steepest expansion curve as clinical-grade specifications migrate downward.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in inversion table equipment reveal a structural deficit in North American and European markets, with Asian contract manufacturers supplying standardized steel-frame units while domestic brands retain premium motorized segments. The United States absorbs the largest import volume, though FDA quality system compliance creates entry barriers for unqualified suppliers. Germany and Japan maintain trade surpluses in clinical-grade equipment.
United States
Medicare Advantage supplemental benefit expansions for wellness devices accelerate household penetration among the 65-plus demographic. FDA regulates therapeutic claims as Class I medical devices under quality system regulations. Dallas-Fort Worth and Phoenix metropolitan clusters concentrate distribution warehousing for direct-to-consumer fulfillment.
Germany
Outpatient physical therapy clinics drive specification requirements for programmable angle precision and reimbursement documentation. EU MDR reclassification imposes clinical evidence burdens on Class I therapeutic device exporters. Stuttgart and Munich industrial zones host precision motor control engineering for rehabilitation equipment.
Japan
Space-constrained Tokyo and Osaka households demand ultra-compact foldable designs with JIS standard compliance. METI oversees stationary training equipment safety certifications under harmonized ISO protocols. Nagoya manufacturing corridor produces aluminum extrusion components for portable frame geometries.
China
Asian contract manufacturers achieve cost advantages on standardized steel-frame geometries through automated tube bending and robotic welding. NMPA registration requirements apply to therapeutic devices marketed domestically. Zhengzhou and Ningbo industrial clusters supply mass-market SKUs to North American and European importers.
United Kingdom
Post-pandemic preventive health habits solidify demand for home-based spinal decompression equipment. MHRA enforces CE marking and UKCA compliance for therapeutic device claims. Greater London and Southeast England concentrate e-commerce distribution infrastructure for direct-to-consumer channels.
Inversion Table Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying standardized frame geometries and motor assemblies. The vendor base organizes around three tiers: heritage brands with decades-long engineering specialization, value-engineered mass-market fabricators, and Asian contract manufacturers competing on automated production scale. Strategic archetypes include premium positioning defenders, cost leadership challengers, and foldable-design innovators targeting urban density. Dominant competitive moves involve certification moat construction around EU MDR compliance and subscription-lease channel innovation reducing consumer capital barriers.
Within the heritage-brand tier, Teeter occupies a position exemplifying decades-long specialized engineering and premium North American channel presence. Among value-engineered fabricators, Innova represents mass-market positioning through steel-frame designs anchoring retail and e-commerce volumes. YOLEO sits within the foldable-innovation archetype, with product lines optimized for space-constrained apartment dwellers in Asian urban markets. These three company names anchor the competitive structure described in this study.
| Leading Market Players |
|---|
| Health Mark |
| Chinesport |
| Teeter |
| Health Gear |
| Fysiomed |
| Innova |
| Ironman |
| YOLEO |
| Body Flex Sport Inc. |
| Others |
Value Network & Pricing Analysis
Undercapacity in precision motor control engineering concentrates among orthopedic device hubs in Germany and the United States, forcing manufacturers to bid up specialized talent while Asian contract manufacturers exploit idle automated tube-bending capacity to compress steel-frame pricing. This utilization asymmetry splits the market into premium motorized tiers facing cost inflation and mass-market mechanical tiers absorbing price erosion.
Pricing Analysis
Home fitness enthusiasts anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on FDA certification tier and brand heritage, with Teeter commanding premiums against Innova's value-engineered positioning. Cost compression in mass-market steel frames is intensifying because Asian contract manufacturers achieve manufacturing advantages on standardized geometries. Rehabilitation centers exhibit the lowest price sensitivity due to reimbursement documentation requirements, while apartment-dwelling urban consumers in Japan drive portable aluminum premiums despite commodity volatility.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for mass-market steel-frame sourcing. Manufacturing concentrates in Zhengzhou and Ningbo industrial clusters for standardized geometries, with Nagoya supplying aluminum extrusion components and Stuttgart hosting precision motor engineering. Raw material dependencies center on high-tensile carbon steel tubing, aircraft-grade aluminum extrusions, and programmable motor assemblies. Single-source vulnerability concentrates in precision angle-control systems. Distribution runs through direct-to-consumer e-commerce channels and mass retail slotting for home users, with clinical procurement flowing through GPO contracts and hospital system partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital angle-precision convergence with telehealth platforms is disrupting traditional channel economics, with FDA and EU MDR regulatory inflections simultaneously raising compliance barriers and consolidating market access for qualified manufacturers.
For Market Incumbents: Harden certification moats around EU MDR technical documentation and FDA quality system investments to filter low-quality imports. Deepen backward integration into precision motor control engineering to offset talent scarcity in orthopedic device hubs. Defensive capacity addition in automated tube-bending facilities preserves cost competitiveness against Asian contract manufacturers. For New Entrants and Emerging Players: Subscription-lease models for premium motorized units in North American metropolitan clusters represent the most penetrable entry point, reducing consumer capital barriers while capturing recurring revenue streams. Foldable aluminum designs compliant with JIS standards for Tokyo and Osaka apartment dwellers offer geographic differentiation. Go-to-market execution should prioritize chronic pain management app integrations over mass retail slotting fees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among platform-integrated hardware providers bundling telehealth subscriptions. Long-term viability over a five-to-ten-year window favors manufacturers with consolidated technical documentation functions and extended quality system investments. Acquisition targets should demonstrate EU MDR certification completion and programmable angle-precision capabilities. The signal to watch is Medicare Advantage supplemental benefit expansion velocity for wellness device reimbursement codes.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Completion | Clinical documentation moats filter low-quality imports from European markets. |
| Telehealth Platform Integration | Hardware-software bundling displaces traditional retail channel dominance. |
| Subscription-Lease Channel Launch | Asset-light models align with fitness app subscription expectations. |
| Precision Motor Control R&D Investment | Programmable angle specifications migrate from clinics to affluent homes. |
| Foldable Aluminum Product Line Expansion | JIS-compliant designs capture premiums from space-constrained urban consumers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement records, and customs trade data. Primary interviews engaged product managers at heritage fitness equipment brands, biomedical engineers at rehabilitation centers, procurement leads at hospital GPOs, and contract manufacturing directors at Asian industrial clusters. Secondary validation drew from ISO 20957-1 safety certification registries, Medicare Advantage benefit expansion disclosures, and aluminum commodity pricing indices. Bottom-up unit economics modeling triangulates against top-down addressable market sizing across the projection horizon.
Forecast inputs incorporate product type segmentation by manual, automatic, deluxe, and foldable configurations alongside material tier differentiation and end-user channel architecture. CAGRs derive from replacement cycle analysis among aging demographics and penetration modeling for motorized migration into home segments. Industry-specific inputs include EU MDR certification timeline compression effects and Medicare reimbursement code development trajectories.
Practitioners should monitor aluminum LME price volatility, notified body capacity constraints for CE marking, and CPT code modifications for spinal traction therapies as early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Pericardial Patches Market
Medical Devices
Digital BTE Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Argentina Ultrasound Devices Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Global Sternal Closure Systems Market
Medical Devices
Nurse Call Systems Market
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Microdebrider Market
Medical Devices
Bioactive Fillings Market