
 Handheld Red Light Therapy Device Market | 2026-2036
Handheld Red Light Therapy Device Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Red Light Therapy Device Market Insights
LED chip substrates is pivoting from gallium arsenide to silicon-based alternatives, cutting raw material costs by half for mid-tier manufacturers. Novaalab leverages its direct-to-consumer channel to control pricing across North American markets. PlatinumLED anchors its position through medical-grade certification in European jurisdictions. Joovv competes on wavelength precision, offering narrow-spectrum devices that target mitochondrial stimulation with greater specificity.
Handheld red light therapy devices emit coherent or incoherent light in the 600–1000 nanometer range, typically powered by arrays of surface-mounted LEDs or low-level laser diodes, to stimulate cellular ATP production and modulate inflammatory cytokine expression. Portable units dominate unit shipments due to their accessibility for home users seeking pain relief and skin rejuvenation without clinical supervision. Wearable devices represent the fastest-growing product category as athletes and sports teams adopt continuous-use formats for muscle recovery protocols. Professional clinics still command the highest margin pool per unit sold, though home users generate the largest aggregate volume base across the end-user spectrum.
The FDA's Class II medical device framework and the EU Medical Device Regulation impose clinical evidence requirements that filter out uncertified competitors. Japan's PMDA and South Korea's MFDS maintain separate electromagnetic compatibility and biocompatibility testing protocols that add country-specific compliance layers. Stakeholders must monitor how divergent wavelength efficacy claims across regulatory jurisdictions reshape product labeling and marketing permissions.
Market Dynamics
The transition from gallium arsenide to silicon-based LED chip substrates is compressing input costs and enabling mid-tier manufacturers to challenge premium incumbents on price-performance metrics.
Growth Catalysts
- EU Medical Device Regulation:Clinical evidence requirements under MDR are filtering out uncertified competitors, concentrating demand among verified suppliers in dermatology clinics across Germany and France.
- Wearable form factor adoption:Sports medicine protocols in South Korea's aesthetic medicine sector are integrating continuous-use devices for muscle recovery, expanding the addressable user base beyond intermittent home use.
- Silicon substrate migration:LED manufacturers are halving raw material expenditures by pivoting from gallium arsenide wafers to silicon alternatives, unlocking margin expansion for mid-tier producers.
Market Restraints
- Gallium arsenide supply concentration:Specialized semiconductor foundries in Taiwan and China control high-purity substrate production, exposing device assemblers to input price volatility and allocation risk.
- FDA Class II compliance friction:The 510(k) pathway demands substantial clinical documentation and quality system audits, extending time-to-market for novel wavelength configurations by 12-18 months.
- Low-level laser competition:Coherent light devices from established aesthetic equipment manufacturers retain physician preference for targeted tissue penetration in professional settings.
Strategic Opportunities
- Japan's PMDA electromagnetic compatibility pathway:Separate testing protocols create first-mover advantages for manufacturers investing in country-specific biocompatibility validation ahead of domestic competitors.
- Athletic team procurement channels:Direct sales to professional sports organizations bypass retail margin erosion and establish volume commitments for wearable recovery formats.
- Telemedicine integration:Remote patient monitoring platforms are incorporating prescription-grade handheld units for post-surgical wound healing protocols, creating reimbursement-advantaged distribution.
Industry Challenges
- Optical engineering talent scarcity:The intersection of photobiomodulation science and consumer electronics design requires specialized expertise that concentrates in Boston, Eindhoven, and Seoul metropolitan clusters.
- Multi-jurisdiction certification timelines:Simultaneous FDA 510(k), EU MDR, and MFDS submissions demand dedicated regulatory affairs capacity that strains emerging manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Red Light Therapy Device Market |
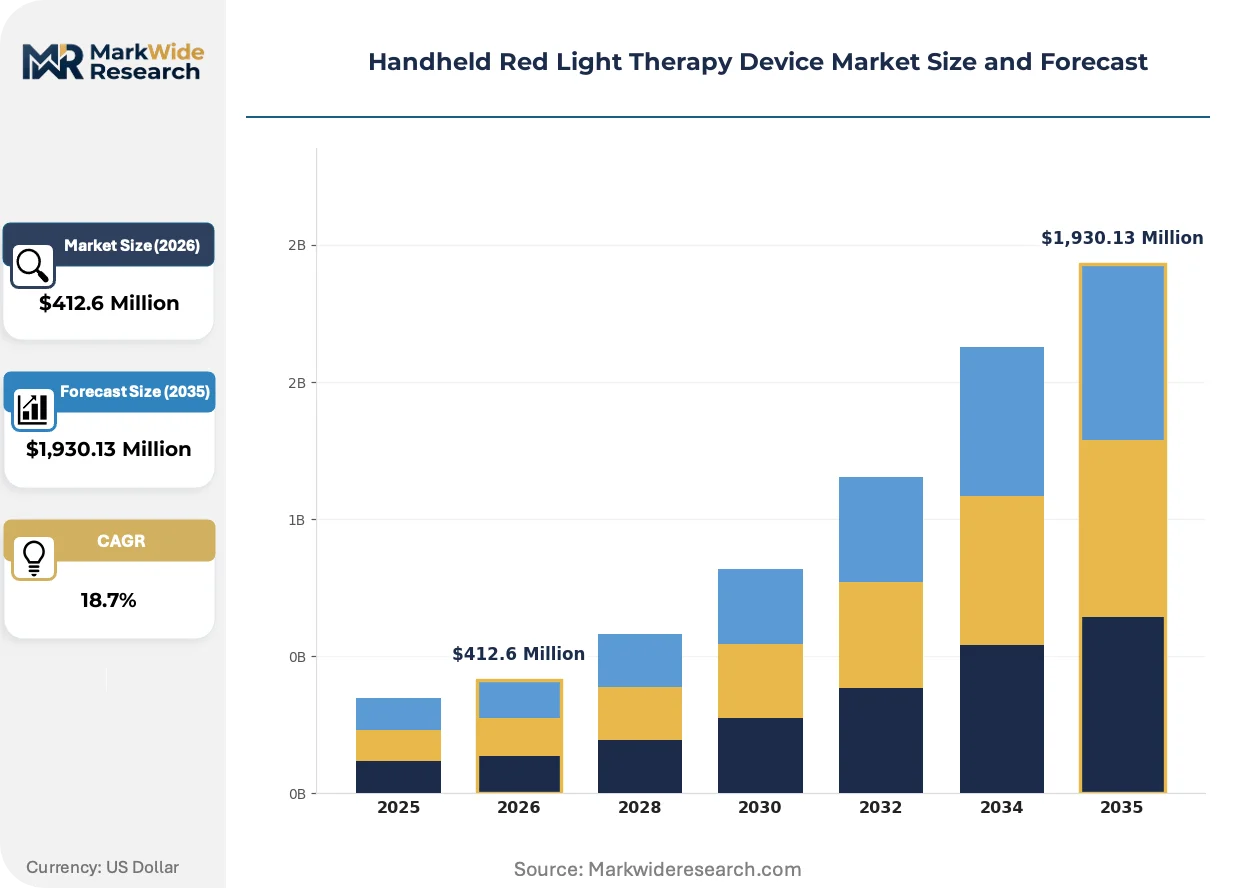
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $1,930.13 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wearable Devices, Handheld Applicators, Multi-Function Devices End User: Home Users, Professional Clinics, Wellness Centers, Sports Teams Technology: LED, Laser, Combination, Fluorescent Application: Pain Relief, Skin Rejuvenation, Muscle Recovery, Hair Growth |
| Companies Covered | Novaalab, PlatinumLED, Dermabeam, Viconor, BestQool, Hooga, Joovv, Lifepro, Kineon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Red Light Therapy Device Market Trends and Innovations
Wavelength precision and device modularity are displacing one-size-fits-all product architectures as clinicians and consumers demand targeted therapeutic protocols for specific tissue depths and conditions.
Multi-wavelength LED arrays with independent channel control are modularizing hardware platforms to support customizable treatment protocols. Dermatology clinics in Germany are adopting these configurable systems to sequence red and near-infrared exposure across post-procedure recovery timelines. The technology is modularizing supplier-customer relationships from transactional device sales toward ongoing protocol subscription models.
The EU Medical Device Regulation's clinical evidence requirements are compressing the competitive field to manufacturers with documented efficacy data. European notified bodies are prioritizing submissions with randomized controlled trials over bench-testing dossiers. Professional clinic segments in France and Italy are consolidating procurement around MDR-certified suppliers, accelerating certification-driven market concentration.
Direct-to-consumer channels are displacing traditional retail and clinical intermediaries for home-use segments. Novaalab's vertically integrated e-commerce infrastructure demonstrates how captive digital distribution captures margin otherwise lost to specialty retailers. This channel compression is most visible in North American markets where telehealth-adjacent wellness spending concentrates.
Handheld Red Light Therapy Device Market Segmentation
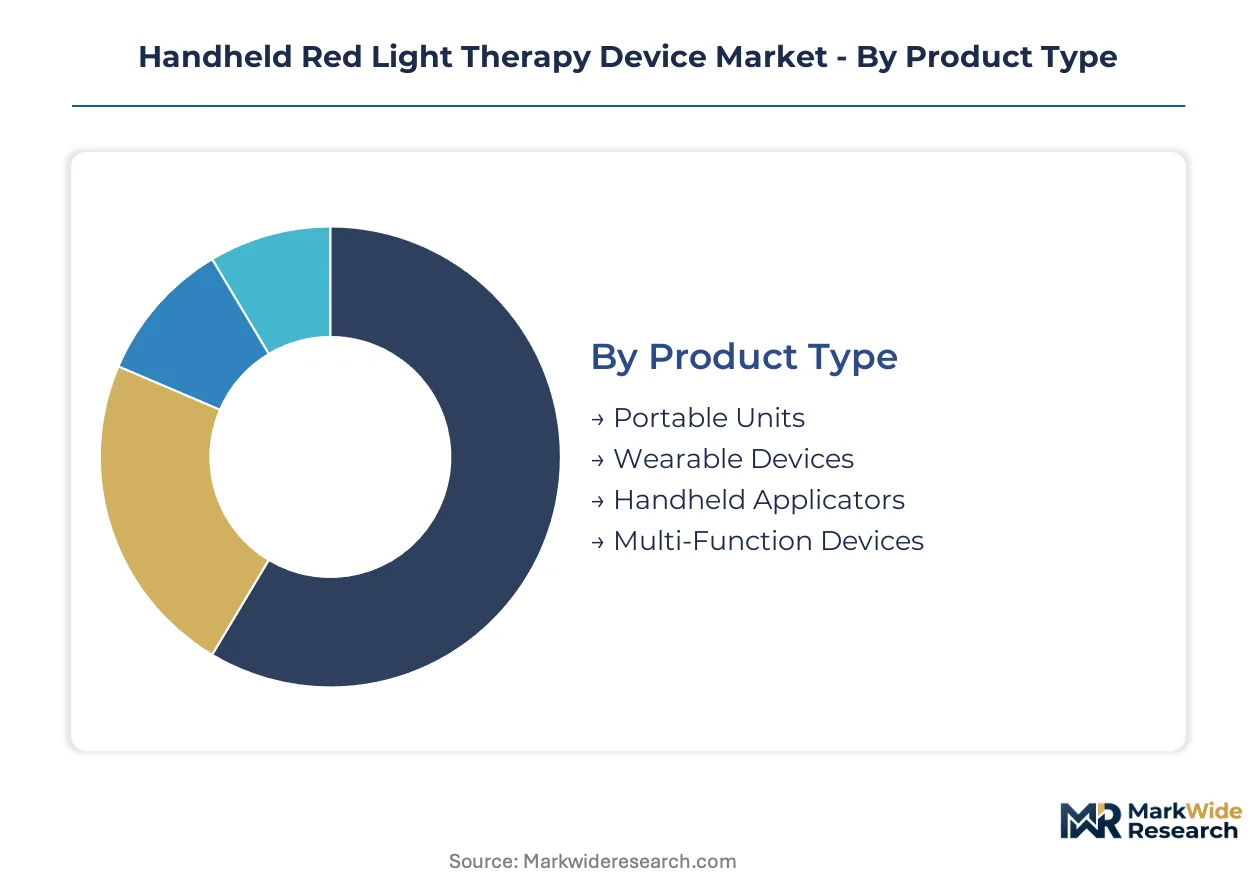
Device manufacturers configure product architectures around distinct use intensities and mobility requirements. Upgrade cycles accelerate where form factors enable new treatment protocols rather than incremental specification improvements.
Product Type:
Replacement decisions hinge on whether newer hardware unlocks treatment modalities unavailable through software updates alone.
- Portable Units:Battery-powered devices with surface-mounted LED arrays dominate unit economics through semiconductor miniaturization. Demand clusters among home users in North American markets seeking pain relief without clinical supervision, constrained by battery degradation curves that drive 3-4 year replacement windows.
- Wearable Devices:Continuous-use formats with flexible substrate integration enable ambulatory treatment protocols. Sports medicine procurement in South Korea's aesthetic medicine sector is expanding addressable use cases beyond stationary home treatment, though textile-embedded electronics raise wash-cycle durability concerns.
- Handheld Applicators:Pistol-grip ergonomics target localized tissue penetration with directional beam control.
- Multi-Function Devices:Modular wavelength switching combines red and near-infrared channels in single hardware platforms.
Volume placements concentrate in Portable Units; the faster expansion belongs to Wearable Devices.
End User:
Customer lifetime value diverges sharply between one-time home purchases and recurring professional procurement with service contracts.
- Home Users:Direct-to-consumer channels capture margin otherwise lost to retail intermediaries, with telehealth-adjacent wellness spending concentrating in North American markets. Price sensitivity limits attachment of disposable accessories, compressing recurring revenue potential.
- Professional Clinics:Dermatology practices in Germany integrate post-procedure protocols requiring MDR-certified hardware with documented efficacy data. Procurement consolidates around suppliers with randomized controlled trial dossiers, extending sales cycles but securing multi-year placement contracts.
- Wellness Centers:Membership-model facilities prioritize device durability under high-cycle commercial use.
- Sports Teams:Athletic organization procurement bypasses retail margin structures through direct manufacturer relationships.
Home Users generate the largest aggregate shipment base; Professional Clinics command the highest margin pool per unit placed.
Technology:
Substrate material transitions are compressing cost structures for mid-tier producers while coherent light maintains professional preference.
- LED:Silicon-based chip substrates are halving raw material expenditures versus gallium arsenide alternatives, enabling price-performance challenges to premium incumbents. Surface-mount packaging dominates portable and wearable formats.
- Laser:Coherent light sources retain physician preference in professional settings for targeted tissue penetration depth, though FDA Class II compliance friction extends 510(k) timelines.
- Combination:Hybrid architectures sequence LED and laser emission through shared control electronics.
- Florescent:Phosphor-converted broadband sources occupy economy positioning with lower wavelength precision.
LED technology captures the dominant placement volume; Combination systems are climbing the fastest as clinicians demand protocol flexibility.
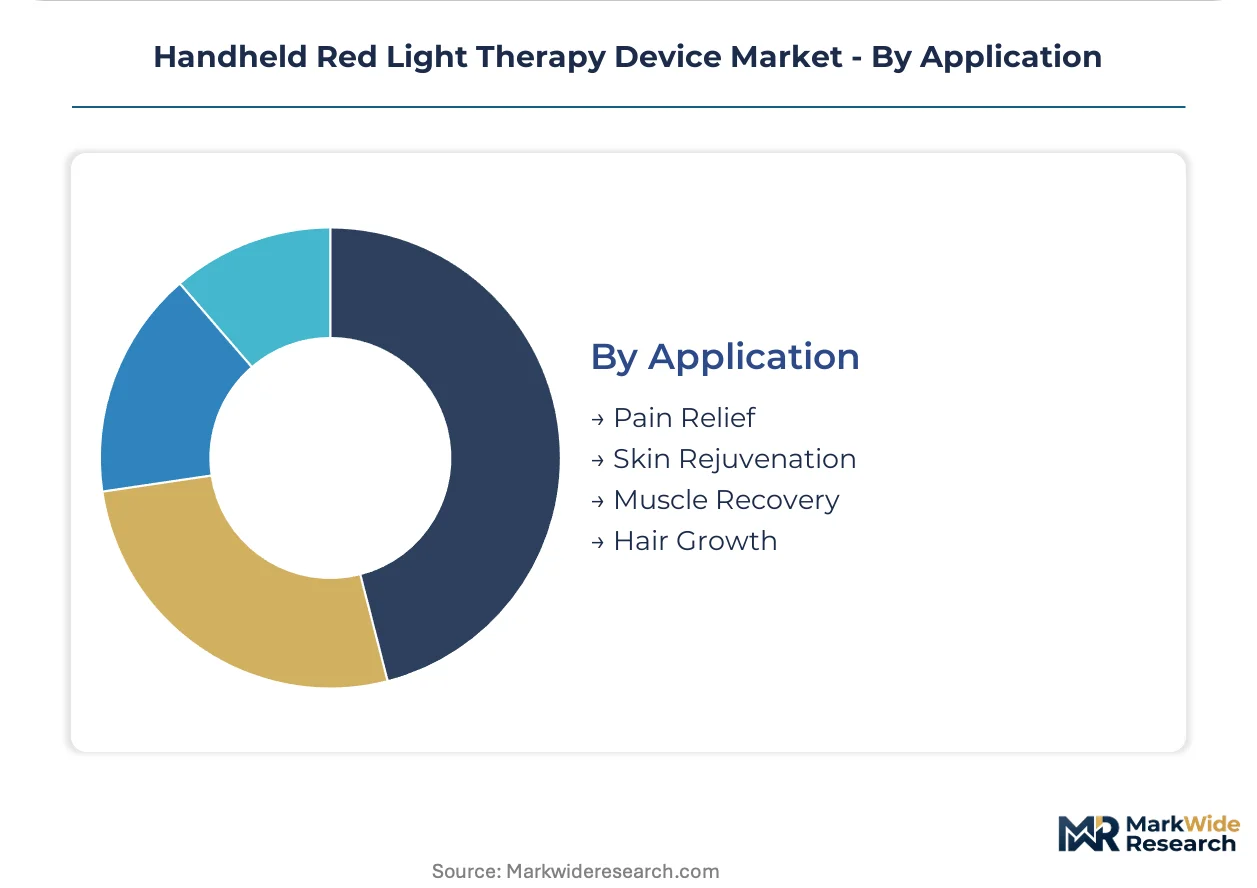
Application:
Treatment indication specificity is displacing general-purpose marketing claims as regulatory scrutiny intensifies.
- Pain Relief:Anti-inflammatory cytokine modulation drives adoption among aging demographics seeking non-pharmacological alternatives. Home-use penetration is highest where reimbursement codes remain unavailable, forcing out-of-pocket purchasing decisions.
- Skin Rejuvenation:Collagen synthesis stimulation commands premium pricing in aesthetic medicine, with dermatology clinics in Germany sequencing red and near-infrared exposure across post-procedure recovery timelines.
- Muscle Recovery:Athlete adoption is accelerating wearable format deployment for continuous-use protocols.
- Hair Growth:Follicular stimulation represents niche positioning with concentrated marketing spend on direct-to-consumer channels.
Pain Relief maintains the broadest installed base; Muscle Recovery is gaining share fastest through sports medicine integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in South Korea's Gyeonggi Province concentrate aesthetic device manufacturing through tax incentives and streamlined MFDS pre-approval pathways. Germany's MedTech clusters leverage EU MDR notified body proximity to compress certification timelines for professional-grade hardware.
United States
FDA 510(k) clearance requirements filter uncertified competitors from professional clinic procurement, concentrating demand among verified suppliers. The IRA's medical device tax provisions influence pricing strategies for home-use segments. Boston's photobiomodulation research cluster anchors optical engineering talent pipelines for wavelength precision development.
Germany
Dermatology clinics in Munich and Hamburg integrate post-procedure protocols requiring MDR-certified hardware with documented efficacy data. The EU Medical Device Regulation's clinical evidence requirements compress the competitive field to manufacturers with randomized controlled trial dossiers. The Eindhoven-Düsseldorf corridor concentrates LED substrate engineering expertise for silicon migration programs.
South Korea
Sports medicine protocols in Seoul's aesthetic medicine sector drive wearable format adoption for continuous muscle recovery use. MFDS electromagnetic compatibility testing protocols create first-mover advantages for manufacturers investing in domestic biocompatibility validation. Busan-Ulsan's semiconductor foundry ecosystem supplies high-purity substrates for mid-tier producers.
Japan
PMDA's separate electromagnetic compatibility and biocompatibility testing protocols add country-specific compliance layers for device assemblers. METI's medical device subsidy programs accelerate domestic adoption of prescription-grade handheld units. The Kanto region's precision electronics manufacturing base supports textile-embedded electronics for wearable formats.
United Kingdom
Post-Brexit divergence from EU MDR creates parallel certification pathways through the MHRA's UKCA marking requirements. London's wellness center density drives membership-model facility procurement prioritizing device durability under high-cycle commercial use. The Cambridge-Oxford corridor concentrates photobiomodulation research translating into startup formation.
Handheld Red Light Therapy Device Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with direct-to-consumer channels capturing margin otherwise lost to retail intermediaries. The vendor base concentrates around three strategic archetypes: vertically integrated e-commerce operators, medical-grade certification holders, and wavelength precision specialists. M&A activity targets optical engineering talent pools in Boston and Seoul, while portfolio diversification into wearable formats accelerates among athletic team procurement channels.
Among North American direct-to-consumer operators, Novaalab exemplifies the vertically integrated e-commerce archetype through captive digital distribution. PlatinumLED occupies a position within the medical-grade certification tier, anchoring European jurisdiction compliance. Joovv represents the wavelength precision specialist archetype, with narrow-spectrum positioning targeting mitochondrial stimulation specificity.
| Leading Market Players |
|---|
| Novaalab |
| PlatinumLED |
| Dermabeam |
| Viconor |
| BestQool |
| Hooga |
| Joovv |
| Lifepro |
| Kineon |
| Others |
Pricing and Supply Chain Analysis
Professional dermatology clinics in Germany and France anchor demand for MDR-certified hardware, forcing a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale differentiate tiers, with telemedicine-integrated procurement commanding premium positioning against direct-to-consumer spot purchases.
Pricing Analysis
Short lead times for MDR-certified inventory command 15-25% premiums over standard delivery windows, while spot inventory liquidation drives discounting in direct-to-consumer channels. Price differentiation hinges on FDA 510(k) tier versus uncertified economy positioning, with silicon substrate migration intensifying cost compression in mid-tier LED arrays. Home users in North American markets exhibit highest price sensitivity, whereas professional clinics in Germany accept premium positioning for documented efficacy data.
Supply Chain Analysis
Dual-sourcing requirements from MDR-notified bodies and FDA-registered assemblers mandate multi-supplier qualification for LED chip substrates and electromagnetic shielding components. Manufacturing concentrates in South Korea's Gyeonggi Province, Taiwan's semiconductor foundries, and Germany's MedTech clusters. Raw material dependencies span silicon wafers, gallium arsenide substrates, and biocompatible polymer housings. Single-source vulnerability in high-purity substrate production exposes assemblers to allocation risk. Distribution runs through direct-to-consumer e-commerce platforms and GPO-contracted clinical procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Medical Device Regulation's clinical evidence requirements erect a cost-of-compliance barrier that filters uncertified competitors and concentrates margin among dossier-holding incumbents.
For Market Incumbents: Cement market position by deepening backward integration into silicon substrate supply and securing multi-year GPO contracts with dermatology clinic networks. The threat of wearable-format specialists from South Korea's aesthetic medicine sector demands preemptive capacity addition in flexible substrate manufacturing.
For New Entrants and Emerging Players: Telemedicine platforms represent the most penetrable channel partner type for bypassing retail margin erosion and accessing prescription-grade reimbursement pathways. Target athletic team procurement channels in North American markets through direct manufacturer relationships, leveraging continuous-use protocol development as the go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors vertically integrated e-commerce operators with captive digital distribution and MDR certification dossiers. Long-term viability rests on consolidation plays capturing optical engineering talent pools in Boston and Seoul. Watch for MFDS pre-approval pathway acceleration as the inflection signal for South Korean market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | EU notified body proximity compresses timeline for dermatology clinic procurement in Germany. |
| Wearable Format Development | South Korea's sports medicine protocols drive continuous-use protocol adoption. |
| Silicon Substrate Migration | Raw material cost halving unlocks price-performance challenges to premium incumbents. |
| Telemedicine Platform Integration | Remote patient monitoring creates reimbursement-advantaged distribution for prescription-grade units. |
| Athletic Team Direct Sales | Professional sports organization procurement bypasses retail margin structures entirely. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with biomedical engineers, dermatology clinic procurement managers, GPO contracts specialists, and LED substrate manufacturing executives combined with FDA 510(k) databases, EU MDR notified body submissions, and MFDS electromagnetic compatibility filings. Bottom-up shipment modeling and top-down value estimation triangulated across the analysis window.
Data-stream reconciliation between professional clinic procurement databases and direct-to-consumer channel audits calibrated volume and value outputs across the projection horizon. Segmentation dimensions spanned product type, end-user archetype, technology substrate, and application indication. CAGRs derived from regression analysis against semiconductor miniaturization curves and aesthetic medicine procedure growth. Industry-specific inputs included wavelength precision adoption rates and wearable format durability testing outcomes.
Caveats apply where regulatory timeline acceleration or substrate supply disruption could materially shift the outlook. Forecasts reflect assumptions on certification pathway efficiency and silicon migration adoption curves. Deviation in FDA 510(k) backlog clearance or gallium arsenide supply allocation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Microwave Ablation Devices Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Global Smart Wearable Healthcare Devices Market
Medical Devices
Implantable Defibrillators Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Global Esophageal Catheters Market
Medical Devices
Wireless Portable Medical Devices Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
Global Vagus Nerve Stimulation Market
Medical Devices
Sinus Dilation Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Epidural Anesthesia Sets Market
Medical Devices
Global Portable Ultrasound Equipment Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Global Cosmetic Contact Lens Market