
 Depression Devices Market | 2026-2036
Depression Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Depression Devices Market Analysis
Psychiatrist-neuromodulation specialist availability is collapsing across rural health systems, forcing hospitals to rely on device platforms that general practitioners can operate with minimal certification. Medtronic leverages its deep neurostimulation portfolio to dominate implantable vagus nerve stimulation for treatment-resistant depression. Flow Neuroscience AB competes with a wearable transcranial direct current stimulation headset designed explicitly for home-use prescription models.
Depression devices comprise regulated therapeutic instruments that deliver electrical, magnetic, or photic stimuli to modulate neural circuits implicated in mood disorders, typically operating at frequencies between 1-20 Hz for magnetic protocols and requiring precise coil positioning over cortical targets. Transcranial Magnetic Stimulation systems anchor the highest-value segment due to established reimbursement and durable capital equipment revenue streams. Wearable Technology represents the fastest-expanding category as prescription-to-home workflows reduce per-treatment facility overhead and expand addressable patient pools beyond metropolitan clinic networks.
FDA breakthrough device pathways and CMS national coverage determinations shape commercial viability timelines for novel depression devices entering the US market. The EU MDR and FDA quality system regulations impose divergent clinical evidence requirements that fragment development roadmaps for firms pursuing simultaneous transatlantic approvals. Stakeholders must monitor evolving telehealth prescribing rules and state-level scope-of-practice expansions that determine whether home-use neurostimulation can bypass traditional clinic-based delivery economics.
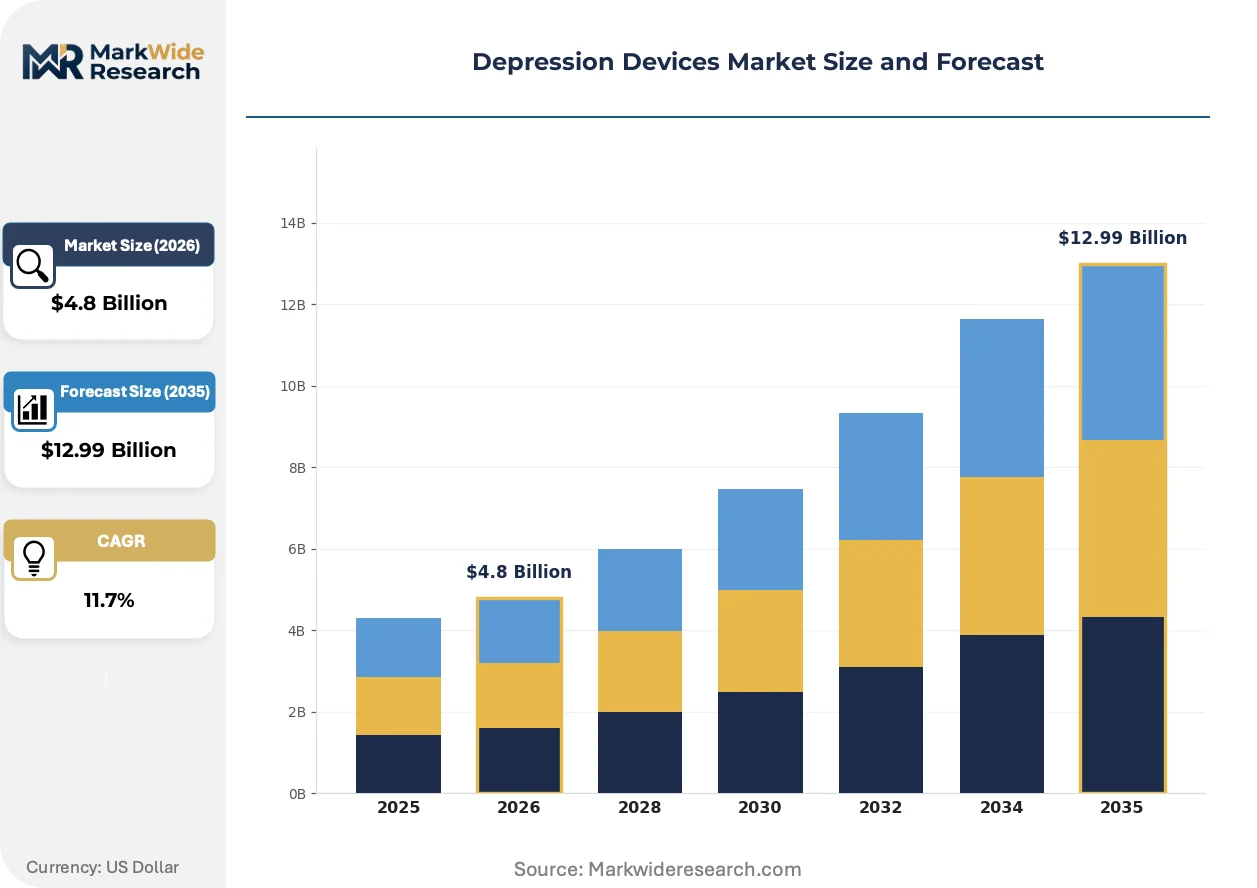
Market Dynamics
Reimbursement pathway fragmentation between CMS national coverage determinations and private payer prior authorization requirements is compressing commercialization timelines for novel neuromodulation platforms while expanding the addressable patient pool for established transcranial magnetic stimulation protocols.
Growth Catalysts
- CMS Reimbursement Expansion:New national coverage determinations for device-based depression therapies in US hospital outpatient departments reduce patient cost burden and accelerate provider adoption of capital equipment.
- Home-Use Prescription Models:Wearable transcranial direct current stimulation systems enable remote patient monitoring platforms to extend therapeutic access beyond metropolitan clinic networks.
- Rural Health System Constraints:Psychiatrist-neuromodulation specialist shortages across non-urban US health systems force hospitals to deploy device platforms operable by general practitioners with minimal certification requirements.
Market Restraints
- Capital Equipment Intensity:Transcranial magnetic stimulation systems require substantial facility investment and dedicated technician staffing, limiting deployment to well-capitalized health systems.
- Regulatory Divergence:EU MDR clinical evidence requirements for neurostimulation devices impose development roadmaps incompatible with FDA breakthrough device pathways, fragmenting transatlantic approval strategies.
- Implantable Procedure Barriers:Vagus nerve stimulation for treatment-resistant depression requires surgical intervention, restricting candidacy to patients with adequate insurance coverage and geographic access to specialized surgical centers.
Strategic Opportunities
- Telehealth Prescribing Expansion:Evolving state-level scope-of-practice regulations in the US may enable remote physician oversight of home-use neurostimulation, bypassing traditional clinic-based delivery economics.
- Technology Convergence:Integration of wearable stimulation hardware with digital biomarker monitoring and algorithmic dosing adjustment creates closed-loop therapeutic systems.
- Underpenetrated Rural Markets:Non-metropolitan US regions with limited psychiatric specialist density represent expansion targets for simplified device platforms with reduced operator training requirements.
Industry Challenges
- Specialist Training Bottlenecks:Certified neuromodulation technician programs fail to produce sufficient operators to match installed base expansion rates, constraining treatment throughput at existing facilities.
- Prior Authorization Friction:Private payer medical necessity documentation requirements for device-based depression therapies create administrative burden that delays patient access and increases provider operational costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Depression Devices Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Transcranial Magnetic Stimulation, Neurostimulation Devices, Biofeedback Devices, Wearable Technology Treatment Modality: Cognitive Behavioral Therapy, Mindfulness Techniques, Light Therapy, Medication Management End User: Patients, Healthcare Providers, Research Institutions, Rehabilitation Centers Delivery Mode: In-Clinic Treatment, Home Use, Teletherapy, Mobile Applications |
| Companies Covered | Medtronic, Abbott Laboratories, Boston Scientific, Neuronetics, Nevro Corp., LivaNova PLC, Flow Neuroscience AB, Electromedical Products International, Inc., NeuroSigma, Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Depression Devices Market Emerging Trajectories
Neuromodulation hardware is separating into capital-intensive clinic-based systems and lightweight prescription-to-home wearables, with software-enabled service layers capturing an expanding share of total therapeutic value.
Transcranial direct current stimulation is bifurcating into prescription-grade wearable headsets with embedded dose tracking and consumer wellness devices with unregulated output parameters. Psychiatric clinics in the United States are adopting the prescription-grade segment for remote patient monitoring programs, while wellness channels absorb the unregulated tier. This split is compressing price points at the boundary between medical and consumer categories while expanding the total addressable population for mild-to-moderate depression management outside traditional healthcare facilities.
FDA breakthrough device designation pathways for neurostimulation systems are compressing premarket review timelines for novel depression therapies targeting treatment-resistant populations. The industrial consequence accelerates first-mover advantage accumulation for firms with established quality management systems and prior FDA clearance histories. Transcranial magnetic stimulation manufacturers with existing 510(k) portfolios respond by filing breakthrough applications for next-generation coil geometries and accelerated treatment protocols.
Patient acquisition through traditional psychiatric referral networks is giving way to direct-to-patient digital channels with embedded clinical screening and telehealth prescribing. Employer-sponsored mental health benefits and specialty pharmacy distributors are displacing hospital outpatient departments as the primary channel for initiating device-based depression therapy. This channel rotation is most visible in the United States, where large self-insured employers and digital health platforms are integrating wearable neuromodulation into employee assistance program offerings.
Depression Devices Market Segmentation
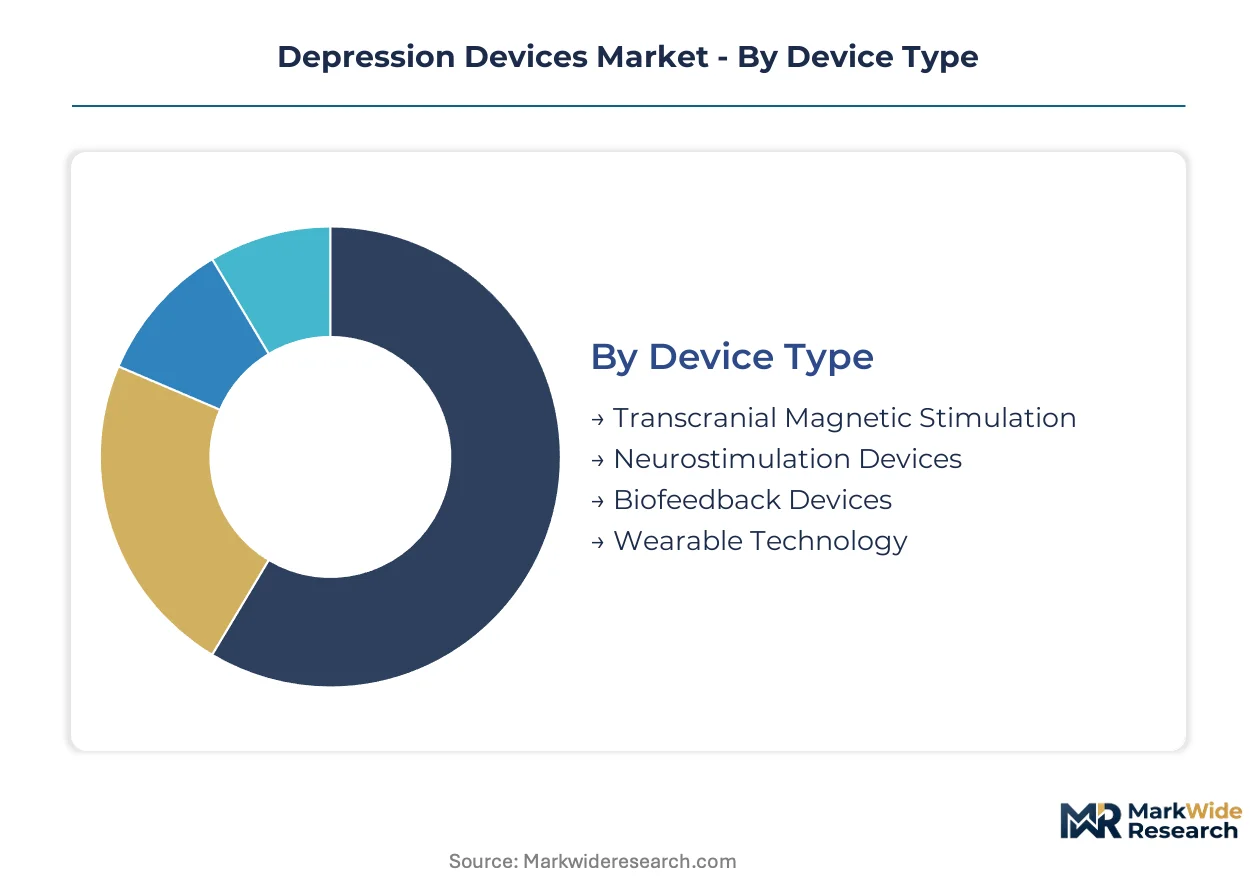
Depression devices segment across hardware specifications, clinical workflows, and care settings. Each dimension shapes reimbursement pathways, regulatory requirements, and competitive positioning for manufacturers navigating psychiatric care delivery transformation.
Device Type:
Margin pools concentrate in capital equipment with durable service revenue and consumable components, while wearable formats capture recurring subscription economics.
- Transcranial Magnetic Stimulation:Coil-based magnetic field generators operating at 1-20 Hz require precise positioning over dorsolateral prefrontal cortex targets. Psychiatric clinics in the United States anchor demand where CMS national coverage determinations and established prior authorization workflows minimize patient cost burden.
- Wearable Technology:Lightweight headsets delivering transcranial direct current stimulation through embedded electrode arrays enable prescription-to-home workflows. Rural health systems with psychiatrist-neuromodulation specialist shortages are expanding fastest as general practitioners operate these platforms with minimal certification.
- Neurostimulation Devices:Implantable vagus nerve stimulation systems for treatment-resistant depression require surgical intervention and specialized programming.
- Biofeedback Devices:Physiological monitoring instruments tracking heart rate variability and galvanic skin response for mood regulation training.
The dominant share belongs to Transcranial Magnetic Stimulation, while Wearable Technology is gaining share fastest through remote patient monitoring platform integration.
Treatment Modality:
Clinical evidence requirements and reimbursement codes determine which modalities device manufacturers can bundle with hardware sales versus position as standalone digital therapeutics.
- Medication Management:Device-drug combination protocols where neuromodulation augments antidepressant pharmacotherapy. Hospital outpatient departments in the United States concentrate demand where FDA breakthrough device designations accelerate CMS coverage determinations for adjunctive device use.
- Light Therapy:Photic stimulation systems targeting circadian rhythm disruption in seasonal affective disorder subtypes. Northern latitude markets with pronounced seasonal variation show strongest utilization patterns.
- Cognitive Behavioral Therapy:Digital platforms integrating neuromodulation with structured psychotherapy protocols.
- Mindfulness Techniques:Biofeedback-guided meditation systems with real-time physiological monitoring.
Medication Management holds the largest installed base, though Light Therapy is climbing the fastest in employer-sponsored mental health benefit programs.
End User:
Purchasing authority and reimbursement access separate institutional buyers from direct-to-patient channels.
- Healthcare Providers:Psychiatric clinics and hospital outpatient departments with capital equipment budgets and technician staffing. The United States dominates where provider network density and payer coverage for device-based depression therapies are most developed.
- Patients:Direct acquisition through prescription-to-home models with telehealth oversight. State-level scope-of-practice expansions are enabling remote physician monitoring that bypasses traditional clinic economics.
- Research Institutions:Academic medical centers conducting clinical trials for novel neuromodulation protocols.
- Rehabilitation Centers:Post-acute care facilities integrating mood disorder treatment into broader functional recovery programs.
Healthcare Providers command the primary revenue channel, while Patients are expanding most quickly through digital health platform distribution partnerships.
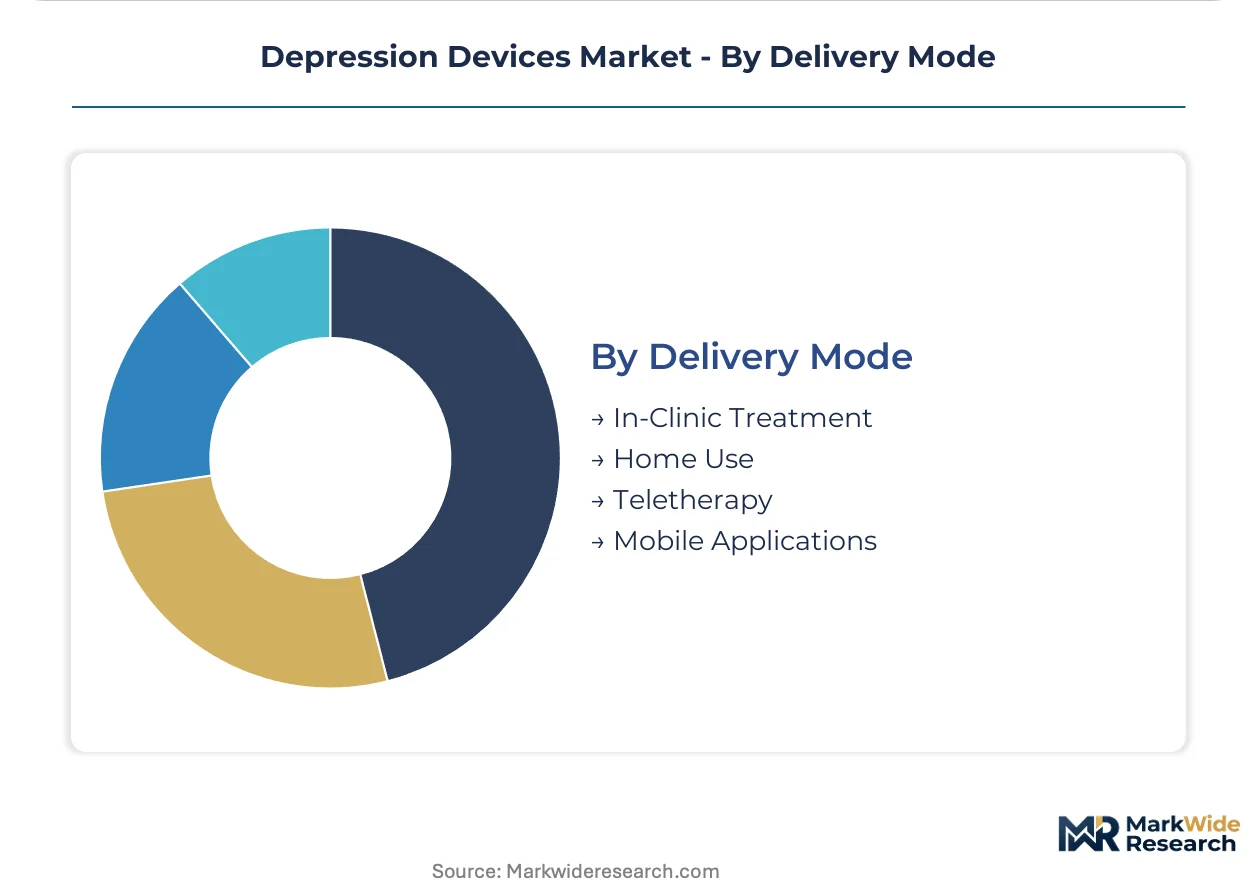
Delivery Mode:
Facility overhead and labor intensity create divergent margin structures across site-of-care options.
- In-Clinic Treatment:Technician-supervised sessions with coil positioning verification and physiological monitoring. Metropolitan health systems in the United States concentrate deployment where certified neuromodulation specialist availability supports treatment throughput.
- Home Use:Prescription-grade wearable systems with embedded dose tracking and algorithmic adjustment. Telehealth prescribing rule evolution is enabling remote oversight that reduces per-treatment facility overhead.
- Teletherapy:Video-based clinical supervision of self-administered neuromodulation sessions.
- Mobile Applications:Software layers capturing patient-reported outcomes and adherence data for care coordination.
In-Clinic Treatment retains the largest revenue base, though Home Use shows the steepest expansion trajectory as prescription workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Depression devices deploy through fundamentally different care models across markets. The United States channels demand through reimbursed clinic-based systems with home-use expansion, while European markets navigate divergent regulatory pathways and Asian markets confront specialist density constraints that favor simplified operator platforms.
United States
Psychiatric clinics and hospital outpatient departments anchor device demand where CMS national coverage determinations reduce patient cost burden. FDA breakthrough device designations accelerate premarket review timelines for novel neuromodulation systems targeting treatment-resistant populations. Metropolitan health systems in Boston, New York, and Los Angeles concentrate installed base expansion, though rural health networks in the Midwest and Mountain West are deploying simplified platforms operable by general practitioners.
Germany
Hospital outpatient departments and academic medical centers drive transcranial magnetic stimulation adoption within statutory health insurance frameworks. EU MDR clinical evidence requirements for neurostimulation devices impose development roadmaps that fragment transatlantic approval strategies for manufacturers. The Rhine-Ruhr and Bavarian medical technology clusters around Munich and Nuremberg host neuromodulation research programs and specialized psychiatric treatment centers.
United Kingdom
NHS England commissioning frameworks determine reimbursement access for device-based depression therapies through specialized mental health services. NICE technology appraisals evaluate clinical and cost-effectiveness evidence for neuromodulation systems prior to routine commissioning. London and the Southeast concentrate provider density, while NHS Scotland and regional trusts in Northern England pilot remote patient monitoring programs for home-use wearable systems.
Japan
PMDA regulatory pathways and reimbursement listings under the national health insurance system shape commercialization timelines for imported and domestic neuromodulation devices. METI industrial policy supports medical device innovation clusters through R&D subsidies and regulatory harmonization initiatives. The Kanto region around Tokyo and the Kansai region around Osaka host the majority of psychiatric specialist capacity and device clinical trial activity.
Australia
Private health insurance coverage and Medicare Benefits Schedule listings determine patient access to transcranial magnetic stimulation in psychiatric practice settings. TGA conformity assessment procedures for active implantable medical devices impose evidence requirements that parallel FDA pathways. Sydney and Melbourne metropolitan areas concentrate neuromodulation service provision, with telehealth prescribing rules enabling rural and regional patient access to device-based therapies.
Depression Devices Market Vendor Landscape
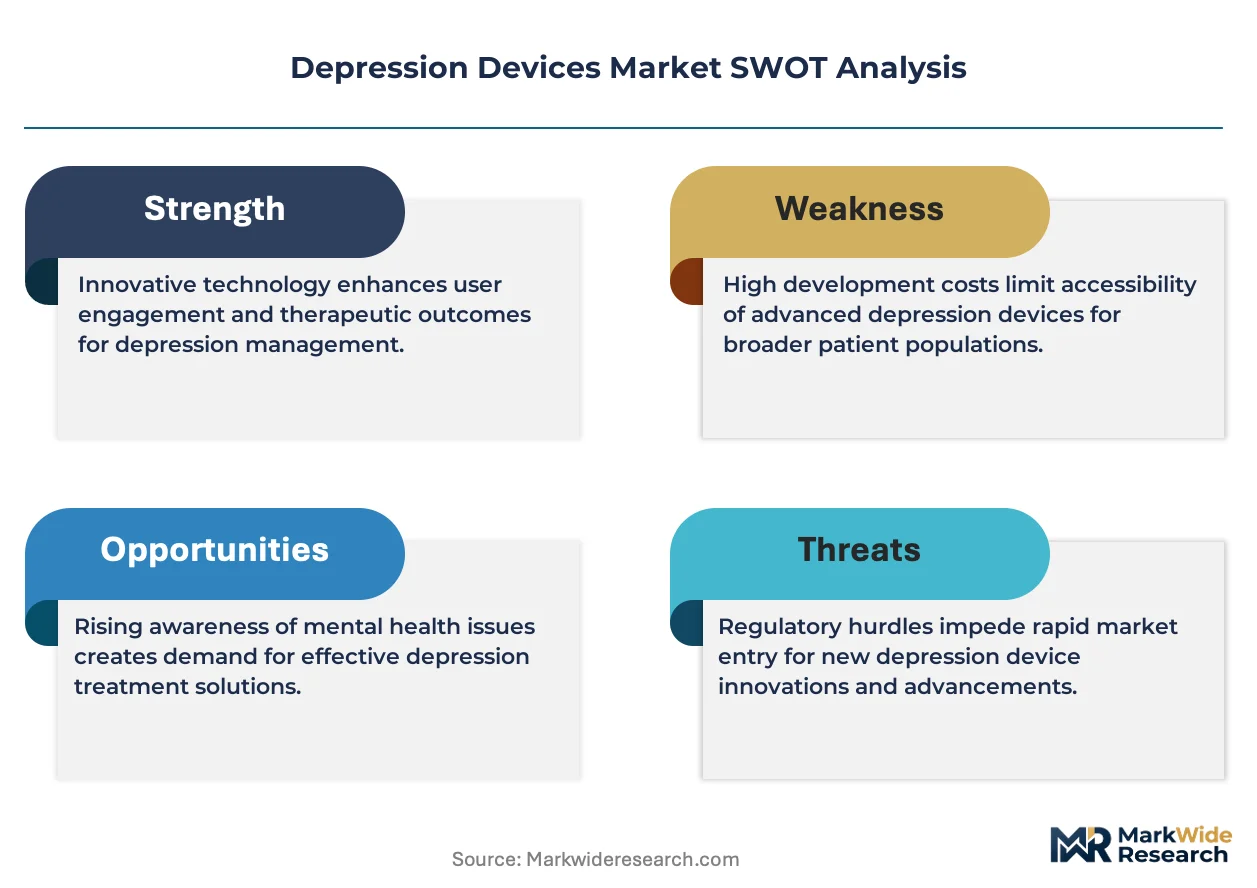
A small set of integrated leaders sits above a broader specialist tier in the depression devices market. Large diversified medical technology corporations with established neurostimulation portfolios leverage regulatory expertise and reimbursement relationships to dominate implantable segments. Mid-size neuromodulation specialists compete on coil geometry innovation, accelerated treatment protocols, and prescription-to-home workflow design. The dominant competitive moves center on FDA breakthrough pathway navigation and strategic partnerships with telehealth platforms to bypass traditional clinic-based distribution economics.
Within the diversified medical technology tier, Medtronic and Abbott Laboratories exemplify integrated players with deep neurostimulation portfolios spanning multiple neurological indications. Among neuromodulation specialists, Neuronetics occupies a position representing clinic-based transcranial magnetic stimulation systems, while Flow Neuroscience AB exemplifies the prescription-to-home wearable segment. These company patterns illustrate the market's bifurcation between capital-intensive institutional platforms and lightweight remote-monitoring formats.
| Leading Market Players |
|---|
| Medtronic |
| Abbott Laboratories |
| Boston Scientific |
| Neuronetics |
| Nevro Corp. |
| LivaNova PLC |
| Flow Neuroscience AB |
| Electromedical Products International, Inc. |
| NeuroSigma, Inc |
| Others |
Supply Flow & Price Mechanics
Home-use wearable tDCS systems substituting for clinic-based TMS protocols are redistributing manufacturing capacity from capital equipment hubs toward consumer electronics corridors in China and Vietnam while compressing per-unit margins through volume scaling and reduced regulatory overhead.
Pricing Analysis
Long-term offtake contracts dominate institutional procurement of TMS systems, with hospital systems negotiating multi-year service agreements that bundle hardware, technician training, and maintenance. Price differentiation separates FDA-cleared prescription-grade wearables from unregulated wellness devices through reimbursement eligibility and clinical validation requirements. Pricing pressure stems from employer-sponsored mental health benefits demanding cost-per-treatment reductions. Large self-insured employers exhibit highest price sensitivity; academic medical centers with research funding demonstrate lowest.
Supply Chain Analysis
Inventory lead times for TMS coil assemblies and magnetic field generators extend to 16-24 weeks due to specialized copper winding and ferrite core sourcing from Germany, Japan, and the United States. Raw material dependencies center on high-purity copper, rare-earth magnetic alloys, and medical-grade polymers for biocompatible electrode arrays. Single-source vulnerability concentrates in precision coil winding equipment manufactured by German and Japanese machine tool specialists. Distribution runs through GPO contracts for institutional buyers and specialty pharmacy channels for prescription-to-home workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent neuromodulation manufacturers face substitution defense against digital therapeutics and AI-guided cognitive behavioral platforms that promise comparable efficacy without hardware overhead.
For Market Incumbents: Fortify installed base loyalty through embedded software service layers that lock in recurring revenue and raise switching costs. Deepen backward integration into coil manufacturing to insulate margin pressure from copper and magnetic alloy volatility. Accelerate FDA breakthrough pathway filings for next-generation accelerated treatment protocols to outpace digital therapeutic efficacy claims. For New Entrants and Emerging Players: Lead with rural health system penetration where psychiatrist-neuromodulation specialist shortages create immediate demand for general practitioner-operable platforms. Target the Midwest and Mountain West regions with simplified certification requirements and telehealth-integrated oversight models. Pursue direct-to-patient digital channels with embedded clinical screening to bypass established hospital outpatient department procurement. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed neuromodulation specialists possessing FDA clearance histories but constrained distribution reach. Long-term viability hinges on convergence toward closed-loop therapeutic systems integrating hardware, biomarker monitoring, and algorithmic dosing. Watch for state-level scope-of-practice expansions enabling remote physician oversight of home-use neurostimulation as inflection signal for prescription-to-home workflow maturation.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates premarket review timelines for treatment-resistant depression indications. |
| CMS Reimbursement Strategy | Secures national coverage determinations that reduce patient cost burden and expand addressable pools. |
| Telehealth Platform Partnership | Enables remote physician oversight that bypasses traditional clinic-based delivery economics. |
| Software Companion Development | Creates closed-loop therapeutic systems with algorithmic dosing adjustment and adherence monitoring. |
| Hospital System Partnership | Locks in capital equipment placement through integrated service agreements and technician training programs. |
Methodological Framework
The analysis maps transcranial magnetic stimulation systems, wearable tDCS platforms, implantable neurostimulation devices, and biofeedback instruments, each validated through psychiatrists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Primary interviews with neuromodulation specialists and regulatory affairs executives combined with secondary validation against FDA 510(k) filings, CMS national coverage determinations, clinical trial registries, and hospital procurement databases. Bottom-up unit economics triangulated against top-down market sizing across device categories.
Consistency checks validated volume and value outputs against external benchmarks including installed base expansion rates, reimbursement code utilization, and capital equipment shipment data. Segmentation dimensions modeled include device type, treatment modality, end user category, and delivery mode across the projection horizon. CAGRs derived from patient population growth, provider network expansion, and payer coverage evolution. Forecast inputs incorporated FDA breakthrough designation timelines and state-level telehealth prescribing rule changes.
Underlying assumptions cover CMS reimbursement stability, EU MDR regulatory pathway continuity, and psychiatrist-neuromodulation specialist supply constraints, with deviation risk concentrated in private payer prior authorization friction and digital therapeutic efficacy claims. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Anesthesia Resuscitators Masks Market
Medical Devices
Medical Device and Accessories Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Absorbable Antibacterial Envelope Market
Medical Devices
Veterinary Anesthesia Equipment Market
Medical Devices
Adjustable Speed Vortex Mixer Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
China Contraceptive Devices Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Needle Destroyer Market
Medical Devices
Global Surgical Power Tools Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Global Deep Brain Stimulation Devices Market
Medical Devices
Mobile Operating Rooms Market