
 Global Wearable Healthcare Devices Market | 2026-2036
Global Wearable Healthcare Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wearable Healthcare Devices Market Outlook
FDA 510(k) premarket notification volume is expanding, raising compliance investment thresholds for new entrants while rewarding incumbents with established quality management systems. Abbott Laboratories leverages its FreeStyle Libre ecosystem to anchor glucose monitoring within integrated care workflows. Dexcom, Inc. differentiates through sensor accuracy benchmarks that sustain premium positioning in intensive insulin therapy.
Wearable healthcare devices encompass body-worn instruments that capture physiological data through biosensors, accelerometers, and photoplethysmography modules, transmitting metrics via Bluetooth or Wi-Fi to clinical decision support platforms for preventive screening and disease management. Smartwatches and health monitors dominate hardware shipment value, while fitness trackers face margin compression as sensor commoditization accelerates in the consumer tier. Chronic disease management applications command the highest reimbursement rates, whereas fitness tracking remains volume-led with enterprise wellness programs driving bulk procurement.
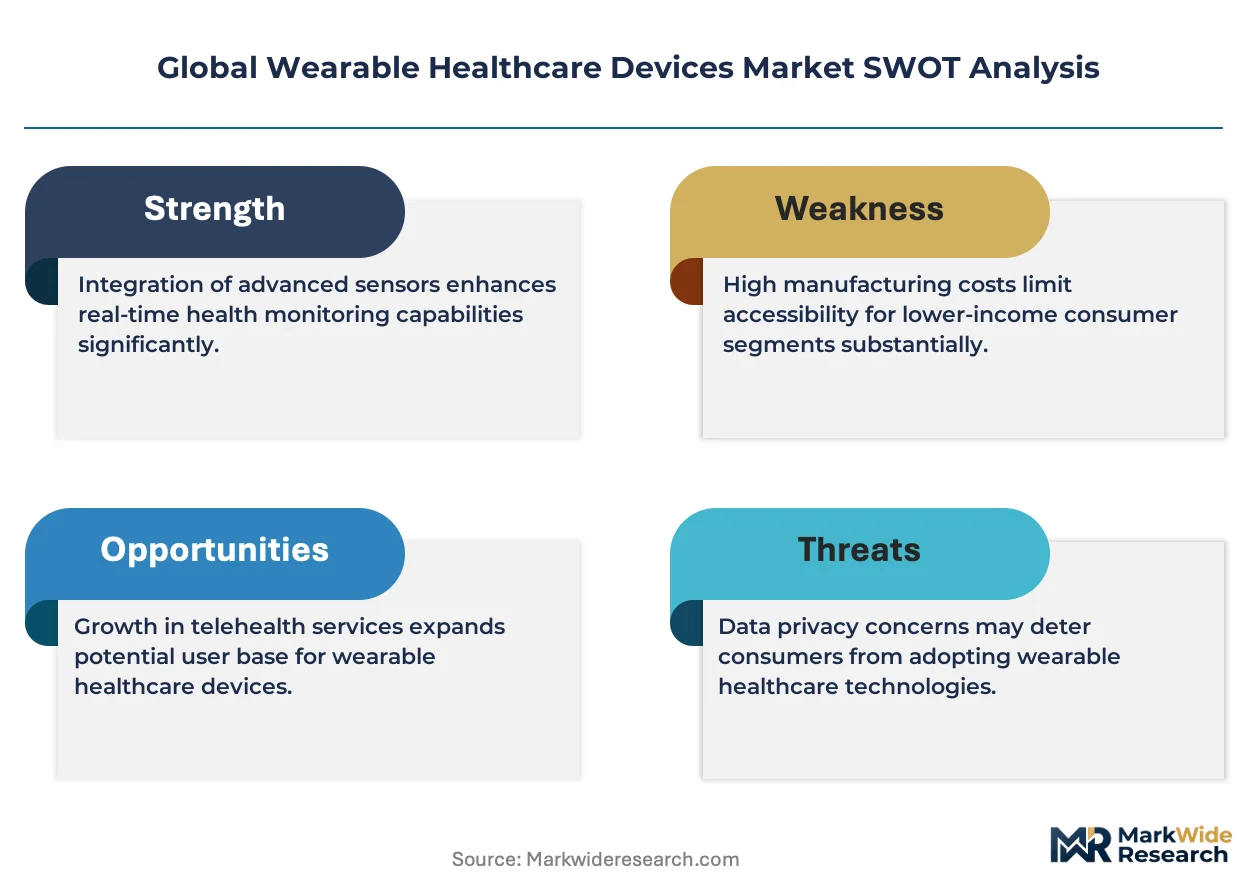
FDA, EMA, and NMPA each enforce distinct clinical evidence requirements for Class II medical wearables, fragmenting go-to-market strategies and inflating regulatory affairs headcount for multi-territory launches. HIPAA in the United States and GDPR in Europe impose parallel data governance obligations that shape cloud architecture choices and vendor qualification criteria. Stakeholders must monitor evolving software-as-medical-device precedents to calibrate R&D allocation between wellness-adjacent consumer features and clinically validated diagnostic outputs.
Market Dynamics
FDA software-as-medical-device precedents are compressing product development timelines while fragmenting go-to-market strategies across multiple jurisdictions. Hospital systems seeking remote patient monitoring alternatives pull demand toward chronic disease management applications with established reimbursement codes.
Growth Catalysts
- Remote Patient Monitoring Reimbursement:CMS reimbursement codes in the United States validate continuous glucose monitoring and cardiac event detection as billable services. Hospital-at-home programs accelerate procurement cycles for multi-parameter wearables.
- NMPA Digital Health Pathways:China's streamlined Class II medical device approvals for AI-enabled diagnostics reduce time-to-market for algorithm-driven wearables. Domestic manufacturers capture preferential procurement in public hospital tenders.
- Photoplethysmography Miniaturization:Optical sensor module costs declined sufficiently to enable SpO2 and blood pressure estimation in sub-$50 consumer hardware. Fitness tracker OEMs upgrade specifications without price erosion.
Market Restraints
- Lithium-Polymer Supply Concentration:Battery cell production clusters in China and South Korea expose wearable OEMs to freight volatility and export licensing delays. Alternative chemistries lack energy density parity for multi-day continuous monitoring.
- GDPR Data Localization:European cloud infrastructure mandates inflate operational expenditure for US-based platform vendors. Cross-border health data flows require redundant regional data centers.
- Clinical Validation Burden:EMA demands prospective trials for novel biomarker claims, extending development timelines by 18-24 months against wellness-adjacent competitors. Smaller entrants lack capital reserves for parallel regulatory submissions.
Strategic Opportunities
- Germany DiGA Fast-Track:Digital Health Applications reimbursement creates a precedent pathway for prescription-grade wearables. BfArM approvals enable statutory health insurance coverage within 12 months of submission.
- Continuous Blood Pressure Monitoring:Cuffless optical estimation algorithms address the hypertension management gap in ambulatory settings. Cardiology practices seek alternatives to 24-hour Holter monitoring for longitudinal data capture.
- Direct-to-Employer Distribution:Self-insured corporations in the United States procure bulk wearable deployments for metabolic syndrome prevention. Wellness program budgets bypass traditional hospital procurement committees.
Industry Challenges
- Firmware Validation Talent Scarcity:IEC 62304 medical device software lifecycle expertise commands premium compensation. Startups compete with established diagnostics firms for embedded systems engineers with FDA submission experience.
- Multi-Terrorial Quality Management:ISO 13485 certification gaps between notified bodies delay EU MDR conformity assessments. Simultaneous FDA 510(k) and NMPA filings strain regulatory affairs headcount.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wearable Healthcare Devices Market |
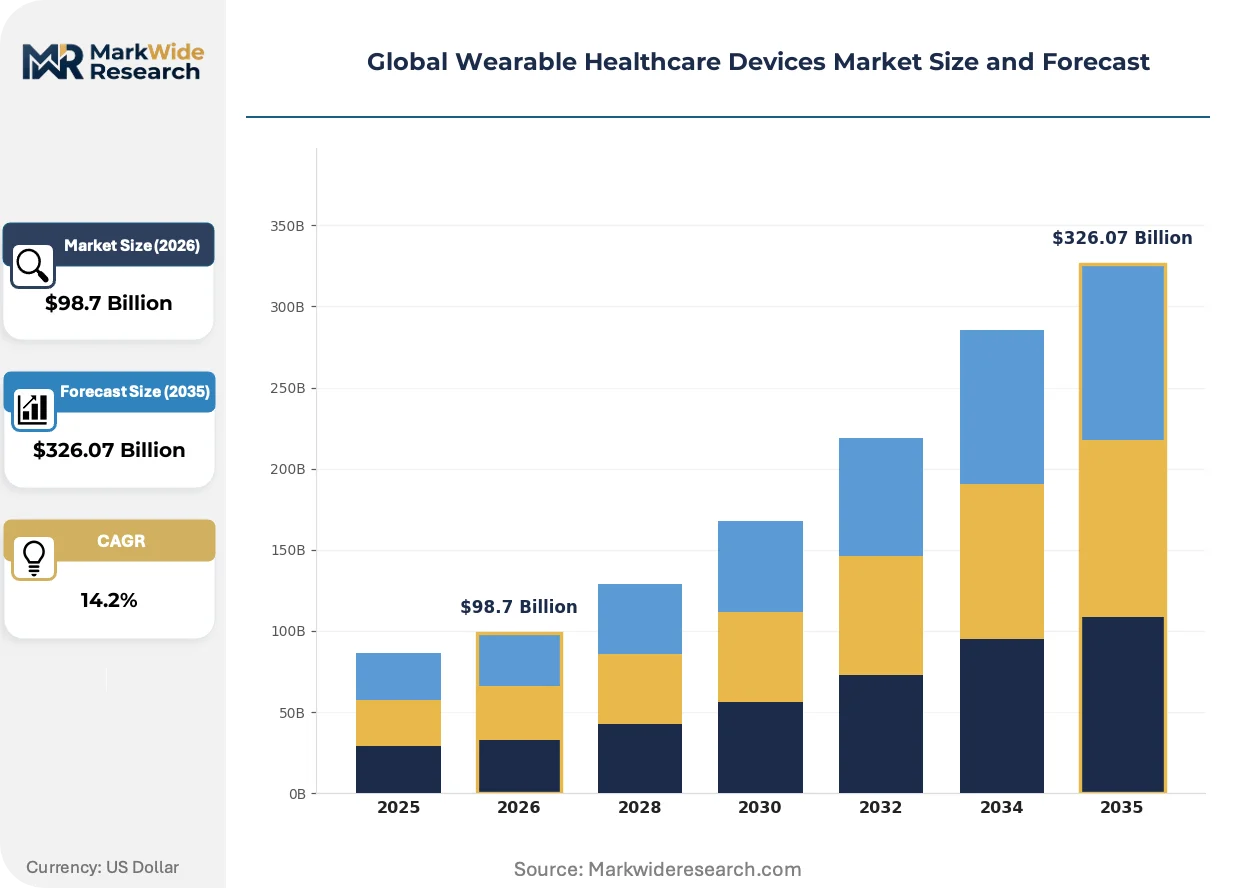
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $326.07 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Health Monitors, Sleep Monitors Application: Chronic Disease Management, Fitness Tracking, Elderly Care, Sleep Analysis End User: Individuals, Healthcare Providers, Enterprises, Insurance Companies Technology: Bluetooth, Wi-Fi, NFC, Cloud Computing |
| Companies Covered | Apple Inc., Samsung Electronics Co., Ltd., Abbott Laboratories, Dexcom, Inc., Fitbit Inc., Garmin Ltd., Koninklijke Philips N.V., Medtronic, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wearable Healthcare Devices Market Strategic Shifts
Sensor fusion architectures and algorithmic biomarker discovery are collapsing the distinction between consumer wellness hardware and clinical-grade diagnostics. Platform vendors race to secure regulatory clearances that validate algorithm outputs for physician decision-making.
Multi-wavelength photoplethysmography is integrating with accelerometer-derived motion compensation to enable continuous blood pressure estimation without cuff calibration. Cardiology departments in Germany and the United States pilot these systems for post-discharge hypertension management. The technology is integrating ambulatory monitoring into primary care workflows previously served by episodic office measurements.
EMA's MDR transition tightened clinical evidence requirements for Class IIa wearable devices, forcing retrospective data collection from real-world performance studies. Manufacturers with legacy CE marks under the Medical Devices Directive face certificate expiration cliffs through 2027. Diabetes management applications bear the heaviest documentation burden given the volume of predicate devices requiring technical file updates.
Hospital procurement committees now demand interoperability with existing electronic health record systems before contract approval. Epic and Cerner integration capabilities determine vendor shortlists for remote patient monitoring programs in the United States. This certification-driven preference shift disadvantages point-solution startups lacking health information exchange infrastructure investment.
Global Wearable Healthcare Devices Market Segmentation
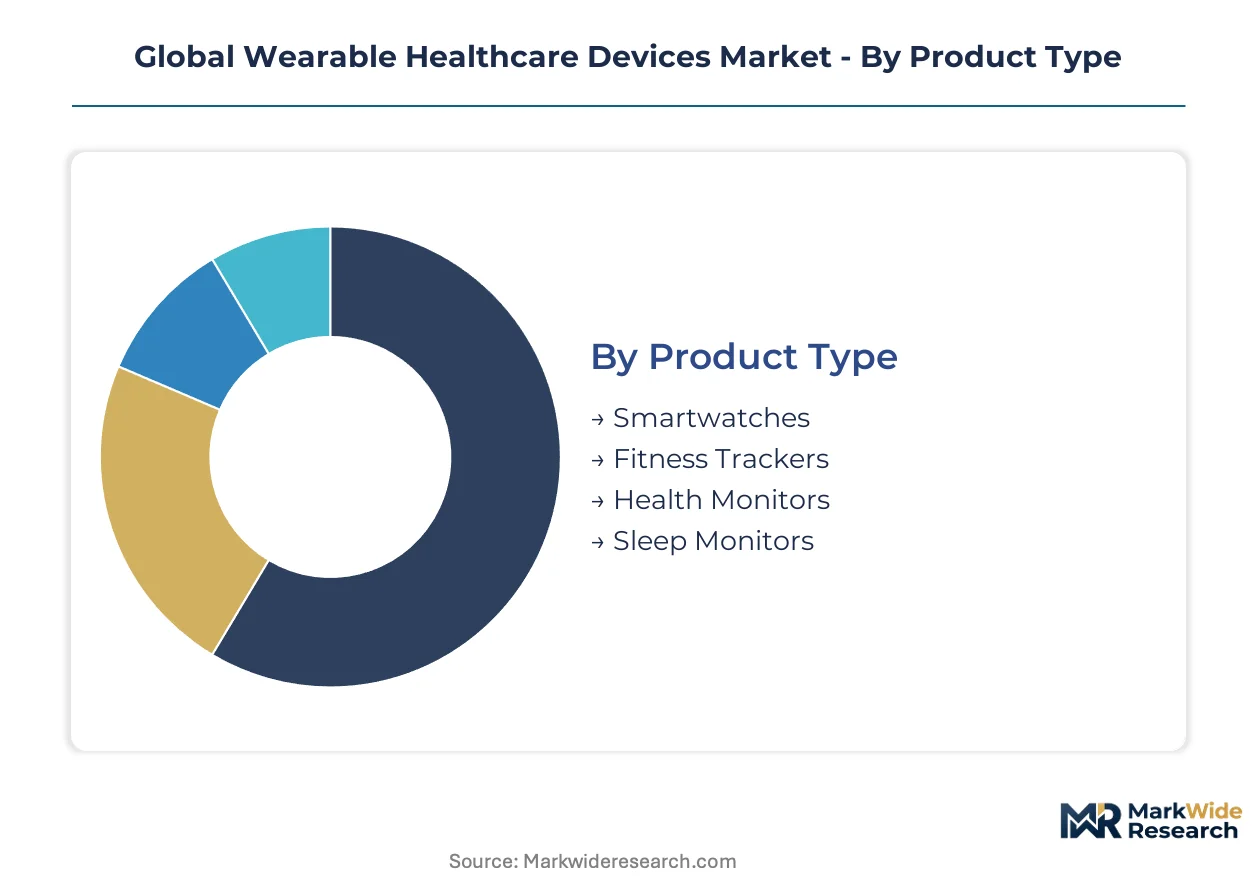
Segmentation in wearable healthcare devices reveals divergent commercial models. Hardware form factors determine margin structures while application use cases dictate reimbursement eligibility and regulatory pathways.
Product Type:
Integration depth varies sharply across form factors, with some segments functioning as standalone diagnostic instruments and others as embedded modules within broader consumer electronics ecosystems.
- Smartwatches:Multi-sensor platforms combining photoplethysmography, accelerometry, and ECG electrodes in wrist-worn enclosures. Hospital-at-home programs in the United States drive procurement for FDA-cleared cardiac monitoring variants, though most volume ships through consumer retail channels without clinical validation.
- Health Monitors:Dedicated single-purpose devices such as continuous glucose monitors and pulse oximeters with specialized biosensor arrays. Chronic disease management applications in Germany and the United States command premium pricing through established reimbursement codes.
- Fitness Trackers:Basic accelerometer-based activity quantification with emerging SpO2 add-ons. Enterprise wellness programs in China procure bulk deployments for metabolic syndrome prevention initiatives.
- Sleep Monitors:Contactless radar or under-mattress pressure sensors tracking sleep architecture without wearable encumbrance. Direct-to-consumer channels dominate, with limited clinical integration due to absence of diagnostic-grade validation.
Smartwatches lead volumes today; health monitors are gaining share fastest through chronic disease reimbursement expansion.
Application:
Cost tier stratification separates clinically billable services from wellness-adjacent consumer offerings, with reimbursement status determining R&D allocation and go-to-market investment intensity.
- Chronic Disease Management:Continuous physiological monitoring for diabetes, hypertension, and cardiac arrhythmias with physician-directed interpretation. CMS reimbursement codes in the United States validate continuous glucose monitoring and cardiac event detection as billable remote patient monitoring services.
- Fitness Tracking:Activity quantification and basic biometric feedback without clinical decision support integration. Margin compression accelerates as sensor commoditization enables sub-$50 hardware with previously premium features.
- Sleep Analysis:Circadian rhythm assessment and sleep disorder screening, predominantly consumer-funded. BfArM in Germany has begun evaluating prescription-grade sleep monitoring applications for DiGA fast-track eligibility.
- Elderly Care:Fall detection, medication adherence, and emergency response systems for aging-in-place populations. Japan's METI has prioritized wearable integration into municipal long-term care insurance programs.
Chronic disease management commands the highest revenue per unit; fitness tracking remains the volume anchor.
End User:
Customer type determines procurement cycle length, technical specification requirements, and data governance obligations, with institutional buyers demanding interoperability certifications absent from consumer transactions.
- Healthcare Providers:Hospital systems and physician practices procuring FDA-cleared or CE-marked devices for clinical decision support. Epic and Cerner integration capabilities determine vendor shortlists for remote patient monitoring programs in the United States.
- Insurance Companies:Risk-bearing entities deploying wearables for policyholder engagement and claims cost reduction. Self-insured corporations in the United States procure bulk deployments bypassing traditional hospital procurement committees.
- Individuals:Direct-to-consumer purchasers motivated by wellness optimization and preventive health awareness. Retail channel dynamics favor ecosystem lock-in through smartphone platform integration.
- Enterprises:Employer-sponsored wellness programs and occupational health departments. Procurement emphasizes aggregate population analytics over individual diagnostic precision.
Healthcare providers dominate premium-tier procurement; insurance companies are expanding fastest through value-based care contracts.
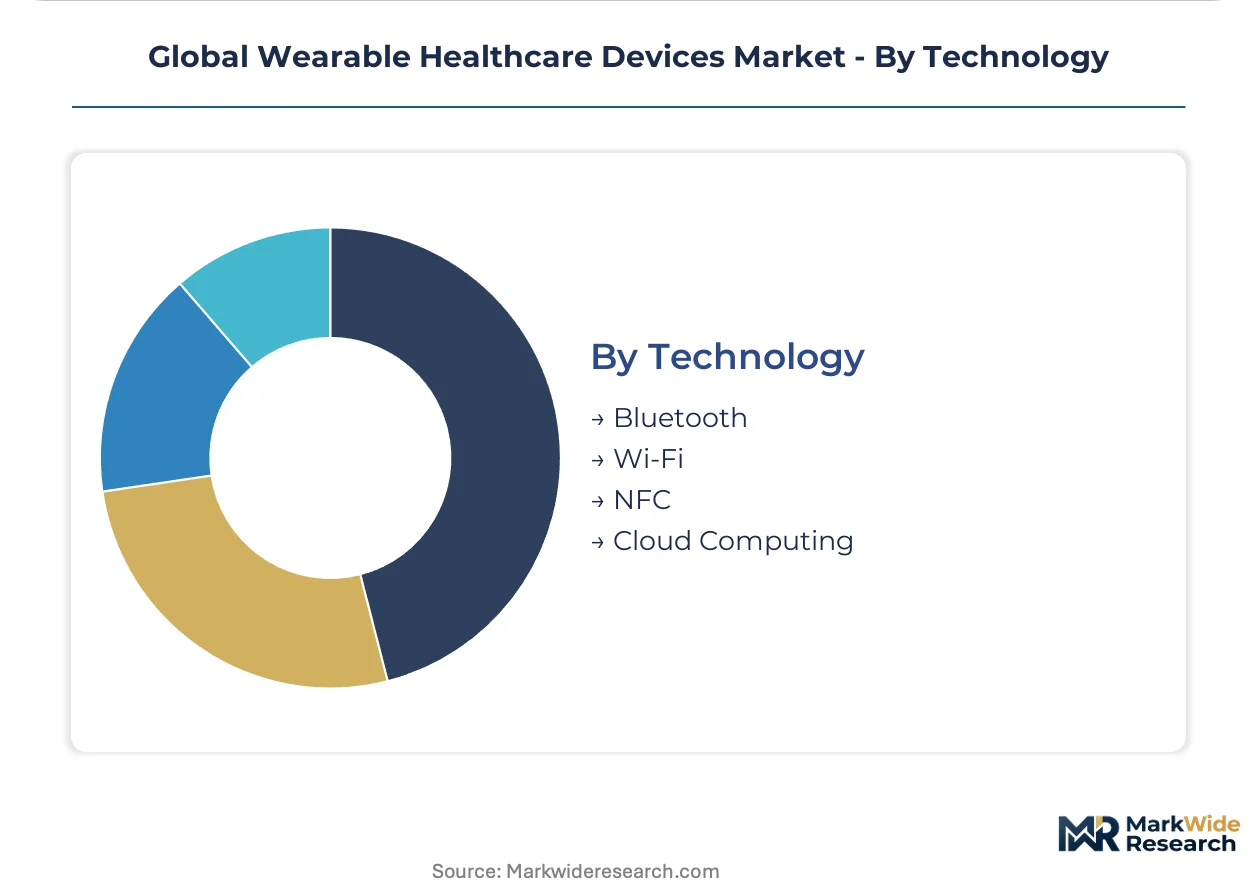
Technology:
Supply concentration in wireless connectivity modules and cloud infrastructure shapes vendor qualification criteria and operational expenditure structures across deployment scales.
- Bluetooth:Low-energy protocol dominating short-range wearable-to-smartphone transmission. Module cost declines have enabled sub-$25 fitness tracker BOM structures.
- Cloud Computing:Scalable data aggregation and algorithmic processing infrastructure. GDPR data localization mandates in Europe inflate operational expenditure for US-based platform vendors requiring redundant regional data centers.
- Wi-Fi:Direct-to-infrastructure connectivity for stationary health monitors and bedside devices. Hospital IT security policies increasingly restrict Wi-Fi wearable deployments due to network segmentation complexity.
- NFC:Contactless pairing and payment integration, primarily in smartwatch segments. Limited clinical application due to range constraints and security certification burdens.
Bluetooth anchors shipment volumes; cloud computing investment scales fastest with platform vendor consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biomedical engineering talent clusters in Boston, Basel, and Shenzhen anchor wearable device development across three continents. Regulatory science expertise concentrates in FDA-experienced hubs and EMA-notified body proximity zones. Manufacturing scale advantages follow lithium-polymer battery supply corridors.
United States
Hospital-at-home program expansion drives procurement for multi-parameter cardiac monitors and continuous glucose systems. FDA 510(k) premarket notification volume growth rewards incumbents with established quality management systems. Greater Boston's biomedical corridor hosts algorithm development for software-as-medical-device clearances.
Germany
BfArM DiGA fast-track approvals enable statutory health insurance coverage for prescription-grade wearables within 12 months. EMA MDR transition tightens clinical evidence requirements for Class IIa devices through 2027. Baden-Württemberg's precision engineering cluster supplies optical sensor modules for blood pressure estimation devices.
China
NMPA streamlined Class II medical device approvals for AI-enabled diagnostics accelerate domestic manufacturer time-to-market. Municipal long-term care insurance programs in tier-1 cities pilot elderly fall detection deployments. Shenzhen's electronics manufacturing ecosystem integrates photoplethysmography modules into sub-$50 fitness tracker bill-of-materials.
Japan
METI prioritizes wearable integration into municipal long-term care insurance programs for aging-in-place populations. PMDA clinical trial requirements for novel biomarker claims extend development timelines against wellness-adjacent competitors. Kanto region's semiconductor packaging facilities supply low-energy Bluetooth modules for multi-day continuous monitoring devices.
Switzerland
Swissmedic's alignment with EMA procedures enables parallel EU-Swiss market access for CE-marked wearables. Basel's pharmaceutical diagnostics heritage anchors glucose monitoring algorithm development. Zurich's precision manufacturing base produces accelerometer-derived motion compensation systems for cuffless blood pressure estimation.
Global Wearable Healthcare Devices Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, algorithm, and platform layers. Market structure shows tiered consolidation with premium clinical-grade segments concentrating around established diagnostics firms and consumer tiers fragmenting among electronics OEMs. Three archetypes dominate: integrated ecosystem builders anchoring smartphone platform lock-in, medical device incumbents leveraging FDA clearance portfolios, and sensor module suppliers capturing value from optical component commoditization. Competitive moves center on health information exchange interoperability certifications and strategic partnerships with electronic health record vendors.
Among diversified technology conglomerates, Apple Inc. and Samsung Electronics Co., Ltd. exemplify ecosystem-first positioning that leverages smartphone install bases for health platform distribution. Abbott Laboratories and Dexcom, Inc. occupy the medical device specialist tier where regulatory clearance portfolios determine hospital procurement access. These four entities represent divergent strategic paths: consumer electronics scale versus clinical validation depth.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co., Ltd. |
| Abbott Laboratories |
| Dexcom, Inc. |
| Fitbit Inc. |
| Garmin Ltd. |
| Koninklijke Philips N.V. |
| Medtronic |
| GE HealthCare |
| Others |
Value Chain & Pricing Dynamics
Firmware validation engineers with IEC 62304 expertise concentrate in Greater Boston and Basel, commanding compensation premiums that widen spreads between FDA-cleared clinical tiers and wellness-adjacent consumer hardware. Labor-cost differentials between these regulatory-grade hubs and Shenzhen manufacturing centers directly map to three-tier pricing stratification across premium diagnostic, standard health monitor, and economy fitness tracker segments.
Pricing Analysis
Bundled subscription services for continuous glucose monitoring separate from unbundled per-unit hardware transactions for fitness trackers. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance status and algorithmic biomarker validation depth. Cost compression in the fitness tracker segment intensifies as photoplethysmography module commoditization enables sub-$50 bill-of-materials. Enterprise wellness programs exhibit lowest price sensitivity; direct-to-consumer purchasers drive hardest bargain negotiations.
Supply Chain Analysis
Freight volatility from Asia-Pacific battery cell corridors exposes wearable OEMs to margin erosion during ocean shipping rate spikes. Lithium-polymer cell production clusters in China and South Korea; optical sensor modules source predominantly from Taiwan and Japan. Single-source vulnerability concentrates in advanced photoplethysmography chipsets. Distribution runs through hospital procurement committees for clinical-grade devices and consumer electronics retail for wellness hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA software-as-medical-device precedents compound market demand by compressing product development timelines while elevating compliance investment thresholds. This regulatory milestone rewards incumbents with established quality management systems and quality-accredited regulatory affairs headcount.
For Market Incumbents: Lock in hospital system procurement relationships through Epic and Cerner interoperability certifications before certificate expiration cliffs force predicate device updates. Deepen backward integration into optical sensor module production to defend margin position against commoditization pressure from Shenzhen ecosystem competitors.
For New Entrants and Emerging Players: Launch via direct-to-employer distribution channels that bypass traditional hospital procurement committee gatekeeping. Germany's DiGA fast-track pathway represents the most penetrable regulatory entry point for prescription-grade wearable reimbursement. Target self-insured corporations in the United States with metabolic syndrome prevention program pitches.
For Investors and Strategic Acquirers: Valuations sit cheapest among sensor module suppliers lacking algorithm development capabilities and platform integration expertise. Long-term viability over the next decade hinges on regulatory clearance portfolio depth rather than consumer brand recognition. Watch FDA 510(k) premarket notification volume acceleration as inflection indicator for sector consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway | Software-as-medical-device clearances compress competitive timelines against wellness-adjacent hardware. |
| Hospital System Partnership | Epic and Cerner integration certifications determine vendor shortlists for remote patient monitoring programs. |
| Reimbursement Strategy | CMS code validation for continuous glucose monitoring anchors premium pricing in chronic disease management. |
| CE Marking Pathway | EMA MDR transition tightens clinical evidence requirements through certificate expiration cliffs. |
| Software Companion Development | Algorithmic biomarker discovery collapses distinction between consumer wellness and clinical-grade diagnostics. |
Study Parameters
Multiple input streams — hospital procurement database analysis, GPO contract reviews, CMS reimbursement code tracking, and regulatory filing monitoring — were reconciled against primary interviews with biomedical engineers, hospital purchasing committee members, regulatory affairs leads, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, EMA MDR submission records, BfArM DiGA approval registers, and NMPA Class II medical device clearance filings. Bottom-up shipment estimates and top-down reimbursement value analysis were triangulated to anchor segmentation outputs.
Cross-referencing historical regulatory clearance velocity against expert panel input shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hardware form factor, application use case with reimbursement eligibility, end-user procurement archetype, and connectivity technology. CAGRs were derived from reconciling unit shipment trajectories with average selling price evolution by tier. Industry-specific forecast inputs incorporated photoplethysmography miniaturization cost curves and cloud infrastructure expenditure scaling under GDPR data localization mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium-polymer supply disruption scenarios or accelerated EMA MDR enforcement actions. Forecasts reflect documented assumptions about regulatory pathway efficiency and reimbursement code expansion velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Europe Sternal Closure Systems Market
Medical Devices
Medical Radiation Detectors Market
Medical Devices
Global Biliary Stents Market
Medical Devices
US Surgical Microscopes Market
Medical Devices
Saudi Arabia Minimally Invasive Surgery Devices Market
Medical Devices
Skincare Devices Market
Medical Devices
Interventional Cardiology Devices Market
Medical Devices
Echogenic Catheters Market
Medical Devices
Penile Implants Market
Medical Devices
North America and Europe Group 2 Powered Mobility Devices Market
Medical Devices
Pectus Bar System Market
Medical Devices
Global Body Composition Analyzers Market
Medical Devices
Global Electrotherapy Devices Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Global Angiography Devices Market