
 Global Auto-Injectors Market | 2026-2036
Global Auto-Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Auto-Injectors Market Analysis
Glass-to-cyclic olefin polymer substitution is recalibrating cost structures and break-resistance profiles across disposable auto-injector portfolios. Becton Dickinson and Company leverages captive polymer supply chains to anchor North American manufacturing scale. Eli Lilly and Company differentiates through biologic-specific device co-development programs with integrated digital connectivity. Ypsomed sustains European leadership via precision molding expertise and regulatory dossier depth.
An auto-injector is a spring-loaded or gas-powered medical device designed to deliver a pre-measured drug dose intramuscularly or subcutaneously, typically incorporating needle-safety shields and dose-completion indicators. These devices eliminate manual syringe handling, reduce administration error rates, and enable non-clinical users to self-medicate during anaphylaxis, insulin deficiency, or autoimmune flare episodes. Pre-filled disposable auto-injectors command the largest revenue pool due to sterility assurance and pharmacy dispensing convenience. Smart injectors with electronic dose logging represent the fastest-expanding technology segment as payers condition reimbursement on adherence documentation. Home care dominates end-user volume, though emergency services applications carry premium pricing for ruggedized construction and temperature stability.
FDA combination product regulations, EU MDR device classification requirements, and ISO 11608-5 needle-based injection system standards collectively govern design validation, human factors testing, and post-market surveillance obligations. These frameworks elevate capital requirements for market entry while creating compliance-based differentiation among established manufacturers. Stakeholders must monitor evolving pharmacovigilance linkages between device performance and drug efficacy as regulators tighten accountability for integrated delivery systems.
Market Dynamics
The convergence of chronic disease prevalence and regulatory pressure on combination product safety is compressing development timelines while elevating validation requirements across auto-injector portfolios. Manufacturers must now synchronize drug-device development cycles with evolving FDA, EMA, and PMDA expectations for human factors engineering and post-market surveillance.
Growth Catalysts
- EU MDR device classification requirements:Stricter conformity assessment pathways for Class III combination products are accelerating investment in validated manufacturing infrastructure across European contract development organizations.
- Home care settings:Patient self-administration protocols for biologics are expanding addressable volume beyond clinical environments into pharmacy-dispensed channels.
- ISO 11608-5 needle-based injection standards:Harmonized international testing protocols are reducing regulatory duplication costs for multi-jurisdiction product registrations.
Market Restraints
- Glass barrel supply concentration:Borosilicate glass sourcing depends on a limited supplier base in Germany and Switzerland, exposing device makers to input cost volatility and qualification delays.
- Spring mechanism precision requirements:Tolerance thresholds below 0.1 millimeters for consistent dose delivery constrain viable contract manufacturer pools.
- Biologic viscosity limitations:High-concentration monoclonal antibody formulations exceed current spring-powered delivery mechanics, restricting addressable therapeutic categories.
Strategic Opportunities
- India's CDSCO streamlined medical device pathways:Recent regulatory harmonization initiatives are opening local manufacturing and registration channels for export-oriented production.
- Connected adherence platforms:Integration of Bluetooth-enabled dose logging with electronic health record systems creates reimbursement differentiation for payers demanding outcomes documentation.
- Emergency services ruggedization:Temperature-stable, shock-resistant construction specifications for ambulance and field deployment command premium pricing relative to standard home-use devices.
Industry Challenges
- Human factors engineering talent scarcity:Qualified usability testing professionals with combination product experience command compensation premiums that strain mid-tier development budgets.
- Validation batch capex intensity:Sterility assurance and process performance qualification requirements for pre-filled syringe assembly demand eight-figure capital commitments per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Auto-Injectors Market |
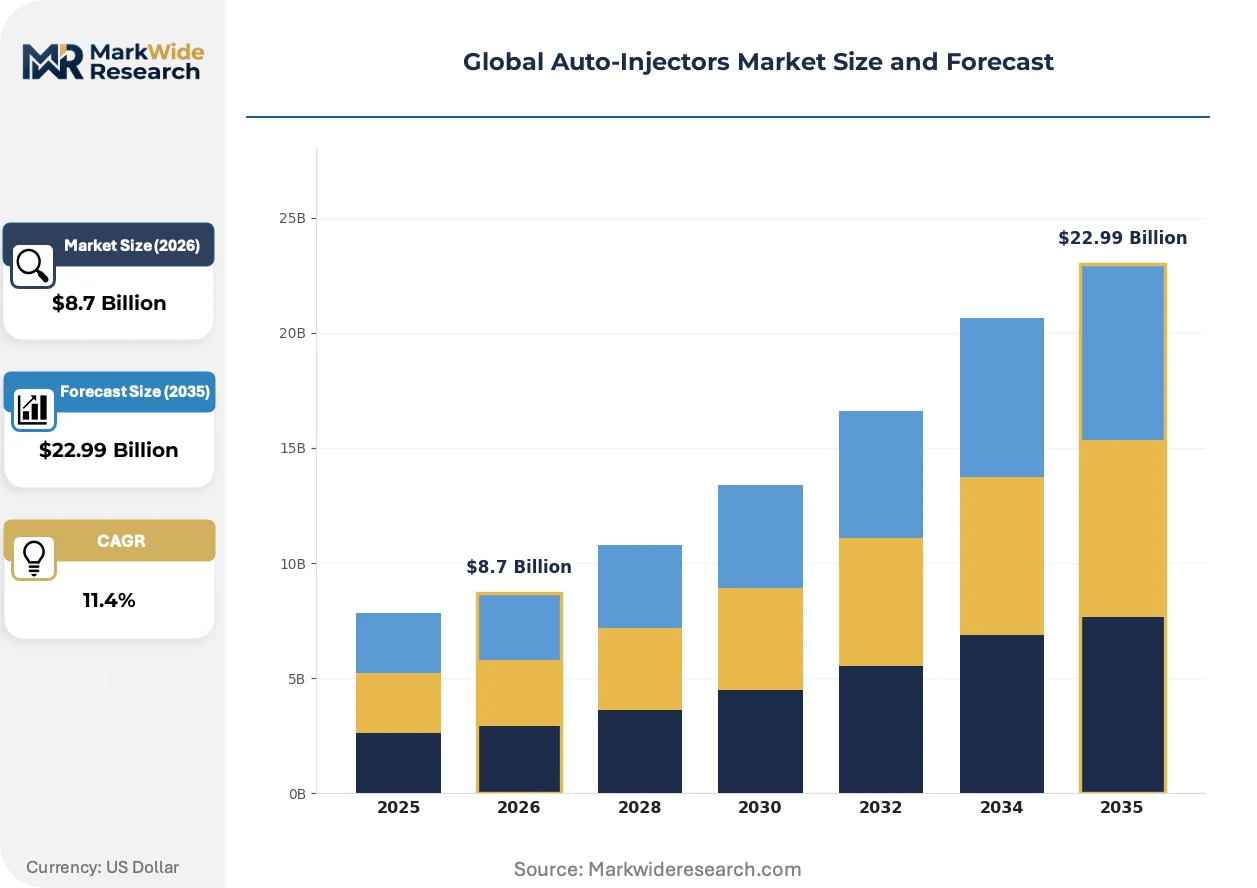
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-Filled, Disposable, Reusable, Smart Injectors End User: Hospitals, Clinics, Home Care, Emergency Services Technology: Mechanical, Electronic, Hybrid, Digital Therapy Area: Allergy, Diabetes, Autoimmune Disorders, Oncology |
| Companies Covered | Becton Dickinson and Company, SHL Medical AG, Ypsomed, AbbVie, Amgen, Eli Lilly and Company, Teva Pharmaceutical Industries, Novo Nordisk, Owen Mumford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Auto-Injectors Market Emerging Trajectories
Digital connectivity and materials science are converging to redefine device differentiation beyond mechanical reliability toward data-enabled therapeutic management. The competitive frontier is shifting from injection mechanics to ecosystem integration.
Smart auto-injectors with embedded sensors and wireless transmission modules are electrifying competitive positioning across the premium device segment. Rheumatology and endocrinology practices in the United States are piloting these systems for remote patient monitoring. The technology is compressing differentiation timelines as connectivity becomes table stakes for biologic co-development partnerships.
FDA's evolving guidance on human factors validation for combination products is tightening documentation requirements for design history files and summative usability studies. Device manufacturers must now conduct testing with representative patient populations across age and dexterity spectrums. Pediatric and geriatric indication expansions face elongated review cycles as a result.
Hospital and clinic procurement departments are consolidating supplier relationships around full-service device-drug integration partners. Large health systems in Germany and Japan are reducing vendor counts in favor of single-source contracts covering formulation, device, and adherence platform components. This concentration is squeezing standalone mechanical device suppliers without digital or pharmaceutical alliances.
Global Auto-Injectors Market Segmentation
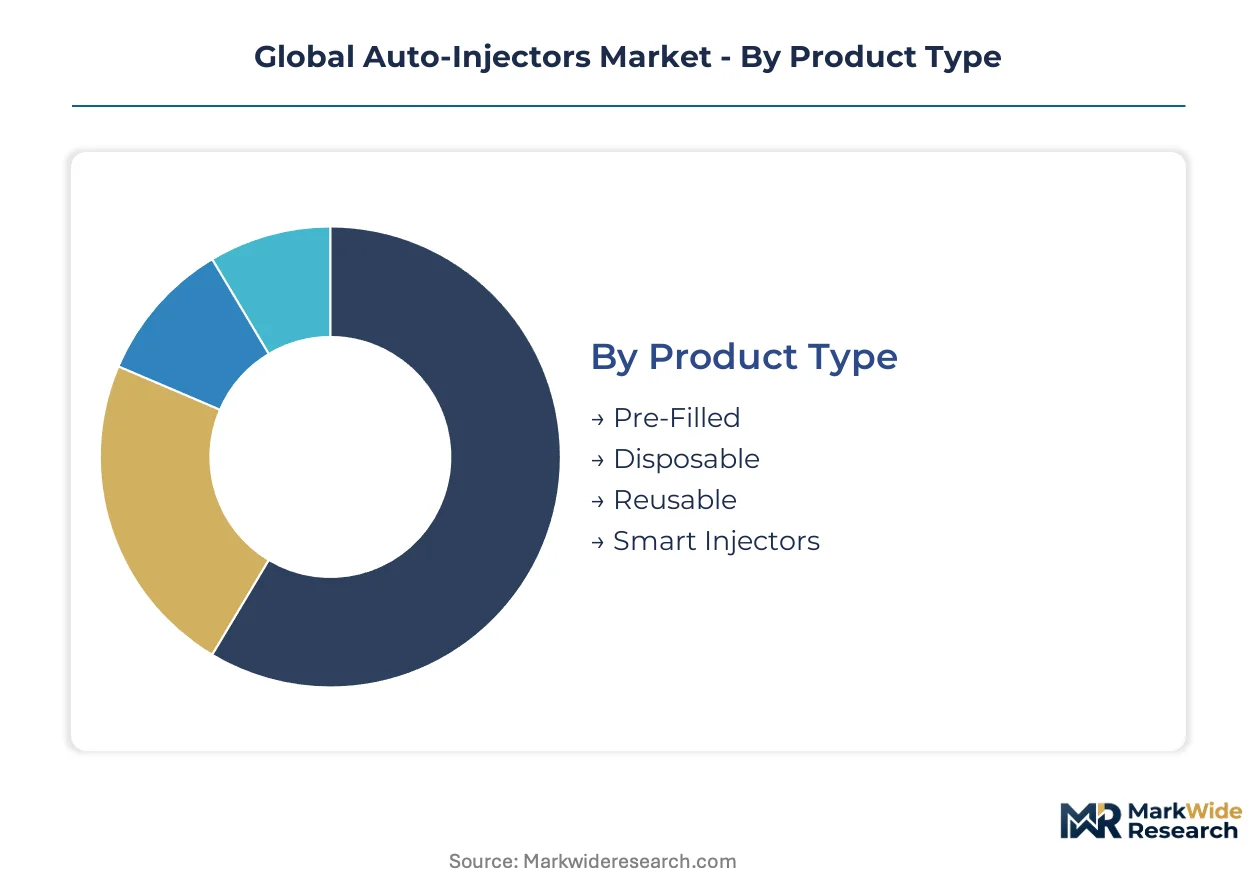
Auto-injector segmentation reveals divergent regulatory pathways and capital intensity profiles across product architectures. Device manufacturers calibrate portfolio investments against certification timelines, reimbursement codes, and manufacturing scale thresholds that vary sharply by segment.
Product Type:
FDA combination product classification and EU MDR Class III conformity assessment obligations concentrate disproportionately on pre-filled and disposable formats, while reusable and smart platforms navigate modular device-only pathways.
- Pre-Filled:Factory-sterilized syringe-barrel integration eliminates compounding pharmacy handling. United States rheumatology practices drive volume through biologic co-development partnerships requiring validated cold-chain integrity from fill-finish through patient administration.
- Disposable:Single-use construction with integrated needle-safety shields dominates pharmacy dispensing economics. German hospital procurement consortia favor this format for anaphylaxis emergency stockpiles due to sterility assurance and minimal training burden.
- Reusable:Cartridge-based systems with replaceable drug containers reduce per-dose material costs for high-frequency insulin administration.
- Smart Injectors:Bluetooth-enabled dose logging and adherence tracking embedded in electronic housing modules.
Leading the category by volume: Pre-Filled. Growing fastest: Smart Injectors.
End User:
Cost-to-serve economics and reimbursement tiering separate institutional purchasers from direct-to-patient channels, with emergency services commanding premium pricing for ruggedized specifications.
- Home Care:Self-administration protocols for biologics expand pharmacy-dispensed volume beyond clinical supervision. Japanese health ministry reimbursement codes for home-use auto-injectors now cover connectivity-enabled adherence monitoring.
- Emergency Services:Temperature-stable, shock-resistant construction for ambulance and field deployment withstands operational stress beyond standard home-use specifications.
- Hospitals:Central pharmacy-controlled distribution with formulary restrictions on device-drug pairings.
- Clinics:Outpatient administration with nurse-supervised injection training programs.
Home Care generates the largest absolute volume. Emergency Services captures the highest per-unit margin.
Technology:
Intellectual property density and development timeline risk escalate from mechanical spring systems through fully electronic platforms, with hybrid architectures splitting validation obligations across mechanical and software quality systems.
- Mechanical:Spring-loaded delivery with passive needle retraction relies on precision metal stamping and polymer molding expertise concentrated in Swiss and German component suppliers.
- Electronic:Motor-driven piston control with programmable dose settings enables high-viscosity biologic delivery beyond spring-powered limits. FDA software-as-medical-device guidance extends validation timelines for these platforms.
- Hybrid:Spring primary actuation with electronic dose-completion sensing and logging.
- Digital:Smartphone-integrated adherence platforms with cloud-based data transmission.
Mechanical platforms retain manufacturing scale leadership. Electronic systems are climbing the fastest on biologic viscosity expansion.
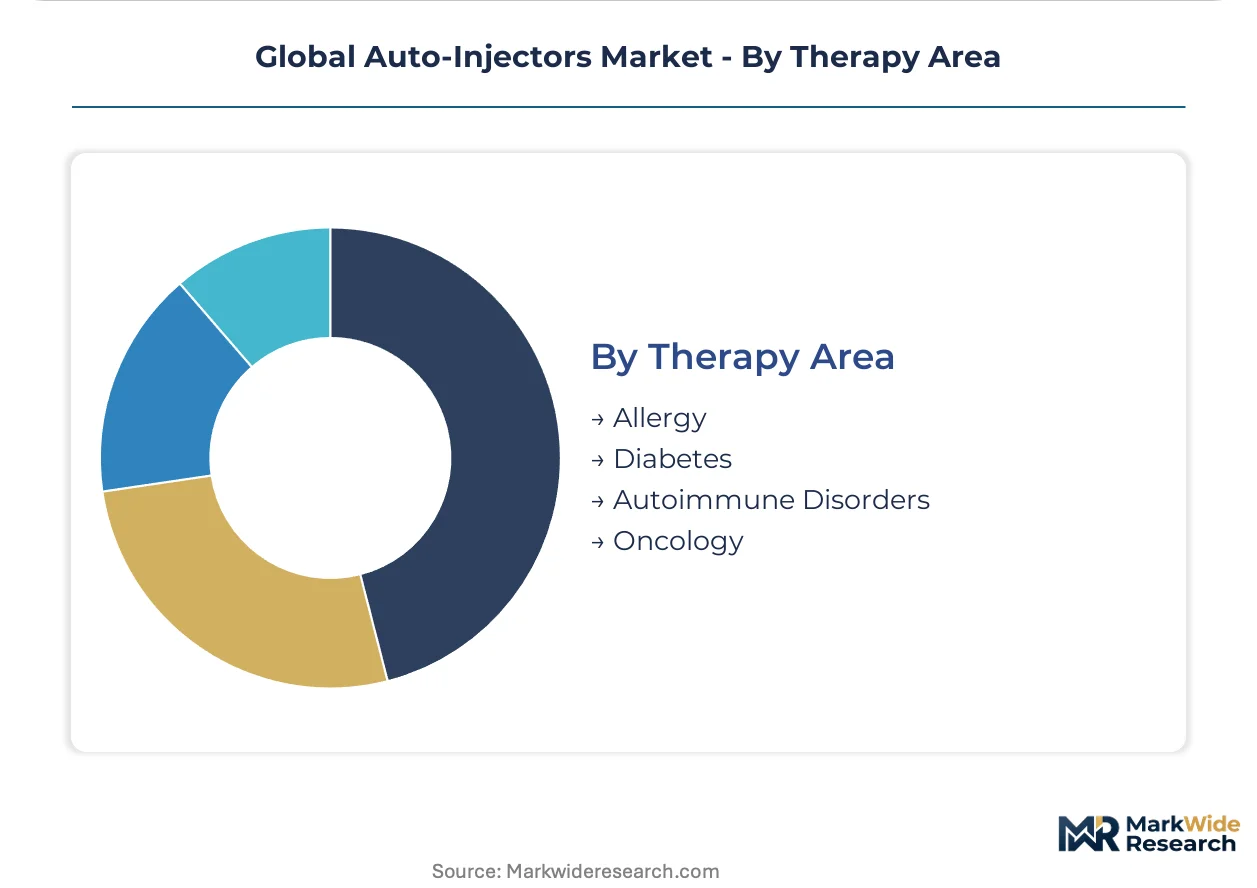
Therapy Area:
Patient population size, injection frequency, and reimbursement durability create divergent addressable value pools across therapeutic applications, with oncology presenting the most complex device-drug co-development requirements.
- Diabetes:High-frequency insulin administration supports reusable device economics and connectivity subscription models. United States endocrinology practices pilot remote glucose-insulin dose optimization through integrated auto-injector and continuous glucose monitor data streams.
- Autoimmune Disorders:Rheumatology and gastroenterology biologics require subcutaneous formulation conversion from intravenous infusion. PMDA accelerated approval pathways in Japan compress development timelines for device-drug combinations in this category.
- Allergy:Epinephrine delivery for anaphylaxis with standardized dose volumes and minimal training requirements.
- Oncology:Cytotoxic agent handling protocols and healthcare professional administration constraints limit self-injection penetration.
Diabetes commands the largest installed device base. Autoimmune Disorders is expanding most quickly on biologic pipeline conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States reimbursement frameworks and Japanese chronic disease management programs concentrate demand for self-administration devices, while German manufacturing clusters and Swiss precision component suppliers anchor supply-side capacity.
United States
Endocrinology practices and rheumatology clinics drive volume through biologic co-development partnerships requiring validated cold-chain integrity. FDA combination product regulations tighten human factors documentation requirements for design history files. Boston and San Francisco medical device clusters host specialized usability testing facilities serving combination product developers.
Germany
Hospital procurement consortia favor disposable formats for emergency stockpiles due to sterility assurance and minimal training burden. EU MDR Class III conformity assessment obligations accelerate investment in validated manufacturing infrastructure. Stuttgart and Munich precision molding clusters supply polymer components to North American device assemblers.
Japan
Health ministry reimbursement codes for home-use auto-injectors now cover connectivity-enabled adherence monitoring. PMDA accelerated approval pathways compress development timelines for device-drug combinations in autoimmune categories. Osaka and Tokyo pharmaceutical corridors concentrate biologic formulation expertise alongside device integration capabilities.
Switzerland
Swissmedic oversight of combination products aligns with EU MDR requirements while maintaining distinct pharmacovigilance linkages. Precision metal stamping and polymer molding expertise concentrates in component suppliers serving global device manufacturers. Basel and Zurich host regulatory dossier specialists supporting multi-jurisdiction registrations.
India
Domestic biologic manufacturing expansion creates localized demand for pre-filled syringe assembly capacity. CDSCO streamlined medical device pathways open local manufacturing and registration channels for export-oriented production. Hyderabad and Bengaluru pharmaceutical clusters develop contract manufacturing capabilities for combination product assembly.
Global Auto-Injectors Market Vendor Landscape
Strategic partnerships dominate the current landscape as pharmaceutical manufacturers seek integrated device-drug development capabilities. The vendor base stratifies across three tiers: diversified medical technology conglomerates with captive polymer supply chains, specialized precision molding firms with regulatory dossier depth, and biologic developers with in-house device co-development programs. Two strategic archetypes define positioning: full-service integration partners capturing health system consolidation contracts, and component specialists supplying validated sub-assemblies. M&A activity and capacity expansion represent the dominant competitive moves, with manufacturers acquiring human factors engineering talent and sterilization infrastructure.
Among diversified medical technology conglomerates, Becton Dickinson and Company exemplifies the integration archetype through captive supply chain control. SHL Medical AG and Ypsomed occupy positions within the precision manufacturing tier, with the former representing Swiss component supply capabilities and the latter anchoring European regulatory expertise. Eli Lilly and Company sits within the pharmaceutical-led integration segment, embodying biologic-specific device co-development models with digital connectivity requirements.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| SHL Medical AG |
| Ypsomed |
| AbbVie |
| Amgen |
| Eli Lilly and Company |
| Teva Pharmaceutical Industries |
| Novo Nordisk |
| Owen Mumford |
| Others |
Supply Flow & Price Mechanics
Captive polymer supply chains anchored by Becton Dickinson and Company reshape competitive economics across disposable auto-injector portfolios. This backward integration into cyclic olefin polymer production insulates North American manufacturers from borosilicate glass cost volatility while compressing margins for non-integrated assemblers competing on standard mechanical platforms.
Pricing Analysis
High-volume disposable formats trade at compressed per-unit economics while emergency services ruggedization commands substantial premiums for temperature-stable, shock-resistant construction. Pricing stratifies across premium smart-injector tiers with Bluetooth-enabled adherence logging, standard pre-filled disposables for pharmacy dispensing, and economy reusable cartridge systems for insulin administration. Price differentiation hinges on FDA combination product certification tier and integrated digital connectivity depth. Cost compression in standard mechanical segments is intensifying as German hospital procurement consortia consolidate supplier relationships around single-source contracts. Home care patients exhibit highest price sensitivity, while emergency medical services demonstrate lowest elasticity due to operational reliability requirements.
Supply Chain Analysis
Dual-sourcing requirements for precision spring mechanisms and polymer barrel components mandate multi-supplier qualification across Swiss, German, and North American precision molding specialists. Component sourcing draws from Stuttgart and Munich polymer clusters, Swiss metal stamping corridors, and emerging Hyderabad assembly capacity. Borosilicate glass barrel dependence on limited German and Swiss suppliers creates single-source vulnerability for pre-filled syringe integration. Distribution runs through pharmacy-dispensed channels for home care volume and direct health system contracts for institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU MDR Class III conformity assessment obligations and eight-figure validation batch capital requirements is systematically eliminating mid-tier mechanical device suppliers without pharmaceutical partnerships or digital platform capabilities.
For Market Incumbents:Anchoring regulatory dossier depth through expanded Swissmedic and FDA combination product submission capabilities defends against emerging contract manufacturers from India. Incumbents should deepen backward integration into polymer supply chains to neutralize input cost volatility from borosilicate glass concentration. Priority investment in human factors engineering talent pools addresses scarcity premiums straining development budgets.
For New Entrants and Emerging Players:Electronic motor-driven delivery platforms for high-viscosity biologics represent the most penetrable technology wedge, as spring-powered mechanics face viscosity limitations excluding monoclonal antibody categories. CDSCO streamlined pathways in India offer registration channel expansion with lower capital intensity than EU MDR Class III conformity assessment. Go-to-market positioning should target biologic developers seeking device-drug co-development partnerships without captive manufacturing infrastructure.
For Investors and Strategic Acquirers:Exit pathways concentrate in acquisition by pharmaceutical manufacturers seeking integrated delivery system capabilities rather than standalone device IPOs. Long-term viability across the projection horizon favors precision molding specialists with validated sterile assembly infrastructure and regulatory dossier depth in multiple jurisdictions. Watch for PMDA accelerated approval pathway expansion in autoimmune categories as inflection indicator for Japanese market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Combination Product Submission | Human factors validation documentation accelerates biologic co-development partnership access with rheumatology practices. |
| CE Marking Pathway Investment | EU MDR Class III conformity assessment capability opens German hospital procurement consortium contracts. |
| Hospital System Partnership | Single-source integration contracts with large US health systems displace standalone mechanical device suppliers. |
| Software Companion Development | Bluetooth-enabled adherence logging meets payer reimbursement conditioning on outcomes documentation. |
| Reimbursement Strategy | Japanese health ministry connectivity coverage codes unlock premium pricing for home-use smart injectors. |
Methodological Framework
Document review covered FDA 510(k) and combination product filings, EMA centralized procedure submissions, and ISO 11608-5 testing protocols, complemented by interviews with regulatory affairs leads at device manufacturers, hospital procurement managers at German consortia, and GPO contracts managers at US health systems. Secondary validation drew from PMDA accelerated approval pathway documentation, CDSCO medical device registration databases, and Swissmedic combination product guidance. Bottom-up segment sizing triangulated against top-down pharmaceutical partnership announcement tracking.
Cross-referencing historical FDA review cycle patterns with expert panel input on EU MDR implementation timelines anchored the analytical framework across the analysis window. Segmentation modeling spanned product architecture, end-user setting, actuation technology, and therapy area with regional regulatory cluster differentiation. CAGRs derived from patient population growth projections, biologic pipeline conversion rates, and reimbursement code expansion assumptions. Industry-specific inputs included spring mechanism precision tolerance evolution and cyclic olefin polymer substitution elasticity.
Several conditions sit outside the modeled scope, including specific pharmaceutical formulation failures in subcutaneous conversion, abrupt FDA guidance revisions on human factors validation, and geopolitical disruption to Swiss-German precision component corridors. Forecasts reflect documented assumptions on chronic disease prevalence trajectories and reimbursement durability. Deviation in biologic viscosity delivery mechanics breakthrough would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Electroceutical Devices Market
Medical Devices
Fluid and Blood Warmer Market
Medical Devices
Face Mask Device Market
Medical Devices
Volumetric Arc Therapy Market
Medical Devices
Interventional Spine Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
Global Centesis Catheters Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
United States Contraceptive Devices Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Pulse Electromagnetic Field (PEMF) Therapy Devices Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Aesthetic Devices Market
Medical Devices
Home Dialysis Systems Market
Medical Devices
Urolithiasis Management Devices Market
Medical Devices
Accelerometers Medical Sensors Market