
 Digital Vision Lenses Market | 2026-2036
Digital Vision Lenses Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Vision Lenses Market Outlook
The EU Medical Device Regulation is restructuring quality assurance requirements for ophthalmic lens manufacturing across European markets. Essilor International leverages its captive freeform surfacing network to sustain premium positioning in progressive lens supply. Carl Zeiss Meditec AG anchors German precision engineering standards across its digital lens portfolio. HOYA Corporation dominates high-index material formulations for Asian facial geometries.
Digital vision lenses are ophthalmic corrective devices manufactured through computer-numerical-controlled freeform surfacing that achieves surface accuracy below 0.01 diopter deviation from prescribed optical power. These lenses correct refractive errors while integrating functional coatings for specific light management purposes. Progressive lenses represent the largest margin pool as presbyopia incidence rises among screen-intensive occupational cohorts. Blue light blocking coatings capture the fastest expansion as employers in finance and technology sectors fund occupational vision programs. Photochromic technology segments retain stable replacement demand from outdoor-active demographics.
The US FDA classifies digital vision lenses as Class I medical devices, requiring substantial equivalence demonstrations for new freeform designs entering commercial distribution. Japan's PMDA enforces JIS T 8147 standards for blue light attenuation claims on ophthalmic products. China's NMPA aligns with GB 10810 series optical tolerances while tightening registration pathways for imported high-index materials. Stakeholders must monitor divergence between regional coating performance standards before committing to unified manufacturing platforms.
Market Dynamics
Freeform surfacing equipment consolidation among German and Japanese precision optics manufacturers is compressing equipment lead times while elevating capital barriers for new entrants seeking MDR-compliant production capacity.
Growth Catalysts
- EU MDR certification thresholds:Elevated quality requirements for freeform surfacing equipment are filtering out subscale manufacturers and concentrating supply among validated producers.
- Occupational vision programs:Technology and finance sector employers in China's tier-one cities now fund blue light filtering prescriptions as workforce retention tools.
- Presbyopia demographics:Aging populations in Japan and Germany are expanding the patient pool for progressive lens designs with integrated digital coatings.
Market Restraints
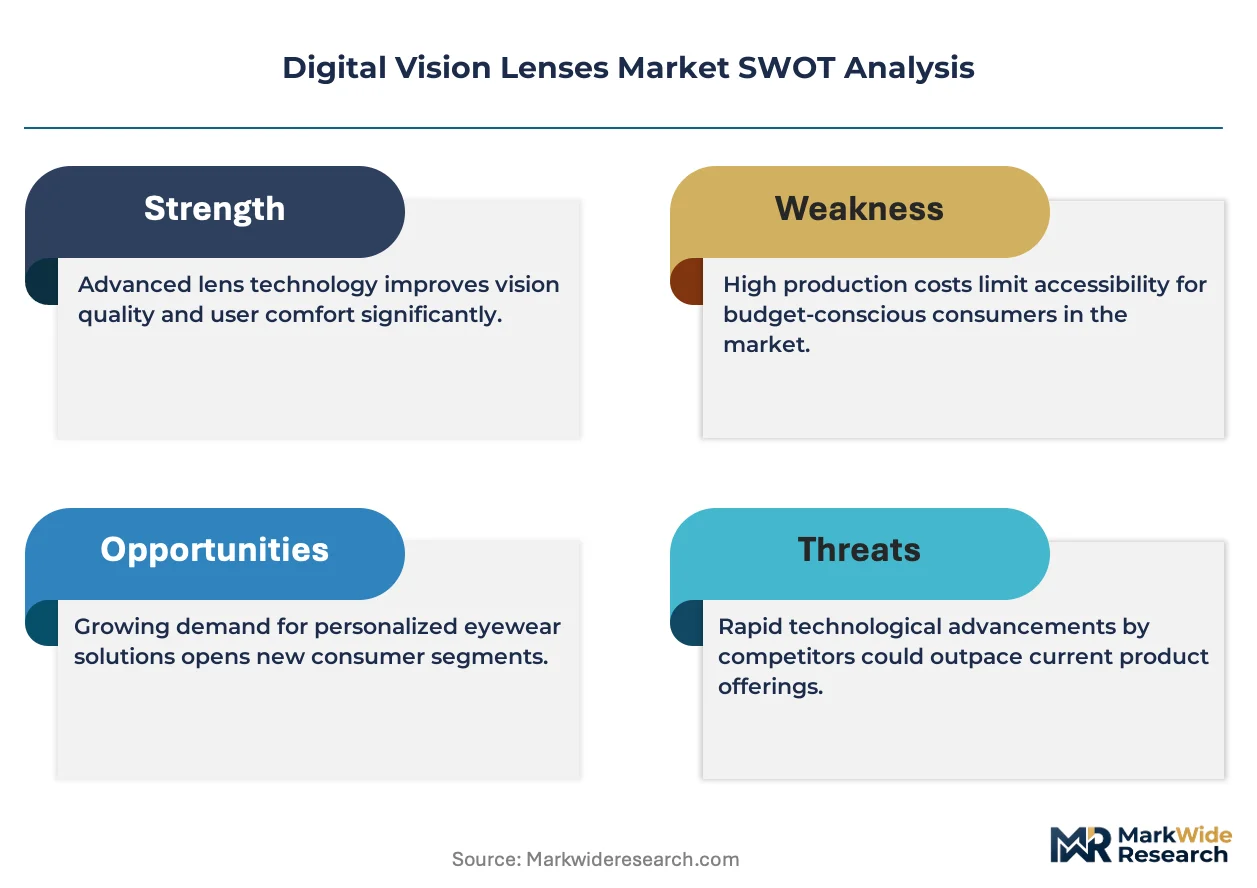
- High-index monomer supply:Petrochemical feedstock volatility affects optical resin costs for lenses above 1.67 refractive index.
- Equipment vendor concentration:Freeform generator and polisher supply concentrates among Stuttgart-area and Nagoya-area precision machinery specialists.
- Coating standard divergence:JIS T 8147 blue light attenuation metrics differ from FDA substantial equivalence pathways, fragmenting R&D allocation.
Strategic Opportunities
- India's tier-two cities:Ophthalmic retail chains in Bengaluru and Hyderabad are expanding beyond metro saturation into presbyopia-underserved demographics.
- Smart eyewear convergence:Waveguide integration with corrective lenses opens prescription AR applications for logistics and surgical training verticals.
- Tele-optometry channels:Remote refraction platforms in Brazil and Mexico are creating direct-to-consumer prescription capture outside traditional retail.
Industry Challenges
- Freeform metrology talent:Surface accuracy verification below 0.01 diopter deviation requires specialized optomechanical engineers scarce outside Stuttgart and Rochester optics clusters.
- Dual-registration complexity:Simultaneous FDA 510(k) and NMPA GB 10810 compliance timelines extend product commercialization by 18-24 months for imported high-index materials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Vision Lenses Market |
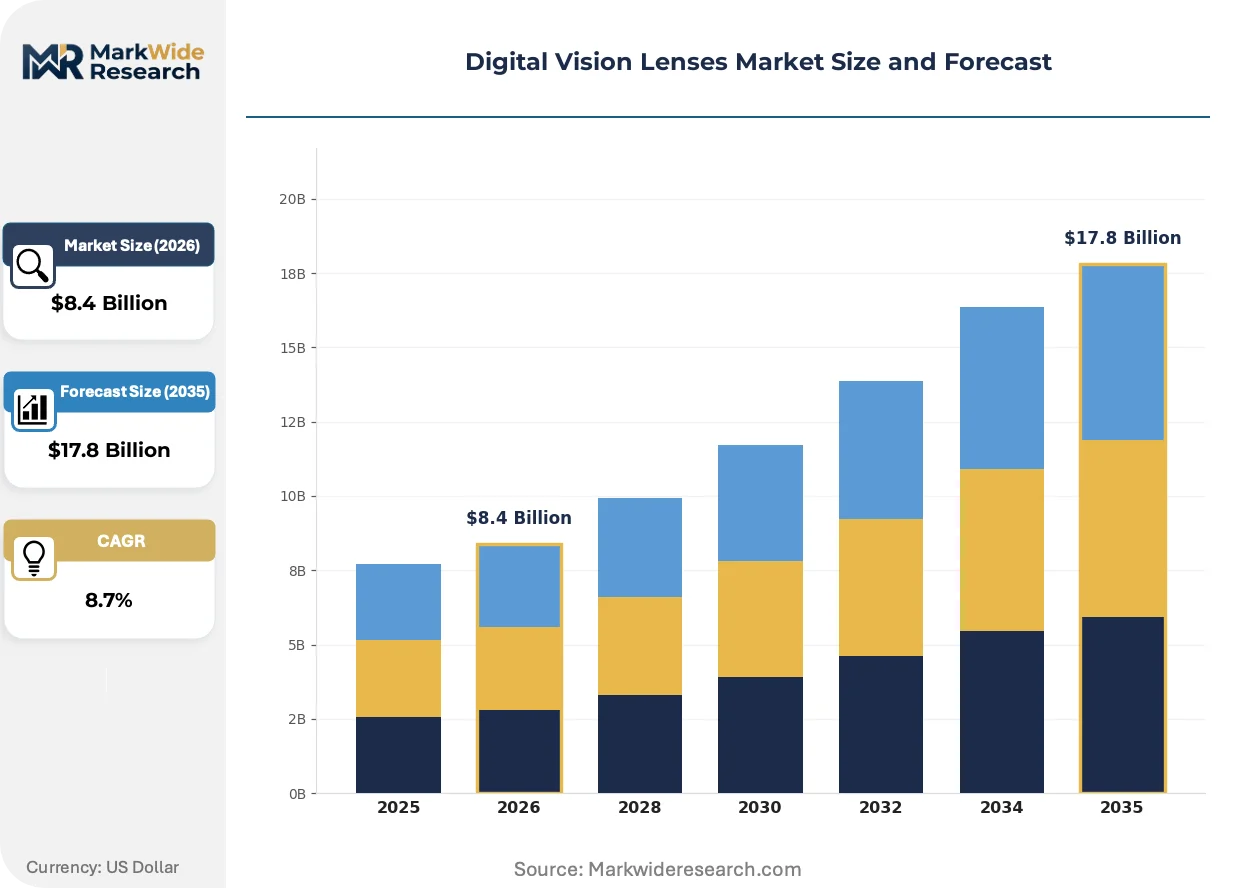
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Vision, Bifocal, Progressive, Blue Light Blocking End User: Optometrists, Ophthalmologists, Retail Stores, Online Retailers Technology: Digital Freeform, Anti-Reflective, Photochromic, Polarized Material: Polycarbonate, Trivex, Glass, High-Index Plastic |
| Companies Covered | Essilor International, Carl Zeiss Meditec AG, HOYA Corporation, Nikon Corporation, Shamir Optical Industry Ltd., Seiko Optical Products Co., Ltd., Luxottica, Johnson & Johnson Vision Care, Safilo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Vision Lenses Market Strategic Shifts
Wavefront-guided customization is compressing the gap between ophthalmic correction and visual performance optimization, reshaping how lens laboratories compete on optical precision rather than throughput scale.
AI-powered surface optimization algorithms are converging with traditional freeform surfacing to enable real-time compensation for material shrinkage during polymerization. Mid-sized independent laboratories in Italy and South Korea are adopting these tools to match multinational quality without captive equipment networks. The technology is converging with cloud-based prescription management platforms, enabling distributed manufacturing footprints that reduce finished lens shipping distances to optical retailers.
The EU Medical Device Regulation's post-market surveillance requirements are mandating traceable coating performance data across progressive lens portfolios. Manufacturers must now maintain batch-level documentation of blue light attenuation and photochromic response metrics for decade-long liability windows. German and French optical laboratories are responding by integrating spectrophotometric testing directly into surfacing workflows rather than outsourcing verification.
Employer-funded occupational vision benefits are compressing replacement cycles for screen-intensive workers from three-year intervals to annual allowances. Technology sector HR departments in San Francisco, Singapore, and Tel Aviv now negotiate group rates with optical chains for blue light filtering packages bundled with ergonomic assessments. This procurement model is displacing out-of-pocket lens purchases among 25-45 year-old knowledge workers, shifting price sensitivity from individual consumers to enterprise benefits administrators.
Digital Vision Lenses Market Segmentation
Digital vision lenses segment across multiple technical and commercial dimensions that determine manufacturing complexity, distribution pathways, and margin capture. Product type and material selection drive capital equipment requirements, while end-user channel and coating technology shape pricing architecture and regional competitive dynamics.
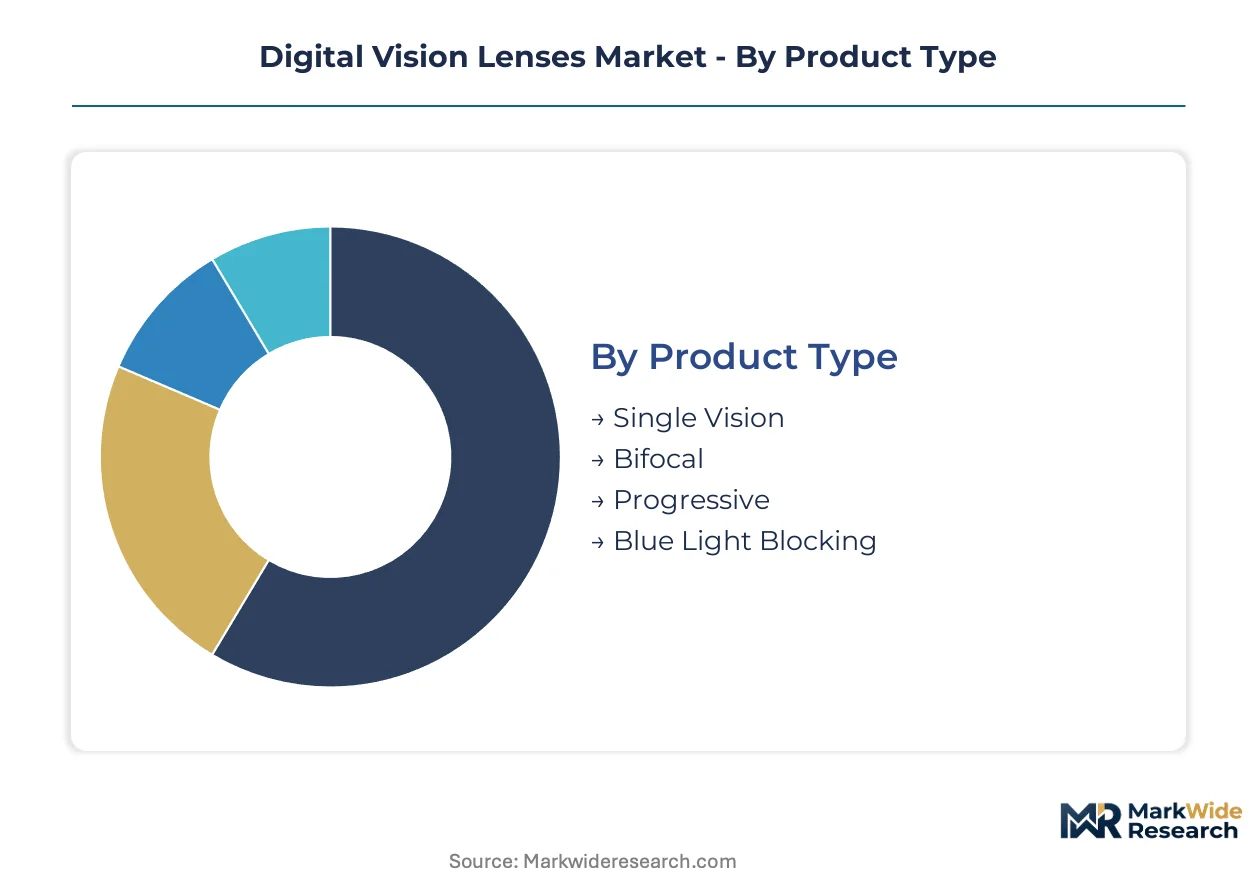
Product Type:
Supply concentration in freeform surfacing equipment favors manufacturers with progressive lens portfolios, while single-vision commoditization pushes volume toward automated coating lines.
- Progressive:Multi-focal designs with seamless power gradients require CNC freeform generators achieving sub-0.01 diopter surface accuracy. Demand concentrates among Japan's and Germany's aging presbyopic populations, where occupational screen exposure accelerates replacement cycles.
- Blue Light Blocking:Integrated coatings attenuating high-energy visible light between 415-455 nanometers. China's tier-one city employers now fund these prescriptions for technology and finance sector workforces, compressing procurement decisions from individual consumers to enterprise benefits administrators.
- Single Vision:Standard corrective lenses for myopia or hyperopia dominate volume production through automated surfacing lines in high-throughput laboratories.
- Bifocal:Segmented designs with distinct distance and near zones retain stable demand among price-sensitive demographics and specific occupational safety applications.
Today's leader: Progressive. Tomorrow's challenger: Blue Light Blocking.
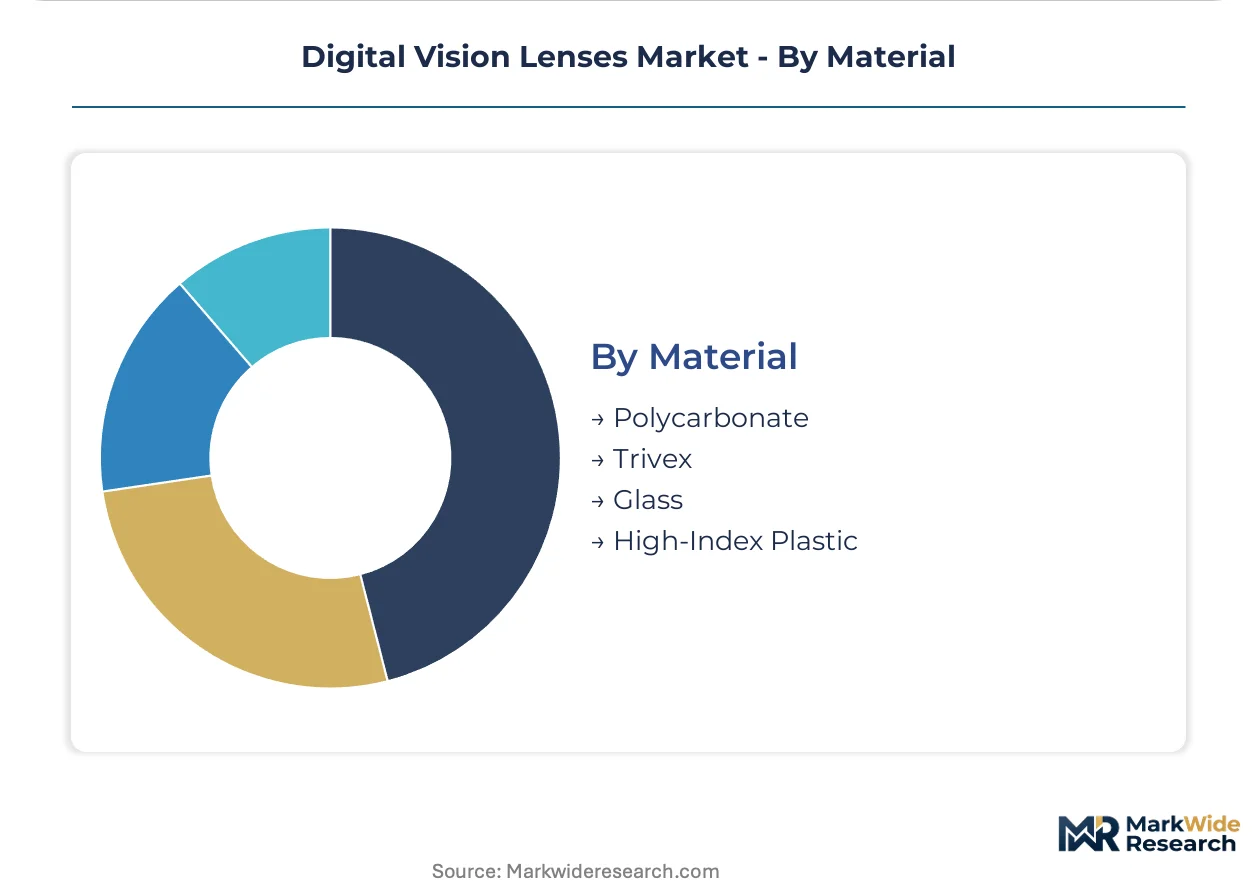
Material:
Cost tier stratification separates premium high-index formulations from commodity polycarbonate volume, with refractive index directly correlating to petrochemical feedstock sensitivity.
- High-Index Plastic:Resins above 1.67 refractive index enable thinner profiles for strong prescriptions. HOYA Corporation dominates formulations optimized for Asian facial geometries, though EU MDR certification requirements now extend registration timelines for imported monomers.
- Polycarbonate:Impact-resistant thermoplastic capturing safety eyewear and pediatric segments through lower price points and ANSI Z87.1 compliance.
- Trivex:Lightweight urethane-based material combining impact resistance with optical clarity for rimless and semi-rimless frame designs.
- Glass:Mineral lenses retain niche demand for scratch resistance and thermal stability in specialized industrial and military applications.
High-Index Plastic commands premium positioning. Polycarbonate defends volume share through safety certification requirements.
Technology:
Application-specific performance requirements determine coating stack complexity, with occupational vision programs driving fastest adoption of functional surface treatments.
- Digital Freeform:Computer-numerical-controlled surfacing enables point-by-point power optimization across the entire lens surface. Stuttgart-area and Nagoya-area equipment vendors concentrate supply, elevating capital barriers for MDR-compliant production capacity.
- Photochromic:Light-adaptive molecules embedded in substrate or applied as surface coating respond to UV intensity. Outdoor-active demographics in Australia and the western United States sustain replacement demand despite slower growth trajectories.
- Anti-Reflective:Multi-layer interference coatings reduce surface reflections and improve light transmission for night driving and screen-intensive use cases.
- Polarized:Laminated filters blocking polarized glare from horizontal surfaces serve fishing, boating, and high-altitude recreational markets.
Digital Freeform anchors precision positioning. Photochromic holds replacement stability.
End User:
Customer type determines service intensity, prescription capture mechanics, and reimbursement pathway complexity across diverging regulatory environments.
- Retail Stores:Optical chains and independent dispensaries dominate finished lens distribution, bundling refraction services with frame-lens packages. India's tier-two city expansion in Bengaluru and Hyderabad extends beyond metro saturation into presbyopia-underserved demographics.
- Online Retailers:Direct-to-consumer platforms leverage remote refraction technology and home trial programs to bypass traditional optical retail. Brazil and Mexico tele-optometry channels capture prescriptions outside conventional brick-and-mortar networks.
- Optometrists:Primary eye care providers control initial prescription issuance and lens recommendation authority in most developed markets.
- Ophthalmologists:Medical specialists manage complex refractive cases and post-surgical correction, commanding higher service fees and specialized lens requirements.
Retail Stores defend incumbent position. Online Retailers gain share fastest through tele-optometry integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision optics manufacturing originated in German and Japanese industrial clusters during the mid-20th century, establishing the technical foundations for contemporary freeform surfacing capabilities. These heritage centers continue to define quality certification standards and equipment supply chains.
United States
Employer-funded occupational vision benefits now cover annual lens allowances for technology sector workers in San Francisco and Seattle. The FDA maintains Class I medical device classification for digital vision lenses with substantial equivalence requirements for new freeform designs. Rochester, New York retains specialized optomechanical engineering talent for surface accuracy verification below 0.01 diopter deviation.
Germany
Stuttgart-area precision machinery manufacturers concentrate supply of freeform generators and polishers for MDR-compliant production capacity. The EU Medical Device Regulation elevates post-market surveillance requirements with decade-long liability windows for coating performance data. Baden-Württemberg optical laboratories integrate spectrophotometric testing directly into surfacing workflows.
Japan
Aging demographics expand the presbyopic patient pool for progressive lens designs in Tokyo and Osaka metropolitan areas. PMDA enforces JIS T 8147 standards for blue light attenuation claims on ophthalmic products. Nagoya-area equipment vendors compress lead times for precision optics manufacturing systems.
China
Digital eye strain clinics in Shanghai and Beijing bundle blue light filtering prescriptions with ophthalmic consultations for finance and technology workforces. NMPA aligns with GB 10810 series optical tolerances while tightening registration pathways for imported high-index materials. Yangtze River Delta manufacturing clusters scale automated coating lines for domestic market volume.
India
Ophthalmic retail chains in Bengaluru and Hyderabad expand beyond metro saturation into presbyopia-underserved demographics in tier-two cities. The country's national medical device regulator extends quality certification timelines for imported freeform surfacing equipment. Maharashtra optical dispensaries capture rising demand from screen-intensive occupational cohorts.
Digital Vision Lenses Market Competitive Environment
Capital-heavy producers compete with asset-light designers across a tiered market structure where equipment ownership separates premium positioning from volume commoditization. German and Japanese heritage manufacturers anchor the precision tier through captive freeform surfacing networks. Three strategic archetypes dominate: integrated optical conglomerates with laboratory-to-retail control, specialized lens manufacturers focused on material formulations, and equipment-dependent laboratories serving regional retail chains. Competitive moves concentrate on M&A for distribution access and strategic partnerships for coating technology licensing.
Within the integrated conglomerate tier, Essilor International and Luxottica exemplify vertical control from prescription capture through finished lens delivery. Among precision engineering specialists, Carl Zeiss Meditec AG occupies a position reflecting German optical heritage standards. HOYA Corporation represents the material formulation archetype with high-index resin expertise. These three anchors demonstrate how geographic origin and corporate structure align with competitive positioning in certification-intensive markets.
| Leading Market Players |
|---|
| Essilor International |
| Carl Zeiss Meditec AG |
| HOYA Corporation |
| Nikon Corporation |
| Shamir Optical Industry Ltd. |
| Seiko Optical Products Co., Ltd. |
| Luxottica |
| Johnson & Johnson Vision Care |
| Safilo Group |
| Others |
Value Chain & Pricing Dynamics
Captive freeform surfacing networks anchor pricing power for German and Japanese heritage manufacturers, while outsourced coating operations in China's Yangtze River Delta compress margins for commodity single-vision producers. EU MDR certification requirements for batch-level coating performance documentation extend liability windows and elevate quality-assurance costs that concentrate among validated precision optics clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Essilor International's progressive lens portfolios from mid-tier independent laboratories and volume-driven polycarbonate producers. Certification grade under EU MDR and JIS T 8147 standards, alongside refractive index specifications, anchor price differentiation between high-index formulations and commodity resins. Cost compression in standard-tier single-vision lenses intensifies as automated surfacing lines in Italy and South Korea match multinational throughput without captive equipment networks. Enterprise benefits administrators show lowest price sensitivity for occupational blue light filtering packages, while individual consumers in India's tier-two cities remain most responsive to out-of-pocket lens expenditures.
Supply Chain Analysis
Direct-to-retail optical chains handle finished lens distribution for progressive and blue light blocking prescriptions, while tele-optometry platforms in Brazil and Mexico bypass traditional brick-and-mortar for single-vision capture. Equipment supply concentrates in Germany's Stuttgart area and Japan's Nagoya region for MDR-compliant freeform generators and polishers. High-index monomer formulations draw from petrochemical feedstocks, precision optics machinery, and spectrophotometric testing equipment. Single-source vulnerability runs through German and Japanese precision machinery specialists for sub-0.01 diopter surface accuracy verification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as employer-funded occupational vision programs shift procurement authority toward benefits administrators demanding premium coating performance documentation.
For Market Incumbents: Anchor MDR-compliant production capacity through captive freeform surfacing networks in Stuttgart and Nagoya clusters. Defend against mid-tier independent laboratories adopting AI-powered surface optimization by integrating spectrophotometric testing directly into surfacing workflows. Certification investment in EU post-market surveillance systems extends decade-long liability coverage.
For New Entrants and Emerging Players: Tele-optometry channels in Brazil and Mexico offer the most penetrable route for prescription capture outside established retail networks. Target India's tier-two cities in Bengaluru and Hyderabad where ophthalmic retail chains expand beyond metro saturation. Direct-to-consumer platforms with home trial programs bypass traditional optical retail's frame-lens bundling economics.
For Investors and Strategic Acquirers: Roll-up economics work for mid-sized independent laboratories because AI-powered surface optimization algorithms now enable distributed manufacturing footprints without captive equipment networks. Five-to-ten year viability hinges on coating technology licensing partnerships and cloud-based prescription management integration. Watch employer-funded occupational vision benefit expansion as the inflection indicator for premium tier demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Validates freeform surfacing equipment for decade-long coating performance liability coverage. |
| Tele-Optometry Platform Integration | Captures prescriptions in Brazil and Mexico outside traditional brick-and-mortar retail networks. |
| AI-Powered Surface Optimization Deployment | Enables Italian and South Korean laboratories to match multinational quality without captive equipment. |
| Employer Benefits Partnership | Shifts procurement decisions from individual consumers to enterprise HR administrators in technology sectors. |
| High-Index Material Registration | Accelerates NMPA pathways for imported monomers serving China's tier-one city demand concentration. |
Study Parameters
Direct dialogue with freeform surfacing equipment manufacturers, optical laboratory operations directors, ophthalmic retail chain procurement managers, and enterprise benefits administrators grounded qualitative findings. Secondary validation drew from FDA 510(k) filings, NMPA registration databases, EU MDR post-market surveillance reports, and JIS T 8147 standard documentation. Bottom-up prescription volume modeling and top-down equipment capacity analysis provided triangulation across the analysis window.
Segment-level outputs across product type, material formulation, coating technology, and end-user channel informed the analytical framework throughout the projection horizon. CAGRs derived from equipment installation rates, replacement cycle compression in occupational vision programs, and demographic presbyopia incidence curves. Refractive index adoption patterns and blue light attenuation certification timelines served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for wavefront-guided customization and AI-powered surface optimization; alternative pathways for smart eyewear waveguide integration would alter the outlook. Forecasts reflect assumptions regarding EU MDR implementation timelines, petrochemical feedstock stability, and tele-optometry regulatory acceptance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Vision Aids Market
Medical Devices
Distraction Osteogenesis Devices Market
Medical Devices
Interspinous Process Decompression Devices Market
Medical Devices
Europe Electroencephalography Devices Market
Medical Devices
Intravaginal Device Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Endocavity Transducer Market
Medical Devices
Global Spirometers Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Intracranial Pressure Monitors Market
Medical Devices
Global Voice Prosthesis Devices Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Transcranial Magnetic Stimulator for Depression Requisition Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Europe Spinal Fusion Devices Market