
 Carotid Artery Disease Market | 2026-2036
Carotid Artery Disease Market Size, Share, and Industry Trends Forecast 2026-2036
Carotid Artery Disease Market Outlook
Aftermarket service revenue for carotid stent systems is rewriting how device manufacturers capture lifetime value from each implant. Medtronic leverages its extensive field service network to sustain recurring revenue streams across installed procedural suites. Abbott Laboratories anchors its vascular portfolio through specialized catheter refurbishment programs that extend customer relationships beyond initial device sales.
Carotid artery disease denotes atherosclerotic narrowing of the carotid bifurcation, typically quantified by duplex ultrasound peak systolic velocity ratios or angiographic percent stenosis, which elevates risk of ischemic stroke through embolization or hemodynamic compromise. Stent platforms command the largest product segment share due to their integration with embolic protection systems, while angioplasty balloons compete on procedural cost efficiency in cost-sensitive settings. Endovascular technology leads procedural volume growth as transcarotid artery revascularization protocols expand eligible patient pools beyond traditional surgical candidates.
The FDA's premarket approval pathway and the European Medicines Agency's Medical Device Regulation framework govern clinical evidence requirements for carotid interventions, with both agencies tightening scrutiny on long-term stroke prevention outcomes. The Centers for Medicare & Medicaid Services' national coverage determinations directly shape United States procedure economics by defining eligible patient populations and facility reimbursement tiers. Stakeholders must monitor evolving randomized trial readouts comparing transcarotid approaches against transfemoral standards to anticipate potential shifts in clinical guidelines and subsequent technology procurement priorities.
Market Dynamics
The transition from transfemoral to transcarotid artery revascularization protocols is compressing procedural timelines and redrawing competitive positioning among stent manufacturers.
Growth Catalysts
- Transcarotid Protocol Expansion:TCAR eligibility criteria broadening through Society for Vascular Surgery guidelines pulls previously surgical-only patients into endovascular suites.
- CMS Reimbursement Alignment:Medicare national coverage determinations for transcarotid stenting with embolic protection now match transfemoral rates, removing facility-level economic disincentives.
- Embolic Protection Integration:Filter-based protection systems co-developed with stent platforms reduce periprocedural stroke rates below 2%, satisfying FDA long-term outcome thresholds.
Market Restraints
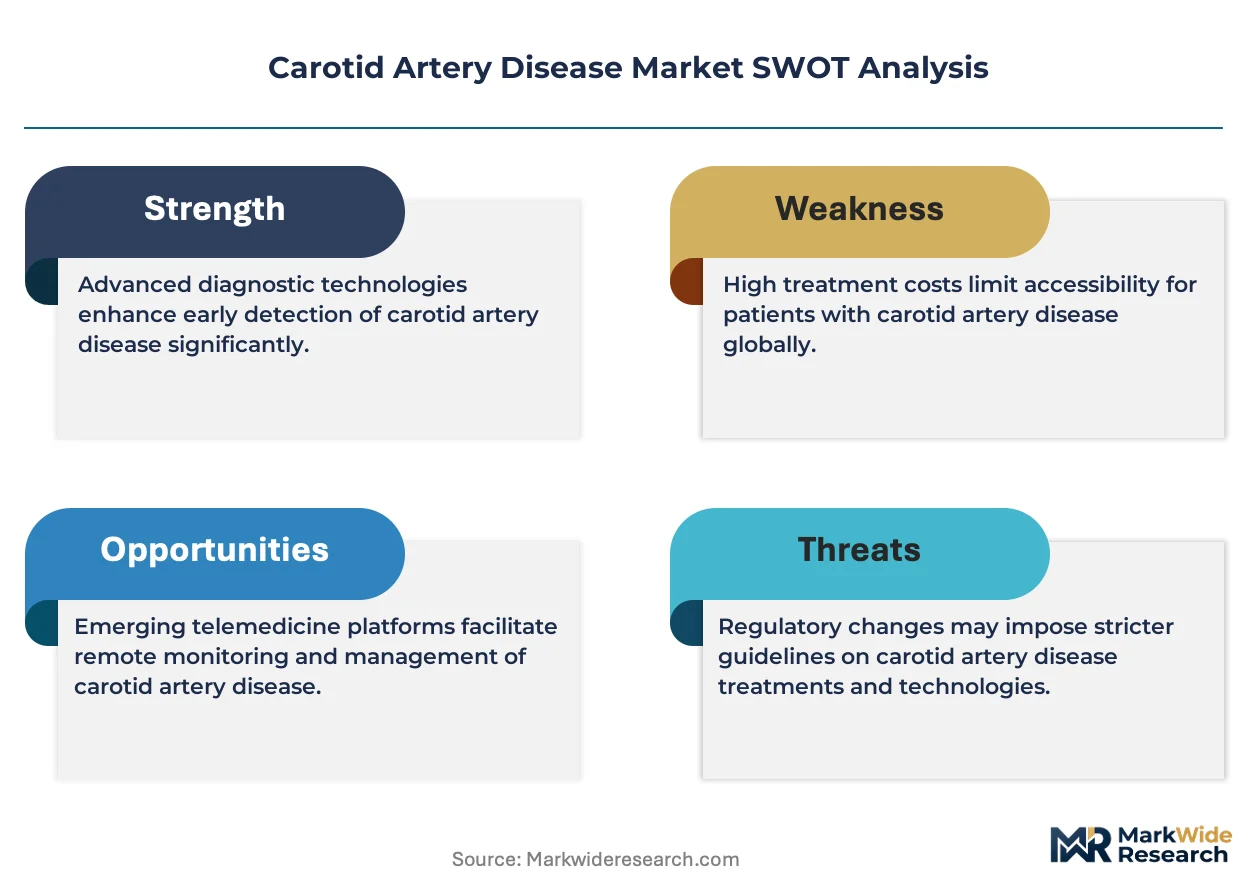
- Nitinol Alloy Supply Concentration:Superelastic nitinol sourcing clusters among three primary melt shops, exposing stent manufacturers to raw material allocation volatility.
- CE Mark Transition Costs:European Medical Device Regulation recertification demands extended clinical follow-up data, freezing new product introductions in EU markets.
- Surgical Resection Persistence:Carotid endarterectomy retains guideline-preferred status for low-surgical-risk patients, capping endovascular ceiling in optimal anatomy cases.
Strategic Opportunities
- Japan Regulatory Pathway:PMDA's conditional early approval framework for breakthrough devices offers accelerated market access for next-generation stent platforms with superior radial force profiles.
- Outpatient Migration:Ambulatory surgical centers adopting TCAR protocols capture cases shifting from inpatient hospital settings, creating channel-specific volume pools.
- AI-Enabled Plaque Characterization:Machine learning analysis of intravascular ultrasound and OCT imaging converges with stent sizing algorithms to enable patient-specific device selection.
Industry Challenges
- Neurointerventionalist Training Pipeline:TCAR credentialing requires dedicated vascular surgery or neurointerventional fellowship exposure, constraining eligible operator supply below procedural demand growth.
- Biocompatibility Testing Backlogs:ISO 10993-5 cytotoxicity and ISO 10993-10 sensitization study queues at contract laboratories extend pre-submission timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotid Artery Disease Market |
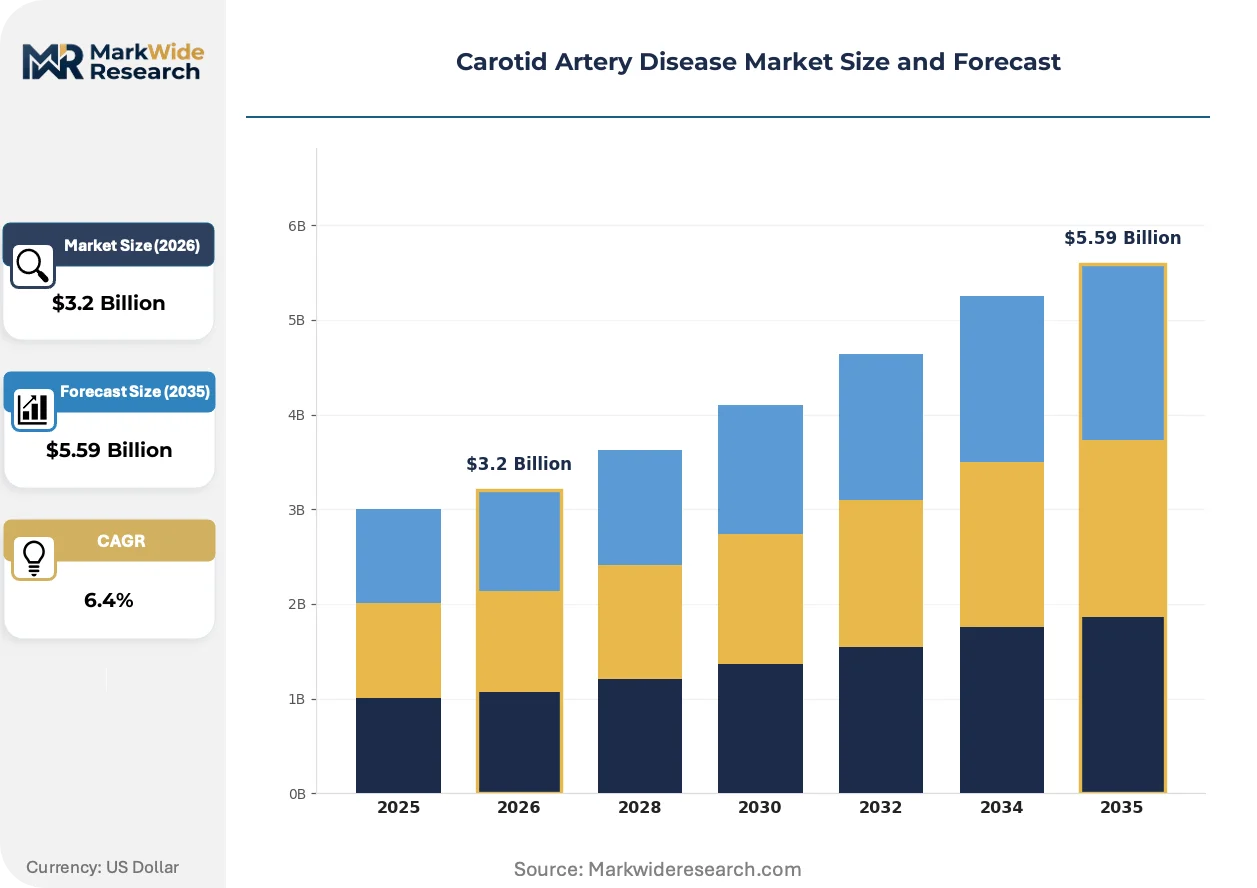
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Angioplasty Balloons, Catheters, Filters End User: Hospitals, Clinics, Specialized Centers, Home Healthcare Technology: Endovascular, Surgical, Ultrasonography, Imaging Patient Group: Geriatric, Diabetic, Hypertensive, Asymptomatic |
| Companies Covered | B. Braun Melsungen AG, Stryker, Boston Scientific Corporation, Terumo Corporation, Johnson & Johnson Services Inc., Medtronic, BIOTRONIK SE & Co. KG, InspireMD, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotid Artery Disease Market Strategic Shifts
Device miniaturization and procedural simplification are compressing the skill threshold required for carotid intervention, expanding addressable operator pools beyond traditional vascular specialists.
Dual-layer micromesh stent technology is migrating from coronary applications into carotid platforms, offering embolic capture without separate protection device deployment. Interventional cardiologists familiar with coronary micromesh designs are adopting these platforms for carotid cases at accelerating rates. The technology is enabling single-device procedures that compress lab time and reduce hardware costs per case.
EMA's Medical Device Regulation Article 61 clinical evidence requirements now mandate randomized trial data for Class III implantable devices, superseding historical equivalence pathways. Manufacturers must sponsor purpose-built stroke-prevention trials rather than leveraging historical carotid stent data. Small-cap developers without trial infrastructure are exiting EU markets, concentrating European supply among established players with dedicated clinical affairs divisions.
Hospital procurement committees now bundle stent-protection system contracts across cardiac and vascular service lines, consolidating vendor relationships. Integrated delivery networks in Texas and Florida are replacing product-by-product purchasing with two-source agreements covering coronary, peripheral, and carotid portfolios. This concentration rewards manufacturers with full vascular platforms while marginalizing single-product specialists.
Carotid Artery Disease Market Segmentation
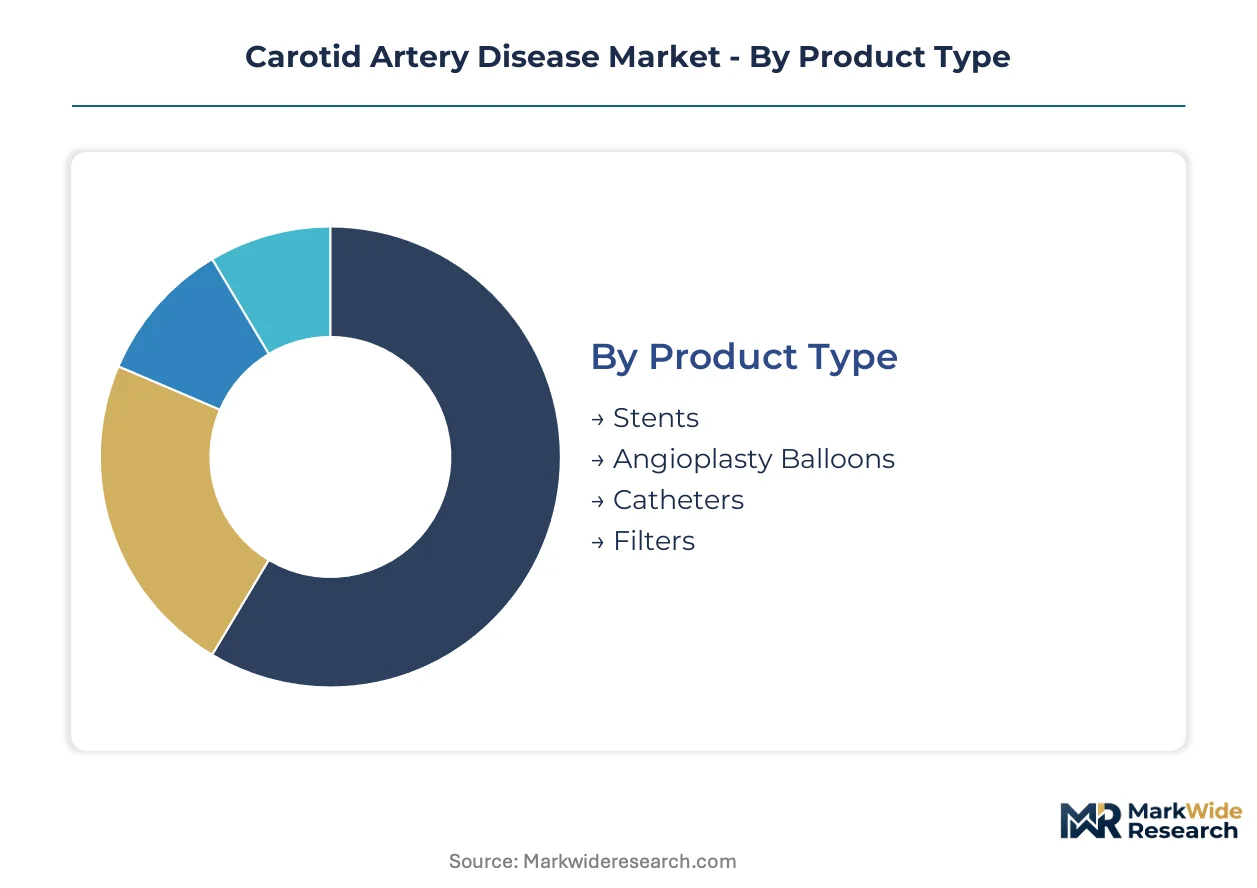
Carotid intervention markets fragment across device modalities, care settings, and patient risk profiles. Each segmentation layer exposes distinct procurement dynamics and reimbursement dependencies that shape manufacturer go-to-market priorities.
Product Type:
Mature stent platforms dominate procedural economics while emerging balloon technologies compete on cost efficiency in constrained budgets.
- Stents:Nitinol self-expanding platforms with integrated embolic protection command premium pricing in hospital catheterization labs. United States Medicare reimbursement parity between transcarotid and transfemoral approaches sustains volume concentration in integrated delivery networks.
- Angioplasty Balloons:Semi-compliant and non-compliant balloon catheters enable predilation and postdilation sequences. Cost-sensitive European clinics under EMA Medical Device Regulation cost pressures adopt balloon-only protocols for select low-risk anatomies.
- Catheters:Guiding and diagnostic catheters deliver contrast and device access.
- Filters:Distal and proximal embolic protection devices capture debris during intervention.
Stents handle the majority of throughput; angioplasty balloons are gaining share fastest in cost-constrained settings.
End User:
Procurement authority concentrates in acute-care institutions while ambulatory migration restructures site-of-service economics.
- Hospitals:Inpatient surgical suites and catheterization labs maintain procedural complexity thresholds for high-risk cases. CMS facility fee schedules reinforce hospital anchoring for transcarotid revascularization with overnight observation protocols.
- Clinics:Outpatient vascular clinics capture stable post-procedural surveillance and duplex ultrasound monitoring. Florida and Texas regulatory environments permit office-based lab procedures with streamlined credentialing.
- Specialized Centers:Dedicated stroke centers and vascular institutes concentrate operator expertise.
- Home Healthcare:Remote patient monitoring and antiplatelet therapy management extend care continuity.
Hospitals retain the dominant reimbursement tier; specialized centers are expanding most quickly on procedural volume.
Technology:
Volume distribution tilts toward minimally invasive platforms while imaging modalities enable patient selection precision.
- Endovascular:Transfemoral and transcarotid stenting protocols minimize surgical morbidity. Society for Vascular Surgery guideline expansions pull anatomically suitable patients from surgical queues into endovascular suites.
- Surgical:Carotid endarterectomy preserves guideline-preferred status for low-surgical-risk patients with favorable anatomy. United States Veterans Affairs health system maintains surgical volume through standardized perioperative protocols.
- Ultrasonography:Duplex ultrasound quantifies stenosis severity and plaque morphology.
- Imaging:CT angiography and MR angiography guide procedural planning.
Endovascular approaches absorb the majority of growth; surgical resection defends share in optimal-risk populations.
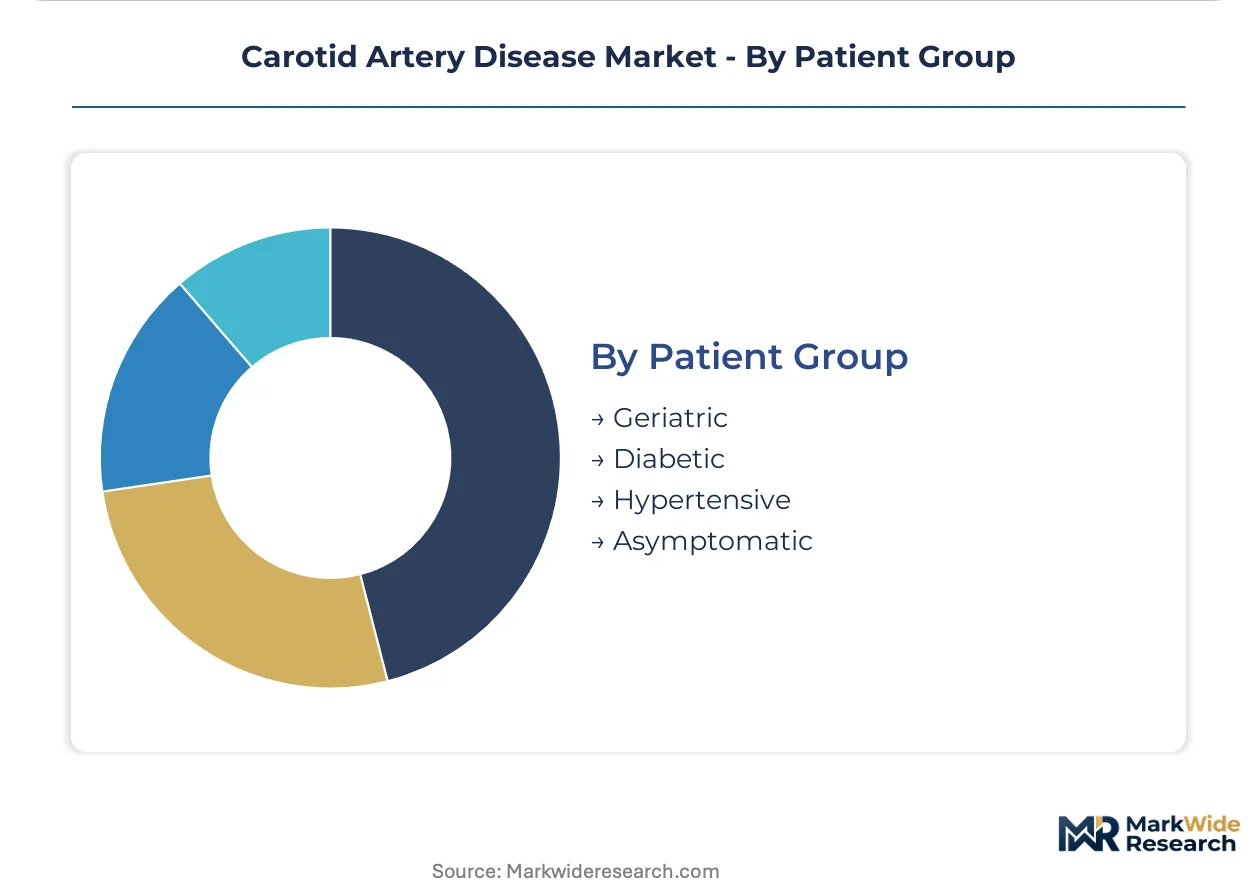
Patient Group:
Risk stratification drives device selection intensity and antithrombotic regimen complexity across demographic and comorbidity profiles.
- Geriatric:Patients over 75 years present calcified anatomy and elevated periprocedural stroke risk. Japanese PMDA regulatory pathways prioritize geriatric-specific stent radial force profiles for fragile vessel walls.
- Diabetic:Accelerated atherosclerosis and diffuse disease patterns complicate device sizing. United Kingdom National Institute for Health and Care Excellence guidelines mandate tighter glycemic control thresholds prior to intervention.
- Hypertensive:Chronic blood pressure elevation correlates with carotid bifurcation disease severity.
- Asymptomatic:Screening-detected stenosis below intervention thresholds requires surveillance protocols.
Geriatric patients represent the largest addressable population; diabetic subgroups are climbing the fastest on intervention intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States procedural volumes concentrate in Medicare-reimbursed hospital settings, while Japanese clinicians pursue PMDA conditional approvals for next-generation platforms. European facilities navigate EMA Medical Device Regulation recertification delays. Chinese hospitals expand endovascular suites under centralized procurement reforms. Australian stroke centers align with TGA guidance for embolic protection integration.
United States
Medicare national coverage determinations for transcarotid stenting now match transfemoral reimbursement rates, eliminating facility-level economic disincentives. FDA premarket approval pathways demand long-term stroke prevention outcomes below 2% periprocedural rates. Integrated delivery networks in Texas and Florida consolidate vendor contracts across cardiac and vascular service lines.
Germany
CE Mark transition costs under EMA Medical Device Regulation freeze new product introductions as manufacturers compile extended clinical follow-up data. KBA-equivalent device safety standards influence hospital procurement committee evaluations. Medical technology clusters in Baden-Württemberg concentrate stent platform refurbishment operations.
Japan
PMDA conditional early approval frameworks accelerate market access for breakthrough devices with superior radial force profiles. METI industrial policy supports domestic nitinol alloy processing capabilities. Tokyo and Osaka metropolitan stroke centers lead TCAR protocol adoption across the Asia-Pacific region.
United Kingdom
National Institute for Health and Care Excellence guidelines mandate tighter glycemic control thresholds for diabetic patients prior to carotid intervention. NHS England procurement frameworks bundle stent-protection system contracts across regional networks. London and Manchester vascular institutes concentrate operator training pipelines.
Australia
TGA conformity assessment procedures align with ISO 14155 clinical investigation standards for implantable device trials. State-based health department funding models favor outpatient migration to ambulatory surgical centers. Sydney and Melbourne stroke centers pilot AI-enabled plaque characterization protocols.
Carotid Artery Disease Market Competitive Environment
Capability concentration sits with specialized stent platform developers; scale advantage sits with diversified cardiovascular conglomerates. The vendor base organizes around three archetypes: integrated delivery network contract holders, micromesh technology specialists, and regional refurbishment service providers. Dominant competitive moves include portfolio diversification across coronary-peripheral-carotid segments and backward integration into nitinol alloy supply.
Among diversified cardiovascular conglomerates, Medtronic and Abbott Laboratories occupy positions as integrated delivery network anchor vendors. Boston Scientific Corporation exemplifies the technology licensing archetype through its embolic protection co-development partnerships. These three entities represent the scale-driven tier where hospital procurement consolidation concentrates purchasing authority.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Stryker |
| Boston Scientific Corporation |
| Terumo Corporation |
| Johnson & Johnson Services Inc. |
| Medtronic |
| BIOTRONIK SE & Co. KG |
| InspireMD |
| Abbott Laboratories |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in European nitinol alloy melt shops is compressing raw material premiums and forcing stent manufacturers toward multi-year offtake commitments that lock in volume but sacrifice pricing flexibility. This utilization dynamic cascades through contract negotiations, with buyers extracting concessions on per-unit stent costs while suppliers defend margins through aftermarket service bundling.
Pricing Analysis
Long-term offtake agreements dominate procurement between stent manufacturers and nitinol suppliers, with three-year contracts anchoring unit economics against spot market volatility. Price differentiation rests on embolic protection integration tiers and FDA PMA certification status, with dual-layer micromesh platforms commanding premiums over conventional open-cell designs. Cost compression in standard stent tiers is intensifying as integrated delivery networks consolidate vendor contracts across cardiac and vascular service lines. Ambulatory surgical centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize clinical outcome data over per-unit costs.
Supply Chain Analysis
Contract manufacturing for nitinol stent fabrication concentrates in Germany, Switzerland, and the United States, with specialized laser-cutting foundries holding captive capacity for tier-one device developers. Superelastic nitinol alloy, platinum-iridium radiopaque markers, and biocompatible polymer coatings constitute critical input dependencies. Single-source vulnerability in superelastic nitinol sourcing from three primary melt shops exposes manufacturers to allocation disruptions during demand spikes. Distribution runs through direct sales forces for hospital catheterization labs and specialized distributors for ambulatory surgical center penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is exiting a regulatory recertification trough, with EMA MDR compliance costs peaking and FDA PMA pathway timelines stabilizing to support cyclical recovery momentum.
For Market Incumbents: Pre-empt micromesh technology displacement by accelerating dual-layer platform FDA submissions ahead of coronary-trained interventionalist adoption curves. Secure backward integration into nitinol alloy supply through equity stakes in primary melt shops to defend against raw material allocation volatility. Consolidate integrated delivery network contracts across coronary-peripheral-carotid portfolios before procurement committee rationalization completes. For New Entrants and Emerging Players: Establish a beachhead in Japanese PMDA conditional approval pathways for geriatric-specific stent radial force profiles, where breakthrough device designation accelerates market access without historical trial data requirements. Target outpatient migration corridors in Florida and Texas ambulatory surgical centers, where streamlined credentialing protocols reduce operator training barriers. Pursue AI-enabled plaque characterization partnerships with imaging system OEMs to differentiate on patient-specific device selection workflows. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across stent platform development as FDA long-term outcome thresholds standardize trial designs and reduce protocol variability costs. Long-term viability over the next decade favors developers with captive clinical affairs infrastructure capable of sponsoring purpose-built stroke-prevention trials. Monitor PMDA breakthrough device approval velocity as the inflection indicator for next-generation platform commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | FDA PMA submissions with sub-2% periprocedural stroke data satisfy long-term outcome thresholds for transcarotid platforms. |
| CE Marking Recertification | EMA MDR Article 61 compliance mandates randomized trial data, freezing EU new product introductions among small-cap developers. |
| Hospital System Partnership | Integrated delivery networks in Texas consolidate cardiac-vascular contracts across two-source procurement frameworks. |
| Software Companion Development | AI-enabled plaque characterization algorithms converge with intravascular ultrasound for patient-specific stent sizing. |
| Reimbursement Strategy | CMS national coverage determinations for TCAR match transfemoral rates, eliminating facility-level economic disincentives. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA PMA filings, CMS Medicare reimbursement databases, and Society for Vascular Surgery guideline publications. Primary interviews engaged vascular surgeons, neurointerventionalists, hospital purchasing committee directors, GPO contracts managers, and biomedical engineers across United States, German, and Japanese medical centers. Bottom-up procedural volume estimates triangulate against top-down manufacturer revenue disclosures and nitinol alloy consumption patterns.
Forecast inputs incorporate endovascular versus surgical procedure splits, stent platform technology generations, and patient risk stratification demographics across the projection horizon. Segmentation dimensions model product type, end-user setting, procedural technology, and patient comorbidity profiles. CAGRs derive from logistic diffusion curves fitted to Medicare claims data and Society for Vascular Surgery registry submissions. Industry-specific inputs include PMDA conditional approval timelines and EMA MDR recertification completion rates.
Stress conditions across nitinol alloy supply disruptions, CMS reimbursement rate revisions, and TCAR credentialing pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding guideline expansion trajectories and competitive response latency. Quarterly review of PMDA breakthrough device designations and integrated delivery network contract awards is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular
Global Cardiac Rehabilitation Market
Cardiovascular
Stroke Management Market
Cardiovascular
Cardiovascular Pledgets Market
Cardiovascular
Peptide-Based Cardiovascular Therapeutics Market
Cardiovascular
Global Atrial Fibrillation Market
Cardiovascular
Myocardial Ischemia Market
Cardiovascular
Global Hypotension Treatment Market
Cardiovascular
Ischemia Reperfusion Injury Therapeutics Market
Cardiovascular
Peripheral Artery Disease Market
Cardiovascular
Angina Pectoris Treatment Market
Cardiovascular
Global Pericarditis Market
Cardiovascular
Cardiovascular Disease Drugs Market
Cardiovascular
Tachycardia Market
Cardiovascular
Prinzmetal Angina Therapeutics Market
Cardiovascular
Pericarditis Treatment Market
Cardiovascular
Carotid Artery Stenosis Market