
 Cardiovascular Devices Market | 2026-2036
Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Cardiovascular Devices Market Analysis
EU MDR is expanding the cost-of-entry calculus for cardiovascular device manufacturers by mandating extended clinical follow-up and stricter notified body oversight. Medtronic leverages its established European regulatory infrastructure to sustain market access across high-margin stent and pacemaker portfolios. Abbott Laboratories differentiates through drug-eluting stent platforms that navigate evolving PMCF requirements, while Boston Scientific Corporation anchors its competitive position with deep cath lab channel control in reimbursed procedure markets.
Cardiovascular devices encompass implantable and interventional instruments engineered from cobalt-chromium alloys, nitinol, or bioresorbable polymers to restore or monitor cardiac function, typically requiring ISO 10993 biocompatibility validation and fatigue-tested structural integrity under cyclic vascular loading. Their primary commercial purpose centers on reducing mortality and repeat intervention rates in coronary and peripheral circulatory pathologies. Stent platforms occupy the largest value pool within product type segmentation, driven by recurring restenosis intervention volumes, while MRI-compatible devices represent the fastest-expanding technology tier as health systems prioritize multimodal imaging workflows without device explantation. Catheters compete on procedural efficiency metrics, with margin concentration favoring integrated delivery systems over commodity single-use variants.
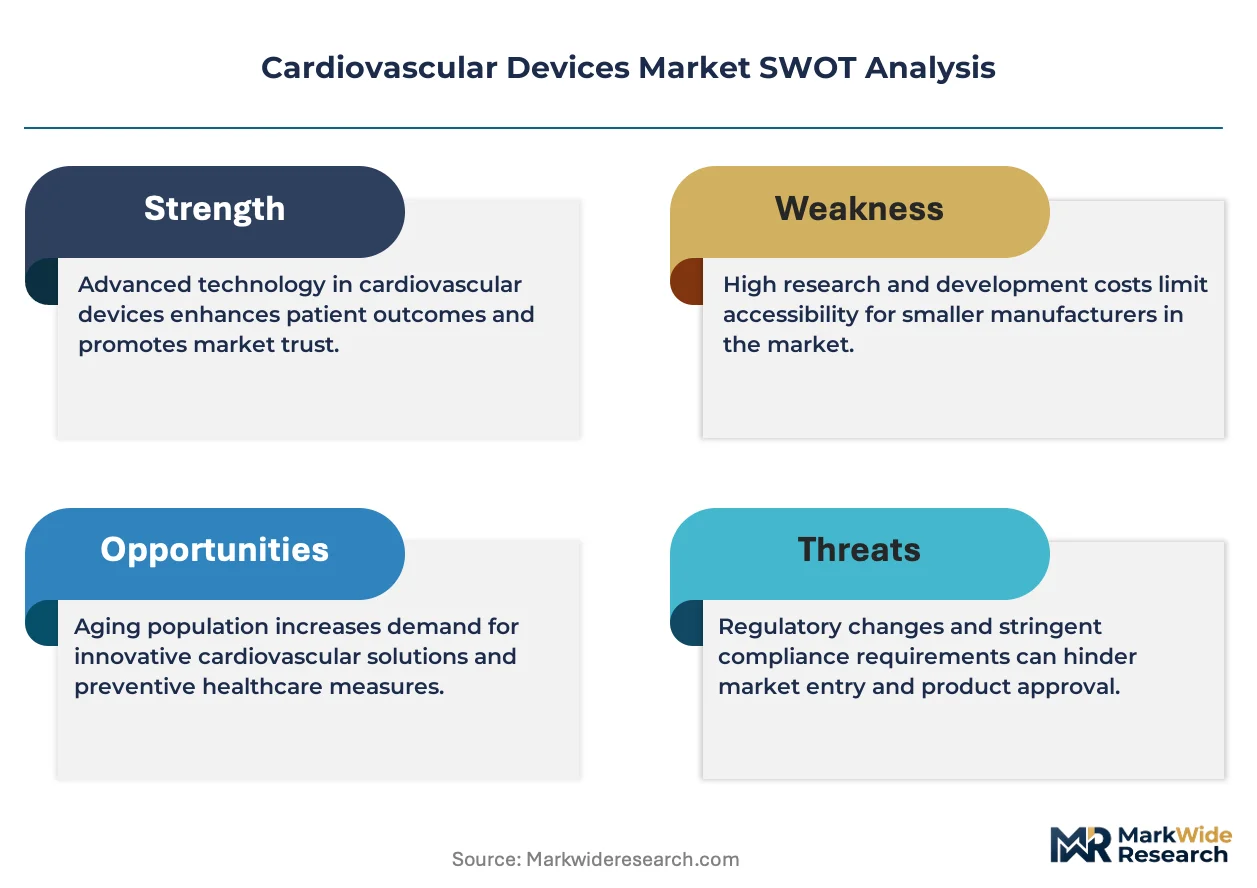
FDA premarket notification and EU MDR notified body conformity assessments shape product standards, trial design, and market access timelines for cardiovascular devices across their primary commercial geographies, with ISO 14155 clinical investigation standards further governing evidence generation protocols. Japan's PMDA imposes additional local bridging study requirements that extend registration timelines for Western manufacturers seeking reimbursement listing. Stakeholders must monitor evolving FDA guidance on bio-absorbable stent long-term safety surveillance and EU MDR Article 120 transition deadlines to calibrate portfolio investment and regulatory resource allocation.
Market Dynamics
EU MDR Article 120 transition deadlines are forcing cardiovascular device manufacturers to accelerate clinical evidence generation or exit European markets entirely, reshaping competitive viability across stent and pacemaker portfolios.
Growth Catalysts
- Bioresorbable polymer platforms:Scaffold technologies that dissolve post-vessel healing eliminate long-term implant complications and are capturing cath lab preference in Germany and Switzerland.
- FDA breakthrough device designation:Expedited review pathways for MRI-compatible pacing systems compress regulatory timelines and accelerate hospital procurement cycles.
- Japan PMDA reimbursement alignment:Revised fee schedules for transcatheter valve procedures expand addressable patient pools beyond surgical candidates.
Market Restraints
- Cobalt-chromium alloy supply concentration:Primary smelting capacity clusters in Chinese and Russian mining operations expose stent manufacturers to geopolitical input volatility.
- EU MDR notified body scarcity:Consolidated certification capacity extends conformity assessment timelines to 18-24 months for Class III implantable devices.
- Drug-eluting balloon substitution:Restenosis treatment alternatives with shorter dual antiplatelet therapy requirements threaten bare-metal and early-generation drug-eluting stent volumes.
Strategic Opportunities
- India CDSCO fast-track registration:Streamlined import licensing for CE-marked devices opens procedural volume in underpenetrated tier-2 hospital networks.
- Remote cardiac monitoring convergence:Integration of implantable loop recorders with cloud-based diagnostic platforms creates subscription revenue streams beyond device sale.
- US hospital vertical integration:Cath lab joint ventures between device manufacturers and integrated delivery networks secure exclusive supply agreements and procedure volume commitments.
Industry Challenges
- ISO 14155 clinical investigation expertise:Shortage of investigators trained in Good Clinical Practice standards for cardiovascular device trials delays study initiation across European sites.
- Legacy EMR interoperability:Implantable device data transmission protocols require costly middleware development to integrate with hospital information systems from Cerner and Epic.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cardiovascular Devices Market |
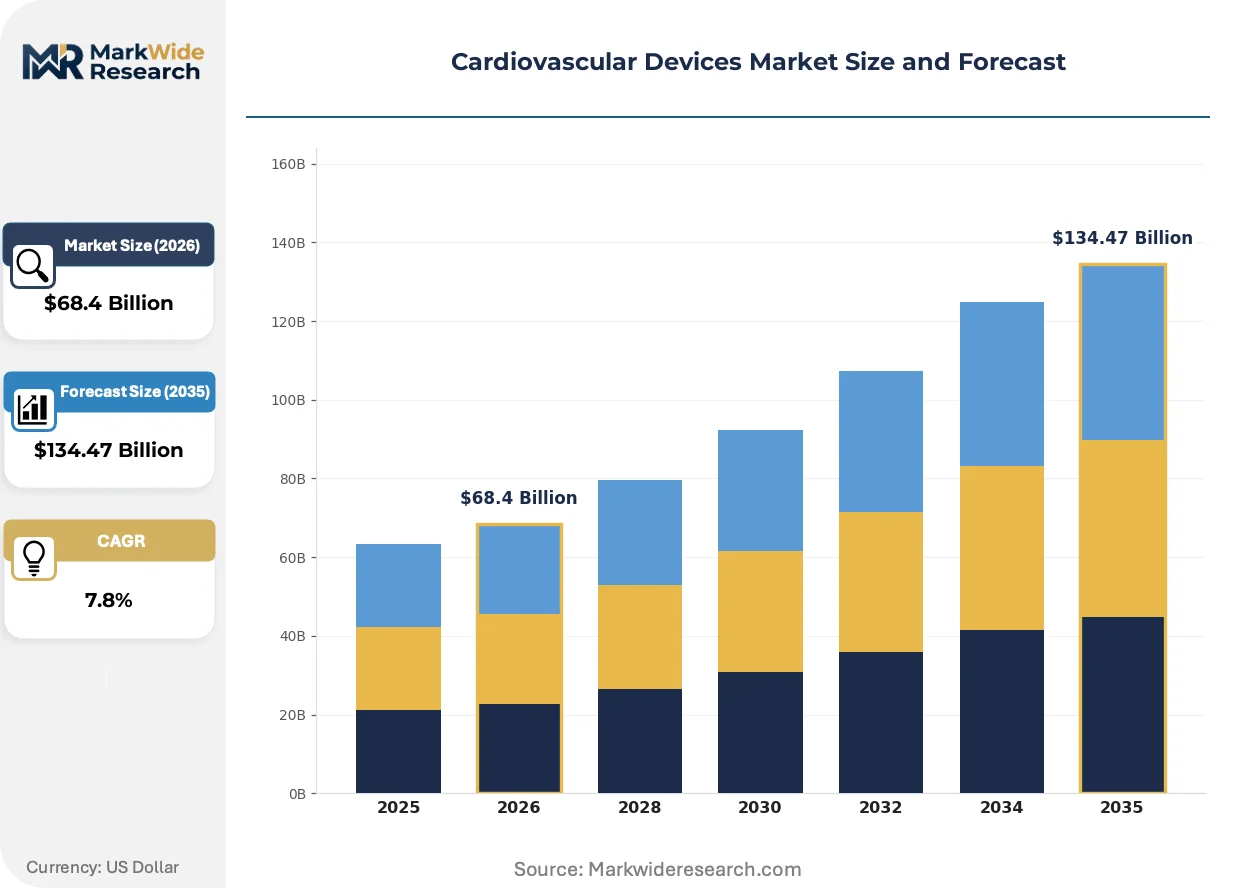
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $134.47 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Angioplasty Balloons, Pacemakers, Catheters End User: Hospitals, Clinics, Outpatient Surgical Centers, Cardiac Rehabilitation Centers Technology: Drug-Eluting Stents, Bio-absorbable Stents, MRI-Compatible Devices, Implantable Cardioverter Defibrillators Application: Coronary Artery Disease, Heart Valve Disease, Arrhythmia Management, Peripheral Vascular Disease |
| Companies Covered | GE HealthCare, Edwards Lifesciences Corporation, Medtronic, Terumo Corporation, Siemens Healthineers, Abbott Laboratories, Philips Healthcare, Biotronik, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cardiovascular Devices Market Emerging Trajectories
Digital twin modeling and AI-assisted procedural planning are compressing physician learning curves and expanding treatable anatomical complexity in interventional cardiology.
Nitinol shape-memory alloys with enhanced fatigue resistance are expanding into transcatheter structural heart applications previously dominated by stainless steel delivery systems. Academic medical centers in the US and Germany are adopting these platforms for mitral valve repair procedures at twice the pace of community hospitals. The technology is expanding into anatomically challenging patient subsets that device manufacturers previously excluded from trial enrollment.
EU MDR post-market clinical follow-up requirements are mandating 10-15 year patient registries for permanent implants, fundamentally altering trial design economics. Manufacturers must now budget for extended surveillance infrastructure before product launch. High-margin electrophysiology devices face the steepest compliance cost escalation as arrhythmia recurrence data collection extends through device lifecycle.
Hospital procurement committees are consolidating vendor relationships around full cath lab ecosystem suppliers rather than single-product negotiations. Integrated delivery networks in Texas and California are awarding sole-source contracts covering stents, guidewires, and diagnostic catheters to capture volume discounts. France and the Netherlands display similar concentration, with regional hospital groups centralizing cardiovascular device purchasing through cooperative procurement organizations.
Cardiovascular Devices Market Segmentation
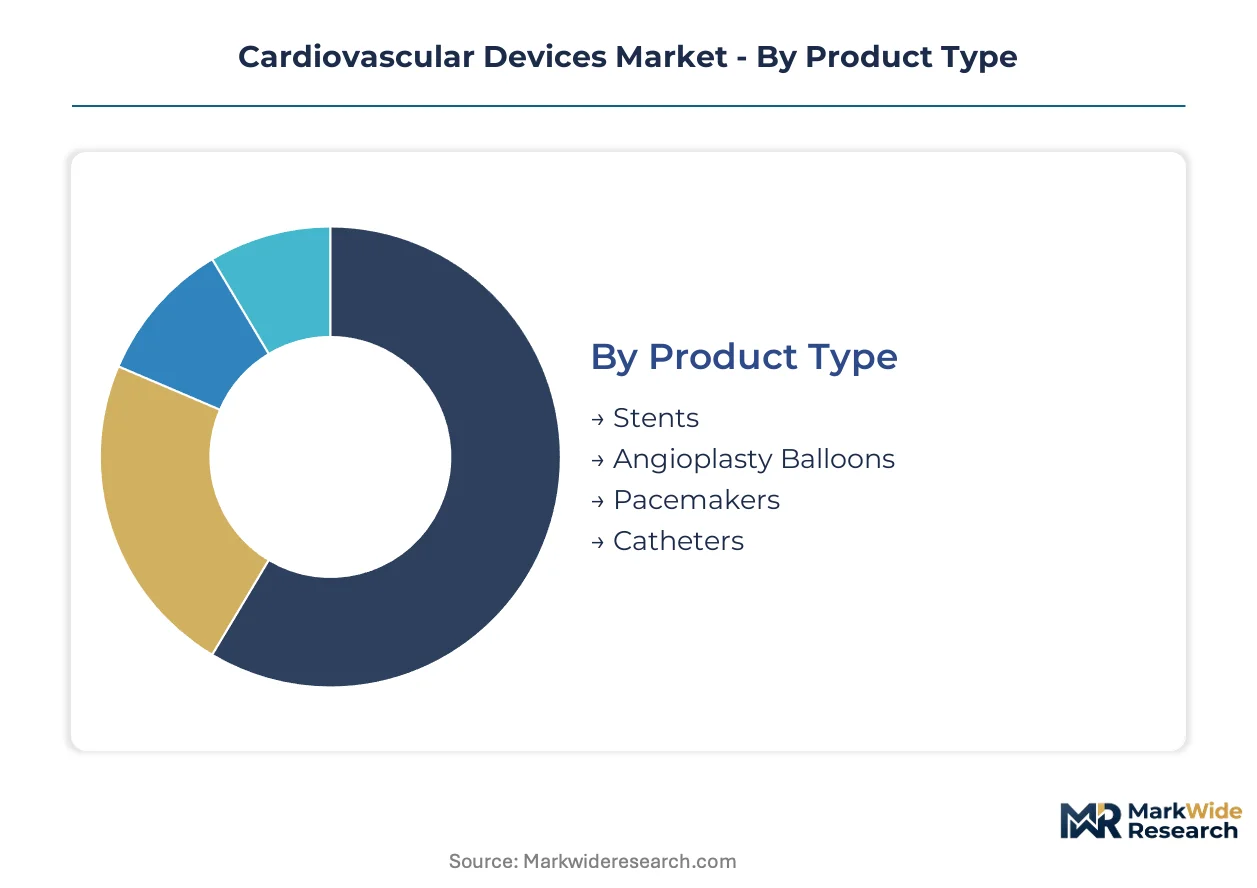
Segmentation in cardiovascular devices reveals distinct procurement patterns across product categories, with upgrade cycles varying dramatically between permanent implants and disposable interventional tools. Hospital capital budgets and reimbursement pathways create divergent demand profiles that manufacturers must navigate through specialized sales channels and evidence packages.
Product Type:
Replacement cycles differ sharply across implantable versus interventional categories, with permanent devices demanding decade-long clinical surveillance while disposable tools compete on per-procedure economics.
- Stents:Cobalt-chromium and platinum-chromium alloy platforms dominate coronary interventions, with drug-eluting variants commanding premium positioning in German and Swiss cath labs where restenosis reduction drives procurement decisions. Volume concentrates in acute myocardial infarction protocols across tertiary hospital networks.
- Angioplasty Balloons:Semi-compliant and non-compliant balloon catheters enable lesion preparation and vessel dilation, with scoring balloon technology gaining traction in calcified lesion subsets previously requiring rotational atherectomy. Demand clusters in high-throughput interventional cardiology departments.
- Pacemakers:Dual-chamber and leadless miniaturized systems address bradyarrhythmia management, with MRI-conditional models capturing preference as multimodal imaging protocols expand.
- Catheters:Diagnostic and guiding catheters compete on torque response and trackability metrics, with integrated delivery systems commanding margin premiums over commodity single-use variants.
Volume placements concentrate in Stents; the faster expansion belongs to MRI-Compatible Devices as health systems prioritize imaging compatibility without device explantation.
End User:
Procurement authority varies dramatically across facility types, with integrated delivery networks centralizing purchasing for hospital systems while outpatient operators prioritize disposable cost efficiency.
- Hospitals:Tertiary cardiac centers with 24/7 interventional capabilities anchor stent and pacemaker volumes, leveraging cath lab joint ventures to secure exclusive supply agreements and procedure volume commitments with manufacturers. These facilities command the deepest clinical evidence requirements and longest evaluation timelines.
- Clinics:Cardiology-focused ambulatory practices concentrate on diagnostic catheterization and stable patient monitoring, with reimbursement alignment determining technology adoption thresholds for advanced imaging integration.
- Outpatient Surgical Centers:Freestanding interventional facilities prioritize rapid turnover and disposable cost minimization, favoring pre-integrated procedure kits over component-level purchasing.
- Cardiac Rehabilitation Centers:Post-acute monitoring facilities drive demand for wearable and implantable loop recorders, with remote monitoring convergence creating subscription revenue opportunities beyond device sale.
Revenue concentration sits with Hospitals; Clinics are climbing the fastest as ambulatory payment reform shifts lower-acuity procedures from inpatient settings.
Technology:
Regulatory pathway complexity stratifies competitive positioning, with breakthrough designations compressing timelines for novel platforms while legacy technologies face intensifying generic substitution.
- Drug-Eluting Stents:Polymer-based and polymer-free limus-analog platforms suppress neointimal hyperplasia through controlled drug release, with biodegradable polymer variants addressing late stent thrombosis concerns in Japanese and European markets where extended dual antiplatelet therapy compliance varies.
- Bio-absorbable Stents:Magnesium and poly-l-lactide scaffolds dissolve post-vessel remodeling, eliminating permanent metal caging and capturing preference in younger patient cohorts with longer life expectancy in Germany and Switzerland.
- MRI-Compatible Devices:Non-ferromagnetic pacing leads and titanium-enclosed pulse generators enable safe magnetic resonance imaging, with conditional labeling expanding to full-body scan compatibility in latest-generation platforms.
- Implantable Cardioverter Defibrillators:Transvenous and subcutaneous systems deliver tiered therapy for sudden cardiac death prevention, with leadless extravascular configurations addressing extraction risk in long-dwelling implants.
Installed base dominance belongs to Drug-Eluting Stents; Bio-absorbable Stents are gaining share fastest as FDA tightens long-term safety surveillance requirements that favor established clinical evidence portfolios.
Application:
Procedure volume distribution reflects demographic disease burden and reimbursement accessibility, with coronary interventions maintaining volume leadership while structural heart applications expand treatable anatomical complexity.
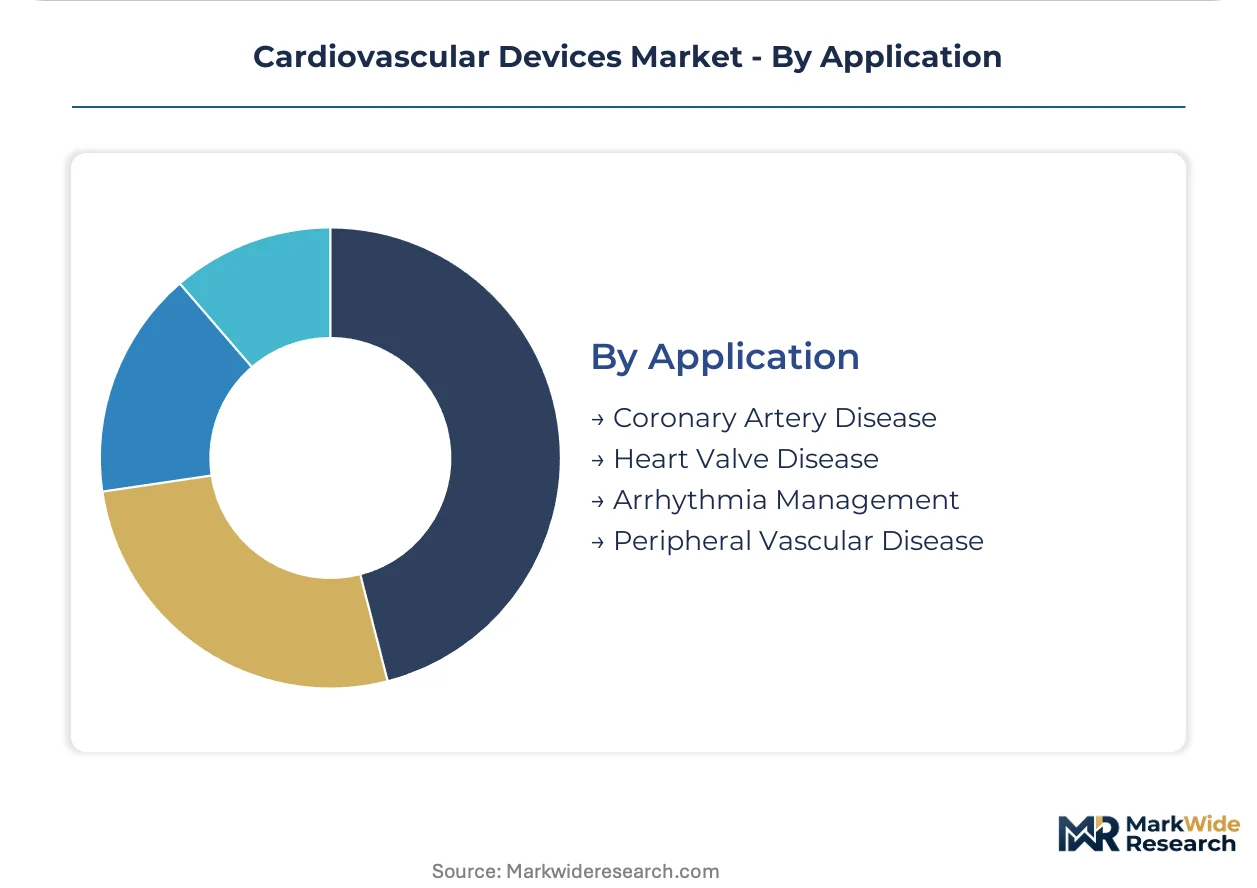
- Coronary Artery Disease:Percutaneous coronary intervention with stent deployment remains the dominant revascularization modality, with fractional flow reserve-guided decision protocols optimizing stent placement economics in US and German hospital systems.
- Heart Valve Disease:Transcatheter aortic and mitral valve replacement and repair procedures displace surgical candidates, with Japan PMDA reimbursement alignment expanding addressable patient pools beyond traditional surgical risk scores.
- Arrhythmia Management:Electrophysiology ablation and device-based rhythm control address atrial fibrillation and ventricular tachyarrhythmias, with pulsed field ablation emerging as a tissue-selective alternative to thermal energy delivery.
- Peripheral Vascular Disease:Lower extremity and renal artery interventions compete with surgical bypass and medical management, with drug-coated balloon substitution threatening bare-metal stent volumes in femoropopliteal segments.
Procedure volume concentrates in Coronary Artery Disease; the steepest expansion trajectory belongs to Heart Valve Disease as transcatheter platforms capture intermediate-risk surgical candidates previously excluded from interventional trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German hospital systems anchor cardiovascular device procurement volume, with Siemens Healthineers and Biotronik anchoring a precision manufacturing cluster that supplies cath labs across Western Europe. FDA and EU MDR regulatory pathways create divergent market access timelines that reshape competitive positioning across major commercial geographies.
United States
Hospital systems in Texas and California are consolidating vendor relationships around full cath lab ecosystem suppliers, awarding sole-source contracts that bundle stents, guidewires, and diagnostic catheters. FDA breakthrough device designation for MRI-compatible pacing systems compresses regulatory timelines and accelerates procurement cycles. The Greater Boston and Minneapolis-St. Paul corridors host dense clusters of electrophysiology device development and clinical trial infrastructure.
Germany
Reimbursement-aligned innovation in Baden-Württemberg and Bavaria drives preference for bioresorbable polymer platforms that eliminate long-term implant complications. EU MDR notified body scarcity extends conformity assessment timelines to 18-24 months for Class III implantable devices. Siemens Healthineers and Biotronik anchor a manufacturing concentration in Erlangen and Berlin that supplies precision stent and pacemaker platforms across European hospital networks.
Japan
PMDA reimbursement alignment for transcatheter valve procedures expands addressable patient pools beyond traditional surgical risk scores in Tokyo and Osaka metropolitan hospital systems. Revised fee schedules accelerate adoption of drug-eluting stent platforms with biodegradable polymer variants. The Kansai region hosts clinical investigation sites trained in ISO 14155 Good Clinical Practice standards for extended cardiovascular device surveillance.
Switzerland
Swissmedic oversight of permanent implants mandates rigorous clinical evidence portfolios that favor established manufacturers with extended surveillance infrastructure. Younger patient cohorts with longer life expectancy drive preference for bio-absorbable stent platforms that dissolve post-vessel remodeling. The Basel-Zurich corridor concentrates precision polymer processing capabilities for bioresorbable scaffold manufacturing.
India
CDSCO fast-track registration for CE-marked devices opens procedural volume in underpenetrated tier-2 hospital networks in Maharashtra and Gujarat. Import licensing streamlines accelerate cath lab modernization in Delhi-NCR and Bangalore metropolitan cardiac centers. Regional hospital groups in South India are centralizing cardiovascular device purchasing through cooperative procurement organizations to capture volume discounts on stent and balloon catheter platforms.
Cardiovascular Devices Market Vendor Landscape
German and Swiss producers anchor one tier of precision manufacturing; US specialists hold dominant positions in integrated delivery network contracting and cath lab channel control. The vendor base stratifies across full-ecosystem suppliers capable of sole-source hospital agreements and focused interventional tool manufacturers competing on per-procedure economics. Three archetypes dominate: diversified health technology conglomerates with regulatory infrastructure scale, interventional cardiology pure-plays with deep physician training relationships, and emerging platform developers targeting bio-absorbable and MRI-compatible niches. Competitive moves concentrate on cath lab joint ventures securing exclusive supply agreements and extended post-market clinical follow-up infrastructure for EU MDR compliance.
Among diversified health technology conglomerates, GE HealthCare, Siemens Healthineers, and Philips Healthcare exemplify the regulatory infrastructure scale archetype, occupying positions that span diagnostic imaging and interventional device portfolios. These entities represent the capital equipment integration tier where hospital procurement committees consolidate vendor relationships. Medtronic and Abbott Laboratories sit within the interventional cardiology pure-play category, anchoring competitive positioning through established European regulatory infrastructure and drug-eluting stent platform portfolios. Boston Scientific Corporation exemplifies deep cath lab channel control in reimbursed procedure markets, representing the physician training and procedure volume commitment archetype that secures exclusive supply agreements with integrated delivery networks.
| Leading Market Players |
|---|
| GE HealthCare |
| Edwards Lifesciences Corporation |
| Medtronic |
| Terumo Corporation |
| Siemens Healthineers |
| Abbott Laboratories |
| Philips Healthcare |
| Biotronik |
| Boston Scientific Corporation |
| Others |
Supply Flow & Price Mechanics
Polymer processing specialists in the Basel-Zurich corridor anchor labor-cost differentials that widen pricing-tier spreads between premium bioresorbable scaffolds and commodity balloon catheters. Swiss and German precision manufacturing clusters command wage premiums that manufacturers pass through to hospital procurement committees, while Asian assembly operations enable economy-tier positioning for high-volume disposable tools.
Pricing Analysis
Volume placements concentrate in bare-metal and early-generation drug-eluting stents where per-unit margins compress under drug-coated balloon substitution, while premium-tier pricing stratifies across biodegradable polymer platforms and MRI-conditional pacing systems that capture cath lab preference. Price differentiation hinges on CE-mark certification tier and cath lab joint venture exclusivity, with integrated delivery networks in Texas and California extracting volume discounts through sole-source contracts. Cost compression in commodity catheter tiers is intensifying because hospital procurement committees consolidate vendor relationships around full-ecosystem suppliers. Outpatient surgical centers display the highest price sensitivity, prioritizing pre-integrated procedure kits over component-level purchasing, whereas tertiary cardiac centers with 24/7 interventional capabilities accept premium positioning for extended surveillance infrastructure.
Supply Chain Analysis
Freight cost volatility from Chinese and Russian cobalt-chromium alloy smelting operations exposes stent manufacturers to geopolitical input volatility that reshapes inventory carrying strategies. Raw material dependencies center on nitinol shape-memory alloys, platinum-chromium feedstock, and bioresorbable polymer resins. Supply chain risk rests on single-source vulnerability for EU MDR notified body conformity assessments that extend certification timelines. Distribution runs through GPO contracts managers and hospital procurement committees that centralize cardiovascular device purchasing through cooperative procurement organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body scarcity creates a supply-constrained environment where extended conformity assessment timelines prop pricing power for established manufacturers with regulatory infrastructure scale.
For Market Incumbents: Lock in cath lab joint ventures with integrated delivery networks in Texas and California to secure exclusive supply agreements against drug-coated balloon substitution threats. Deepen backward integration into precision polymer processing capabilities in the Basel-Zurich corridor to defend margin position as bioresorbable scaffold demand accelerates. For New Entrants and Emerging Players: Launch via CDSCO fast-track registration pathways for CE-marked devices to capture procedural volume in underpenetrated tier-2 hospital networks in Maharashtra and Gujarat. Target remote cardiac monitoring convergence with cloud-based diagnostic platforms, the most penetrable white space, through subscription revenue models that extend beyond device sale economics. For Investors and Strategic Acquirers: Re-rating potential sits with interventional cardiology pure-plays with deep physician training relationships given FDA breakthrough device designation acceleration for MRI-compatible platforms. Long-term viability favors manufacturers with extended post-market clinical follow-up infrastructure already deployed for EU MDR Article 120 compliance. Watch PMDA reimbursement alignment signals for transcatheter valve procedures as the inflection indicator for structural heart expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body engagement secures 18-24 month conformity assessment timelines for Class III implants. |
| Hospital System Partnership | Cath lab joint ventures with integrated delivery networks lock in exclusive supply agreements and procedure volume. |
| Reimbursement Strategy | PMDA fee schedule alignment in Japan expands transcatheter valve addressable pools beyond surgical candidates. |
| Software Companion Development | Cloud-based diagnostic platforms for implantable loop recorders create subscription revenue beyond device sale. |
| FDA Submission | Breakthrough device designation for MRI-compatible pacing systems compresses regulatory timelines and accelerates procurement. |
Methodological Framework
FDA 510(k) filings, EU MDR notified body conformity assessments, and hospital procurement databases formed the secondary backbone, supplemented by primary interviews with cath lab directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads at cardiovascular device manufacturers. Bottom-up segmentation modeling across stent platforms, pacing systems, and interventional catheters was cross-validated through top-down triangulation against CMS Medicare procedure volume data and Japanese PMDA reimbursement fee schedules.
Historical trendline analysis of coronary intervention volumes, structural heart procedure adoption curves, and electrophysiology device replacement cycles informed the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end-user facility tier, technology platform, and application-specific reimbursement pathway. CAGRs were derived through regression analysis of procedural volume growth against capital equipment installation rates and physician training pipeline expansion.
EU MDR Article 120 transition deadline delays, FDA guidance revisions on bio-absorbable stent surveillance, and cobalt-chromium alloy supply disruptions are the dominant revision risks. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Global Intravascular Temperature Management Market
Cardiovascular Devices
Intravascular Stents Market
Cardiovascular Devices
Cardiovascular OCT Imaging Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Centrifugal Blood Pumps Market
Cardiovascular Devices
India Coronary Stent Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Self-Expanding Stents Market
Cardiovascular Devices
Implantable Infusion Pumps Market
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Global Angio Suites Market
Cardiovascular Devices
Peripheral Intravenous Catheters Market
Cardiovascular Devices
Cardiovascular and Soft Tissue Repair Patches Market
Cardiovascular Devices
North America Vascular Graft Market
Cardiovascular Devices
Global Coronary Stent Market
Cardiovascular Devices
Cardiac Ablation Market