
 Wearable Cardiac Devices Market | 2026-2036
Wearable Cardiac Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Wearable Cardiac Devices Market Analysis
Subscription-based leasing for remote cardiac monitoring hardware is tilting competitive dynamics toward asset-light service providers. Medtronic plc leverages its vertically integrated manufacturing network to sustain hardware margins across hospital and home settings. iRhythm Technologies Inc. anchors its position through proprietary patch-based ECG diagnostics and specialized reimbursement expertise. AliveCor Inc. differentiates via direct-to-consumer channel control and FDA-cleared smartphone-connected ECG technology.
Wearable cardiac devices combine miniaturized biosensors, conductive electrodes, and wireless transmission modules to capture electrophysiological signals during daily activity for arrhythmia detection and heart failure surveillance. Smartwatches and ECG monitor patches command the highest margin pools due to recurring data service revenue and clinical-grade diagnostic claims respectively. Fitness trackers occupy a commoditized tier where optical heart rate sensors face price pressure from consumer electronics giants. Bluetooth and biometrics technologies are reshaping interoperability demands as health systems integrate streaming cardiac data into electronic medical records.
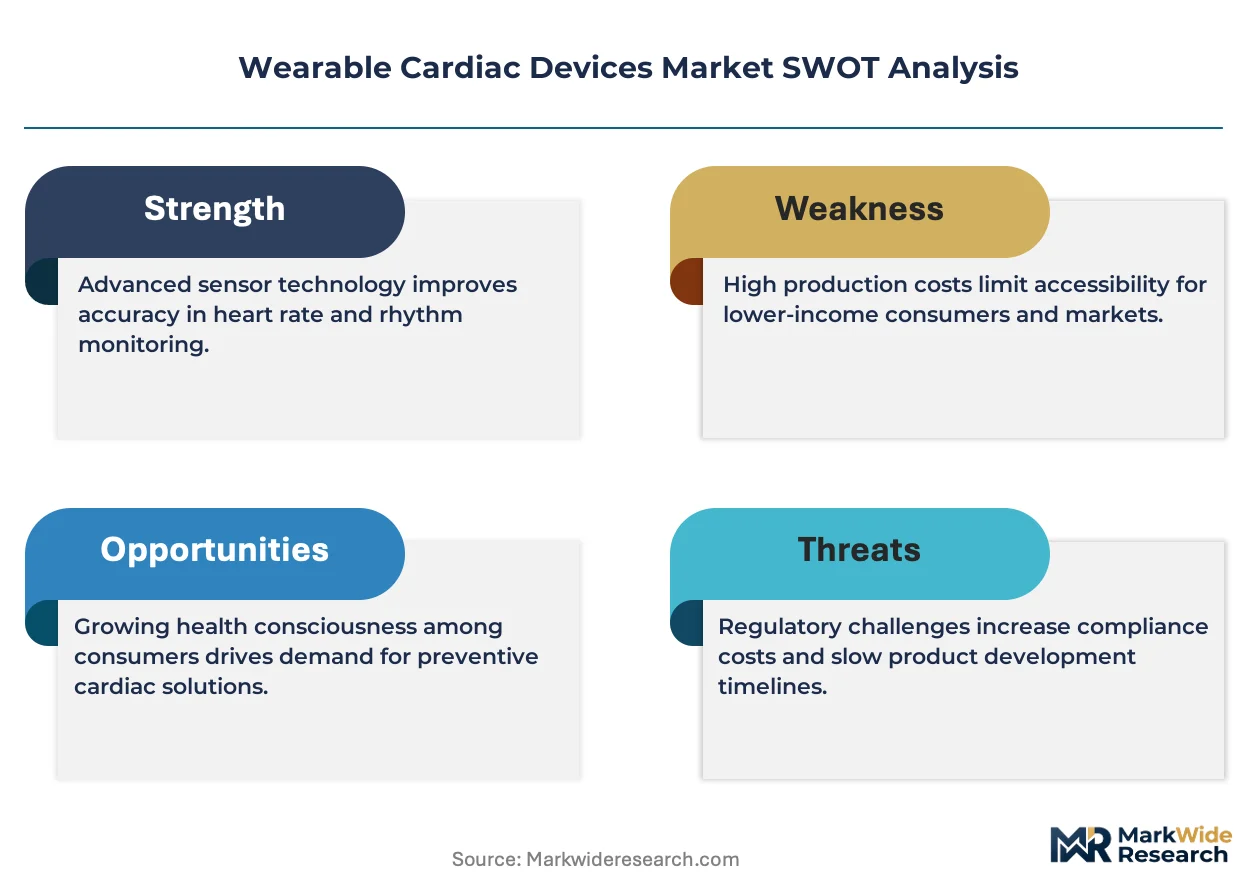
FDA premarket review under 510(k) and De Novo pathways governs diagnostic claims for ECG-enabled wearables in the United States, while the EU Medical Device Regulation enforces post-market surveillance and clinical evidence standards across European markets. HIPAA compliance requirements constrain how US healthcare providers share streaming cardiac data with third-party analytics platforms. Stakeholders must monitor evolving FDA guidance on artificial intelligence-based arrhythmia detection algorithms and corresponding payer coverage determinations for autonomous diagnostic interpretations.
Market Dynamics
Subscription-based hardware leasing is concentrating purchasing power among asset-light remote monitoring service providers, compressing traditional device ownership models and rewiring vendor-customer relationships across hospital and home care settings.
Growth Catalysts
- Medicare reimbursement infrastructure:The Centers for Medicare & Medicaid Services has established sustainable payment codes for remote cardiac monitoring, creating predictable revenue streams for ambulatory care centers and home health agencies.
- AI-enabled diagnostic algorithms:Machine learning models trained on ambulatory ECG datasets are reducing false-positive arrhythmia alerts and accelerating clinical workflow integration in cardiology practices.
- Hospital-at-home expansion:Acute care systems in the United States are deploying patch-based monitors to substitute inpatient telemetry beds, driving hardware procurement for post-discharge surveillance programs.
Market Restraints
- Conductive electrode supply concentration:Silver-silver chloride electrode manufacturing clusters in East Asia create single-source vulnerability for disposable patch producers facing logistics disruptions.
- FDA premarket review timelines:De Novo pathway submissions for novel ECG form factors average 18-24 months, delaying revenue recognition for algorithm-first entrants lacking predicate devices.
- Optical heart rate commoditization:Consumer electronics manufacturers with captive photoplethysmography sensor supply are compressing pricing for fitness-tier wearables below sustainable hardware margins.
Strategic Opportunities
- Underpenetrated rural Medicare populations:Federally qualified health centers in the Southeastern United States lack systematic remote monitoring deployment, representing white-space demand for turnkey service models.
- EU Medical Device Regulation harmonization:MDR Article 120 transitional provisions are creating temporary competitive windows for notified body-certified patch manufacturers ahead of full IVDR enforcement.
- Continuous glucose-cardiac convergence:Integration of ECG and CGM data streams into unified metabolic-cardiovascular dashboards is opening new reimbursement conversations with integrated payer-providers.
Industry Challenges
- Electrophysiologist workforce scarcity:Fellowship-trained arrhythmia specialists are concentrated in academic medical centers, creating interpretation bottlenecks for high-volume remote monitoring services.
- Legacy EMR integration complexity:Proprietary data formats from wearable ECG devices require expensive middleware development to achieve seamless HL7 FHIR connectivity with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wearable Cardiac Devices Market |
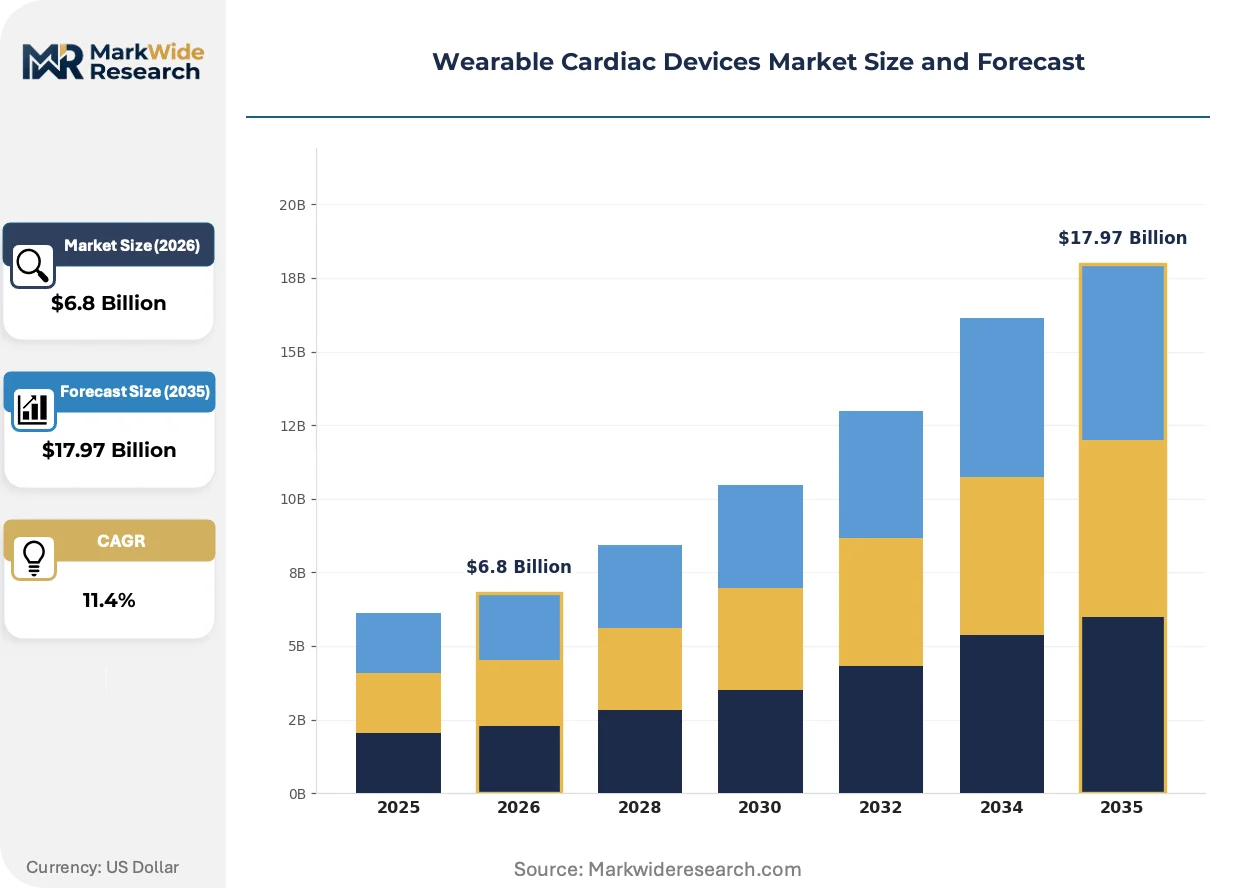
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Smartwatches, ECG Monitors, Fitness Trackers, Patches Technology: Biometrics, Optical Sensors, ECG Technology, Bluetooth End User: Patients, Healthcare Providers, Clinical Researchers, Fitness Enthusiasts Application: Monitoring, Diagnostics, Fitness Tracking, Telehealth |
| Companies Covered | Apple Inc., Fitbit Inc., Garmin Ltd., Medtronic plc, Philips, BioTelemetry Inc., iRhythm Technologies Inc., AliveCor Inc., ZOLL Medical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wearable Cardiac Devices Market Emerging Trajectories
Dry electrode technologies and ambient power harvesting are eliminating disposable consumables from cardiac monitoring workflows, while regulatory frameworks coalesce around autonomous diagnostic claims for algorithm-interpreted ECG data.
Photoplethysmography signal processing is migrating from consumer fitness applications into clinical-grade atrial fibrillation screening through advanced motion artifact rejection algorithms. Cardiology outpatient departments are piloting smartwatch-based rhythm monitoring for post-ablation surveillance, replacing Holter monitors for selected low-risk cohorts. Hardware margin compression in the fitness tier is forcing component suppliers to seek premium positioning through FDA 510(k) clearance for specific arrhythmia detection claims.
The EU Medical Device Regulation is enforcing post-market clinical follow-up requirements for ECG-enabled wearables marketed with diagnostic claims, mandating systematic safety and performance data collection across notified body jurisdictions. Manufacturers must maintain post-market surveillance systems capable of detecting rare adverse events in distributed home-use populations. German and French competent authorities are prioritizing review resources for AI-based diagnostic modules, creating regulatory velocity advantages for algorithm-native entrants over legacy hardware vendors.
Health system procurement departments are consolidating vendor relationships through enterprise-wide remote monitoring contracts that bundle hardware, data interpretation services, and EMR integration. Independent cardiology practices are losing negotiating leverage as integrated delivery networks centralize purchasing decisions for cardiac diagnostic services. This concentration is most pronounced in the United States, where Medicare Advantage plans are steering members toward contracted monitoring platforms with guaranteed turnaround times for clinical event notifications.
Wearable Cardiac Devices Market Segmentation
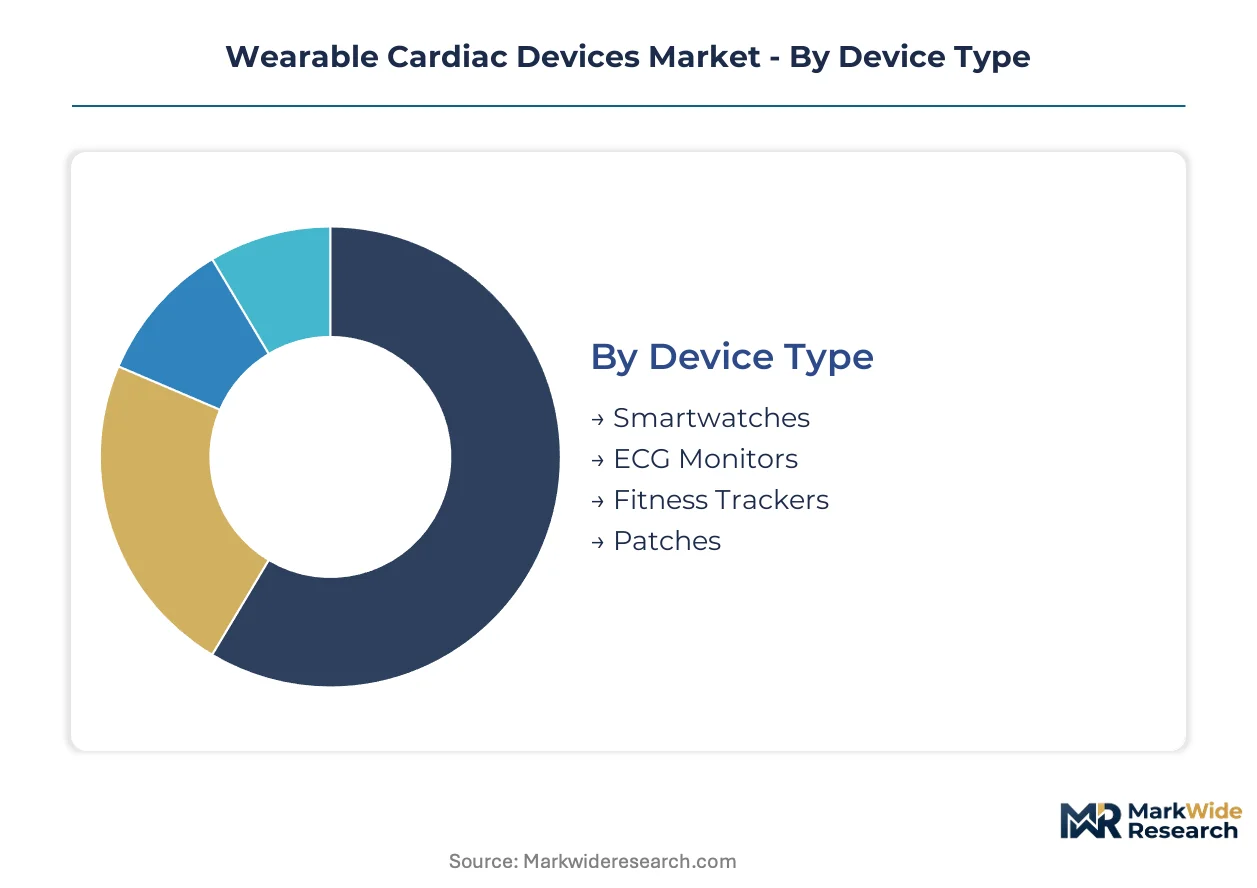
Wearable cardiac devices fragment across four intersecting dimensions that determine procurement patterns, reimbursement pathways, and hardware refresh cycles. Device type and technology choices drive margin structures, while end user and application segments dictate regulatory classification and channel strategy.
Device Type:
Patch-based monitors turn over fastest through disposable electrode consumption, while smartwatches cycle slowest through multi-year consumer replacement patterns.
- Smartwatches:Multi-sensor wrist-worn platforms integrate ECG electrodes with photoplethysmography for atrial fibrillation screening and heart rate variability tracking. Demand concentrates among Medicare Advantage plans in the United States seeking member engagement tools with guaranteed clinical event notification turnaround times.
- ECG Monitors:Dedicated handheld or chest-worn devices capture single-lead to twelve-lead electrocardiograms with diagnostic-grade signal quality. Hospital-at-home programs in the United States substitute these for inpatient telemetry beds, driving procurement for post-discharge surveillance.
- Fitness Trackers:Consumer-grade wristbands with optical heart rate sensors face commoditization pressure from electronics manufacturers with captive photoplethysmography supply.
- Patches:Disposable adhesive electrodes with integrated biosensors enable continuous ambulatory monitoring through multi-day wear periods.
ECG Monitors dominate installed base in clinical settings. Patches are where expansion concentrates for remote patient monitoring programs.
Technology:
Cost tiers separate proprietary ECG acquisition circuits from commodity Bluetooth radio modules and optical sensor packages.
- Biometrics:Multi-modal physiological signal fusion combines electrocardiography with impedance cardiography and accelerometry for comprehensive cardiovascular assessment. Integrated delivery networks in the United States bundle biometric-enabled platforms into enterprise-wide remote monitoring contracts.
- Optical Sensors:Photoplethysmography modules using green or infrared LEDs detect blood volume changes for heart rate estimation. Consumer electronics supply chain concentration in East Asia compresses pricing below sustainable margins for standalone fitness-tier vendors.
- ECG Technology:Analog front-end circuits with noise cancellation and motion artifact rejection enable clinical-grade arrhythmia detection.
- Bluetooth:Low-energy wireless protocols transmit encrypted physiological data to paired smartphones or dedicated gateways.
ECG Technology commands premium positioning through FDA 510(k) clearance requirements. Biometrics is climbing the fastest as health systems demand unified metabolic-cardiovascular dashboards.
End User:
Customer type determines regulatory burden and reimbursement pathway complexity across the purchase journey.
- Patients:Direct-to-consumer purchasers seek smartphone-connected ECG devices for self-directed arrhythmia screening without clinical supervision. Federally qualified health centers in the Southeastern United States lack systematic deployment, representing white-space demand for turnkey service models.
- Healthcare Providers:Cardiology practices and hospital systems require FDA-cleared devices with HL7 FHIR connectivity for electronic medical record integration. Legacy proprietary data formats force expensive middleware development.
- Clinical Researchers:Academic medical centers and contract research organizations deploy wearable ECG for decentralized clinical trials and real-world evidence generation.
- Fitness Enthusiasts:Performance-oriented consumers prioritize optical heart rate accuracy during high-intensity training over diagnostic claims.
Healthcare Providers dominate procurement volume through centralized purchasing. Patients are gaining share fastest as direct-to-consumer channels bypass traditional distribution.
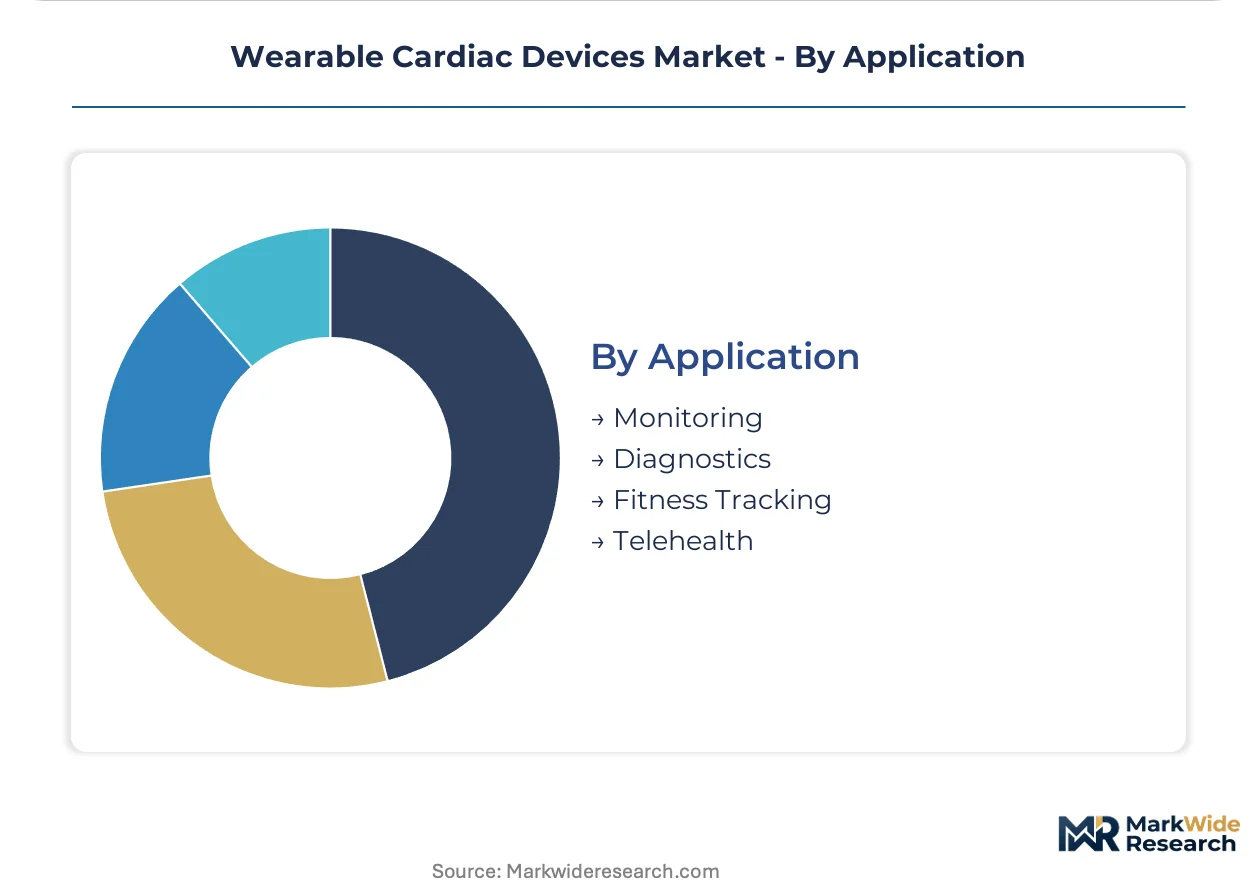
Application:
Maturity curves separate established diagnostic workflows from emerging telehealth reimbursement categories.
- Monitoring:Continuous or intermittent surveillance for arrhythmia recurrence, heart failure decompensation, or post-ablation recovery. Medicare reimbursement infrastructure in the United States creates predictable revenue streams for ambulatory care centers.
- Diagnostics:Acute symptom evaluation and screening for atrial fibrillation, bradycardia, or conduction abnormalities. FDA De Novo pathway timelines averaging 18-24 months delay revenue recognition for novel form factors.
- Fitness Tracking:Performance optimization and wellness-oriented heart rate zone management without clinical claims.
- Telehealth:Remote clinical encounters supported by streaming cardiac data and algorithm-interpreted ECG findings.
Monitoring anchors current reimbursement. Telehealth represents the steepest expansion trajectory as autonomous diagnostic claims for AI-interpreted ECG data gain regulatory acceptance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in wearable cardiac devices tilt toward net importing positions in European and Asian markets, while the United States maintains domestic manufacturing capacity for FDA-cleared diagnostic hardware. Trade flows concentrate disposable electrode components from East Asian suppliers toward North American and European assembly operations.
United States
Medicare reimbursement codes for remote cardiac monitoring sustain procurement volumes from hospital-at-home programs and ambulatory care centers. FDA 510(k) and De Novo pathways govern diagnostic claims for ECG-enabled wearables, with AI-based arrhythmia detection algorithms gaining accelerated review designations. The Minneapolis-St. Paul corridor hosts concentrated manufacturing operations for patch-based monitors serving integrated delivery networks.
Germany
Statutory health insurance reimbursement for telecardiology services drives adoption of prescription-grade wearable ECG devices in outpatient cardiology practices. EU Medical Device Regulation post-market surveillance requirements enforce clinical evidence standards for diagnostic claims, with notified body certification creating compliance barriers for non-EU manufacturers. The Baden-Württemberg region clusters precision electronics manufacturing for biosensor modules supplying patch producers.
China
Domestic demand for consumer-grade heart rate monitoring devices absorbs substantial optical sensor production from captive supply chains. NMPA regulatory pathways for Class II medical devices require in-country clinical trials for ECG diagnostic claims, extending time-to-market for foreign entrants. Shenzhen's electronics manufacturing ecosystem produces Bluetooth transmission modules and miniaturized electrodes for export-oriented device assemblers.
Japan
Aging demographics and government-promoted home healthcare initiatives expand reimbursement-eligible remote cardiac monitoring for post-discharge patients. PMDA consultation procedures for software as a medical device streamline approval pathways for AI-interpreted ECG algorithms. The Kansai region hosts specialized component suppliers for dry electrode technologies eliminating disposable consumables.
United Kingdom
NHS Long Term Plan commitments to digital-first cardiology services accelerate procurement of patch-based monitors for community-based arrhythmia detection. MHRA recognition of FDA and EU MDR approvals facilitates parallel market entry for multinational device manufacturers. The Oxford-Cambridge arc concentrates health technology assessment expertise influencing NICE coverage determinations for wearable diagnostics.
Wearable Cardiac Devices Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive electrode production and asset-light service providers leasing hardware through subscription models. Strategic archetypes include diversified medical technology conglomerates with hospital system relationships, specialized cardiac monitoring pure-plays with reimbursement expertise, and consumer electronics entrants leveraging optical sensor scale. Dominant competitive moves encompass enterprise-wide remote monitoring contract consolidation and FDA clearance acquisition for autonomous diagnostic algorithms.
Within the diversified medical technology tier, Medtronic plc and Philips occupy positions anchored by hospital procurement channel control and integrated service bundling. Among specialized cardiac monitoring providers, iRhythm Technologies Inc. and AliveCor Inc. exemplify contrasting channel strategies— institutional reimbursement optimization versus direct-to-consumer regulatory clearance. ZOLL Medical Corporation represents the emergency care equipment specialist archetype extending into ambulatory monitoring workflows.
| Leading Market Players |
|---|
| Apple Inc. |
| Fitbit Inc. |
| Garmin Ltd. |
| Medtronic plc |
| Philips |
| BioTelemetry Inc. |
| iRhythm Technologies Inc. |
| AliveCor Inc. |
| ZOLL Medical Corporation |
| Others |
Supply Flow & Price Mechanics
Shenzhen's electronics manufacturing ecosystem concentrates Bluetooth transmission module and miniaturized electrode capacity, translating upstream component availability into downstream pricing power for patch-based monitor assemblers. Disposable silver-silver chloride electrode supply from East Asian suppliers feeds directly into hardware leasing economics for remote monitoring service providers.
Pricing Analysis
Healthcare provider buyers anchor subscription-based hardware leasing as the dominant pricing structure, with FDA 510(k) certification tier and volume scale driving price differentiation between clinical-grade and consumer-tier devices. Pricing pressure stems from optical heart rate commoditization by electronics manufacturers with captive photoplethysmography supply. Fitness tracker purchasers exhibit highest price sensitivity, while integrated delivery networks negotiating enterprise-wide remote monitoring contracts demonstrate lowest sensitivity due to bundled service value.
Supply Chain Analysis
Extended payment terms from East Asian component suppliers finance working capital for device assemblers facing hospital procurement cycle delays. Manufacturing concentrates in China, South Korea, and Taiwan for biosensor modules, conductive electrodes, and wireless transmission components. Supply chains rest on silver-silver chloride electrode feedstocks and analog front-end semiconductors. Single-source vulnerability in East Asian electrode manufacturing creates structural risk. Distribution runs through medical device distributors and direct-to-consumer e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates opportunity as hospital-at-home expansion and AI-enabled diagnostic algorithms fragment demand across specialized service models and algorithm-native entrants.
For Market Incumbents: Harden hospital procurement channel control through HL7 FHIR connectivity investments that lock in electronic medical record integration. Deepen backward integration into disposable electrode manufacturing to offset East Asian supply concentration. Defend against algorithm-first entrants by accelerating FDA premarket review timelines for autonomous diagnostic claims.
For New Entrants and Emerging Players: Pursue federally qualified health centers in the Southeastern United States as the most penetrable segment, where systematic remote monitoring deployment remains absent. Target direct-to-consumer channels with smartphone-connected ECG devices bypassing traditional distribution. Lead with FDA-cleared atrial fibrillation screening as the go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among asset-light remote monitoring service providers with subscription-based hardware leasing models. Five-to-ten year viability favors algorithm-native entrants over legacy hardware vendors facing margin compression. Watch FDA guidance on artificial intelligence-based arrhythmia detection as the inflection signal for autonomous diagnostic reimbursement.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Shortens time-to-market for ECG-enabled wearables seeking diagnostic claims in the United States. |
| Hospital System Partnership | Secures enterprise-wide remote monitoring contracts bundling hardware, data services, and EMR integration. |
| Reimbursement Strategy | Aligns Medicare Advantage plan contracting with guaranteed clinical event notification turnaround times. |
| Software Companion Development | Enables AI-interpreted ECG algorithms to gain autonomous diagnostic claims alongside hardware. |
| CE Marking Pathway | Unlocks EU Medical Device Regulation compliance for patch manufacturers ahead of full IVDR enforcement. |
Methodological Framework
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committees, GPO contracts managers, and cardiology practice administrators and secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and EU Medical Device Regulation notified body certifications anchors the qualitative findings. Bottom-up demand modeling from device shipment data and top-down macroeconomic calibration ensure triangulation across the analysis window.
Calibration against historical Medicare reimbursement code adoption rates and FDA clearance timeline distributions shapes the forecast framework. The analytical framework models device type, technology tier, end user category, and application maturity across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs include electrophysiologist workforce availability and AI algorithm regulatory velocity.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement policy, FDA premarket review resource allocation, or silver commodity pricing would shift the trajectory. Forecasts reflect documented assumptions about regulatory pathway efficiency and payer coverage determination timing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Transcatheter Aortic Valve Replacement Market
Cardiovascular Devices
Japan Cardiovascular Devices Market
Cardiovascular Devices
Peripheral Vascular Stents Market
Cardiovascular Devices
Chronic Total Occlusion Catheter Market
Cardiovascular Devices
Arteriotomy Closure Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Intravascular Ultrasound (IVUS) System Market
Cardiovascular Devices
Latin America Compression Therapy Market
Cardiovascular Devices
Brazil Cardiovascular Devices Market
Cardiovascular Devices
Neuroendovascular Coil Market
Cardiovascular Devices
Pressure Infusion Bags Market
Cardiovascular Devices
Arterial Stabilization Device Market
Cardiovascular Devices
Normal Balloon Catheter Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
Pulmonary Artery Catheter Market