
 South Africa Cardiovascular Devices Market | 2026-2036
South Africa Cardiovascular Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Cardiovascular Devices Market Analytics
Minimally invasive catheter-based intervention is rewriting clinical workflows across South African cardiac centers, shifting volume away from open-chest procedures toward transcatheter alternatives. Medtronic PLC leverages its broad structural heart portfolio to anchor premium device segments in private hospital networks. Boston Scientific Corporation competes through specialized coronary stent platforms optimized for complex lesion anatomy. Abbott Laboratories differentiates via electrical rhythm management systems that sustain recurring generator replacement revenue.
Cardiovascular devices encompass implantable and non-implantable instruments engineered for cardiac diagnosis, intervention, or long-term management, with biocompatible alloys and polymer coatings typically specified for blood-contacting surfaces exceeding 30-day dwell times. Coronary stent deployment dominates procedural volume given South Africa's elevated ischemic heart disease burden, while bioabsorbable scaffold technology commands concentrated R&D investment despite slower clinical uptake. Catheter-based delivery systems capture expanding share as cardiac centers adopt hybrid operating room configurations that blend surgical and interventional capabilities under single anesthesia events.
SAHPRA governs device registration through risk-based classification pathways that mandate local clinical evidence for Class III and active implantable devices, extending approval cycles relative to CE-marked reference timelines. The South African Bureau of Standards (SABS) administers electrical safety and electromagnetic compatibility testing protocols that constrain import sourcing to certified manufacturing facilities. Stakeholders must monitor pending amendments to the National Health Insurance procurement framework, which will reshape reimbursement thresholds and channel preference between public and private delivery settings.
Market Dynamics
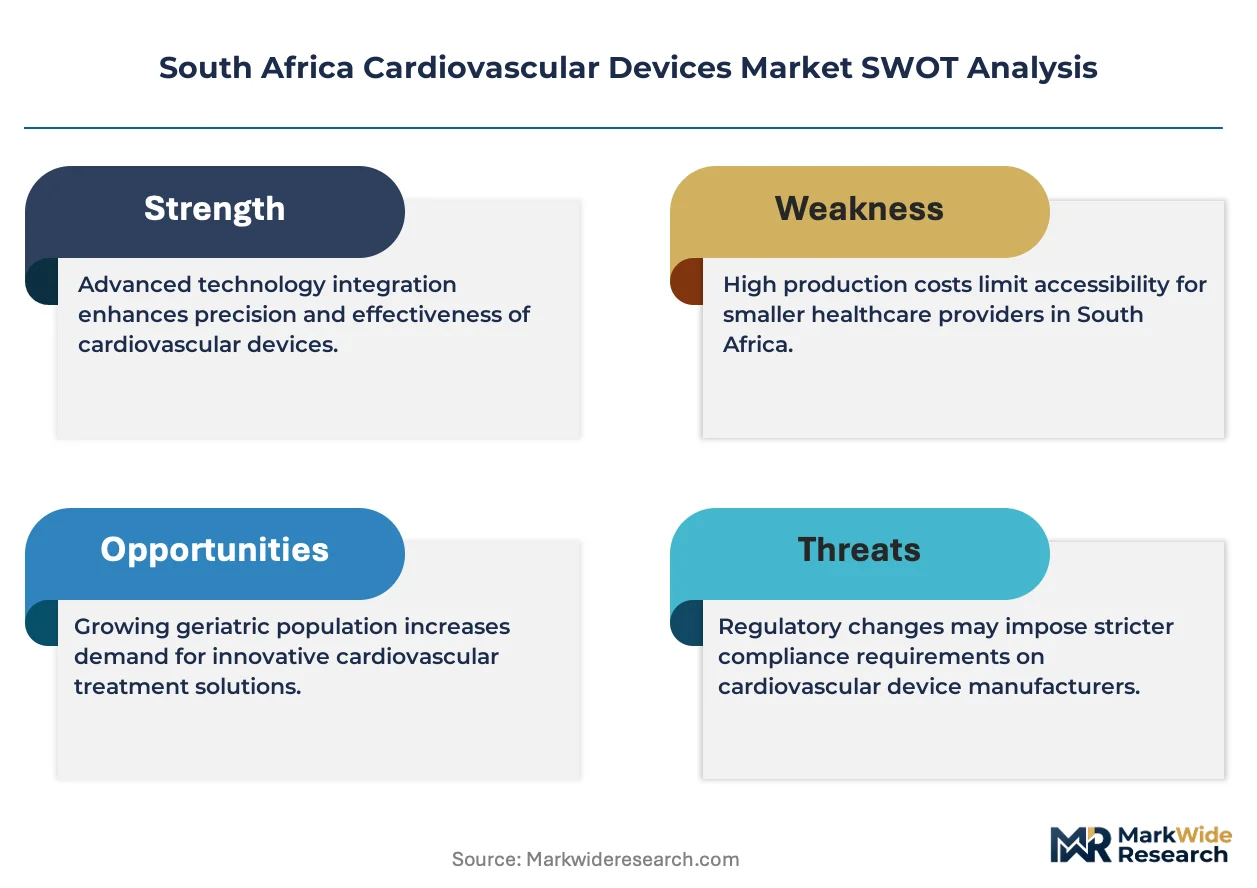
SAHPRA's compressed pre-market approval timelines for Class III implantables are compressing go-to-market cycles and forcing manufacturers to front-load clinical evidence generation, fundamentally restructuring how cardiac device portfolios enter South African hospital networks.
Growth Catalysts
- National Health Insurance procurement framework:Pending amendments will expand public sector reimbursement pools, unlocking catheterization laboratory investments across Eastern Cape and Limpopo provinces previously dependent on out-of-pocket private expenditure.
- Hybrid operating room configurations:Cardiac centers in Gauteng are blending surgical and interventional capabilities under single anesthesia events, driving demand for catheter-based delivery systems that reduce procedure time and ICU occupancy.
- Structural heart disease burden:Rheumatic heart disease prevalence in KwaZulu-Natal sustains demand for transcatheter valve interventions as surgical capacity constraints limit open-chest alternatives.
Market Restraints
- Platinum-iridium alloy sourcing:Electrode and lead manufacturers face concentrated supply from South African mining operations, exposing pacemaker and ICD producers to rand-denominated input volatility.
- SAHPRA local clinical evidence mandate:Risk-based classification pathways for active implantables extend approval cycles relative to CE-marked reference timelines, delaying product launches by 18-24 months against European benchmarks.
- Bioresorbable scaffold limitations:Restenosis rates and deliverability constraints in complex coronary anatomy have constrained uptake despite intensive R&D investment, preserving metallic platform dominance.
Strategic Opportunities
- Western Cape catheterization laboratory deficit:Cape Town's public health infrastructure operates below national average interventional capacity per capita, creating whitespace for mobile cath lab deployments and public-private partnership models.
- Electromagnetic compatibility certification streamlining:SABS-administered testing protocols that constrain import sourcing present first-mover advantage for manufacturers establishing certified local manufacturing or assembly facilities.
- Generator replacement revenue capture:Electrical rhythm management systems with predictable 7-10 year battery depletion cycles create recurring revenue streams that offset upfront device margin pressure in price-sensitive procurement environments.
Industry Challenges
- Interventional cardiologist training pipeline:Fellowship positions and simulation-based credentialing programs lag procedural volume growth, creating bottlenecks for transcatheter valve and complex PCI program expansion.
- SAHPRA compliance documentation:Biocompatibility testing and sterilization validation requirements for blood-contacting surfaces exceeding 30-day dwell times demand specialized regulatory affairs capacity that mid-tier manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Cardiovascular Devices Market |
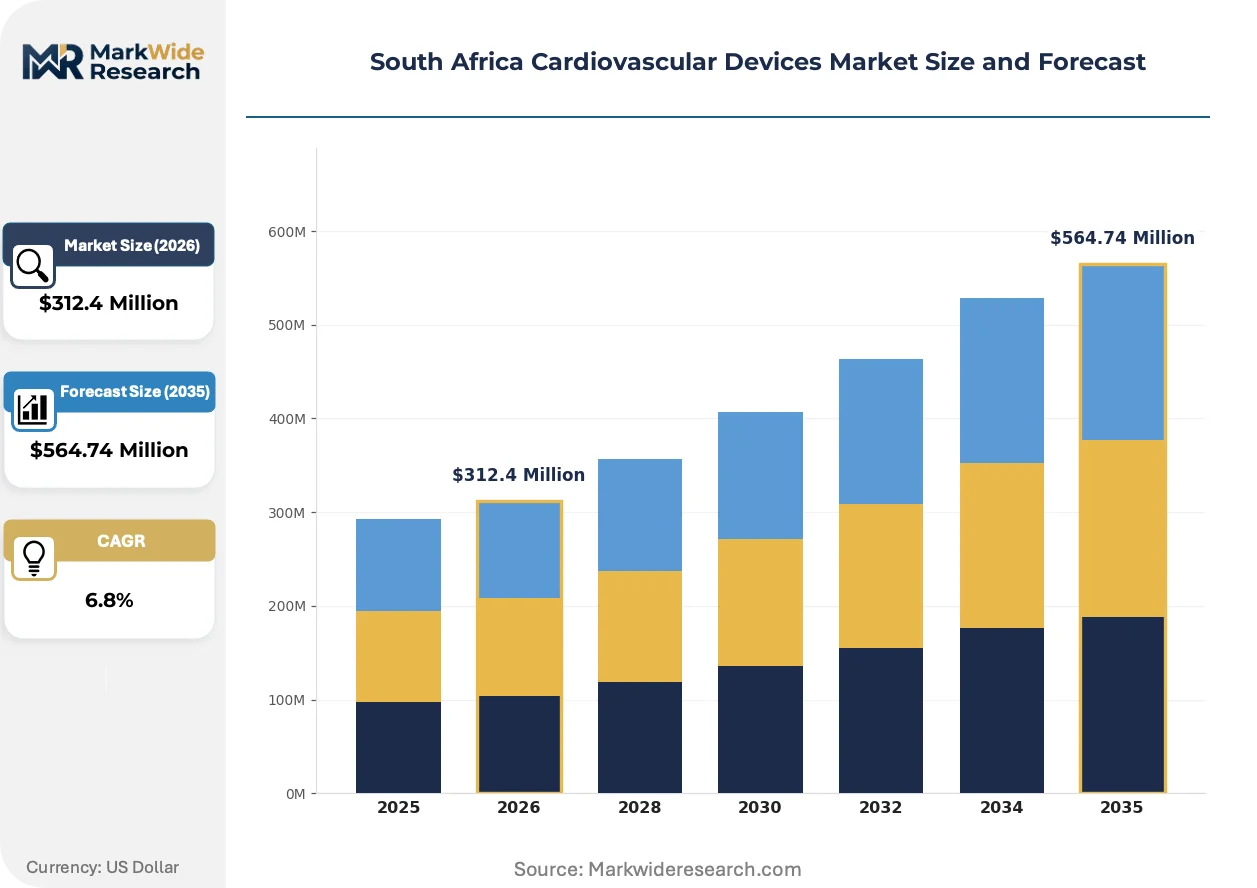
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Pacemakers, Valves, Catheters End User: Hospitals, Outpatient Clinics, Cardiac Centers, Laboratories Technology: Minimally Invasive, Bioabsorbable, Mechanical, Electrical Application: Coronary Artery Disease, Heart Failure, Arrhythmia, Hypertension |
| Companies Covered | Edwards Lifesciences, GE Healthcare, Abbott Laboratories, Canon Medical Systems Corporation, Siemens AG, Boston Scientific Corporation, Cardinal Health, Inc., W. L. Gore & Associates, Medtronic PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Cardiovascular Devices Market Evolving Landscape
Transcatheter platforms are compressing the traditional surgical-interventional boundary, while regulatory data localization and procurement centralization reshape how cardiac devices reach South African patients.
Drug-eluting balloon technology is rendering obsolete provisional stenting strategies in small vessel coronary interventions. Interventional cardiologists at Johannesburg academic medical centers are adopting this approach for diffuse distal disease and bifurcation lesions where stent deliverability is compromised. The structural consequence is reduced permanent metal burden and shortened dual antiplatelet therapy duration, compressing total episode costs for payers.
SAHPRA's risk-based classification pathways now mandate local clinical evidence generation for Class III and active implantable devices, extending approval timelines but improving post-market surveillance granularity. Manufacturers must establish investigator-initiated study infrastructure or sponsor local registry participation to satisfy pre-market requirements. High-risk structural heart segments including transcatheter mitral repair and left atrial appendage closure face the steepest evidentiary barriers.
Public hospital procurement is consolidating purchasing authority under provincial health department frameworks, displacing individual facility tendering. Private hospital networks respond through centralized device formulary committees that standardize across cardiac catheterization laboratory sites. The geographic concentration of this shift is most visible in Gauteng, where Johannesburg and Pretoria health clusters negotiate multi-year supply agreements that privilege volume commitments over unit pricing flexibility.
South Africa Cardiovascular Devices Market Segmentation
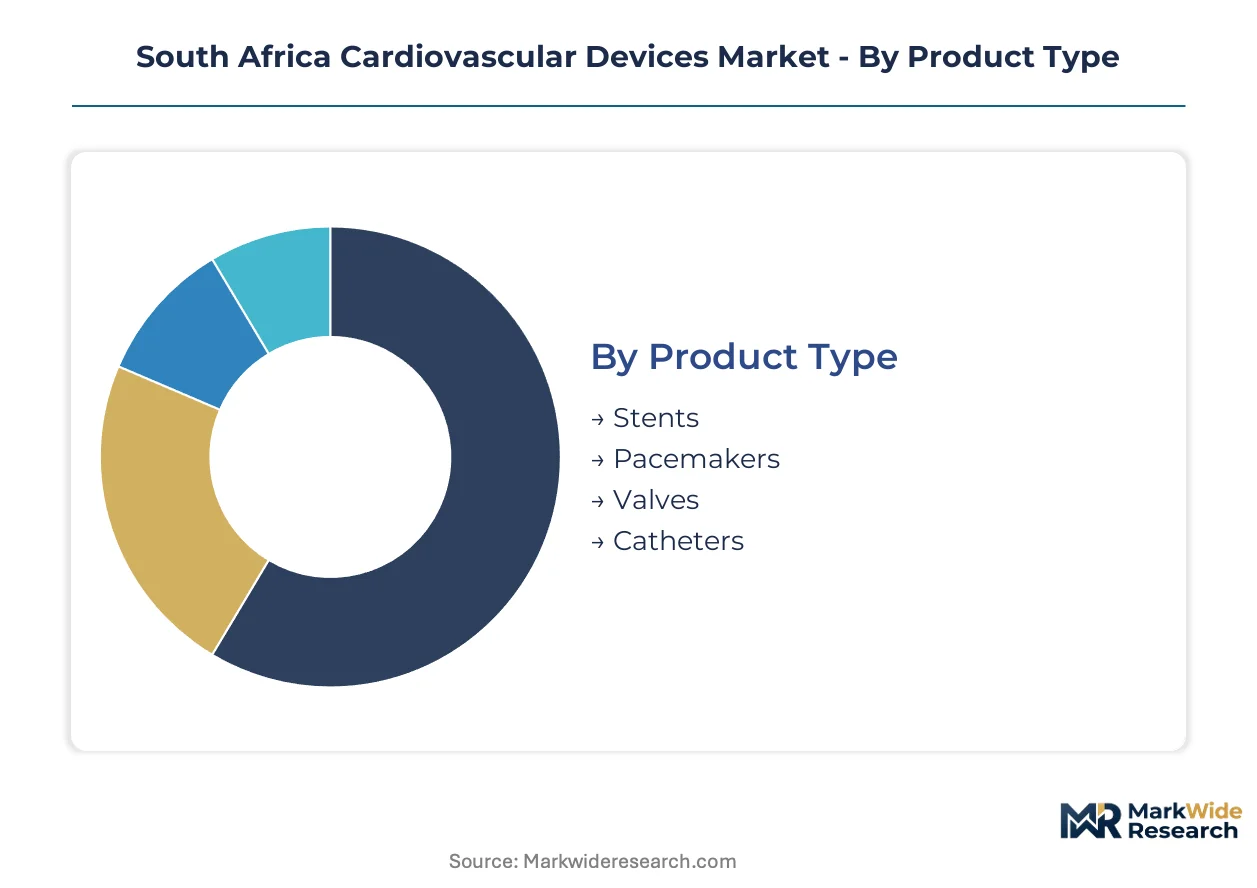
Device segmentation in South Africa tracks how procurement authority, reimbursement pathways, and clinical training infrastructure concentrate demand across distinct product configurations and care delivery settings. Understanding these divisions exposes where manufacturers must anchor service networks and where public-private volume splits reshape commercial priorities.
Product Type:
After-sales service intensity varies sharply across implantable categories, with generator-dependent systems demanding scheduled replacement programs that metallic platforms simply do not require.
- Stents:Metallic scaffolds and drug-eluting platforms dominate procedural volume in Gauteng catheterization laboratories, where complex PCI programs at Johannesburg academic centers drive sustained demand despite bioabsorbable alternatives. Procurement concentrates in provincial health department tenders that privilege volume commitments over unit flexibility.
- Pacemakers:Battery-powered electrical rhythm management systems with 7-10 year replacement cycles generate recurring revenue through generator exchanges, with follow-up dependency creating sticky hospital-supplier relationships that transcend initial implant transactions. Rand-denominated platinum-iridium electrode sourcing exposes manufacturers to input cost volatility.
- Valves:Transcatheter and surgical configurations address structural heart disease prevalence in KwaZulu-Natal.
- Catheters:Delivery and diagnostic platforms enable minimally invasive workflows across hybrid operating room installations.
Stents hold the largest share; momentum sits with pacemakers.
End User:
Procurement centralization is concentrating purchasing authority differently across public and private delivery settings, with provincial frameworks displacing individual facility autonomy.
- Hospitals:Public sector institutions in Eastern Cape and Limpopo provinces are expanding catheterization laboratory access through National Health Insurance procurement amendments, while private networks in Johannesburg and Pretoria negotiate multi-year supply agreements that standardize device formularies across cardiac sites.
- Cardiac Centers:Specialized interventional facilities in Gauteng blend surgical and catheter-based capabilities under single anesthesia events, driving demand for hybrid-compatible delivery systems that reduce ICU occupancy and compress episode costs.
- Outpatient Clinics:Diagnostic and follow-up services extend care continuity beyond acute interventions.
- Laboratories:Testing and monitoring infrastructure supports device programming and patient surveillance.
Hospitals command the greatest volume; cardiac centers are expanding most quickly.
Technology:
Regulatory evidence requirements and clinical training pipelines favor established platforms over novel materials, extending commercialization timelines for breakthrough configurations.
- Minimally Invasive:Catheter-based interventions are displacing open-chest procedures across South African cardiac centers, with transcatheter platforms compressing surgical-interventional boundaries and enabling hybrid operating room configurations that blend capabilities under single anesthesia events.
- Electrical:Rhythm management systems with predictable battery depletion cycles create recurring generator replacement revenue that offsets upfront margin pressure in price-sensitive procurement environments, sustaining manufacturer presence through long-term service relationships.
- Mechanical:Durable surgical valves and metallic stents retain preference where transcatheter alternatives face capacity or contraindication constraints.
- Bioabsorbable:Scaffold technology commands R&D investment despite restenosis and deliverability limitations that constrain clinical uptake.
Minimally invasive platforms lead installed base; electrical systems show steepest expansion trajectory.
Application:
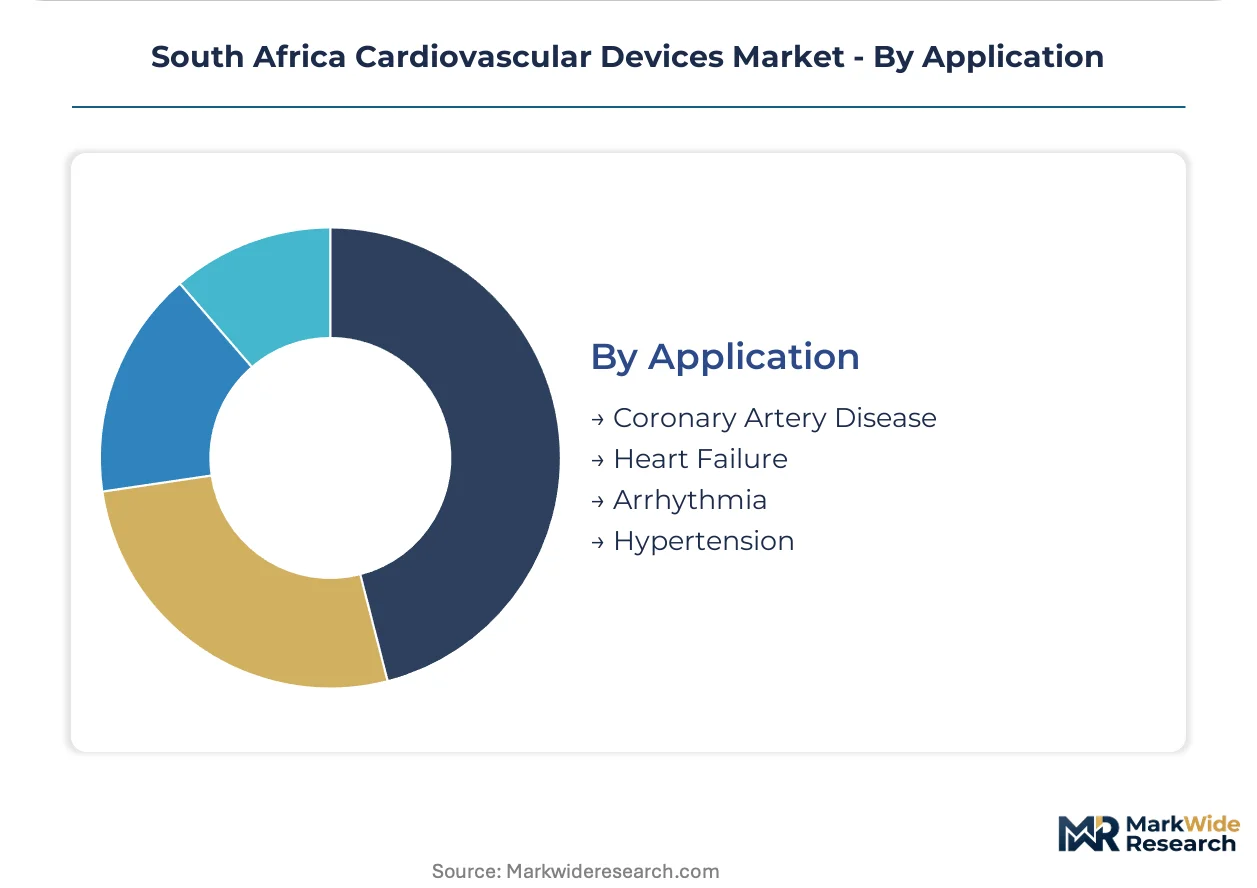
Disease burden distribution and intervention readiness determine where device demand concentrates across South Africa's uneven cardiac care infrastructure.
- Coronary Artery Disease:Ischemic heart disease prevalence drives stent deployment volume, with drug-eluting balloon technology rendering obsolete provisional stenting strategies in small vessel interventions at Johannesburg academic centers where diffuse distal disease and bifurcation lesions challenge deliverability.
- Arrhythmia:Electrical rhythm disorders sustain pacemaker and ICD demand, with Western Cape public health infrastructure operating below national average interventional capacity per capita and creating whitespace for mobile diagnostic deployments and public-private partnership models.
- Heart Failure:Structural and electrical interventions address progressive cardiac dysfunction.
- Hypertension:Device-based management complements pharmaceutical approaches in resistant cases.
Coronary artery disease captures the greatest procedural volume; arrhythmia management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa imports cardiovascular devices primarily from the United States, Germany, and Switzerland, with Gauteng province absorbing the highest concentration of interventional cardiac capacity.
Gauteng
Johannesburg and Pretoria host the country's densest catheterization laboratory networks, with private hospital clusters negotiating multi-year supply agreements that standardize device formularies across cardiac sites. SAHPRA's risk-based classification pathways mandate local clinical evidence for Class III implantables, compressing approval timelines but extending pre-market cycles. The Johannesburg academic medical centers drive complex PCI program expansion and transcatheter valve intervention adoption.
Western Cape
Cape Town's public health infrastructure operates below national average interventional capacity per capita, creating whitespace for mobile cath lab deployments. The provincial health department is consolidating purchasing authority under centralized frameworks that displace individual facility tendering. Groote Schuur Hospital anchors the region's structural heart disease referral pathway for rheumatic valve interventions.
KwaZulu-Natal
Rheumatic heart disease prevalence sustains demand for transcatheter valve interventions as surgical capacity constraints limit open-chest alternatives. The National Health Insurance procurement amendments will expand public sector reimbursement pools across this historically underserved province. Durban's cardiac centers are adopting hybrid operating room configurations that blend surgical and interventional capabilities.
Eastern Cape
Previously dependent on out-of-pocket private expenditure, this province is unlocking catheterization laboratory investments through National Health Insurance framework amendments. Provincial health department procurement centralization is displacing fragmented facility-level purchasing. Nelson Mandela Bay's cardiac infrastructure is expanding through public-private partnership models for device-intensive interventions.
South Africa Cardiovascular Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across South Africa's cardiovascular devices market. The vendor base clusters around three strategic archetypes: diversified medtech conglomerates with full cardiac portfolios, imaging and diagnostic systems specialists, and focused interventional device manufacturers. Consolidation pressure favors scale-driven players with established SAHPRA compliance infrastructure. Dominant competitive moves include strategic partnerships with provincial procurement frameworks and technology licensing agreements that accelerate local clinical evidence generation.
Within the diversified cardiac portfolio tier, Medtronic PLC and Abbott Laboratories exemplify channel-controlling archetypes that anchor premium device segments across private hospital networks. Boston Scientific Corporation occupies a product-specialist position focused on interventional cardiology platforms. Among imaging systems providers, GE Healthcare and Siemens AG represent the diagnostic infrastructure backbone that enables procedure volume growth.
| Leading Market Players |
|---|
| Edwards Lifesciences |
| GE Healthcare |
| Abbott Laboratories |
| Canon Medical Systems Corporation |
| Siemens AG |
| Boston Scientific Corporation |
| Cardinal Health, Inc. |
| W. L. Gore & Associates |
| Medtronic PLC |
| Others |
Value Network & Pricing Analysis
Gauteng's catheterization laboratory cluster concentrates procurement authority for cardiovascular devices, with Johannesburg and Pretoria hospitals leveraging volume scale to extract price concessions from manufacturers facing SAHPRA compliance cost burdens. This geographic demand concentration creates asymmetric bargaining power that compresses margins for device suppliers while rewarding integrated players with captive service networks.
Pricing Analysis
Current-generation drug-eluting stents command premium positioning over bare-metal platforms and next-generation bioabsorbable scaffolds, with three-tier pricing structure across premium, standard, and economy levels reflecting CE-mark certification status and local clinical evidence depth. Price differentiation rests on SAHPRA approval tier and after-sales generator replacement bundling for pacemaker systems. Cost compression in the economy tier is intensifying because provincial health departments are consolidating tenders under National Health Insurance amendments. Public hospital procurement committees exhibit highest price sensitivity, while private cardiac centers in Pretoria clusters prioritize device performance metrics over unit cost.
Supply Chain Analysis
Flextronics and Jabil Medical anchor contract manufacturing capacity for active implantable assemblies, with final device production drawing from Ireland, Malaysia, and Costa Rica for sterilization-validated facilities. Platinum-iridium electrode feedstock sources from South African mining operations, while polymer coatings for drug-eluting platforms hinge on German and Swiss specialty chemical suppliers. Single-source vulnerability concentrates in SAHPRA-certified sterilization facilities, where limited approved vendors create bottleneck risk for Class III device launches. Distribution runs through provincial health department central warehouses for public sector fulfillment, with direct-to-hospital logistics serving private network clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's cardiovascular device market is recovering from cyclical trough conditions, with National Health Insurance procurement amendments restoring public sector investment momentum after years of constrained capital expenditure.
For Market Incumbents: Insulate generator replacement revenue streams by locking multi-year service contracts with Johannesburg and Pretoria private hospital networks before provincial tender consolidation accelerates. Anchor SAHPRA compliance infrastructure against emerging entrant cost advantages by pre-positioning local clinical evidence generation for next-generation transcatheter platforms. Vertical integration into platinum-iridium electrode sourcing mitigates rand-denominated input volatility threatening pacemaker margin stability. For New Entrants and Emerging Players: Western Cape public health infrastructure gaps represent the most penetrable entry point, with Cape Town's below-national-average interventional capacity per capita creating whitespace for mobile catheterization laboratory partnerships. Eastern Cape provinces transitioning from out-of-pocket expenditure to National Health Insurance reimbursement pools offer second-mover advantage for stent and catheter platforms. A public-private partnership go-to-market angle bypasses entrenched Gauteng supply relationships. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because electrical rhythm management systems with predictable 7-10 year battery depletion cycles generate sustained replacement income that transcends device margin cyclicality. Acquisition targets should prioritize SAHPRA-registered manufacturers with established investigator-initiated study infrastructure rather than technology-only assets lacking regulatory pathway experience. Monitor National Health Insurance procurement framework amendment implementation velocity as the critical inflection signal for public sector volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SAHPRA Local Clinical Evidence Generation | Accelerates pre-market approval timelines for Class III implantables against CE-marked benchmarks. |
| Provincial Health Department Partnership | Secures multi-year supply agreements as Eastern Cape and Limpopo expand catheterization access. |
| Generator Replacement Service Contracting | Creates sticky hospital relationships through scheduled 7-10 year battery exchange programs. |
| Hybrid Operating Room Configuration Sales | Captures demand from Gauteng cardiac centers blending surgical and interventional capabilities. |
| Platinum-Iridium Electrode Backward Integration | Reduces rand-denominated input cost exposure for pacemaker and ICD manufacturing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SAHPRA registration databases, provincial health department tender records, and SABS electromagnetic compatibility certification logs. Primary interviews engaged interventional cardiologists at Johannesburg academic centers, biomedical engineers managing Groote Schuur Hospital device programs, and procurement officers within Eastern Cape provincial health frameworks. Secondary validation incorporated hospital procurement database extracts, GPO contract filings, and customs import records for cardiovascular device categories. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Forecast inputs span product type segmentation across stents, pacemakers, valves, and catheters; end-user splits between public hospitals, private cardiac centers, and outpatient clinics; and technology categories including minimally invasive, electrical, mechanical, and bioabsorbable platforms. CAGRs were derived from regression analysis against National Health Insurance expenditure projections and catheterization laboratory installation trajectories across the analysis window. Industry-specific inputs include SAHPRA approval pipeline velocity and interventional cardiologist fellowship graduation rates.
Practitioners should monitor National Health Insurance procurement framework amendment timing, platinum-rand exchange rate volatility, and SAHPRA staffing capacity for early signals requiring forecast revision. Cross-checking against WHO cardiovascular disease burden estimates for South Africa is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Balloon Catheters Market
Cardiovascular Devices
Resuscitation Bags Market
Cardiovascular Devices
Peripheral Vascular Interventions Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Stent Grafts Market
Cardiovascular Devices
Perfusion Systems Market
Cardiovascular Devices
Extracorporeal Membrane Oxygenation (ECMO) Market
Cardiovascular Devices
Cardiac Ablation Technologies Market
Cardiovascular Devices
Human Non-Invasive Blood Pressure (NIBP) Recording System Market
Cardiovascular Devices
Medical Devices Cuffs Market
Cardiovascular Devices
Saudi Arabia Cardiovascular Devices Market
Cardiovascular Devices
Cardiovascular Anastomosis Devices Market
Cardiovascular Devices
Germany Cardiovascular Devices Market
Cardiovascular Devices
Radiofrequency Balloon Catheter Market
Cardiovascular Devices
Global Aortic Valve Market
Cardiovascular Devices
US Hemostats Market