
 Vascular Prostheses Market | 2026-2036
Vascular Prostheses Market Size, Share, and Industry Trends Forecast 2026-2036
Vascular Prostheses Market Analytics
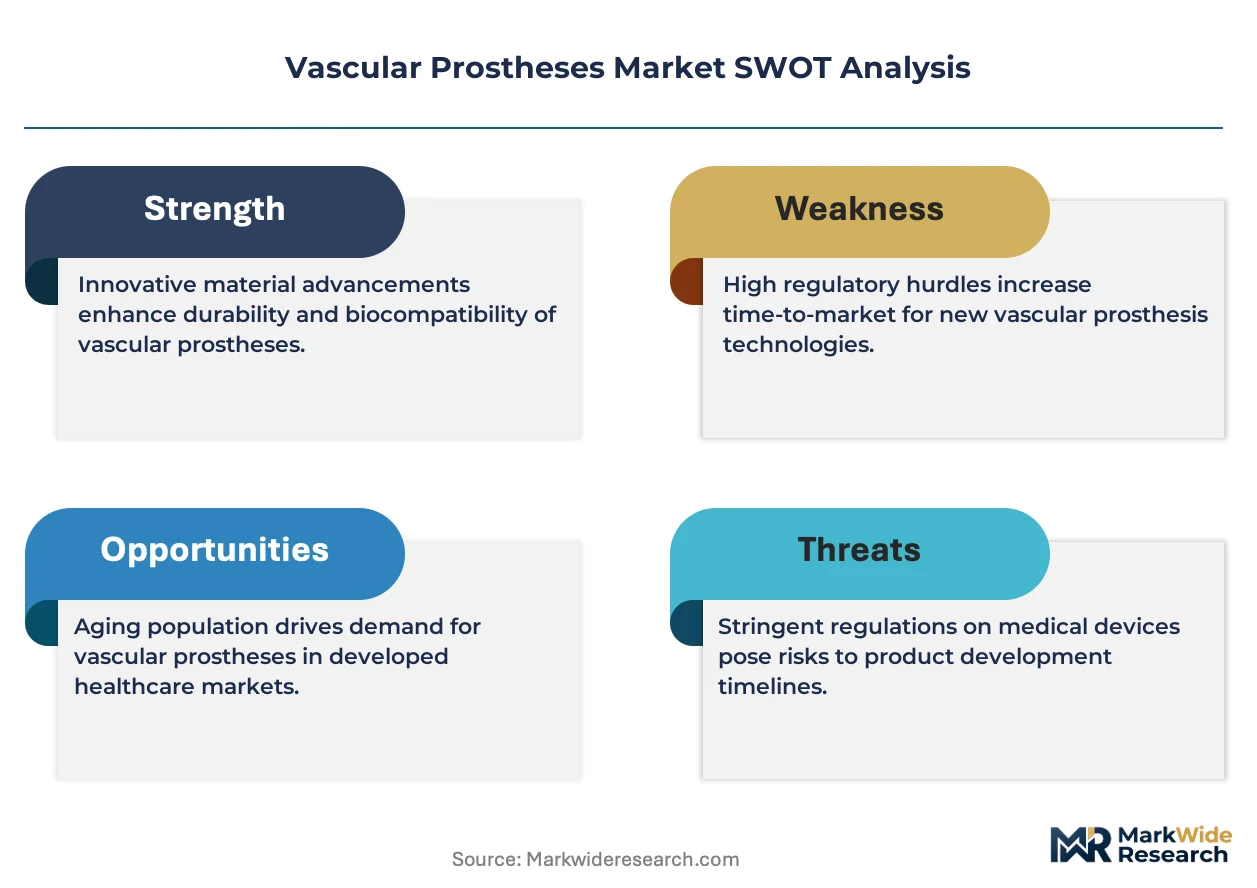
ISO 25539 is redrawing competitive boundaries for vascular prosthesis manufacturers by mandating fatigue resistance and delivery system integrity benchmarks that filter out undercapitalized entrants. Gore leverages its vertically integrated expanded polytetrafluoroethylene supply chain to control material consistency from resin to finished graft. Medtronic anchors its position through broad hospital contracting networks across North American and European cath labs. Terumo Corporation competes with differentiated hydrophilic coating technologies that reduce thrombogenicity in coronary stent applications.
Vascular prostheses are implantable or catheter-delivered devices designed to restore patency, exclude aneurysms, or filter emboli within arterial and venous systems, typically constructed from expanded polytetrafluoroethylene, polyester woven fabrics, nitinol alloys, or bioabsorbable polymers with wall thicknesses calibrated between 0.1 mm and 0.6 mm depending on anatomical target. Their primary purpose is to replace or bypass diseased native vessels while withstanding cyclic pulsatile pressures exceeding 120 mmHg without material creep or delamination. Grafts constructed from polymer materials sustain premium pricing due to proven long-term durability in aortoiliac and femoropopliteal bypass procedures. Endovascular delivery modes represent the fastest-expanding structural category as physician training and cath lab infrastructure shift lower-acuity cases away from open surgical suites.
FDA premarket approval and EMA MDR conformity assessment create dual compliance burdens that extend development timelines and concentrate resources among firms with dedicated regulatory affairs divisions. The EU F-Gas Regulation and REACH restrictions on perfluorinated compounds are forcing material substitutions in graft manufacturing that may alter supply economics for expanded polytetrafluoroethylene-based products. Japan's PMDA Shonin pathway adds a third major gate for Asian market access, particularly for drug-eluting stent platforms. Stakeholders must monitor how evolving biocompatibility testing standards and sustainability mandates reshape raw material sourcing and manufacturing location decisions.
Market Dynamics
Endovascular delivery systems are compressing procedural economics by shifting aortoiliac and femoropopliteal interventions from inpatient surgical suites to outpatient cath labs, forcing manufacturers to recalibrate device durability requirements and pricing models around same-day discharge protocols.
Growth Catalysts
- Japan's aging surgical population:PMDA reimbursement pathways for transcatheter aortic valve replacement are expanding hospital cath lab capacity in Osaka and Tokyo, creating procedural volume anchors for stent graft platforms.
- ISO 25539-1 fatigue testing mandates:Updated cardiovascular implant standards are filtering out graft designs with inadequate pulsatile durability, consolidating procurement decisions around manufacturers with validated 400-million-cycle test data.
- Polyester woven fabric innovation:Advances in low-porosity PET textile engineering are reducing perigraft seroma rates in abdominal aortic aneurysm repair, improving long-term patency metrics that drive hospital formulary placement.
Market Restraints
- Expanded polytetrafluoroethylene supply concentration:Resin production for ePTFE grafts concentrates among three chemical suppliers in the US and Germany, exposing device manufacturers to input cost volatility and allocation constraints during semiconductor-industry demand spikes.
- EMA MDR technical documentation burdens:The EU's Medical Device Regulation requires clinical evidence upgrades for legacy vascular grafts, extending recertification timelines and freezing product line extensions for mid-tier manufacturers.
- Bioresorbable scaffold thrombosis history:Earlier-generation poly-L-lactic acid stent failures in coronary applications have created physician skepticism that slows adoption of bioabsorbable peripheral platforms despite improved polymer formulations.
Strategic Opportunities
- India's underpenetrated peripheral artery disease segment:CDSCO streamlined approval pathways for Class D implantables are opening access to tertiary hospitals in Mumbai and Delhi where cath lab infrastructure investment outpaces graft supply localization.
- Drug-eluting balloon convergence with nitinol stents:Combination therapies pairing paclitaxel delivery with self-expanding scaffold platforms are creating new procedure categories in below-the-knee interventions previously managed by bypass surgery alone.
- US hospital vertical integration:IDN consolidation into super-systems with captive distribution networks is creating direct contracting channels that bypass traditional distributor markups for high-volume graft purchasers.
Industry Challenges
- Interventional cardiologist training bottlenecks:Complex endovascular aneurysm repair requires 200+ supervised cases for credentialing, constraining procedural expansion in community hospitals without academic medical center affiliations.
- Dual FDA-EMA quality system audits:Manufacturers maintaining ISO 13485 certification face non-conformance findings across divergent inspection emphasis areas, requiring redundant documentation streams and specialized regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vascular Prostheses Market |
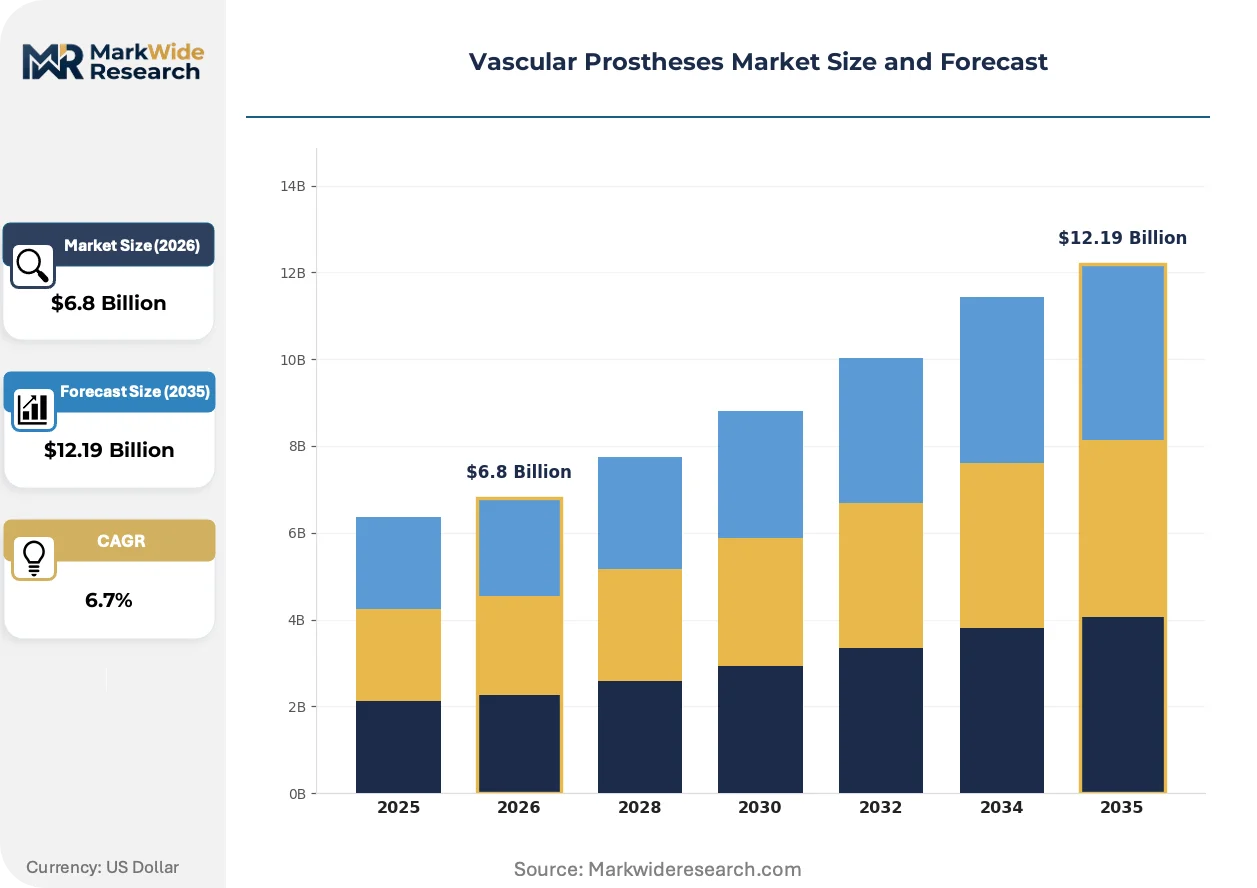
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.19 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stents, Grafts, Balloons, Filters Material: Polymer, Metal, Biodegradable, Composite End User: Hospitals, Clinics, Outpatient Centers, Ambulatory Surgical Centers Delivery Mode: Surgical, Endovascular, Hybrid, Minimally Invasive |
| Companies Covered | Gore, Getinge, LeMaitre Vascular, Terumo Corporation, Medtronic, B. Braun, Abbott, Artivion, Perouse Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vascular Prostheses Market Evolving Landscape
Computational modeling and biomaterial science are converging to redefine graft performance benchmarks, with manufacturers racing to validate next-generation platforms against evolving regulatory durability standards while cath lab economics compress reimbursement timelines.
Thin-wall ePTFE graft construction is decomposing traditional thickness-performance tradeoffs in femoropopliteal bypass applications. Community hospitals in the US Midwest are adopting sub-0.3 mm wall designs for outpatient endovascular procedures, compressing the addressable market for thicker-walled surgical grafts previously required for structural integrity. This technology is decomposing established procurement hierarchies that separated premium surgical from economy endovascular product tiers.
REACH restrictions on perfluorinated compounds are forcing material substitutions in European manufacturing facilities. The ECHA authorization requirements for specific fluoropolymer precursors are elevating compliance costs for ePTFE graft producers, pushing manufacturing location decisions toward US and Asian facilities outside direct EU chemical regulation scope. Small-diameter coronary bypass conduits face the steepest formulation reformulation timelines under these constraints.
Hospital procurement committees are consolidating vendor relationships around integrated stent-graft delivery system contracts. German university hospitals are replacing multi-supplier cath lab inventories with single-source agreements covering nitinol scaffolding, hydrophilic coatings, and delivery sheath compatibility, compressing switching flexibility but reducing unit logistics overhead. This concentration is most visible in Bavaria and Baden-Württemberg where IDN merger activity has accelerated.
Vascular Prostheses Market Segmentation
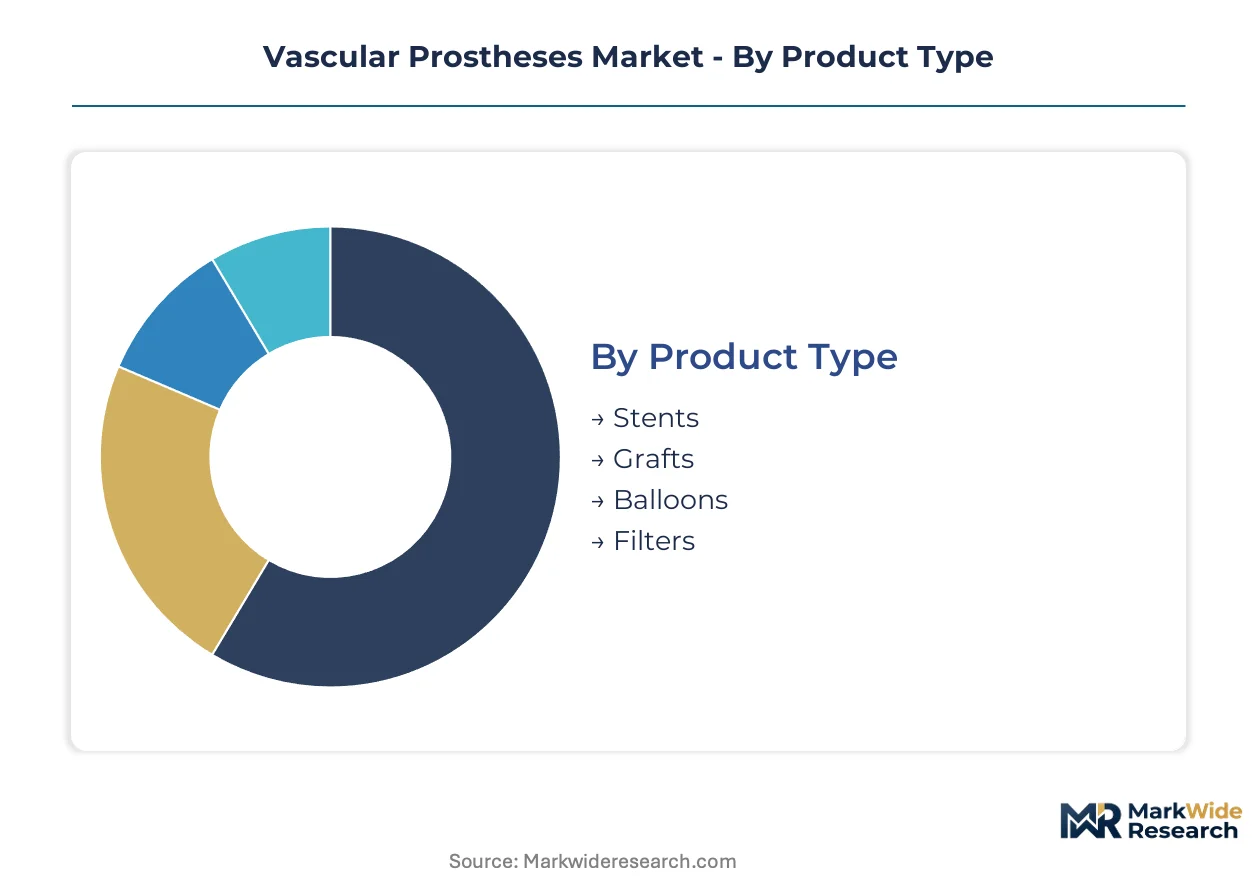
Vascular prosthesis procurement channels diverge sharply by procedural setting, with hospital cath labs, outpatient surgery centers, and hybrid operating rooms each demanding distinct device specifications, inventory models, and contracting terms. Understanding these channel-product alignments reveals where manufacturers must calibrate durability, delivery complexity, and pricing to capture volume.
Product Type:
Stents and grafts flow predominantly through hospital cath labs under bundled procedural contracts, while balloons and filters see heavier outpatient center penetration where simpler logistics and lower capital requirements reduce switching costs.
- Stents:Self-expanding nitinol and balloon-expandable stainless steel scaffolds with strut thicknesses of 80-150 microns. Demand concentrates in Japanese university hospitals in Osaka and Tokyo where PMDA reimbursement for transcatheter procedures is expanding cath lab capacity. ISO 25539 fatigue validation requirements are filtering out designs lacking 400-million-cycle test data.
- Grafts:Tubular woven polyester or expanded polytetrafluoroethylene conduits with calibrated porosity for tissue ingrowth. German hospital procurement committees in Bavaria and Baden-Württemberg are consolidating around integrated stent-graft delivery system contracts that bundle scaffolding with sheaths and coatings.
- Balloons:Catheter-delivered dilatation devices for pre-dilation and post-dilation in stent deployment.
- Filters:Embolic protection devices for carotid and saphenous vein graft interventions.
By volume, stents lead. By growth pace, grafts are ahead.
Material:
Material selection drives manufacturing location decisions as REACH restrictions on perfluorinated compounds reshape supply economics for European production facilities.
- Polymer:Expanded polytetrafluoroethylene and polyester woven fabrics dominate aortoiliac and femoropopliteal applications. US Midwest community hospitals are adopting sub-0.3 mm wall ePTFE designs for outpatient endovascular procedures, compressing demand for thicker surgical alternatives.
- Metal:Nitinol superelastic alloys and cobalt-chromium formulations provide radial force and fatigue resistance. Demand clusters in German cath labs where IDN consolidation into super-systems is creating direct contracting channels that bypass traditional distributor markups.
- Biodegradable:Poly-L-lactic acid and polyglycolic acid scaffolds designed for gradual resorption.
- Composite:Multi-layer constructions combining polymer sleeves with metal reinforcement.
Polymer commands the largest revenue share. Biodegradable formulations are expanding most quickly despite physician skepticism from earlier coronary scaffold failures.
End User:
Facility type determines reimbursement pathways, capital equipment requirements, and the feasible complexity of endovascular procedures.
- Hospitals:Academic medical centers and community hospitals with cath lab infrastructure perform complex endovascular aneurysm repair and multi-vessel interventions. Credentialing requirements of 200+ supervised cases constrain procedural expansion in community settings without academic affiliations.
- Clinics:Physician office-based labs handling diagnostic angiography and lower-acuity interventions.
- Outpatient Centers:Standalone facilities capturing same-day discharge protocols for femoropopliteal and renal artery procedures.
- Ambulatory Surgical Centers:Medicare-certified sites expanding into peripheral vascular interventions as reimbursement shifts toward site-neutral payment.
Hospitals generate the highest absolute procedure volume. Outpatient centers are gaining share fastest as endovascular delivery compresses procedural economics toward same-day discharge.
Delivery Mode:
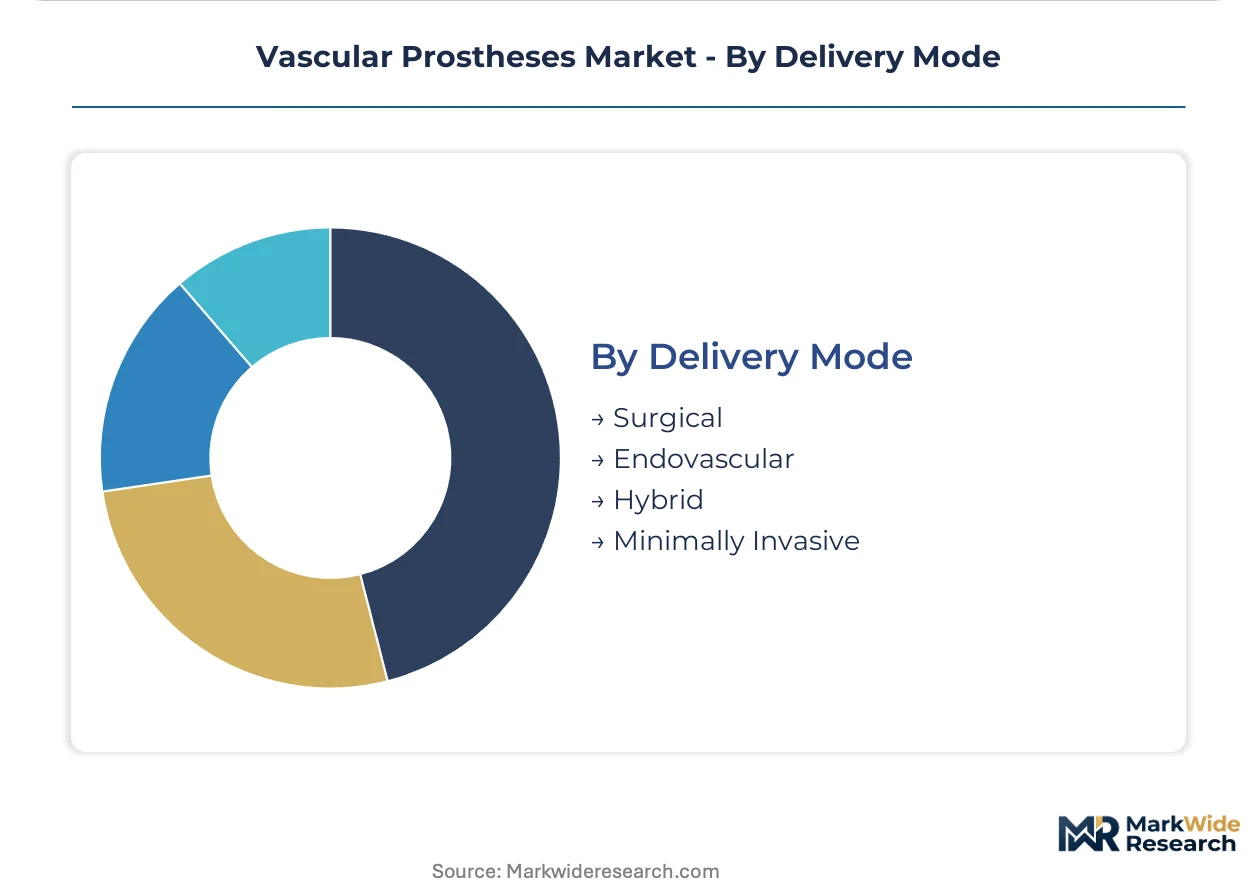
Procedural setting and reimbursement timelines are resegmenting the market by invasiveness, with minimally invasive and endovascular platforms capturing cases previously managed through open surgery.
- Endovascular:Catheter-based deployment through femoral or brachial access without surgical incision. Indian tertiary hospitals in Mumbai and Delhi are expanding cath lab infrastructure faster than graft supply localization, creating import-dependent demand under CDSCO streamlined Class D pathways.
- Surgical:Open bypass with direct vessel anastomosis and suturing. Remains dominant for below-the-knee revascularization where tibial vessel calcification prevents endovascular crossing.
- Hybrid:Combined open and endovascular techniques in hybrid operating rooms.
- Minimally Invasive:Laparoscopic or robotic-assisted vessel exposure with endovascular completion.
Surgical delivery retains the largest installed base. Endovascular approaches are climbing the fastest as physician training and cath lab infrastructure shift lower-acuity cases from inpatient suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in the United States, Germany, and Japan concentrate the bulk of vascular prosthesis purchasing power, with aging surgical populations and established reimbursement frameworks anchoring procedural volume expansion in these markets.
United States
IDN consolidation into super-systems with captive distribution networks is creating direct contracting channels that bypass traditional distributor markups for high-volume graft purchasers. FDA premarket approval pathways for implantable devices are tightening material and biocompatibility requirements. Community hospitals in the US Midwest are adopting sub-0.3 mm wall ePTFE designs for outpatient endovascular procedures.
Germany
German university hospitals in Bavaria and Baden-Württemberg are replacing multi-supplier cath lab inventories with single-source agreements covering nitinol scaffolding, hydrophilic coatings, and delivery sheath compatibility. EMA MDR technical documentation burdens extend recertification timelines for legacy vascular grafts. The EU F-Gas Regulation and REACH restrictions on perfluorinated compounds are forcing material substitutions in graft manufacturing.
Japan
PMDA reimbursement pathways for transcatheter aortic valve replacement are expanding hospital cath lab capacity in Osaka and Tokyo, creating procedural volume anchors for stent graft platforms. Japan's PMDA Shonin pathway adds a third major gate for Asian market access, particularly for drug-eluting stent platforms. Kanto and Kansai regions anchor domestic demand as metropolitan hospital systems invest in endovascular infrastructure.
India
CDSCO streamlined approval pathways for Class D implantables are opening access to tertiary hospitals in Mumbai and Delhi where cath lab infrastructure investment outpaces graft supply localization. India's underpenetrated peripheral artery disease segment offers expansion runway as procedural training expands beyond major metros. Import-dependent demand persists due to limited domestic manufacturing of polymer graft materials.
China
NMPA regulatory harmonization with international standards is accelerating market entry for multinational manufacturers with established biocompatibility testing protocols. Yangtze River Delta hospital clusters in Shanghai and Jiangsu province are expanding hybrid operating room capacity for complex aortic interventions. Local procurement preferences favor domestic suppliers for standard surgical grafts while premium endovascular platforms remain import-reliant.
Vascular Prostheses Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with dedicated cardiovascular divisions, supplemented by specialized vascular surgery firms and regional fabricators with material science expertise. Market structure exhibits tiered consolidation with premium-tier manufacturers controlling cath lab formulary placement through integrated delivery system contracts. Three archetypes dominate: vertically integrated polymer suppliers, nitinol scaffold specialists, and diversified medtech platforms with broad hospital contracting networks. Competitive moves concentrate on backward integration into raw material supply and strategic partnerships with IDN procurement committees.
Within the diversified medtech tier, Medtronic and Abbott exemplify scale-driven hospital contracting strategies, while Gore represents vertically integrated polymer supply control. Terumo Corporation occupies a position bridging Japanese domestic market access with hydrophilic coating differentiation. These three anchors illustrate how geographic footprint and material capabilities stratify competitive positioning across regulatory jurisdictions.
| Leading Market Players |
|---|
| Gore |
| Getinge |
| LeMaitre Vascular |
| Terumo Corporation |
| Medtronic |
| B. Braun |
| Abbott |
| Artivion |
| Perouse Medical |
| Others |
Value Network & Pricing Analysis
REACH-driven fluoropolymer substitution in European manufacturing is redrawing procurement economics for expanded polytetrafluoroethylene grafts, simultaneously pushing production toward US and Asian facilities while compressing margin structures for producers retaining EU-based resin conversion. This geographic relocation of supply capacity is altering price negotiation leverage between device manufacturers and hospital procurement committees.
Pricing Analysis
Cost-plus contracts with medical-grade polymer indexation dominate procurement agreements for woven polyester and ePTFE conduits. Price differentiation hinges on ISO 25539 fatigue certification tier and cath lab formulary placement depth. Pricing pressure intensifies as German university hospitals consolidate around single-source stent-graft bundles. Community hospital systems exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize performance metrics over unit cost.
Supply Chain Analysis
United States and Germany anchor resin production for medical-grade fluoropolymers, with Japan supplying nitinol alloy feedstock for superelastic scaffold manufacturing. Device assembly draws from Taiwanese precision metalworking and Swiss textile engineering for low-porosity PET weaving. Single-source vulnerability concentrates in ePTFE membrane calendering, where three chemical suppliers control medical-grade resin allocation. Distribution runs through IDN captive networks and specialized cardiovascular device distributors serving cath lab accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vascular prostheses sector is entering a high-growth disruption phase as endovascular delivery modes displace open surgical volumes, with ISO 25539 fatigue mandates and REACH chemical restrictions accelerating competitive consolidation around vertically integrated manufacturers.
For Market Incumbents: Secure backward integration into medical-grade fluoropolymer resin supply to defend against REACH-driven input cost volatility and allocation constraints. Deepen hospital system partnerships through integrated stent-graft delivery contracts that bundle scaffolding, coatings, and sheaths into single-source agreements, compressing switching flexibility for German and US IDN procurement committees.
For New Entrants and Emerging Players: Post-market surveillance and clinical data services for legacy graft platforms represent a service-layer gap where incumbents under-serve mid-tier manufacturers facing EMA MDR recertification burdens. Target India's underpenetrated peripheral artery disease segment through CDSCO streamlined Class D pathways, partnering with Mumbai and Delhi tertiary hospitals expanding cath lab capacity faster than domestic graft supply localization.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed vascular surgery specialists holding ISO 25539-validated fatigue test data but lacking integrated delivery system capabilities. Long-term viability centers on manufacturers with demonstrated 400-million-cycle performance and established PMDA Shonin or FDA PMA track records. Watch for PMDA reimbursement expansion signals in Osaka and Tokyo as indicators of procedural volume inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Fatigue Test Data Investment | ISO 25539-1 validation filters out undercapitalized competitors from procurement decisions. |
| Resin Supply Integration | Captive fluoropolymer production insulates margin structures from REACH authorization volatility. |
| Hospital System Partnership | Single-source cath lab contracts reduce logistics overhead in Bavaria and Baden-Württemberg. |
| CDSCO Pathway Navigation | Streamlined Class D approvals unlock Mumbai and Delhi tertiary hospital access. |
| PMDA Reimbursement Strategy | Shonin pathway alignment secures volume anchors in Osaka and Tokyo metropolitan systems. |
Research Methodology
Operator-level perspectives from cath lab directors, hospital procurement committee chairs, biomedical engineers, and GPO contracts managers anchored the qualitative base for this vascular prostheses assessment. Primary interviews combined with secondary validation against FDA PMA filings, EMA MDR technical documentation, PMDA Shonin approval records, and hospital procurement databases. Bottom-up procedure volume estimates triangulated with top-down manufacturer revenue analysis across product type, material, end user, and delivery mode segments.
Sensitivity analysis around regulatory timeline scenarios and cath lab capacity expansion rates informed the forecast framework. Segmentation modeling spanned stent versus graft versus balloon platforms, polymer versus metal versus biodegradable materials, hospital versus outpatient versus ambulatory surgical center settings, and endovascular versus surgical versus hybrid delivery approaches. CAGRs derived from procedure volume trajectories, reimbursement pathway expansions, and material substitution elasticities across the projection horizon.
Forecasts assume regulatory continuity in FDA premarket approval, EMA MDR conformity assessment, and PMDA Shonin evaluation regimes; material policy shifts in fluoropolymer restrictions or biocompatibility testing standards would require re-modeling. Recalibration cycles align with ISO standard revision schedules and major reimbursement determinations in Japan, Germany, and United States markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
United States Cardiovascular Devices Market
Cardiovascular Devices
Global Cardiac Resynchronization Therapy Market
Cardiovascular Devices
Global Heart Valve Repair and Replacement Market
Cardiovascular Devices
Global Stents Market
Cardiovascular Devices
Serration Balloon Catheters Market
Cardiovascular Devices
Europe Vascular Access Device Market
Cardiovascular Devices
Renal Denervation Devices Market
Cardiovascular Devices
Sweden Cardiovascular Devices Market
Cardiovascular Devices
Global Pericardiocentesis Procedures Market
Cardiovascular Devices
Umbilical Vessel Catheters Market
Cardiovascular Devices
Transcatheter Heart Valve Market
Cardiovascular Devices
Heart Valves Market
Cardiovascular Devices
Global Advanced Balloon Catheter Market
Cardiovascular Devices
Non-Invasive Pulse Wave Tonometer Market
Cardiovascular Devices
South Africa Cardiovascular Devices Market
Cardiovascular Devices
Ventricular Drainage Sets Market